
 Saudi Arabia Metal Packaging Market | 2026-2036
Saudi Arabia Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Metal Packaging Market Analytics
The Saudi Green Initiative is repositioning procurement standards across the kingdom's food and beverage supply chain. Ball Corporation leverages its regional coil-coating infrastructure to serve carbonated soft-drink bottlers with lightweight aluminum solutions. Crown Holdings Inc anchors the aerosol segment through dedicated tinplate lines serving personal care contract manufacturers. Saudi Can Co Ltd competes on proximity, operating conversion plants within delivery range of Riyadh-based dairy processors.
Metal packaging denotes rigid containers fabricated from aluminum, steel, tinplate, or stainless steel through deep drawing, two-piece drawing and wall ironing, or three-piece welding and seaming processes, engineered to provide hermetic sealing, ultraviolet light blocking, and mechanical protection for shelf-stable goods. Beverage cans dominate volume throughput given the kingdom's per-capita soft-drink consumption patterns and the material's infinite recyclability loop. Food cans retain structural importance for processed tomato paste, canned fish, and condensed milk distribution across modern trade and traditional retail channels. Aerosol cans represent a specialized growth pocket tied to personal care and household product expansion in urban centers.
SFDA governs food-contact compliance and migration testing for interior can coatings, while SASO administers material standards and conformity assessment procedures for imported metal packaging substrates. The Saudi Standards, Metrology and Quality Organization enforces labeling and recyclability marking requirements that influence supplier qualification timelines. Stakeholders must monitor evolving extended producer responsibility frameworks and alignment with circular economy targets set under Vision 2030 diversification mandates.
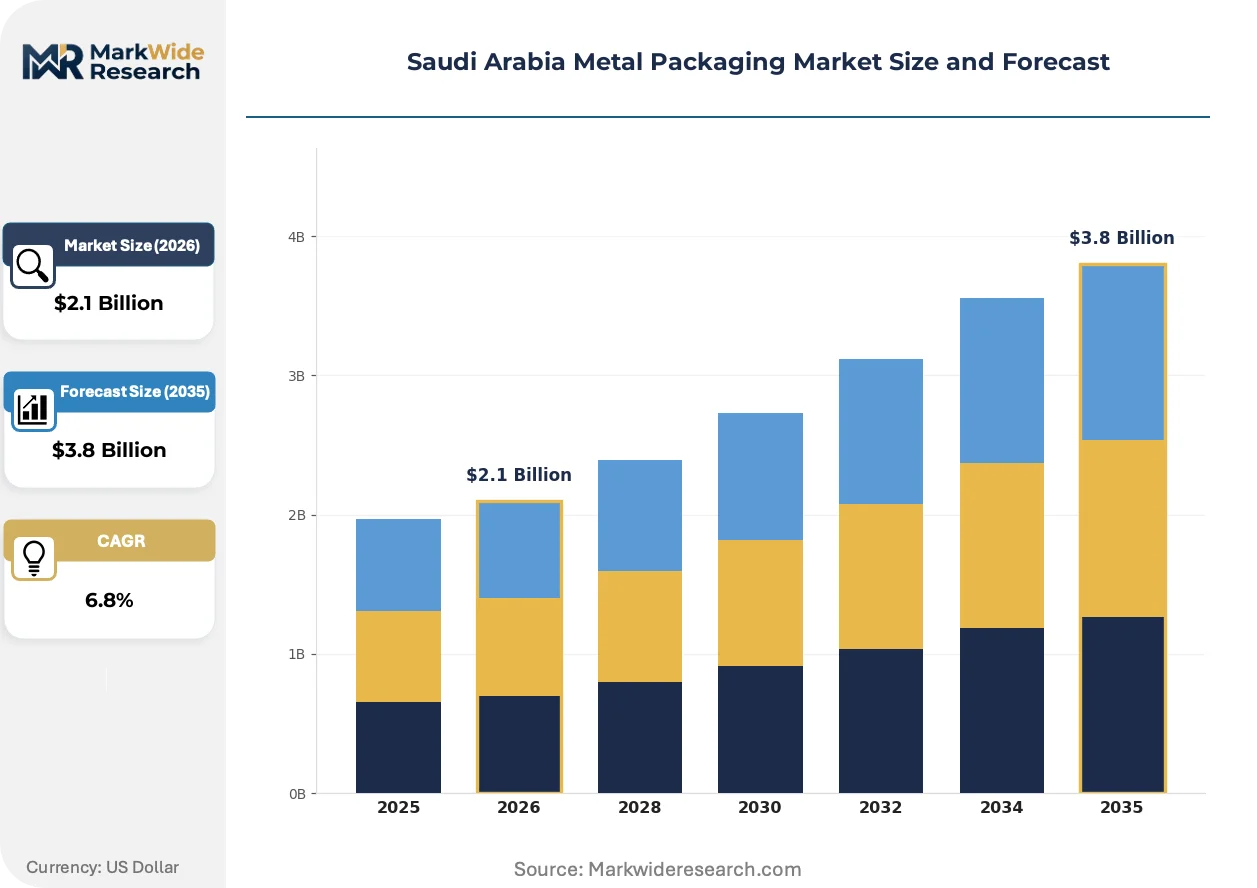
Market Dynamics
The Saudi Arabia Metal Packaging Market pivots on tightening food-contact material standards from SFDA, which are forcing converters to reformulate interior coatings and recertify supply lines ahead of phased migration-limit deadlines.
Growth Catalysts
- Saudi Green Initiative procurement mandates:Beverage bottlers now require aluminum can volumes with verified recycled content thresholds, pulling domestic conversion capacity toward lightweight two-piece designs.
- Dairy sector clustering in Riyadh's industrial corridor:Processed milk and laban processors concentrate procurement within 150-kilometer delivery radii, reducing logistics friction for regional can suppliers.
- Extended producer responsibility frameworks:Draft circular economy regulations under Vision 2030 signal deposit-return scheme adoption, incentivizing metal packaging recyclability investments.
Market Restraints
- Epoxy-based coating substitution costs:Bisphenol-A migration limits force accelerated transition to polyester and vinyl organosol alternatives, raising per-unit coating expenses by 15-22 percent during qualification periods.
- Aluminum coil import dependency:Domestic smelting capacity concentrates primary metal supply, but cold-rolled can-body stock relies on GCC and European mill shipments subject to SASO conformity delays.
- Rigid plastic substitution in condiments:Tomato paste and cooking oil packers trial multilayer polymer pouches for portion-control formats, threatening food-can volume in traditional retail channels.
Strategic Opportunities
- Neom and Red Sea Project hospitality supply:Premium beverage and aerosol personal care demand from giga-project construction camps and future tourism infrastructure outpaces current can-filling capacity.
- Aerosol can growth in Jeddah-Dammam urban corridor:Personal care contract manufacturers expand household product lines, requiring tinplate aerosol volumes with lithographed branding capabilities.
- SASO recyclability marking harmonization:Standardized sorting-code requirements create first-mover advantage for converters offering pre-certified packaging to modern-trade retailers.
Industry Challenges
- Coating chemist talent scarcity:SFDA-compliant formulation expertise concentrates among expatriate technical staff, constraining R&D velocity for domestic can-coating operations.
- Migration-testing laboratory bottleneck:SFDA-recognized third-party testing capacity faces six-month queue times, delaying new product approvals and customer qualification cycles.
- Legacy three-piece can line retrofit costs:Steel food-can producers face capital decisions on welding-equipment upgrades versus asset retirement as two-piece aluminum gains share.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Metal Packaging Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canisters, Aerosol Cans, Beverage Cans, Food Cans End User: Food Industry, Beverage Manufacturers, Personal Care, Household Products Material: Aluminum, Steel, Tinplate, Stainless Steel Packaging Type: Rigid Packaging, Flexible Packaging, Containers, Closures |
| Companies Covered | AFMACO, Saudi Can Co Ltd, Ball Corporation, Can-Pack SA, Sapin WLL, Crown Holdings Inc, MSCANCO, Southern Can Making Co Ltd, Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Metal Packaging Market Evolving Landscape
Material science and regulatory compliance are converging to redefine conversion economics. Can makers balance coating reformulation against lightweighting targets while recyclability verification becomes a competitive differentiator in procurement decisions.
Water-based interior coatings are expanding into beverage can applications as polyester-acrylic hybrids demonstrate equivalent sulfur-resistance to epoxy predecessors. Carbonated soft-drink bottlers in Riyadh and Jeddah are qualifying these formulations at commercial scale. The shift is expanding into food-can segments previously blocked by acidic-content migration concerns, compressing the epoxy coating supply base.
SFDA's tightened migration limits for food-contact materials are forcing coating suppliers to resubmit technical files with extended extraction testing protocols. Industrial consequence includes six-to-nine-month approval delays for reformulated products. Dairy and infant nutrition can segments are most affected, with processors maintaining dual-qualified supplier rosters to mitigate qualification-gap risks.
Buyer consolidation among dairy processors is compressing supplier negotiation cycles and unbundling technical service from base can pricing. Modern-trade retailers now specify recyclability certification as a listing prerequisite. This behavioral shift concentrates procurement leverage with Riyadh-based bottlers possessing scale to mandate coating transparency and recycled-content verification.
Saudi Arabia Metal Packaging Market Segmentation
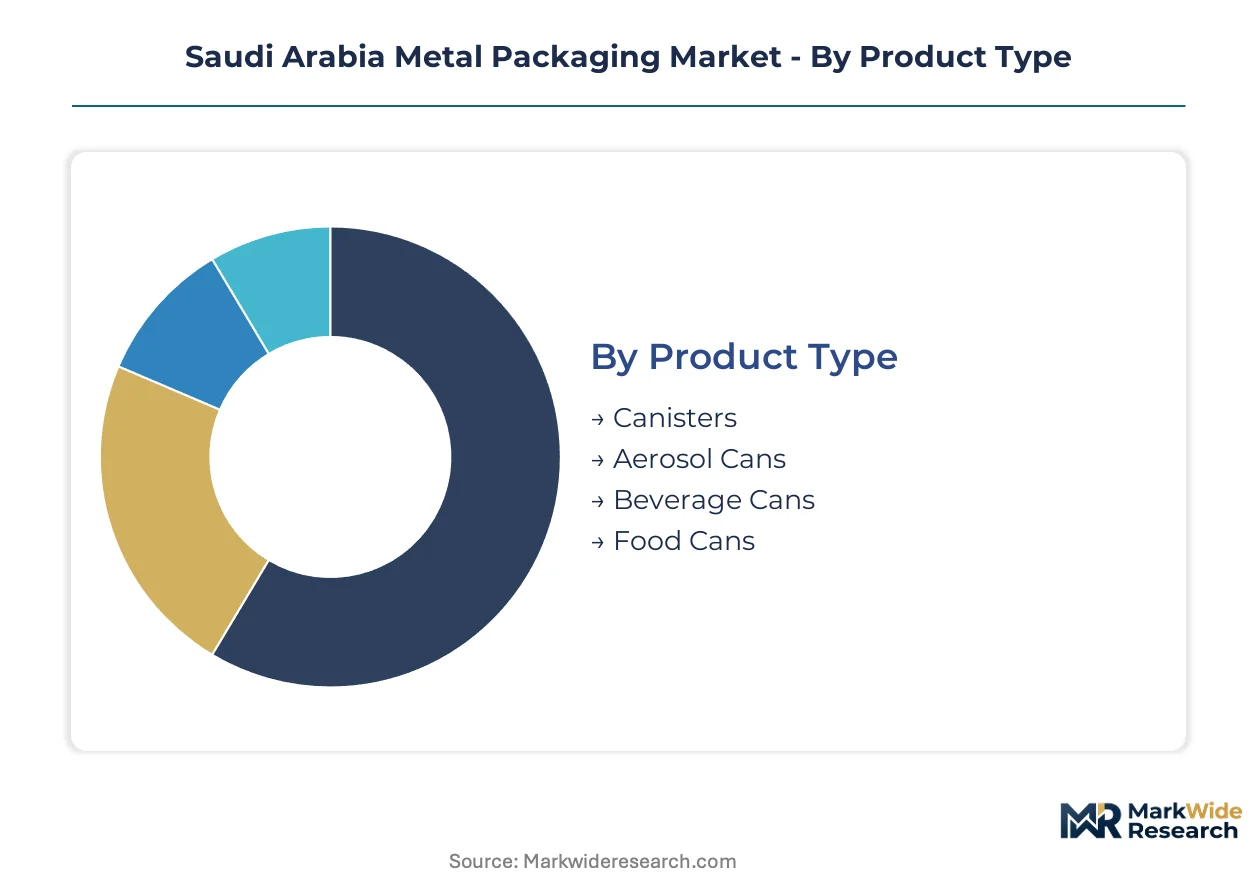
Saudi Arabia's metal packaging market segments along material, end-use, and format dimensions that each carry distinct regulatory and supply-chain implications. Understanding these divisions reveals where coating reformulation pressures, import dependencies, and circular-economy investments concentrate.
Product Type:
Equipment replacement cycles in Saudi conversion plants favor formats compatible with two-piece drawing and wall-ironing technology over legacy three-piece welding lines.
- Beverage Cans:Two-piece aluminum bodies with reduced wall thickness meet Saudi Green Initiative recycled-content thresholds. Carbonated soft-drink bottlers in Riyadh and Jeddah drive procurement volumes requiring lightweight coil-coated stock.
- Food Cans:Three-piece welded steel construction dominates processed tomato paste and canned fish distribution. SFDA migration-limit tightening forces accelerated interior-coating transitions from epoxy to polyester-vinyl organosol alternatives.
- Aerosol Cans:Tinplate cylinders with lithographed branding serve personal care contract manufacturers expanding household product lines.
- Canisters:General-purpose metal containers support industrial lubricant and specialty chemical packaging with lower regulatory compliance burdens.
Beverage Cans sits at the top of the volume ranking, with Aerosol Cans climbing the fastest.
End User:
Customer consolidation patterns across Saudi Arabia's food and beverage supply chain reshape procurement leverage and technical-service expectations.
- Beverage Manufacturers:Scale concentration among Riyadh-based carbonated soft-drink and bottled-water processors enables mandated recycled-content verification and coating transparency requirements.
- Food Industry:Dairy processors cluster within 150-kilometer delivery radii of conversion plants, compressing logistics costs for regional can suppliers serving laban and processed milk segments.
- Personal Care:Contract manufacturers in the Jeddah-Dammam urban corridor expand aerosol volumes for deodorant and hair-care products.
- Household Products:Surface cleaners and air freshener packers trial tinplate aerosol formats with portion-control actuators.
Beverage Manufacturers command the largest procurement scale, with Personal Care gaining share fastest on giga-project hospitality demand.
Material:
Domestic smelting and rolling capacity limitations create import dependency patterns that vary by substrate specification and SASO conformity assessment timelines.
- Aluminum:Primary metal supply concentrates at domestic smelters, but cold-rolled can-body stock relies on GCC and European mill shipments subject to conformity delays.
- Tinplate:Electrolytic tin-coated steel serves aerosol and food-can segments requiring deep-draw formability and corrosion resistance.
- Steel:TFS (tin-free steel) alternatives emerge in food-can applications as coating reformulation reduces dependency on tin barrier properties.
- Stainless Steel:Premium corrosion-resistant substrates support specialty chemical and high-acid food applications with extended shelf-life requirements.
Aluminum dominates beverage-format procurement, with Tinplate expanding most quickly on aerosol personal-care demand.
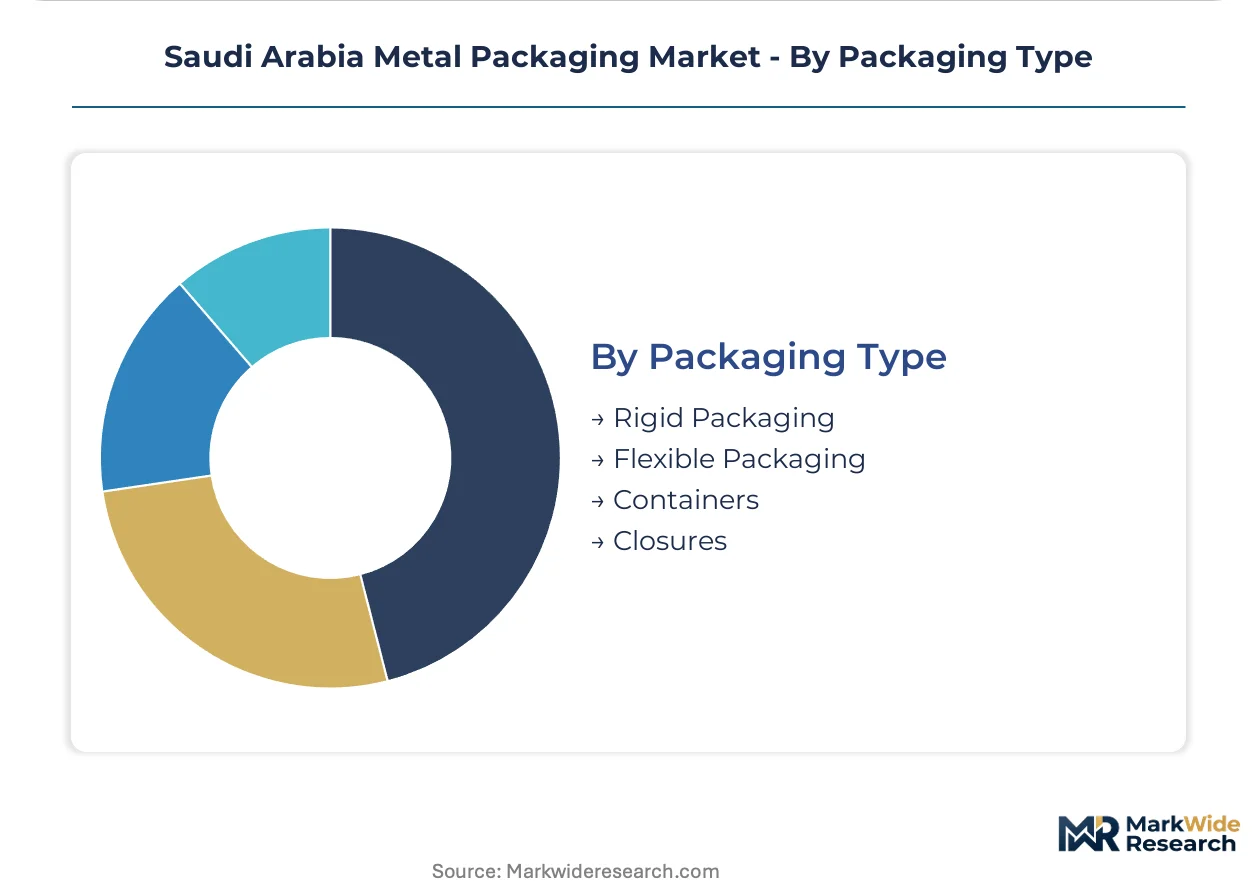
Packaging Type:
Format flexibility requirements from modern-trade retailers and Neom giga-project hospitality suppliers drive differentiation between structural and closure components.
- Rigid Packaging:Hermetic sealing and mechanical protection properties define metal can value propositions against multilayer polymer pouch substitution threats in condiment segments.
- Containers:Open-top and general-line cans support industrial and institutional foodservice volumes with lower decoration and coating complexity.
- Closures:Easy-open ends and screw caps represent high-margin components where converter technical capabilities differentiate procurement decisions.
- Flexible Packaging:Limited metal presence; foil laminates compete in premium chocolate and pharmaceutical blister applications outside core rigid-can markets.
Rigid Packaging anchors the material volume base, with Closures capturing the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's metal packaging sector traces its industrial roots to the 1970s petrochemical buildout, when state-led downstream investments created captive demand for steel and aluminum conversion. The kingdom's packaging infrastructure expanded in lockstep with dairy pasteurization and soft-drink bottling investments during successive five-year development plans.
Riyadh
Riyadh commands the kingdom's beverage can procurement volume through concentrated carbonated soft-drink and bottled-water bottler operations. SFDA's tightened migration limits for food-contact materials are forcing coating reformulation across Riyadh-based conversion plants. The Riyadh industrial corridor hosts Saudi Can Co Ltd facilities positioned within 150-kilometer delivery radii of dairy processors.
Eastern Province
Eastern Province anchors aluminum supply chain integration through proximity to domestic smelting capacity at Ras Al-Khair. SASO conformity assessment procedures for imported cold-rolled can-body stock create compliance friction for Eastern Province converters. The Dammam-Jubail industrial zone concentrates aerosol can demand from personal care contract manufacturers.
Western Region
Jeddah serves as the primary import gateway for European and GCC mill shipments of tinplate and coil-coated aluminum. The city's Red Sea port infrastructure handles can-body stock subject to six-month SFDA-recognized laboratory testing queues. Jeddah-based packers are trialing water-based interior coatings for beverage applications at commercial scale.
NEOM Northwest
NEOM giga-project construction camps are generating premium beverage and aerosol personal care demand that outpaces current can-filling capacity. Vision 2030 circular economy targets are mandating recyclability verification for packaging supplied to NEOM hospitality infrastructure. The northwest development zone is attracting coating suppliers with SFDA-compliant formulation capabilities.
Saudi Arabia Metal Packaging Market Competitive Landscape
Capital-heavy coil-coating and conversion plant operators compete with asset-light trading and technical-service specialists for procurement relationships with Riyadh-based bottlers. Market structure concentrates around three multinational fabricators with regional coil-coating infrastructure and a cluster of domestic converters competing on proximity logistics. Strategic archetypes separate global substrate suppliers, regional conversion specialists, and local fabrication contractors. Dominant competitive moves include coating technology licensing agreements and backward integration into recycled-content aluminum sourcing.
Among multinational fabricators, Ball Corporation and Crown Holdings Inc exemplify the capital-intensive archetype with dedicated regional production lines. Saudi Can Co Ltd occupies a position within the domestic proximity-competitor tier, anchoring supply relationships through geographic adjacency to Riyadh's dairy processing cluster. These three entities represent distinct competitive positioning strategies: technology-led lightweighting, aerosol segment specialization, and logistics-optimized regional service.
| Leading Market Players |
|---|
| AFMACO |
| Saudi Can Co Ltd |
| Ball Corporation |
| Can-Pack SA |
| Sapin WLL |
| Crown Holdings Inc |
| MSCANCO |
| Southern Can Making Co Ltd |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Aluminum coil import costs cascade through three distinct pricing tiers for beverage can converters, with SASO conformity assessment delays amplifying cost premiums for Riyadh-based bottlers seeking SFDA-compliant coated stock. Cold-rolled can-body stock from European and GCC mills carries qualification-period surcharges that compress margins for domestic converters serving dairy processors within the 150-kilometer delivery radius.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SFDA pre-certified converters from qualification-pending suppliers and generic traders. Price differentiation rests on coating transparency documentation and recycled-content verification thresholds mandated under Saudi Green Initiative procurement rules. Cost compression in the standard tier is intensifying because epoxy-to-polyester coating transitions raise per-unit expenses during extended migration-testing queues. Beverage manufacturers with scale command least price sensitivity, while regional dairy processors exhibit highest elasticity to logistics-adjusted delivered costs.
Supply Chain Analysis
Domestic-content mandates under Vision 2030 circular economy frameworks are reshaping sourcing patterns for cold-rolled aluminum and electrolytic tinplate. Primary aluminum draws from domestic smelters at Ras Al-Khair, but can-body stock feeds from GCC rolling mills and European suppliers subject to six-month SFDA laboratory testing bottlenecks. Tinplate for aerosol applications sources from South Korean and Japanese mills with established SASO conformity pathways. Single-source vulnerability concentrates in coating formulation inputs, where expatriate technical expertise constrains domestic substitution. Distribution runs through Jeddah's Red Sea port infrastructure for imported substrates, with final-mile delivery clustering around Riyadh's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's metal packaging sector functions as a regulatory compounder, where SFDA's phased migration-limit deadlines for food-contact materials are forcing capital deployment into coating reformulation capacity ahead of qualification bottlenecks.
For Market Incumbents: Hedge epoxy coating obsolescence by accelerating polyester-vinyl organosol qualification timelines and securing dual-certified supplier rosters for dairy segment continuity. Backward integration into recycled-content aluminum sourcing through GCC mill partnerships defends margin position against import dependency premiums. Capacity retention in Riyadh's 150-kilometer delivery zone preserves logistics-advantaged relationships with consolidated dairy processors. For New Entrants and Emerging Players: Water-based interior coating technology offers a technology-first wedge into beverage can segments where Ball Corporation and Crown Holdings face reformulation lag. White-space concentrates in NEOM giga-project hospitality supply, where premium aerosol and beverage demand outpaces current filling capacity. A coating-chemistry technical-service model, staffed with SFDA-recognized formulation expertise, provides the most penetrable go-to-market angle against multinational fabricators. For Investors and Strategic Acquirers: Consolidation pressure builds where coating chemist talent scarcity and six-month laboratory testing queues strand sub-scale converters without qualification bandwidth. Long-term viability favors asset-light technical-service specialists with pre-certified formulation libraries over capital-heavy three-piece can line operators facing retrofit decisions. Watch SFDA extended producer responsibility framework finalization as the inflection signal for deposit-return scheme economics and recyclability verification monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Reformulation Partnership | Polyester-acrylic hybrid qualification with SFDA-recognized laboratories accelerates product approval timelines. |
| Recycled Content Verification Program | Saudi Green Initiative compliance creates procurement preference with Riyadh-based carbonated soft-drink bottlers. |
| Regional Conversion Capacity Expansion | Two-piece aluminum line investment in Eastern Province reduces GCC coil import logistics friction. |
| Technical Service Specialization | Expatriate coating chemist teams differentiate domestic converters facing talent scarcity constraints. |
| NEOM Hospitality Supply Agreement | Premium beverage and aerosol volumes from giga-project construction camps outpace existing can-filling capacity. |
Research Methodology
Multiple input streams — primary interviews with coating formulation chemists, can plant operations managers, and dairy procurement directors; secondary validation through SASO conformity assessment records, SFDA technical file submissions, and GCC aluminum trade statistics; plus customs documentation for cold-rolled coil shipments — were reconciled through bottom-up and top-down triangulation. Conversations with personal care contract manufacturers in the Jeddah-Dammam corridor and beverage bottler technical service teams informed demand-side segmentation assumptions.
Historical volume trajectories were cross-referenced against panel input from regional conversion specialists to derive expansion rates across the projection horizon. Segmentation dimensions modeled include material substrate, end-use application, format type, and regional production cluster. CAGRs were synthesized from installed capacity utilization rates, coating reformulation investment cycles, and procurement pattern shifts under Vision 2030 circular economy mandates.
The model holds under stable SFDA regulatory implementation timelines and sustained Saudi Green Initiative procurement enforcement; deviation in laboratory testing queue durations or extended producer responsibility scheme adoption schedules would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
North America 3 Piece Metal Cans Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Three Piece Cans Market
Metal Packaging
Metal Packaging Market
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Metal Containers Market
Metal Packaging
Europe Food Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
PTP Aluminum Foil Market