
 Household Aluminum Foils Market | 2026-2036
Household Aluminum Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Household Aluminum Foils Market Analysis
Subscription-based replenishment programs for household aluminum foils is hardening into a standard channel expectation, with retailers bundling auto-delivery with loyalty pricing. Hindalco Industries Ltd leverages its captive alumina-to-foil integration across Indian manufacturing complexes to sustain cost leadership in Asian supply. Reynolds Group Holdings anchors North American brand recognition through decades of retail shelf dominance. Eurofoil competes on specialized thin-gauge capabilities for European private-label converters.
Household aluminum foil is an annealed aluminum alloy product, typically rolled to thicknesses between 0.016 mm and 0.024 mm, with a composition centering on 1xxx or 8xxx series alloys for corrosion resistance and thermal conductivity; its primary commercial purpose is creating a complete moisture, oxygen, and light barrier for food preservation and cooking applications. Standard Weight rolls occupy the largest volume position across supermarket and wholesale channels, while Non-Stick variants command margin premiums through silicone or ceramic coatings that expand baking and grilling applications. Food Trucks represent the fastest-growing end-user category as mobile kitchen operators prioritize lightweight, disposable packaging solutions that minimize cleanup overhead.
The US FDA regulates direct food-contact aluminum foil under 21 CFR 177.1390, while the EU enforces REACH and F-Gas Regulation compliance for rolling lubricants and process emissions. India's BIS certification mandates dimensional tolerances and alloy purity standards for domestically sold household foil products. Stakeholders must monitor evolving extended producer responsibility frameworks and alloy cost volatility as dual inputs to capacity planning and geographic sourcing decisions.
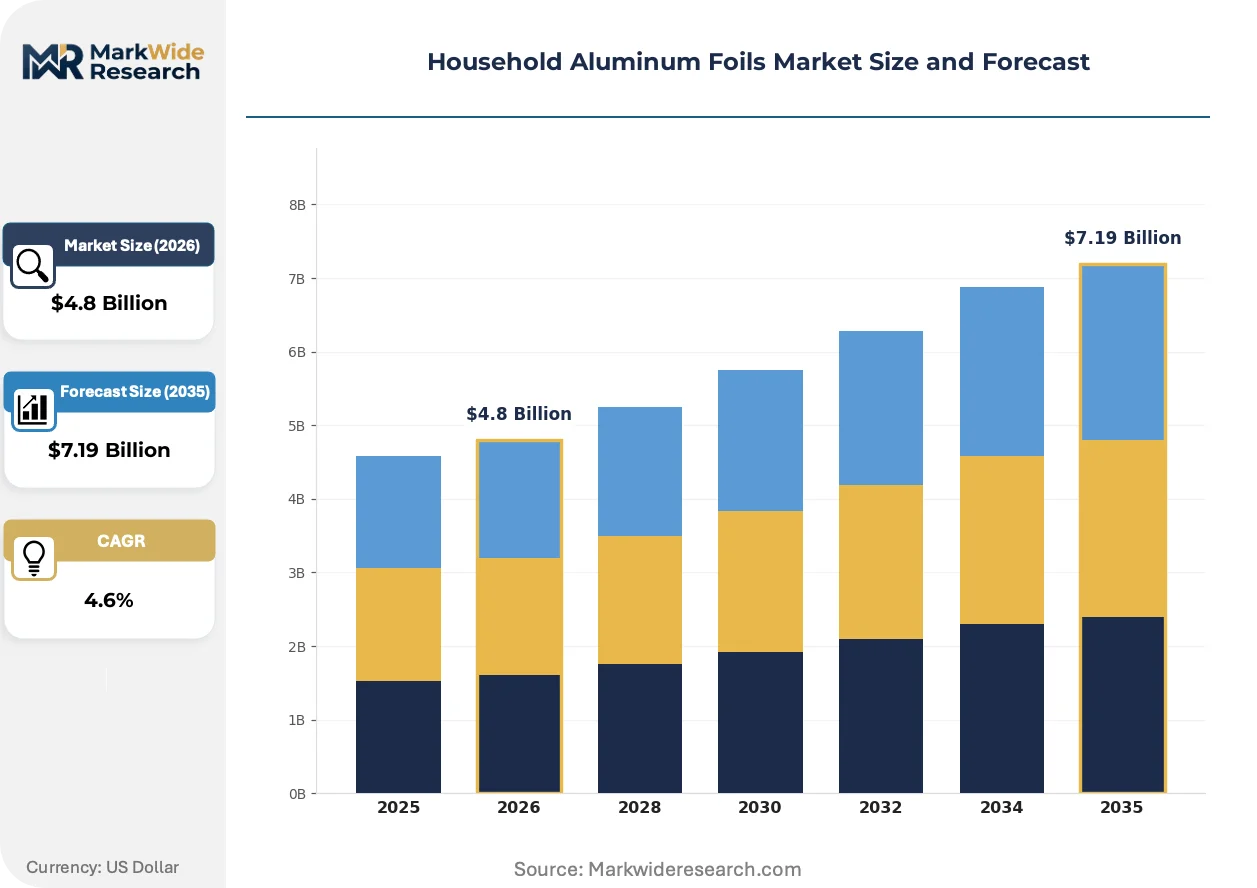
Market Dynamics
Commercial kitchen operators are pulling heavy-duty foil formats through restaurant and catering channels as heat tolerance requirements harden into procurement specifications, while European supply chains absorb material traceability mandates under tightening environmental frameworks.
Growth Catalysts
- Quick-service restaurant expansion:Food truck operators and mobile kitchen fleets are standardizing lightweight, disposable packaging solutions that minimize cleanup overhead across India and Southeast Asian urban corridors.
- F-Gas Regulation compliance:European rolling lubricant reformulation is accelerating process emission reductions, creating certified supply advantages for REACH-aligned converters serving private-label retail.
- Annealed alloy advancement:8xxx series corrosion resistance improvements are extending shelf-life performance in humid climates, penetrating modern trade channels in Mumbai, Delhi, and Bangalore.
Market Restraints
- Alumina cost volatility:Bauxite refining capacity concentration in Guinea and Australia transmits price instability directly to foil rolling margins, squeezing mid-tier converters.
- Substitution by silicone-coated parchment:Baking applications in European home kitchens are fragmenting as ceramic-coated parchment papers capture premium positioning for non-stick performance.
- REACH documentation burden:Extended producer responsibility frameworks are extending compliance timelines for alloy traceability, particularly impacting small-batch European converters.
Strategic Opportunities
- Subscription replenishment models:Auto-delivery bundling with loyalty pricing is hardening into standard retailer expectations across North American e-commerce platforms.
- Thin-gauge specialization:European private-label converters are capturing margin premiums through sub-0.018 mm capabilities for pharmaceutical blister pack crossover applications.
- BIS certification alignment:Indian dimensional tolerance mandates are creating first-mover advantages for domestic manufacturers with integrated alumina-to-foil complexes.
Industry Challenges
- Skilled rolling technician scarcity:Precision gauge control expertise is concentrating at legacy European and Japanese mill operators, constraining capacity expansion in emerging manufacturing bases.
- Legacy coating line retrofit costs:Silicone and ceramic application equipment upgrades are demanding capital deployment that fragments mid-cap converter competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Aluminum Foils Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Duty, Standard Weight, Non-Stick, Extra Wide Packaging Type: Rolls, Sheets, Pouches, Boxes End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Alcoa Corporation, Amcor plc, Hindalco Industries Ltd, Reynolds Group Holdings, Carcano Antonio S.p.A., Alufoil Products Pvt. Ltd, Flexifoil Packaging Pvt. Ltd., Eurofoil, Aluflexpack group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Aluminum Foils Market Emerging Trajectories
Active coating technologies and annealing process refinements are compressing performance differentiation between commodity and specialty foil grades, while regulatory traceability requirements reshape supply chain configuration.
Ceramic-silicone hybrid coatings are consolidating non-stick performance claims across baking and grilling applications. Quick-service restaurant procurement teams are specifying these formats for high-heat operational environments. The technology is consolidating premium tier positioning previously fragmented between pure ceramic and pure silicone alternatives.
REACH Article 33 disclosure obligations are extending material substance reporting through European household foil supply chains. Rolling lubricant chemistry reformulation is absorbing technical resources at converter operations. Private-label sourcing decisions in Germany, France, and Italy are increasingly screening suppliers on SCIP database registration status.
Auto-replenishment subscription models are compressing traditional wholesale-distributor channel control over household volume. North American retail platforms are displacing periodic stock-up purchases with algorithmic reorder systems tied to consumption telemetry. Food service procurement in the United States is converging on this pattern through integrated distributor portal contracts.
Household Aluminum Foils Market Segmentation
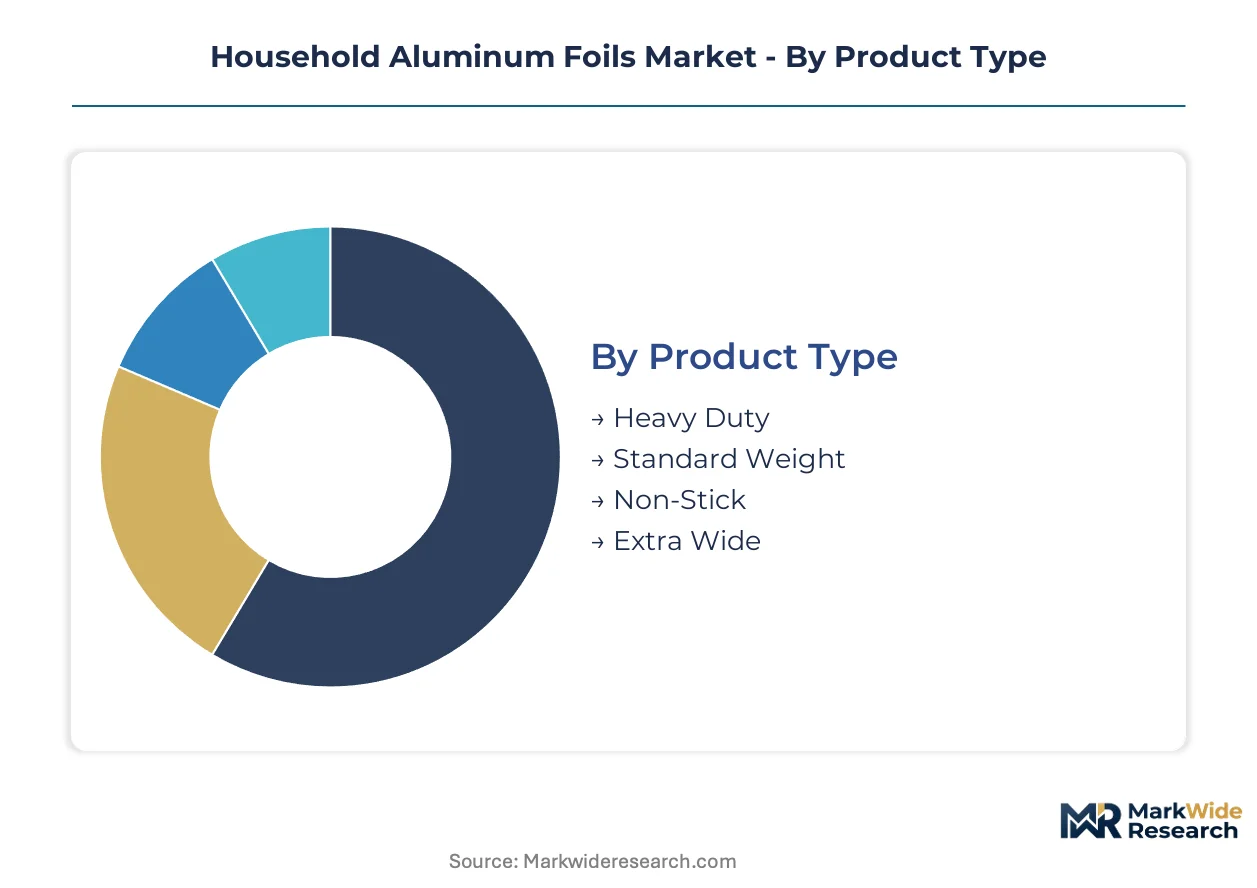
Household aluminum foil demand fragments across performance tiers and procurement contexts, with product specifications and packaging formats calibrated to distinct operational intensities. Channel configuration and end-user scale create divergent margin structures that reward specialized converter capabilities.
Product Type:
Customization intensity spans from commodity standardization to engineered performance layers, with coating technologies and gauge tolerances defining competitive positioning.
- Heavy Duty:Annealed 8xxx series alloys rolled to 0.024-0.030 mm thickness deliver elevated puncture resistance and thermal stability. Restaurant and catering procurement in Mumbai and Delhi specifies these formats for high-heat holding applications, with commercial kitchen operators absorbing 15-20% price premiums over standard gauges.
- Standard Weight:0.016-0.020 mm 1xxx series foil dominates supermarket and wholesale volume through cost-optimized rolling economics. Household penetration across Indian urban corridors pulls this segment through modern trade channels as primary cooking and wrapping substrate.
- Non-Stick:Ceramic-silicone hybrid coatings enable baking and grilling release performance without additional oiling.
- Extra Wide:Extended width formats target commercial barbecue and bulk food service coverage applications.
Most installed capacity flows through Standard Weight. Expansion is steepest in Non-Stick as coating technology costs compress.
Packaging Type:
Consumption occasion and storage constraints shape format selection, with mobility requirements and dispensing ergonomics driving differentiation.
- Rolls:Continuous wound formats with tear-edge perforations remain the baseline household configuration, with 30-meter and 75-meter lengths anchoring retail shelf presence across German and French hypermarkets. Standardization of core diameters enables dispenser interoperability that locks in replacement purchase cycles.
- Sheets:Pre-cut dimensions eliminate dispensing labor for food truck operators and catering prep lines, with interleaved stacking supporting rapid deployment in mobile kitchen environments across Southeast Asian urban corridors.
- Pouches:Flat-pack formats with resealable closures target travel and outdoor cooking segments.
- Boxes:Rigid dispensers with serrated cutting edges protect roll integrity in high-humidity storage conditions.
Roll formats command the greatest production asset deployment. Sheet configurations are gaining share fastest in commercial food service procurement.
End User:
Operational scale and cleanup overhead tolerance create distinct specification requirements across consumer and commercial domains.
- Households:Periodic stock-up purchasing through supermarket and online channels sustains volume foundation, with Indian urban household penetration expansion pulling growth through organized retail in Bangalore and Hyderabad.
- Restaurants:High-throughput kitchens specify heavy-duty gauges with batch-traceable alloy certification for heat-tolerance compliance, particularly under EU F-Gas Regulation documentation requirements for rolling lubricant chemistry.
- Catering Services:Event-scale volume demands drive wholesale procurement with palletized logistics optimization.
- Food Trucks:Mobile kitchen operators prioritize lightweight disposability and minimal cleanup overhead, with this category expanding most quickly across Indian and Southeast Asian metropolitan food corridors.
Household volume anchors converter capacity planning. Food Trucks are climbing the fastest as urban mobility dining scales.
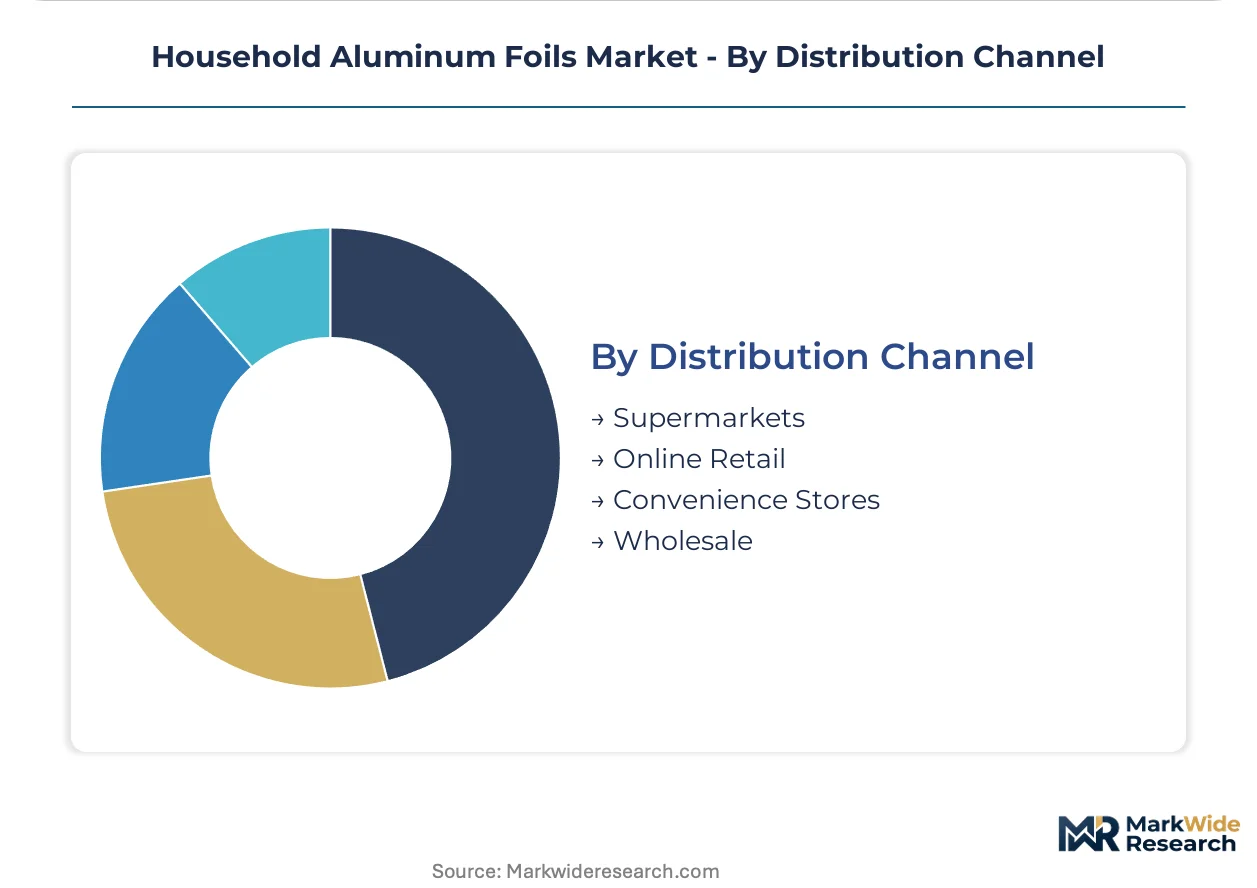
Distribution Channel:
Channel control and replenishment velocity determine working capital requirements and margin capture potential.
- Supermarkets:Organized retail shelf space allocation in the United States and Western Europe sustains brand visibility and impulse purchase conversion, with planogram positioning directly influencing household trial rates.
- Online Retail:Auto-replenishment algorithms and subscription bundling are displacing periodic stock-up behavior across North American e-commerce platforms, compressing traditional distributor channel control.
- Convenience Stores:Emergency purchase occasions capture premium pricing for travel-size formats.
- Wholesale:Pallet-scale procurement serves restaurant and catering volume with contract pricing structures.
Supermarket fixtures hold the greatest volume throughput. Online Retail is gaining share fastest as algorithmic replenishment hardens into consumer expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India pulls volume through modern trade channels faster than Germany, where regulatory documentation burdens compress converter margins. Urban household penetration and quick-service restaurant expansion drive divergent growth trajectories across these markets.
United States
Restaurant and catering procurement of heavy-duty foil formats anchors commercial demand, with food service operators prioritizing heat tolerance in high-throughput kitchen environments. FDA oversight under 21 CFR 177.1390 governs direct food-contact compliance. Chicago and Dallas metropolitan clusters concentrate distributor logistics for pallet-scale wholesale contracts.
Germany
REACH Article 33 disclosure obligations extend material substance reporting through private-label supply chains, screening supplier decisions on SCIP database registration. F-Gas Regulation compliance mandates rolling lubricant chemistry reformulation. The Ruhr industrial corridor hosts specialized thin-gauge converters serving pharmaceutical blister pack crossover applications.
India
Urban household penetration in Bangalore and Hyderabad expands organized retail volume through modern trade channels. BIS certification mandates dimensional tolerances and alloy purity standards for domestically sold products. Hindalco Industries leverages captive alumina-to-foil integration across manufacturing complexes to sustain cost leadership.
France
Supermarket planogram positioning in Paris and Lyon hypermarkets sustains brand visibility and impulse purchase conversion for standard-weight rolls. ECHA oversight aligns with EU-wide REACH frameworks for rolling lubricant emissions. The Auvergne-Rhône-Alpes region concentrates private-label converter capacity for European retail supply.
Japan
Precision gauge control expertise concentrates at legacy mill operators, constraining capacity expansion despite stable household demand. METI standards govern industrial process emissions alongside international ISO alignment. The Kansai corridor around Osaka maintains specialized annealing capabilities for corrosion-resistant 8xxx series alloys.
Household Aluminum Foils Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with retail shelf dominance contrasting against private-label converter flexibility. The vendor base organizes around three archetypes: integrated primary producers with captive alumina supply, specialized thin-gauge European converters, and regional contract manufacturers serving food service procurement. Consolidation pressures concentrate at mid-tier converters facing coating line retrofit costs and skilled technician scarcity. Dominant competitive moves include backward integration into alumina refining and geographic expansion through distributor portal contracts.
Among integrated primary producers, Hindalco Industries Ltd represents the captive supply archetype with India-based manufacturing scale. Reynolds Group Holdings anchors North American brand recognition through decades of retail presence. Eurofoil exemplifies the specialized thin-gauge capabilities serving European private-label demand. These three occupy distinct competitive positions without overlapping core segments.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Amcor plc |
| Hindalco Industries Ltd |
| Reynolds Group Holdings |
| Carcano Antonio S.p.A. |
| Alufoil Products Pvt. Ltd |
| Flexifoil Packaging Pvt. Ltd. |
| Eurofoil |
| Aluflexpack group |
| Others |
Supply Flow & Price Mechanics
Bauxite refining capacity concentration in Guinea and Australia transmits price instability directly to foil rolling margins, with alloy cost volatility compressing mid-tier converter economics while integrated producers sustain pricing power through captive alumina supply.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-weight foil grades as Hindalco's integrated complexes undercut regional converters. Three-tier pricing structure across heavy-duty, standard-weight, and non-stick levels separates heat-tolerance certification from commodity wrapping applications. Cost compression in European thin-gauge segments is intensifying because REACH documentation burdens extend compliance timelines. Quick-service restaurant procurement teams show least price sensitivity due to operational efficiency priorities, while household retail channels absorb margin pressure fastest.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale restaurant and catering procurement through palletized wholesale contracts. Raw material supply draws from bauxite mining in Guinea, Australia, and Brazil, with annealing expertise concentrating in Japan and Germany. Single-source vulnerability runs through rolling lubricant chemistry suppliers facing F-Gas Regulation reformulation mandates. Distribution runs through supermarket planogram fixtures in Western Europe and algorithmic auto-replenishment platforms across North American e-commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU F-Gas tightening and REACH Article 33 disclosure obligations are accelerating certified supply premiums for compliant converters.
For Market Incumbents: Anchor shelf presence through subscription bundling partnerships with North American retail platforms facing algorithmic replenishment consolidation. Defend margin structure by accelerating backward integration into alumina refining where bauxite access permits, while retrofitting coating lines for ceramic-silicone hybrid application before small-batch competitors fragment premium positioning. Threat substitution by silicone-coated parchment in European baking applications demands non-stick performance differentiation. For New Entrants and Emerging Players: Capture food truck procurement specifications across Indian and Southeast Asian urban corridors where lightweight disposability requirements outpace established converter response times. White-space availability concentrates in BIS-certified domestic supply for Indian modern trade channels, with thin-gauge pharmaceutical crossover applications offering margin shelter from commodity foil pricing. Go-to-market execution should leverage distributor portal contracts with integrated food service procurement platforms. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap European converters because REACH documentation burdens and coating line retrofit costs are fragmenting competitive viability for sub-scale operators. Acquisition targets should demonstrate SCIP database registration status and sub-0.018 mm thin-gauge capabilities serving private-label retail. Long-term viability hinges on alloy traceability infrastructure investment. Signal to watch: extended producer responsibility framework implementation timelines across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive bauxite supply insulates Hindalco from Guinea-Australia price transmission volatility. |
| Ceramic-Silicone Hybrid Coating Deployment | Non-stick performance claims consolidate premium tier positioning against parchment substitution. |
| Subscription Auto-Replenishment Partnership | Algorithmic reorder systems displace periodic stock-up behavior across North American retail. |
| REACH-Aligned SCIP Database Registration | Material substance reporting compliance screens private-label sourcing decisions in Germany and France. |
| Thin-Gauge Pharmaceutical Crossover Investment | Sub-0.018 mm capabilities capture margin premiums from European blister pack demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rolling mill operators, restaurant procurement managers, retail category buyers, and regulatory compliance officers with secondary validation from customs trade data, BIS certification records, ECHA SCIP database filings, and SEC disclosures from integrated aluminum producers. Bottom-up volume triangulation across product gauges and packaging formats was cross-checked against top-down market sizing from alumina consumption flows.
Historical reference periods anchored demand modeling across the projection horizon, with segmentation dimensions spanning alloy series specification, coating technology tier, end-user operational scale, and distribution channel control structure. CAGRs were derived from rolling capacity deployment schedules and urban household penetration trajectories, with forecast inputs incorporating F-Gas Regulation compliance timelines and quick-service restaurant expansion patterns across Indian metropolitan corridors.
Underlying measurement precision varies by segment; standard-weight roll volume through supermarket channels carries tighter precision than emerging food truck procurement estimates. Forecasts reflect assumptions about alloy cost transmission and regulatory implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Saudi Arabia Metal Packaging Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Metal Aerosol Can Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Brass Foils Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
GCC Metal Cans Market