
 Vietnam Metal Can Packaging Market | 2026-2036
Vietnam Metal Can Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Metal Can Packaging Market Analytics
Vietnam's Circular Economy Development Plan is shifting procurement criteria for metal packaging across domestic supply chains. Showa Aluminum Can Corporation leverages its technical heritage in lightweight aluminum forming to serve beverage bottlers throughout the Mekong Delta. Hanacan JSC anchors its position through integrated steel can production for processed food exporters. Ball Corporation competes on two-piece aluminum can technology optimized for carbonated soft drinks.
Metal can packaging comprises rigid containers fabricated from aluminum alloys, tinplate, or electrolytic chromium-coated steel, formed through deep drawing, wall ironing, or three-piece welding processes to create hermetically sealed vessels for shelf-stable goods. These containers provide oxygen barrier protection, mechanical durability, and infinite recyclability through established re-melting infrastructure. Aluminum cans dominate the product type landscape due to their superior strength-to-weight ratio and compatibility with high-speed filling lines. Steel cans sustain significant volume in processed seafood and condensed milk segments where puncture resistance outweighs weight considerations. The food and beverage end user category absorbs the majority of domestic output, while pharmaceutical applications occupy a premium tier demanding enhanced interior coating systems.
Vietnam's Ministry of Natural Resources and Environment administers packaging waste regulations that mandate extended producer responsibility for metal container recovery. The General Department of Vietnam Customs enforces import standards on tinplate substrate specifications under national technical regulations aligned with regional trade protocols. BIS-equivalent conformity assessment procedures for food-contact metal surfaces shape supplier qualification timelines. Stakeholders must monitor evolving deposit-return scheme proposals and alloy sourcing rules that will determine competitive positioning in the next planning cycle.
Market Dynamics
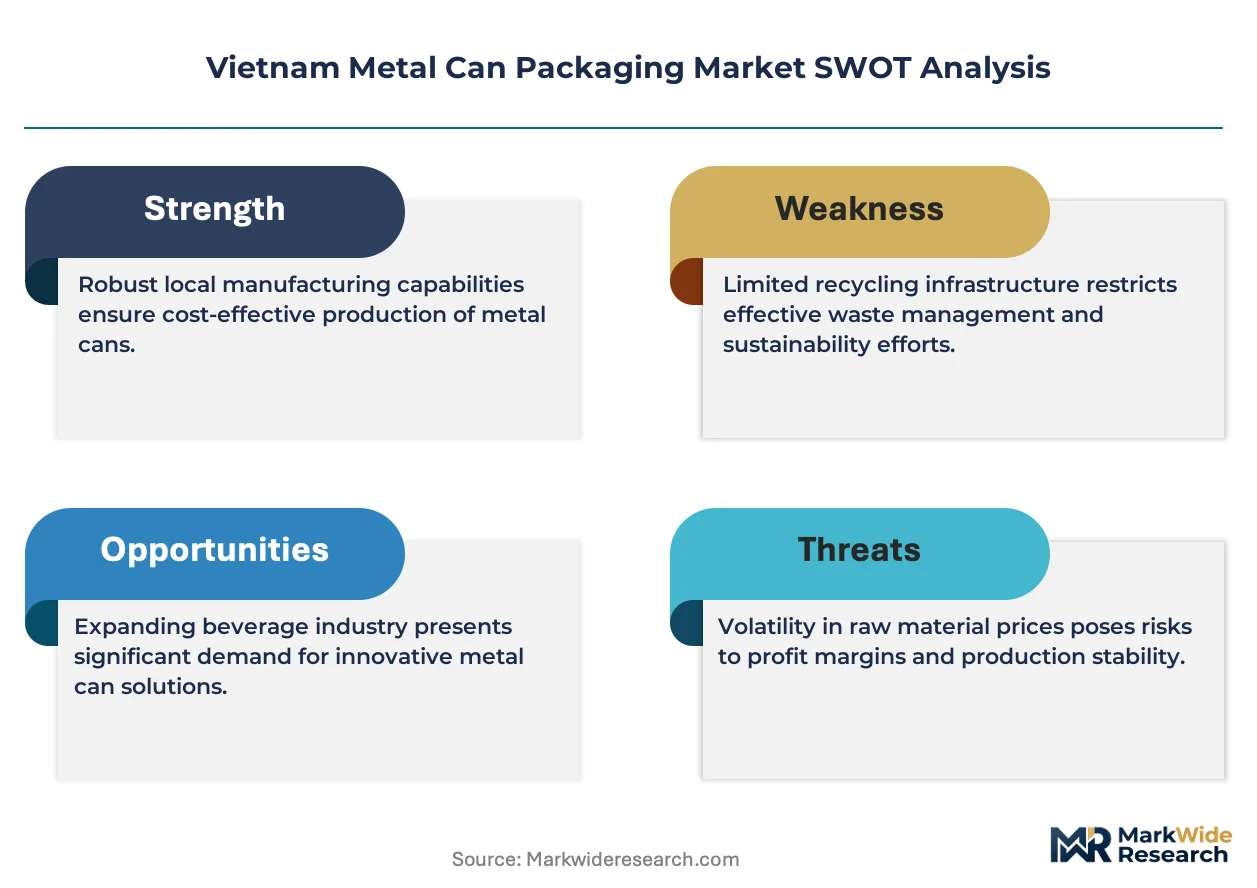
Vietnam's Ministry of Natural Resources and Environment is tightening extended producer responsibility mandates for metal packaging waste, forcing beverage bottlers and food processors to redesign procurement criteria around recyclability targets and alloy traceability requirements.
Growth Catalysts
- Deposit-Return System Proposals:Vietnam's Ministry of Natural Resources and Environment is advancing framework legislation for container recovery incentives that would accelerate aluminum can collection rates and secure feedstock for domestic re-melters.
- Carbonated Beverage Canning Lines:Beverage bottlers throughout the Mekong Delta are installing high-speed aluminum can filling equipment, creating pull demand for two-piece drawn-and-ironed containers with lightweight wall specifications.
- Processed Seafood Export Growth:Steel can demand from Vietnamese seafood processors shipping to Japanese and South Korean markets is expanding, driven by puncture-resistant three-piece welded designs for shelf-stable tuna and mackerel.
Market Restraints
- Primary Aluminum Price Volatility:Vietnamese can makers face margin compression from London Metal Exchange aluminum ingot price swings, with limited hedging infrastructure available to mid-tier converters.
- Tinplate Import Dependency:Domestic steel can production relies on electrolytic tinplate substrate from Chinese and South Korean rolling mills, exposing processors to supply disruption risks from regional trade protocol shifts.
- Coating Chemistry Constraints:Interior epoxy-phenolic lining systems for acidic food contact face technical limitations in sulfur-rich canned fish applications, restricting steel can penetration in premium seafood segments.
Strategic Opportunities
- Central Highlands Beverage Distribution:Underpenetrated rural provinces around Da Lat and Buon Ma Thuot present expansion targets for aluminum can logistics networks serving emerging bottled water and energy drink consumption.
- BIS-Equivalent Certification Fast-Track:Vietnam's conformity assessment alignment with Indian food-contact metal standards creates regulatory tailwinds for exporters targeting South Asian processed food markets.
- Digital Printing Convergence:Integration of high-definition inkjet decoration with lightweight aluminum forming is enabling shorter production runs and SKU proliferation for craft beverage micro-breweries.
Industry Challenges
- Deep-Drawing Die Engineering Talent:Vietnamese technical institutes produce insufficient specialists in multi-stage cupping press calibration, forcing can makers to recruit expatriate toolmakers from Thailand and Taiwan.
- Extended Producer Responsibility Compliance Timelines:The Ministry of Natural Resources and Environment's evolving alloy sourcing documentation rules are stretching supplier qualification cycles beyond eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Metal Can Packaging Market |
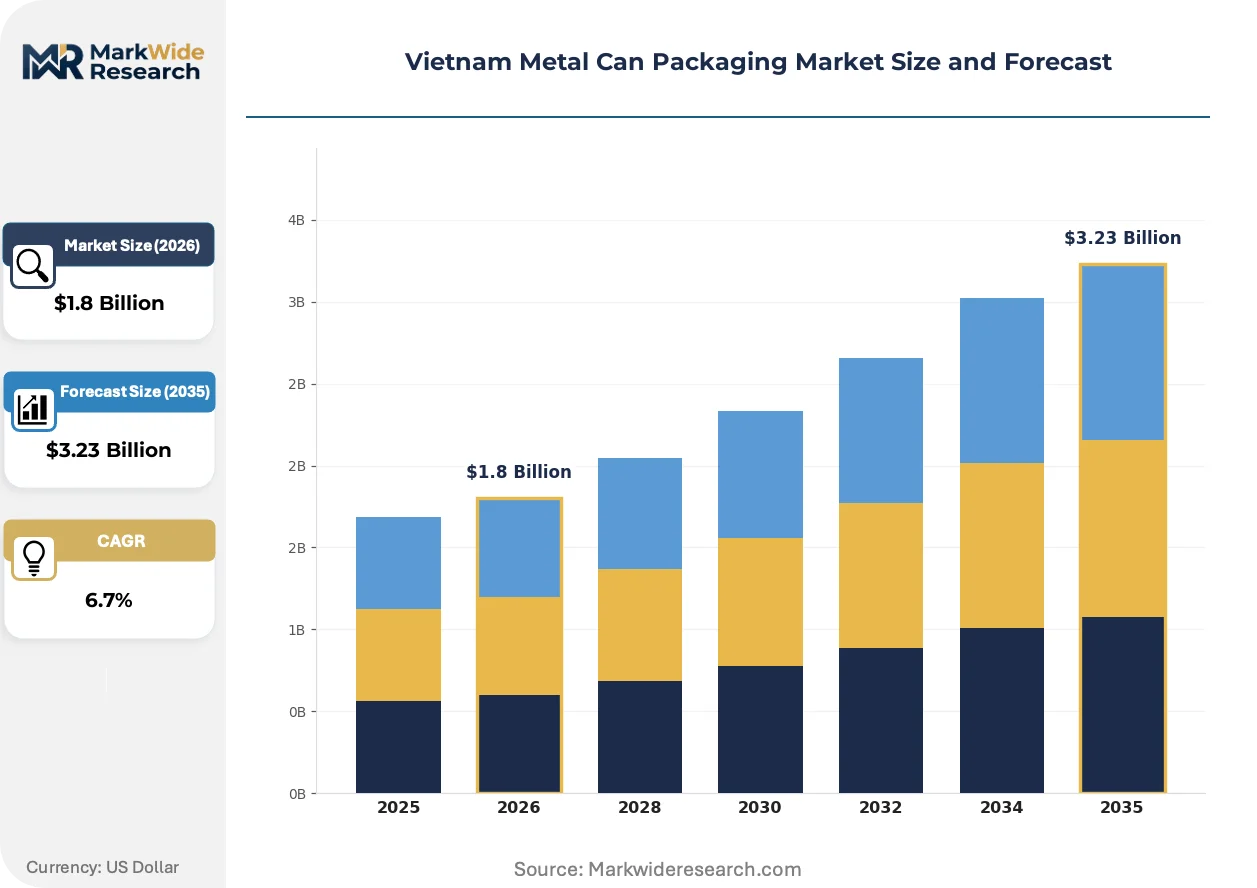
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Tinplate Cans, Specialty Cans End User: Food & Beverage, Personal Care, Household Chemicals, Pharmaceuticals Size: Small Size, Medium Size, Large Size, Custom Size Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Showa Aluminum Can Corporation, Hanacan JSC, Canpac Vietnam Co., Ltd, Superior Multi-packaging Limited (SMPL), Kian Joo Can (Vietnam) Co. Ltd, Ball Corporation, Nihon Canpack (Vietnam) Co., Ltd, Sunrise Group, Crown Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Metal Can Packaging Market Evolving Landscape
Lightweight aluminum forming technologies and regulatory pressure on packaging circularity are compressing traditional can design cycles and forcing rapid retooling across Vietnamese converter facilities.
Ultralight wall-ironing dies capable of producing sub-10-gram aluminum beverage cans are rewriting material efficiency benchmarks for carbonated soft drink packaging. Major bottlers in Ho Chi Minh City's industrial corridor are adopting these specifications for 330-milliliter formats. The technology is compressing per-unit aluminum consumption and enabling price repositioning against PET bottle alternatives.
Vietnam's Ministry of Natural Resources and Environment is implementing technical regulations on packaging waste sorting and collection infrastructure under its Circular Economy Development Plan. Metal can producers must now certify recycled content thresholds and establish reverse logistics partnerships with municipal waste operators. Beverage brands with national distribution networks face the steepest compliance burdens as they renegotiate supplier contracts.
Consolidated procurement by multinational beverage bottlers is displacing fragmented purchasing from regional distributors across southern Vietnam. Direct alloy sourcing agreements between global brand owners and aluminum rolling mills are replacing tiered converter relationships. This pattern is most visible in the Ho Chi Minh City industrial zone where three major bottlers now account for the majority of two-piece can offtake.
Vietnam Metal Can Packaging Market Segmentation
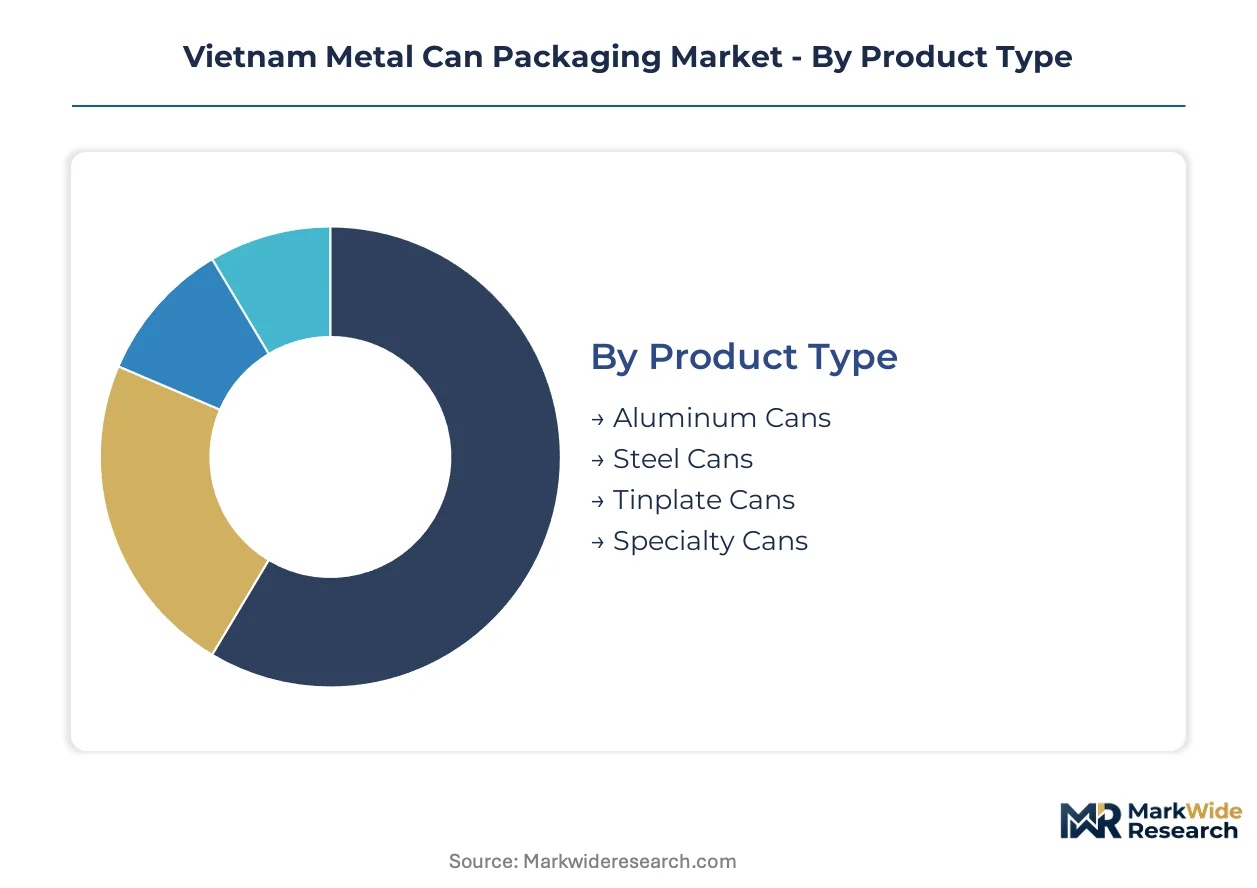
Segmentation in Vietnam's metal can packaging market reveals how regulatory requirements and end-use specifications fragment procurement patterns. Manufacturers must align production capabilities with distinct certification burdens across food-contact, pharmaceutical, and industrial chemical applications.
Product Type:
Aluminum cans require BIS-equivalent conformity assessment for food-contact surfaces under Vietnam's alignment with regional trade protocols. Steel and tinplate variants face additional scrutiny from the General Department of Vietnam Customs on substrate import specifications.
- Aluminum Cans:Fabricated through deep drawing and wall ironing from aluminum alloys with superior strength-to-weight ratios. Demand concentrates in Ho Chi Minh City's industrial corridor where carbonated beverage bottlers operate high-speed filling lines, driven by lightweight specifications that reduce per-unit material costs. Deposit-return system proposals from the Ministry of Natural Resources and Environment are accelerating collection infrastructure investments for this segment.
- Steel Cans:Constructed from electrolytic chromium-coated steel or tinplate through three-piece welding processes, delivering puncture resistance for shelf-stable goods. Processed seafood exporters in the Mekong Delta dominate procurement, with Japanese and South Korean market access requiring compliance with sulfur-resistant interior coating standards.
- Tinplate Cans:Rolled steel substrate with electrolytic tin coating for corrosion resistance in acidic food contact applications. The Ministry of Natural Resources and Environment's extended producer responsibility mandates apply to recovery and re-melting documentation.
- Specialty Cans:Custom-formatted containers with enhanced barrier properties for oxygen-sensitive or reactive contents. Pharmaceutical and premium cosmetic applications in Hanoi and Da Nang drive specification complexity.
Leading the category by volume: Aluminum Cans. Growing fastest: Specialty Cans.
End User:
Food-contact applications carry the heaviest regulatory load through the Ministry of Natural Resources and Environment's circular economy rules, while pharmaceutical tiers demand coating chemistry traceability beyond standard commercial requirements.
- Food & Beverage:Absorbs majority domestic output across carbonated drinks, beer, processed seafood, and condensed milk segments. Ho Chi Minh City bottlers and Mekong Delta seafood processors anchor demand, with aluminum canning lines expanding fastest for beverage applications.
- Personal Care:Aerosol and non-pressurized formats for cosmetics and grooming products. Urban distribution centers around Hanoi and Da Nang concentrate procurement, with shorter production runs enabled by digital printing convergence.
- Household Chemicals:Corrosion-resistant linings for cleaning agents and solvents. Industrial chemical safety standards shape supplier qualification timelines.
- Pharmaceuticals:Premium-tier demand for hermetic sealing and interior coating systems with full batch traceability. BIS-equivalent certification alignment creates export pathways to South Asian markets.
Food & Beverage commands the largest revenue share. Pharmaceuticals delivers the steepest margin expansion trajectory.
Size:
Volume scale determines tooling amortization and line efficiency, with medium formats optimizing throughput for mass-market beverage applications while custom dimensions serve craft micro-brewery proliferation.
- Small Size:Single-serve formats for energy drinks and specialty beverages. Convenience store distribution in urban Vietnam drives replenishment velocity.
- Medium Size:Standard 330-milliliter beverage cans and processed food tins. Ultralight wall-ironing dies capable of sub-10-gram specifications are compressing material benchmarks for this tier.
- Large Size:Family and food-service formats for condensed milk and cooking oils. Steel can construction dominates for puncture resistance during handling.
- Custom Size:Proprietary dimensions for brand differentiation and limited-batch craft production. Digital printing integration enables SKU proliferation without die-change penalties.
Medium Size generates the highest unit throughput. Custom Size is climbing the fastest on craft beverage demand.
Distribution Channel:
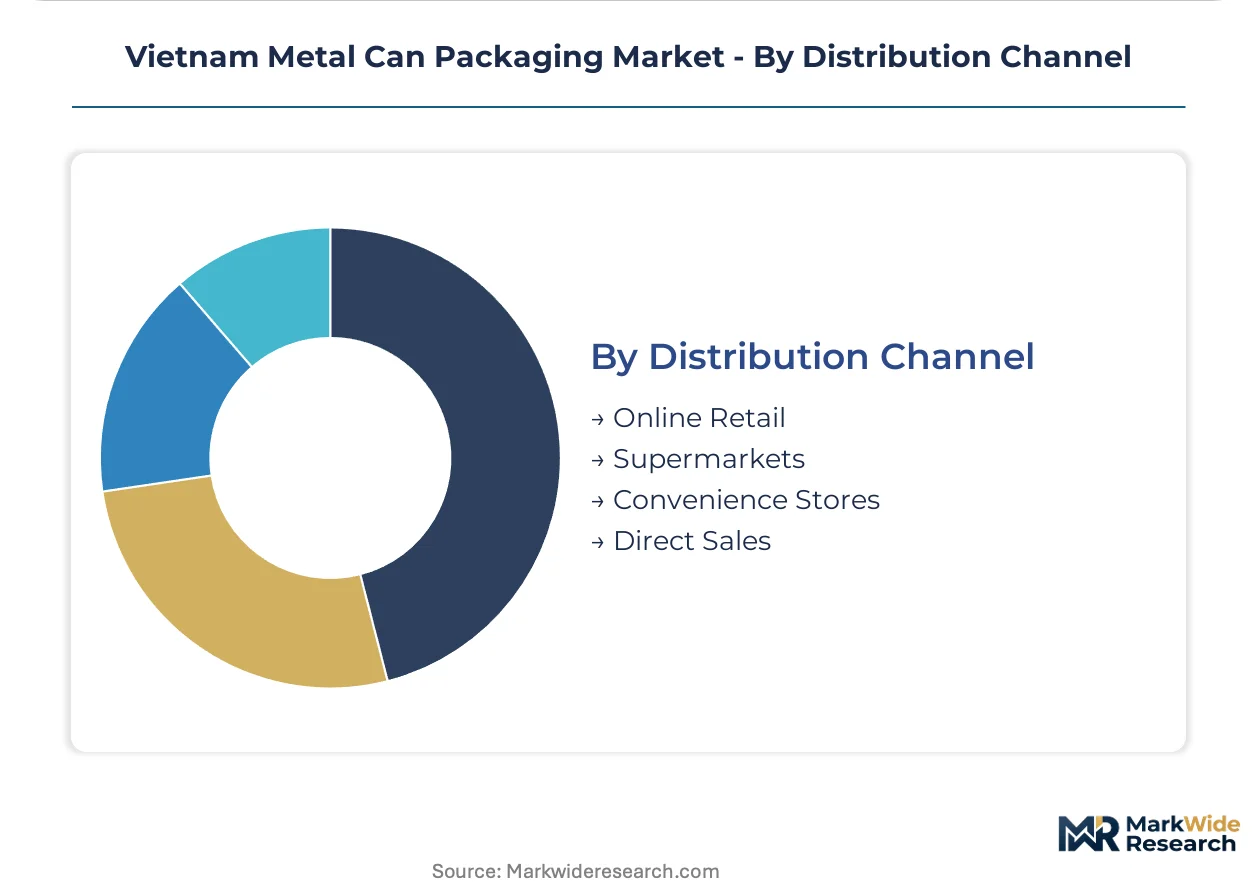
Channel selection shapes logistics network design, with direct sales capturing consolidated multinational procurement while traditional retail maintains penetration in underdeveloped rural corridors.
- Online Retail:E-commerce platforms serving household chemical and personal care segments. Last-mile packaging requirements differ from palletized bulk formats.
- Supermarkets:Mass-market beverage and food can offtake in Ho Chi Minh City and Hanoi metropolitan areas. Shelf-ready display specifications influence secondary packaging design.
- Convenience Stores:High-velocity replenishment for single-serve beverage formats. Urban density in southern Vietnam supports distribution frequency.
- Direct Sales:Alloy sourcing agreements between global brand owners and rolling mills are displacing tiered converter relationships. Three major bottlers in the Ho Chi Minh City industrial zone now account for the majority of two-piece can procurement through this channel.
Direct Sales leads by value concentration. Online Retail is expanding most quickly on digital commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's industrial corridor anchors Vietnam's metal can packaging demand, with the surrounding Mekong Delta provinces supplying processed seafood exporters and beverage bottlers operating high-speed filling lines.
Southern Key Economic Region
Beverage bottlers in Binh Duong and Dong Nai provinces are installing wall-ironing equipment for ultralight aluminum cans. The Ministry of Natural Resources and Environment's extended producer responsibility mandates are forcing these facilities to document alloy sourcing and establish reverse logistics partnerships. Can Tho and Long An industrial zones concentrate steel can production for tuna and mackerel exports to Japan.
Central Coast
Da Nang and Quang Nam provinces are emerging as secondary packaging hubs for craft beverage micro-breweries seeking digital printing capabilities. Provincial environmental departments are implementing Circular Economy Development Plan requirements for packaging waste sorting infrastructure. The Chu Lai Open Economic Zone hosts converters serving personal care and household chemical distributors.
Northern Red River Delta
Hanoi and Hai Phong metropolitan areas drive pharmaceutical-grade specialty can demand with enhanced barrier specifications. The General Department of Vietnam Customs enforces BIS-equivalent conformity assessment on tinplate imports through Hai Phong port. Bac Ninh and Hung Yen industrial parks accommodate food-contact metal surface coating facilities.
Central Highlands
Dalat and Buon Ma Thuot present underpenetrated expansion targets for aluminum can logistics networks serving bottled water and energy drink distribution. Provincial trade departments are negotiating with beverage brands on rural route density. Lam Dong and Dak Lak lack established can collection infrastructure for deposit-return scheme preparation.
Mekong Delta
An Giang and Tien Giang provinces anchor processed seafood canning for Japanese and South Korean market access requiring sulfur-resistant interior coatings. The Ministry of Natural Resources and Environment's alloy traceability rules are stretching supplier qualification cycles for these exporters. Vinh Long and Ben Tre host three-piece welded can fabrication for condensed milk and cooking oil.
Vietnam Metal Can Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating chemistry and certification tiers, with pharmaceutical-grade specialists commanding pricing separation from mass-market beverage converters. The vendor base clusters around three strategic archetypes: Japanese-Korean technical heritage firms with lightweight forming expertise, integrated steel can producers serving processed food exporters, and multinational two-piece aluminum specialists aligned with global beverage brands. Competitive moves concentrate on direct alloy sourcing agreements displacing tiered converter relationships, and digital printing integration enabling shorter production runs for craft beverage proliferation.
Within the technical heritage tier, Showa Aluminum Can Corporation represents Japanese lightweight forming capabilities, while Hanacan JSC exemplifies integrated domestic steel can production. Ball Corporation anchors the multinational aluminum technology vector. These three occupy positions across distinct margin tiers rather than competing directly for identical customer relationships.
| Leading Market Players |
|---|
| Showa Aluminum Can Corporation |
| Hanacan JSC |
| Canpac Vietnam Co., Ltd |
| Superior Multi-packaging Limited (SMPL) |
| Kian Joo Can (Vietnam) Co. Ltd |
| Ball Corporation |
| Nihon Canpack (Vietnam) Co., Ltd |
| Sunrise Group |
| Crown Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Consolidated procurement by multinational beverage bottlers in Ho Chi Minh City's industrial corridor is forcing tiered converter relationships toward direct alloy sourcing agreements, compressing margins for mid-tier fabricators while rewarding rolling mills with volume-backed pricing power.
Pricing Analysis
Throughput-based pricing anchors aluminum can procurement, with beverage bottlers negotiating per-unit rates tied to line-speed guarantees and lightweight wall specifications. Price differentiation separates pharmaceutical-grade specialty cans with full coating traceability from mass-market beverage formats. Cost compression in standard aluminum grades is intensifying because London Metal Exchange volatility outpaces hedging infrastructure. Regional seafood processors show highest price sensitivity, while pharmaceutical buyers absorb premium tiers for hermetic sealing documentation.
Supply Chain Analysis
Regional distribution centers in Binh Duong and Dong Nai provinces operate hub-and-spoke patterns feeding Mekong Delta filling lines and northern Red River Delta pharmaceutical facilities. Raw material sourcing draws from Chinese and South Korean tinplate rolling mills, Vietnamese aluminum smelters, and Japanese coating chemical suppliers. Single-source vulnerability concentrates in electrolytic tinplate substrate from cross-border rolling mills. Distribution runs through direct sales agreements between global brand owners and primary metal producers, displacing fragmented converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's Ministry of Natural Resources and Environment extended producer responsibility mandates function as a cost-of-compliance moat, elevating qualified suppliers above commodity competitors through eighteen-month alloy traceability documentation cycles.
For Market Incumbents: Deploy backward integration into aluminum rolling capacity to capture margin compression from London Metal Exchange volatility. Secure BIS-equivalent certification fast-track pathways for South Asian export expansion. Ball Corporation and Showa Aluminum Can Corporation face emerging pressure from craft beverage micro-breweries demanding shorter digital printing runs. For New Entrants and Emerging Players: Vietnam's Circular Economy Development Plan opens a window for reverse logistics partnerships with municipal waste operators ahead of deposit-return scheme implementation. Target underpenetrated Central Highlands provinces around Da Lat for bottled water and energy drink distribution. Pursue digital printing convergence capabilities to serve SKU proliferation without die-change penalties. For Investors and Strategic Acquirers: The window for entry favors integrated steel can producers with sulfur-resistant coating chemistry for Japanese and South Korean seafood export channels. Long-term viability hinges on regulatory compliance infrastructure rather than pure volume scale. Watch for Ministry of Natural Resources and Environment finalization of alloy sourcing documentation rules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captures margin from LME volatility for Ho Chi Minh City bottler supply. |
| BIS-Equivalent Certification Investment | Unlocks processed food export pathways to South Asian markets under aligned standards. |
| Digital Printing Capability Acquisition | Enables craft beverage micro-brewery SKU proliferation without tooling change costs. |
| Reverse Logistics Partnership Formation | Positions operators for Ministry deposit-return scheme infrastructure requirements. |
| Sulfur-Resistant Coating R&D Expansion | Secures Japanese and South Korean seafood processor contract renewals. |
Research Methodology
Multi-period observation of aluminum ingot price spreads, can line installation rates, and circular economy regulatory filings anchored the trend analysis, supplemented by interviews with beverage procurement directors, seafood processor supply chain managers, aluminum rolling mill technical leads, and Ministry of Natural Resources and Environment policy officers. Secondary validation drew from General Department of Vietnam Customs trade statistics, Ministry circular economy implementation guidelines, BIS food-contact metal standards documentation, and London Metal Exchange price archives. Bottom-up converter capacity estimates triangulated against top-down beverage bottler procurement disclosures.
Input-output matrices modeled aluminum and steel can volume flows across product type, end user, size format, and distribution channel dimensions over the projection horizon. CAGRs derived from segmented growth rate reconciliation against macroeconomic consumption indicators and regulatory implementation timelines. Forecast inputs incorporated wall-ironing die adoption curves for ultralight specifications and extended producer responsibility compliance cost trajectories.
Caveats apply where Ministry of Natural Resources and Environment deposit-return scheme finalization or regional trade protocol shifts on tinplate imports could materially shift the outlook. Forecasts reflect documented assumptions on alloy price stabilization and certification timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Cans Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
United Kingdom Metal Packaging Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Food Tins and Drink Cans Market
Metal Packaging
Global Laminated Steel for Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Food and Beverages Metal Can Market
Metal Packaging
Novelty Tins Market
Metal Packaging
India Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Metal Drums Market