
 Acne Drugs Market | 2026-2036
Acne Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Drugs Market Intelligence
Fragmentation across dermatology clinics, telehealth platforms, and direct-to-consumer channels is restructuring how acne therapies reach patients. Galderma dominates prescription topical innovation through its R&D intensity in retinoid combinations. Johnson & Johnson Services, Inc. anchors over-the-counter benzoyl peroxide distribution through mass retail channel control. Sun Pharmaceutical Industries Ltd. competes on generic oral antibiotic pricing, sustaining volume across price-sensitive markets.
Acne drugs comprise pharmaceutical formulations designed to reduce sebum production, inhibit Cutibacterium acnes colonization, or modulate keratinocyte turnover, with topical retinoids typically formulated at concentrations between 0.025% and 0.1% for inflammatory lesion management. These agents serve primarily to prevent scarring and improve psychosocial outcomes in persistent acne vulgaris. Topical treatments occupy the largest revenue pool due to first-line prescribing patterns, while combination therapies capture expanding margin pools as clinicians seek to reduce antibiotic resistance. E-commerce distribution channels represent the fastest-growing segment, displacing traditional pharmacy foot traffic among adult home users seeking discretion.
The FDA oversees prescription acne drug approval through dermatology division reviews, while the EPA regulates benzoyl peroxide manufacturing emissions under clean air statutes. These frameworks elevate compliance costs for domestic manufacturers but create barriers against unapproved imports. Stakeholders must monitor how evolving antibiotic stewardship guidelines reshape reimbursement for oral acne therapies.
Market Dynamics
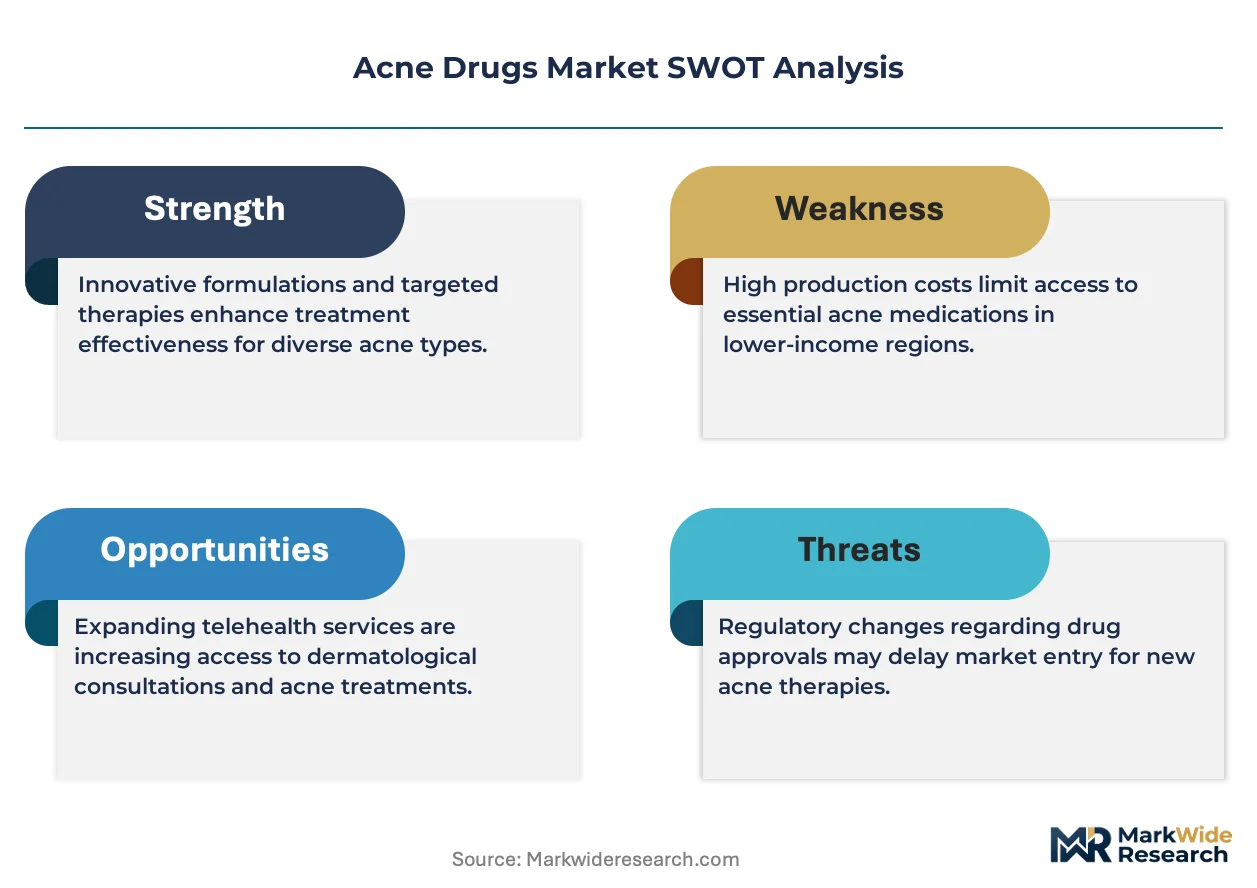
Biologic acne therapies are restructuring competitive positioning as dermatology clinics expand formulary adoption beyond traditional retinoid-antibiotic combinations, forcing incumbents to defend margin pools through combination therapy innovation.
Growth Catalysts
- FDA Labeling Tightening:The FDA's strengthened safety requirements for topical retinoids are accelerating R&D investment in next-generation formulations with improved tolerability profiles.
- Telehealth Platform Expansion:Virtual dermatology consultations are channeling prescription volume toward direct-to-patient delivery models, bypassing traditional pharmacy intermediaries.
- Biologics Pipeline Maturation:Monoclonal antibody development targeting interleukin pathways is opening new therapeutic categories for severe nodular acne resistant to conventional therapy.
Market Restraints
- Isotretinoin REMS Burden:The FDA's Risk Evaluation and Mitigation Strategy imposes costly compliance infrastructure on generic manufacturers, compressing margins for oral retinoid suppliers.
- Benzoyl Peroxide Feedstock Concentration:EPA-regulated manufacturing emissions controls have concentrated domestic production among three specialized chemical processors, creating supply vulnerability.
- Antibiotic Stewardship Guidelines:CDC and WHO recommendations limiting oral antibiotic duration are reducing refill rates for doxycycline and minocycline prescriptions.
Strategic Opportunities
- India Generic Export Expansion:CDSCO-approved manufacturers are capturing volume in price-sensitive Southeast Asian markets through cost-advantaged oral antibiotic production.
- Microbiome-Targeted Topicals:Phage therapy and live biotherapeutic products targeting Cutibacterium acnes strains represent unoccupied therapeutic territory.
- E-Commerce Discretion Channel:Adult acne patients in Japan and South Korea are migrating to subscription-based direct delivery, displacing brick-and-mortar pharmacy visits.
Industry Challenges
- Formulation Stability Expertise:Retinoid oxidation control and combination product shelf-life extension require specialized analytical chemistry capabilities in short supply.
- Clinical Trial Endpoint Standardization:Harmonizing lesion count methodologies across FDA, EMA, and PMDA submissions extends development timelines and inflates study costs.
- Legacy Distribution Integration:Wholesale pharmacy networks resist onboarding temperature-sensitive biologic shipments, forcing manufacturers to build parallel cold-chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Drugs Market |
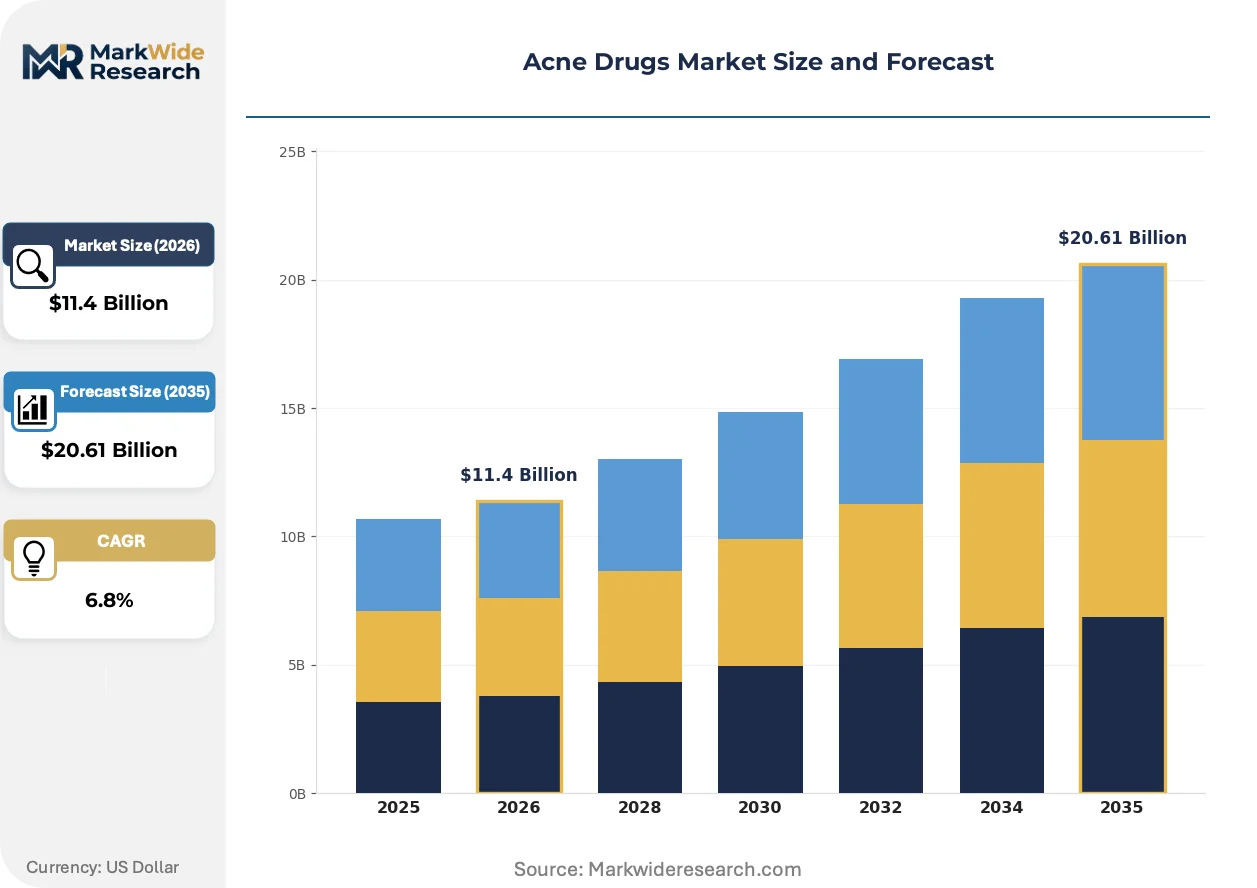
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Oral Medications, Combination Therapies, Light Therapy Devices Active Ingredient: Benzoyl Peroxide, Salicylic Acid, Retinoids, Antibiotics Distribution Channel: Retail Pharmacies, E-commerce, Hospital Pharmacies, Specialty Stores End User: Teenagers, Adults, Dermatology Clinics, Home Users |
| Companies Covered | Galderma, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, AbbVie Inc., Bausch Health Companies Inc., Sun Pharmaceutical Industries Ltd., Pfizer Inc., Bayer AG, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Drugs Market Strategic Shifts & Innovations
Prescription acne therapy development is bifurcating between high-efficacy biologic injections for severe disease and precision-formulated topical combinations for maintenance, with digital channels capturing patient acquisition and adherence monitoring.
Fixed-dose combination gels pairing retinoids with benzoyl peroxide or clascoterone are decentralizing treatment initiation from specialist offices to primary care and telehealth platforms. Nurse practitioners and physician assistants in the United States are prescribing these agents at accelerating rates. This shift is compressing dermatologist visit dependency and reallocating revenue toward pharmacy benefit managers.
EMA's Medical Device Regulation reclassification of certain light-based acne therapy devices is forcing manufacturers to submit clinical efficacy data previously exempt under cosmetic directives. German and French notified bodies are processing backlog applications for blue-light and photodynamic therapy systems. Device companies are responding by acquiring dermatology pharmaceutical firms to access established regulatory pathways and reimbursement codes.
Subscription-based replenishment models are capturing adult acne patients seeking discretion and regimen continuity, particularly among women aged 25-40 managing hormonal flares. Telehealth platforms in California, Texas, and New York are bundling virtual consultations with automated 90-day supply shipments. This pattern is most visible in coastal metropolitan areas where pharmacy deserts and work-hour constraints limit traditional access.
Acne Drugs Market Segmentation
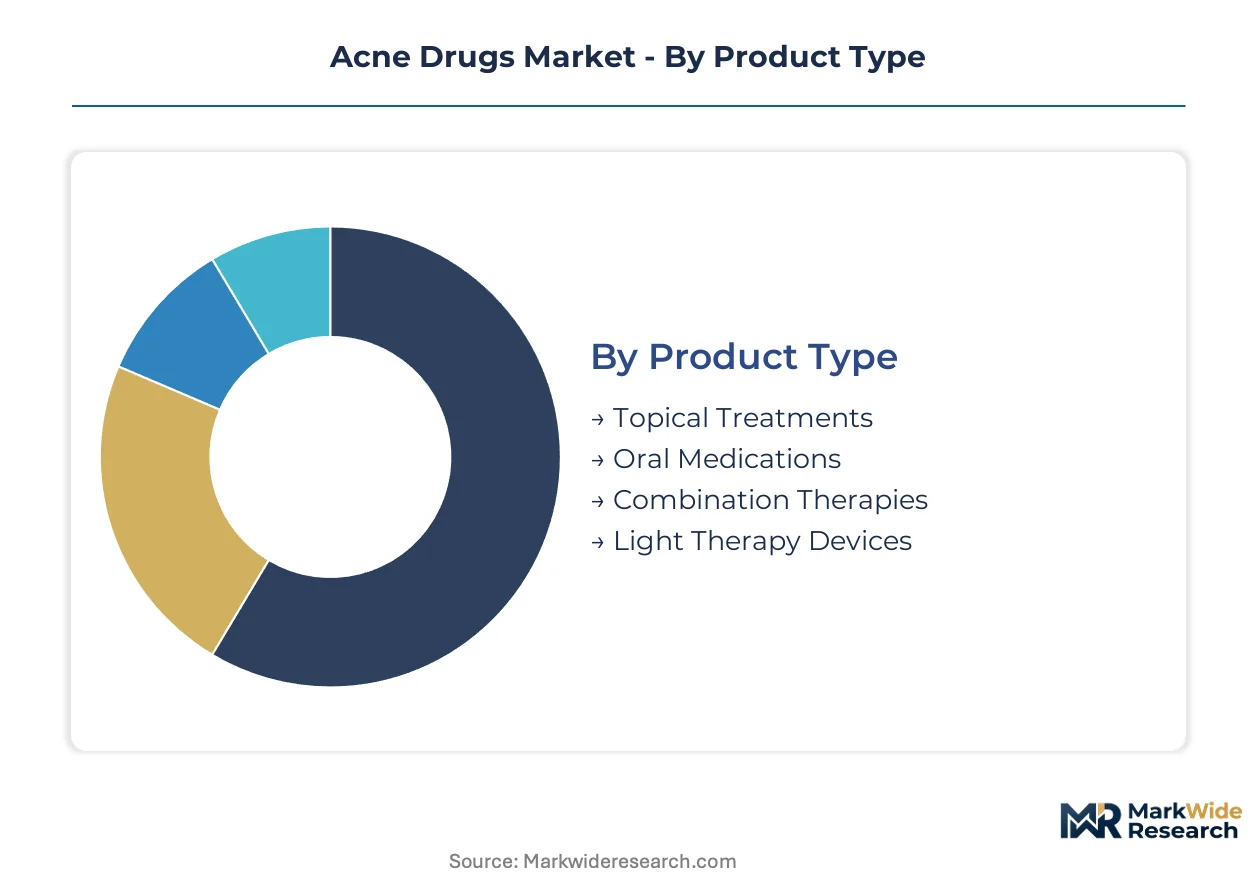
Acne drug purchasing decisions hinge on severity grading, access constraints, and discretion preferences. Each segmentation dimension reveals distinct margin structures and channel control points that manufacturers must navigate.
Product Type:
Clinicians prioritize efficacy-to-irritation ratios when selecting initial therapy, driving divergent R&D investment across formulation categories.
- Topical Treatments:Formulations include gels, creams, and lotions applied directly to affected skin, with retinoid and benzoyl peroxide concentrations calibrated for lesion severity. Demand concentrates in United States dermatology clinics where first-line prescribing protocols favor localized action with minimal systemic exposure. The FDA's tolerability labeling requirements are pushing manufacturers toward microencapsulated delivery systems.
- Oral Medications:Systemic therapies encompass isotretinoin, oral antibiotics, and hormonal agents for moderate-to-severe or treatment-resistant cases. Prescription volume clusters in price-sensitive Indian and Southeast Asian markets where generic doxycycline and minocycline production achieves cost advantages. The REMS infrastructure burden compresses margins for domestic isotretinoin suppliers.
- Combination Therapies:Fixed-dose formulations pair complementary mechanisms to reduce resistance development and simplify adherence.
- Light Therapy Devices:Blue-light and photodynamic systems target Cutibacterium acnes through bacterial porphyrin activation without pharmaceutical exposure.
Topical treatments lead on scale; combination therapies lead on momentum.
Active Ingredient:
Ingredient selection traces directly to resistance patterns, pregnancy safety profiles, and insurance reimbursement tiers.
- Benzoyl Peroxide:An oxidizing agent that reduces C. acnes colonization through oxygen radical generation, available in concentrations from 2.5% to 10%. Johnson & Johnson Services, Inc. controls mass retail distribution through shelf-space agreements with United States pharmacy chains. EPA manufacturing emission regulations have concentrated domestic production among three specialized chemical processors.
- Retinoids:Vitamin A derivatives including tretinoin, adapalene, and tazarotene that normalize keratinocyte turnover and prevent microcomedone formation. Galderma's R&D intensity in retinoid combinations sustains prescription premium positioning in European dermatology clinics. EMA stability requirements for oxidation-prone formulations elevate analytical chemistry costs.
- Salicylic Acid:A beta-hydroxy acid with keratolytic and mild anti-inflammatory properties common in over-the-counter cleansers and spot treatments.
- Antibiotics:Topical and oral formulations including clindamycin, erythromycin, and tetracyclines targeting bacterial protein synthesis.
Retinoids command premium pricing; benzoyl peroxide anchors volume throughput.
Distribution Channel:
Channel selection reflects patient age, severity perception, and desire for professional guidance versus transactional convenience.
- E-commerce:Direct-to-patient platforms capture adult users seeking discretion, particularly women aged 25-40 managing hormonal flares through subscription replenishment. Telehealth bundling in California, Texas, and New York accelerates migration from brick-and-mortar pharmacy visits.
- Retail Pharmacies:United States mass-market chains and independent dispensaries remain the default access point for teenage patients and acute breakout purchases.
- Hospital Pharmacies:Institutional procurement channels serve inpatient dermatology consultations and severe nodular acne requiring specialist oversight.
- Specialty Stores:Beauty retailers and dermatologist-affiliated dispensaries curate premium and professional-grade formulations.
E-commerce gains share fastest; retail pharmacies retain absolute volume leadership.
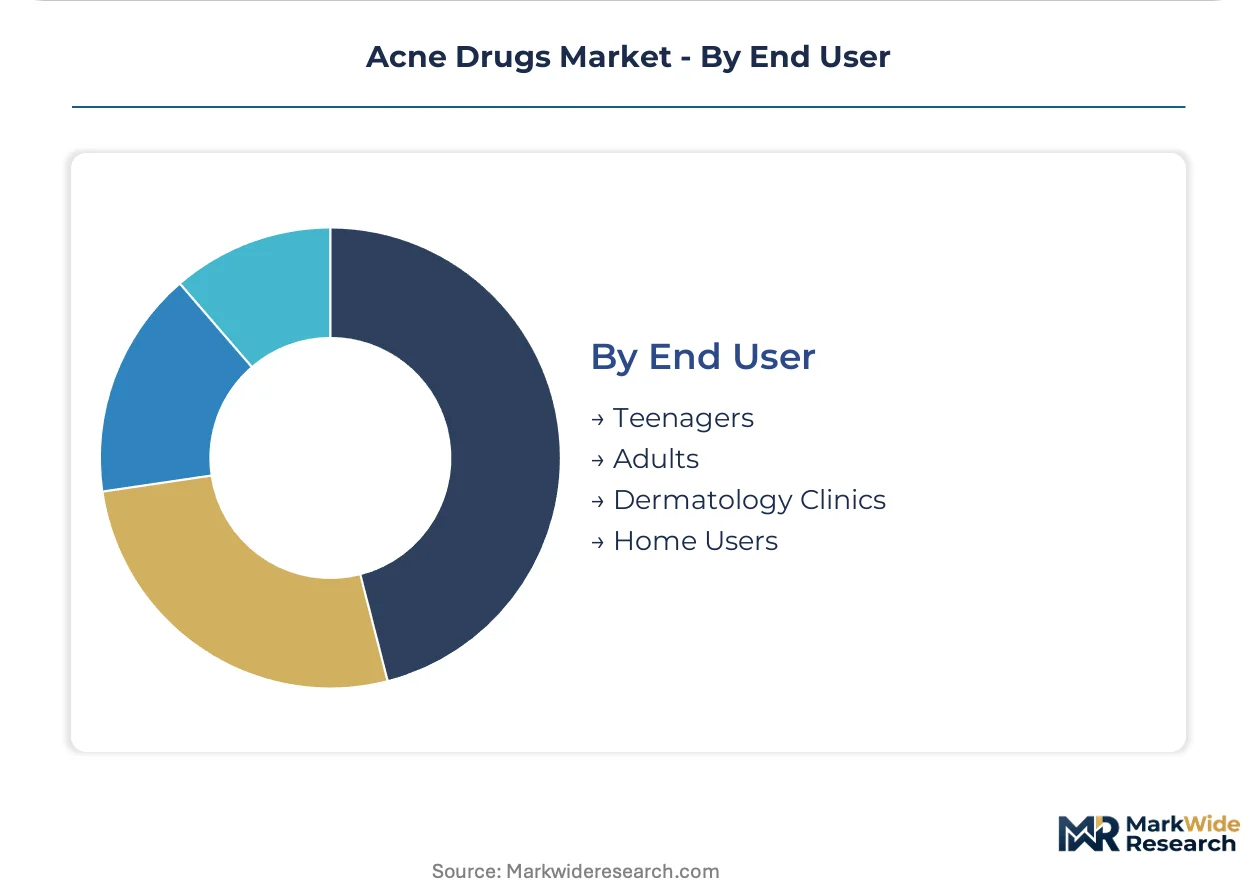
End User:
User demographics determine messaging strategy, formulation preference, and price elasticity across the acne therapy portfolio.
- Adults:Patients aged 25 and above, predominantly female, managing persistent or late-onset acne with greater concern for anti-aging compatibility and discretion. Japanese and South Korean subscription services target this cohort with regimen continuity and privacy. Workplace constraints and pharmacy deserts in coastal United States metropolitan areas accelerate telehealth adoption.
- Teenagers:Adolescent patients with higher lesion counts and greater family-mediated healthcare access, typically initiating therapy through pediatrician or primary care referral.
- Dermatology Clinics:Specialist practices with formulary control over biologic therapies and combination prescriptions for severe or refractory cases.
- Home Users:Self-directed consumers purchasing over-the-counter maintenance products without professional consultation.
Adults drive margin expansion; teenagers sustain foundational volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates premium therapy uptake through specialist channel access, while India dominates generic oral antibiotic production for price-sensitive export markets.
United States
Dermatology clinics in California, Texas, and New York drive biologic therapy adoption through formulary expansion and telehealth bundling. The FDA's tightened labeling requirements for topical retinoids are accelerating R&D investment in microencapsulated delivery systems. Boston and San Francisco host clusters of dermatology-focused biotech development targeting interleukin pathway modulation.
India
CDSCO-approved manufacturers supply cost-advantaged doxycycline and minocycline to Southeast Asian and African markets. The country's national pharmaceutical regulator maintains streamlined export certification for generic oral antibiotics. Maharashtra and Gujarat house concentrated production facilities serving contract manufacturing demand from European and North American marketers.
Germany
EMA stability requirements for oxidation-prone retinoid formulations elevate analytical chemistry costs for domestic manufacturers. The Medical Device Regulation reclassification of light-based therapy devices is forcing clinical efficacy submissions previously exempt under cosmetic directives. Berlin and Munich clusters process backlog applications for blue-light and photodynamic systems.
Japan
Adult acne patients aged 25-40 in Tokyo and Osaka are migrating to subscription-based direct delivery services, displacing traditional pharmacy visits. The PMDA maintains stringent lesion count methodology standards that extend development timelines for combination therapy submissions. Kanto region telehealth platforms bundle virtual consultations with automated 90-day supply shipments.
South Korea
Beauty retailers in Seoul curate premium professional-grade formulations targeting hormonal flare management in working women. The MFDS regulates fixed-dose combination gels through accelerated pathways for primary care and nurse practitioner prescribing. Gyeonggi Province hosts manufacturing facilities supplying the domestic e-commerce discretion channel.
Acne Drugs Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across prescription, over-the-counter, and device segments. The market structure tilts toward consolidation in biologics and fragmentation in generics. Three archetypes dominate: dermatology-focused innovators, mass-market consumer health divisions, and cost-driven generic exporters. Portfolio diversification and geographic expansion represent the primary competitive moves as incumbents defend margin pools.
Within the dermatology pure-play tier, Galderma exemplifies R&D intensity in retinoid combinations, while Sun Pharmaceutical Industries Ltd. anchors the generic oral antibiotic export position. Johnson & Johnson Services, Inc. occupies the mass-market consumer health vector through retail channel control. These three entities represent distinct strategic postures: innovation-driven premium positioning, cost-advantaged volume scaling, and distribution-intensive brand leverage.
| Leading Market Players |
|---|
| Galderma |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
EPA manufacturing emission controls for benzoyl peroxide production gate qualified supply access and premium-tier pricing power, concentrating domestic chemical processing among three specialized handlers while elevating compliance costs that filter through to formulation pricing. Buyers seeking retinoid stability assurance pay premiums for microencapsulated delivery systems that meet FDA tolerability labeling requirements.
Pricing Analysis
Capacity additions in India are reshaping price floors for generic oral antibiotics, compressing margins for domestic isotretinoin suppliers burdened by REMS infrastructure costs. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and regulatory certification tier. Cost compression in the oral antibiotic segment is intensifying because CDSCO-approved manufacturers achieve production economics that undercut Western generics. Teenage patients and family-mediated purchasers show highest price sensitivity, while adult women aged 25-40 demonstrate lowest sensitivity when hormonal compatibility and discretion are assured.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Gujarat anchor hub-and-spoke patterns serving Southeast Asian and African export markets for generic oral antibiotics. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with benzoyl peroxide feedstock sourcing from EPA-regulated domestic chemical processors. Raw material dependencies include retinoid precursors, specialized oxidation-control excipients, and cold-chain biologic carriers. Single-source vulnerability permeates the benzoyl peroxide intermediate layer where three processors control domestic supply. Distribution runs through wholesale pharmacy networks resisting temperature-sensitive biologic onboarding, forcing manufacturers toward parallel cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acne therapeutics rests on microbiome-targeted topical development commanding premium positioning and telehealth subscription models capturing recurring revenue from adult patients.
For Market Incumbents: Hedge against biologic therapy displacement by accelerating fixed-dose combination gel development for primary care and nurse practitioner prescribing channels. Deepen backward integration into retinoid oxidation-control capabilities to defend formulation stability premiums. Counter generic oral antibiotic price erosion through exclusive distribution agreements with telehealth platforms bundling virtual consultations. For New Entrants and Emerging Players: Launch via subscription-based direct delivery targeting adult women aged 25-40 in Japanese and South Korean metropolitan markets where pharmacy deserts and workplace constraints limit traditional access. Penetrate the microbiome-targeted topical white space through phage therapy development for Cutibacterium acnes strain specificity. Exploit underpenetrated Southeast Asian markets through cost-advantaged oral antibiotic production partnerships with CDSCO-certified manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for dermatology-focused biotech specialists because biologics pipeline maturation and EMA device reclassification create fragmented assets seeking regulatory expertise and reimbursement code access. Platform consolidation around interleukin pathway modulation capabilities offers five-to-ten year viability as severe nodular acne therapy shifts from conventional retinoid-antibiotic combinations. Monitor FDA formulary guidance evolution as the inflection signal for biologic adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Targeted Topical Development | Phage therapy and live biotherapeutic products open unoccupied therapeutic territory beyond conventional antibiotics. |
| Telehealth Platform Partnership | Virtual dermatology consultations channel prescription volume toward direct-to-patient delivery models bypassing pharmacy intermediaries. |
| Cold-Chain Infrastructure Buildout | Parallel distribution networks address wholesale pharmacy resistance to temperature-sensitive biologic shipments. |
| Retinoid Formulation Innovation | Microencapsulated delivery systems satisfy FDA tolerability labeling requirements while sustaining premium positioning. |
| Generic Export Certification | CDSCO streamlined export pathways enable cost-advantaged oral antibiotic penetration of price-sensitive Southeast Asian markets. |
Research Approach
Direct dialogue with dermatology formulary directors, drug development executives, regulatory affairs leads, and hospital procurement managers grounded the qualitative foundation, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary validation incorporated SEC 10-K disclosures, customs trade data, and hospital procurement contract repositories. Bottom-up patient population modeling and top-down pharmaceutical market sizing underwent iterative reconciliation.
Segmentation outputs across treatment line, dosage form, patient population, and regional regulatory cluster fed into the analytical framework over the projection horizon. CAGRs derived from historical prescription volume trajectories, pricing elasticity coefficients, and therapy substitution patterns. Forecast inputs incorporated telehealth adoption curves, antibiotic stewardship guideline implementation timelines, and biologics pipeline advancement milestones.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA labeling requirement shifts or benzoyl peroxide supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Cervical Cancer Vaccine Market