
 Europe Pharmaceutical Contract Manufacturing Market | 2026-2036
Europe Pharmaceutical Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Contract Manufacturing Market Foresight
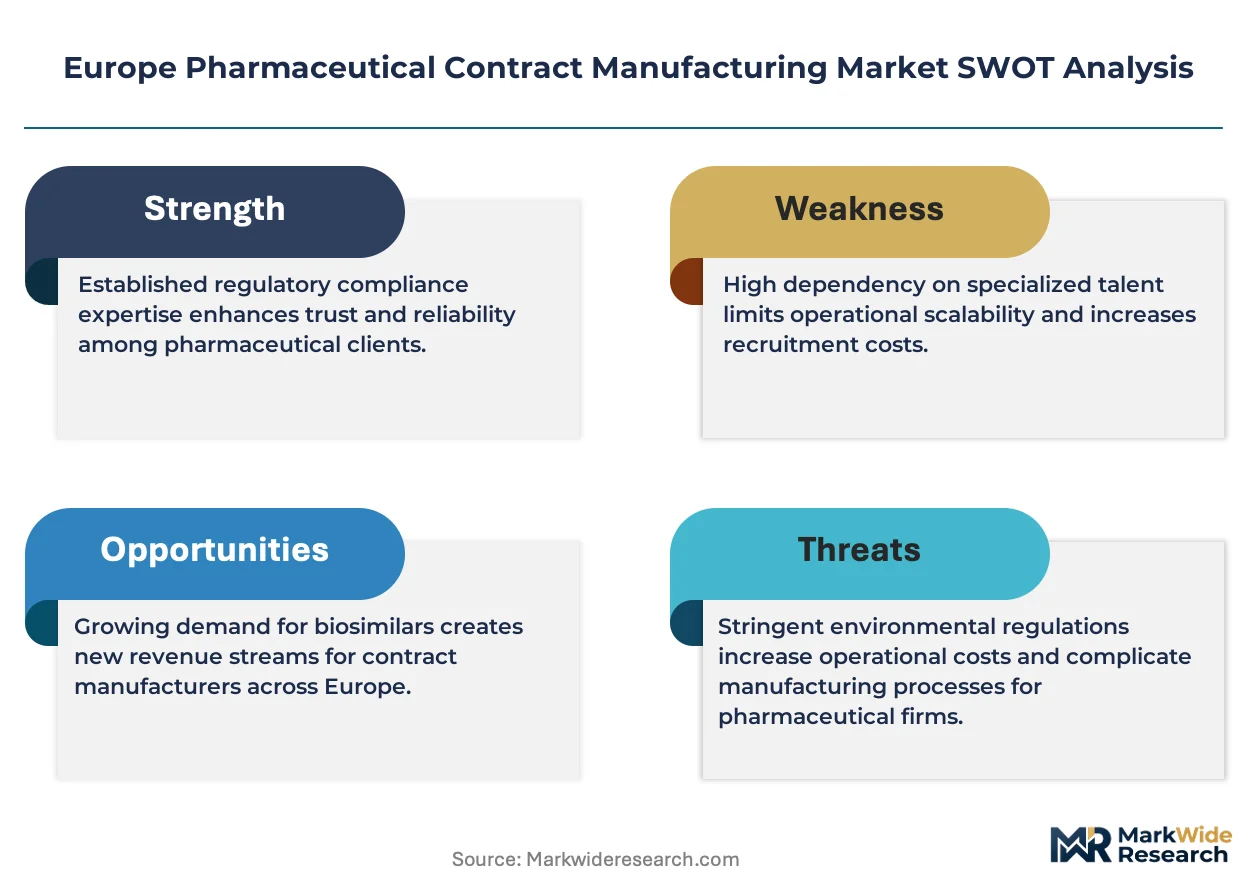
CGMP-grade sterile manufacturing is unwinding older capacity configurations across European contract manufacturing networks. Lonza Group AG leverages its Basel-based biologics infrastructure to anchor high-complexity mammalian cell culture services for global biopharma clients. Patheon Pharmaceuticals competes through integrated drug substance-to-drug product platforms that span multiple European regulatory jurisdictions. Delpharm sustains formulation leadership through specialized oral solid dose capabilities serving mid-tier pharmaceutical sponsors.
Pharmaceutical contract manufacturing encompasses the outsourced production of active pharmaceutical ingredients, finished dosage forms, and associated packaging under client-specified quality and regulatory parameters. European operations must validate processes against EudraLex Volume 4 Annex 1 standards for sterile manufacture, with particular emphasis on isolator technology and closed-system processing. Injectable products command premium capacity allocation due to aseptic processing complexity and limited qualified European sites. Biologics represents the fastest-expanding product category, driven by monoclonal antibody and cell therapy pipeline growth. API production retains mature margin structures while formulation development captures higher value-add per project.
EMA oversight, supplemented by national competent authorities such as Germany's BfArM and France's ANSM, enforces batch-release standards that determine market access for contract-manufactured therapies. REACH and EU GMP frameworks constrain raw material sourcing and facility qualification, elevating compliance costs for smaller manufacturing sites. The EU AI Act introduces emerging requirements for automated process control systems in pharmaceutical manufacturing. Stakeholders must monitor how Annex 1 enforcement timelines and digital validation mandates reshape capacity investment decisions across the European manufacturing footprint.
Market Dynamics
EMA's Annex 1 revisions are forcing wholesale reconfiguration of sterile manufacturing infrastructure across European contract manufacturing networks, compressing timelines for isolator technology deployment and elevating compliance costs for legacy facilities.
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and cell therapy developers in Germany and Switzerland are expanding outsourcing partnerships, concentrating demand in the Rhine-Ruhr and Basel-Lörrach clusters.
- REACH framework enforcement:Stricter raw material traceability requirements under ECHA oversight are disqualifying smaller European manufacturing sites, consolidating volume toward qualified contract manufacturers with validated supply chains.
- Closed-system processing adoption:Isolator technology and restricted access barrier systems are becoming mandatory for aseptic operations, creating premium capacity tiers that command higher project values.
Market Restraints
- Specialized input concentration:Single-use bioreactor bags and cell culture media rely on concentrated Asian suppliers, exposing European manufacturers to supply disruption risk and currency volatility.
- Facility qualification timelines:EMA batch-release validation and national competent authority inspections extend facility commissioning cycles, delaying revenue recognition for new capacity investments.
- Bioprocess technician scarcity:Mammalian cell culture and aseptic processing require specialized expertise that European labor markets supply inadequately, inflating wage costs and turnover rates.
Strategic Opportunities
- Central and Eastern European capacity:Poland, Czech Republic, and Hungary offer qualified workforce pools and lower operating costs for oral solid dose and packaging operations serving Western European sponsors.
- EU AI Act automation pathways:Automated process control systems for real-time release testing and predictive maintenance qualify for regulatory fast-track recognition, reducing compliance documentation burdens.
- Continuous manufacturing convergence:Integration of flow chemistry with downstream bioprocessing enables smaller-footprint facilities that reduce capital intensity and accelerate product changeovers.
Industry Challenges
- Annex 1 remediation execution:Legacy cleanroom facilities face complex retrofitting requirements for isolator integration and environmental monitoring system upgrades, disrupting active production schedules.
- Digital validation complexity:EMA's emerging requirements for automated process control documentation demand harmonization between legacy paper-based quality systems and new electronic batch records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Contract Manufacturing Market |
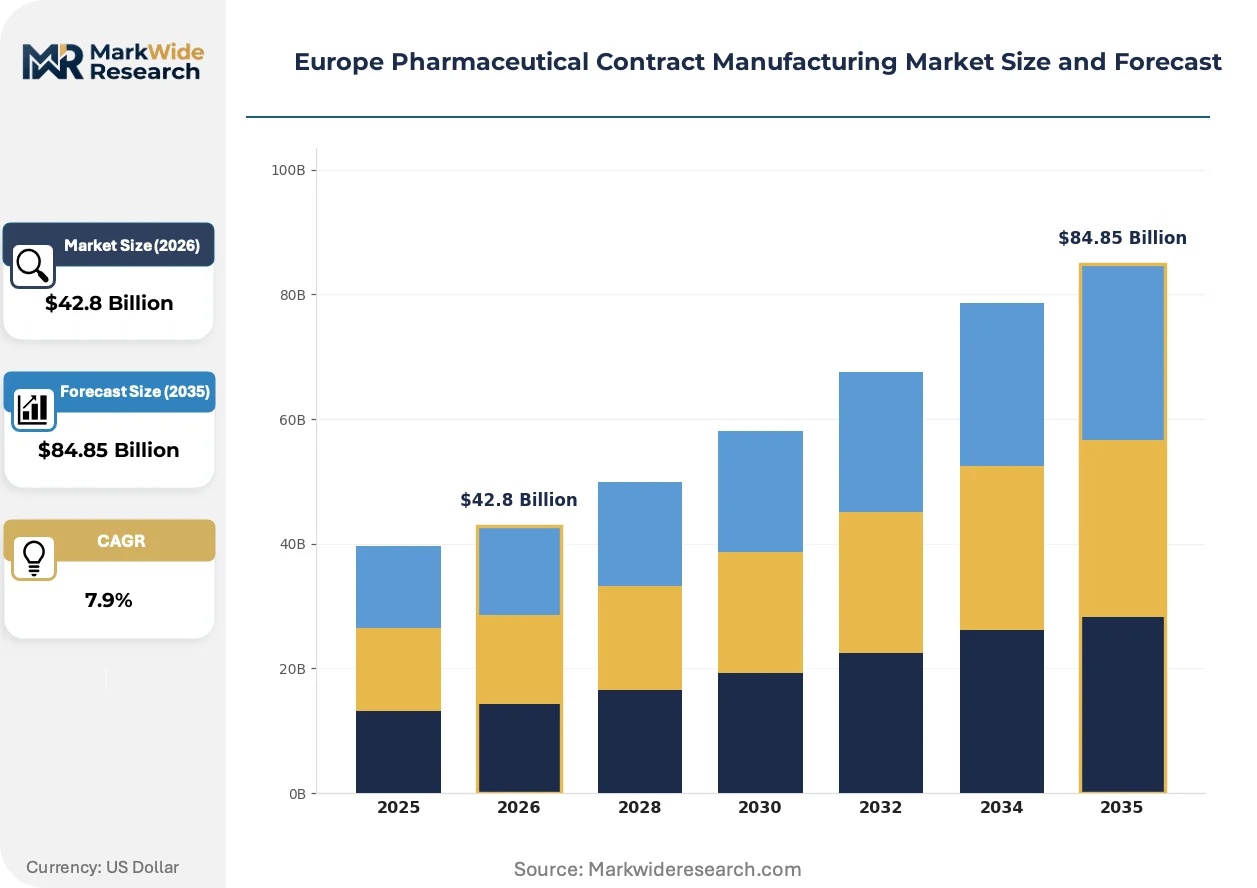
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $84.85 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Production, Formulation Development, Packaging Services, Quality Control Product Type: Oral Drugs, Injectable Products, Biologics, Nutraceuticals End User: Pharmaceutical Companies, Biotechnology Firms, Healthcare Organizations, Contract Research Organizations Deployment: On-demand Services, Batch Production, Continuous Manufacturing, Outsourced Services |
| Companies Covered | Patheon Pharmaceuticals, Recipharm AB, Boehringer Ingelheim BioXcellence, FUJIFILM Diosynth Biotechnologies, Delpharm, Lonza Group AG, Siegfried Holding AG, AGC Biologics, Catalent Pharma Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Contract Manufacturing Market Shifts & Advancements
European pharmaceutical contract manufacturing is experiencing fundamental restructuring as regulatory technology mandates intersect with biologics process intensification, compressing legacy operational models while opening new service tiers.
Single-use bioreactor systems is fragmenting conventional stainless-steel infrastructure economics across European biologics manufacturing. Mid-tier contract manufacturers in France and Italy are adopting modular single-use trains to reduce cleaning validation burdens and enable multi-product flexibility. This technology is fragmenting capital deployment patterns, allowing smaller facilities to compete for mammalian cell culture projects previously requiring hundred-million-euro stainless investments.
EU AI Act provisions for high-risk AI systems are imposing validation frameworks on manufacturing execution software and predictive maintenance algorithms. Automated process control vendors must now document algorithmic transparency and human oversight protocols to maintain GMP compliance. Biologics manufacturers with existing digital infrastructure are accelerating AI adoption for real-time release testing, while oral solid dose specialists lag in system integration.
Virtual pharmaceutical companies are consolidating sponsor relationships with integrated drug substance-to-drug product platforms rather than fragmenting projects across multiple contract manufacturers. This procurement consolidation compresses vendor lists and elevates technical service expectations, particularly for complex parenteral formulations. The shift is most visible in Germany and Switzerland, where biotech startups prefer single-accountability partnerships over multi-site manufacturing strategies.
Europe Pharmaceutical Contract Manufacturing Market Segmentation
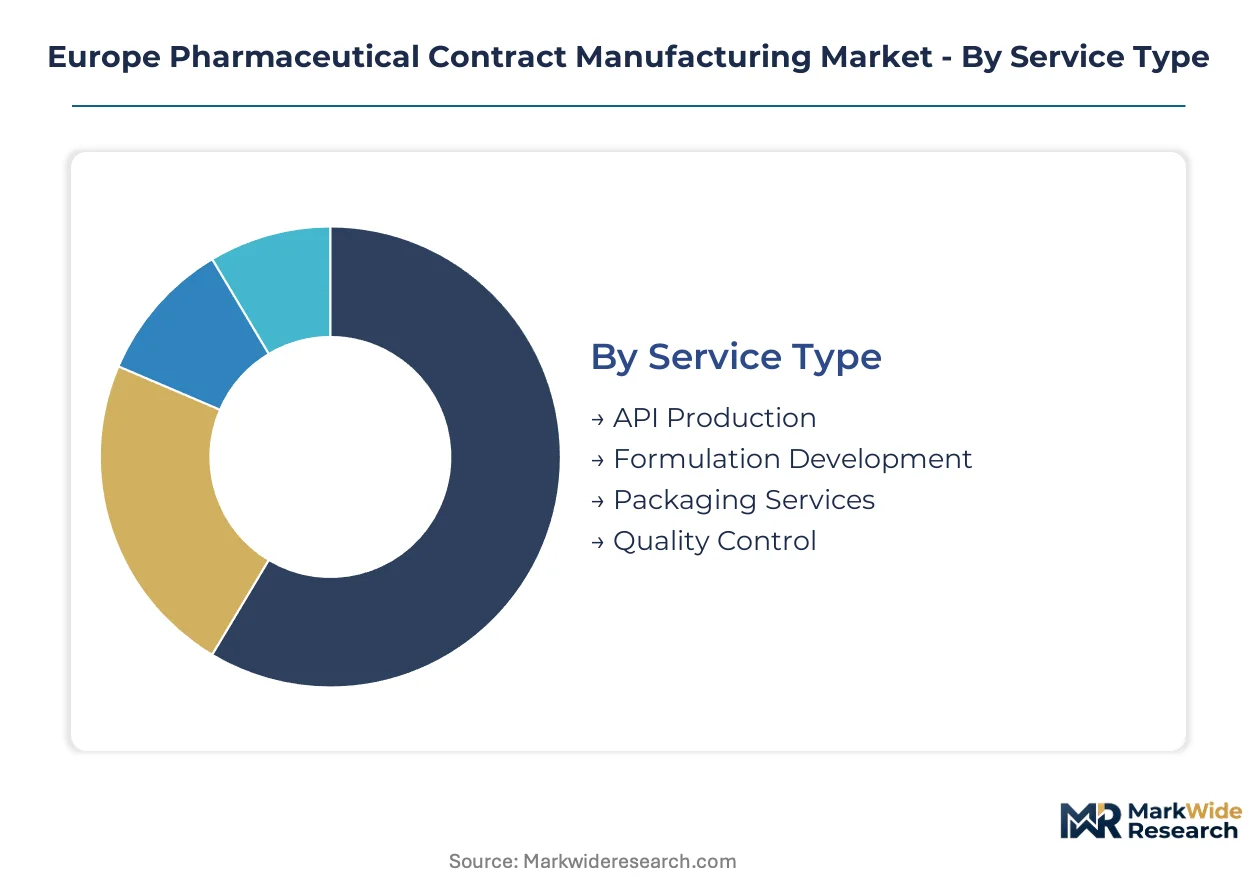
Contract manufacturing segmentation reveals how European sponsors fragment projects across capability tiers. Service complexity, regulatory burden, and batch scale determine vendor selection patterns across the Rhine-Ruhr and Basel-Lörrach clusters.
Service Type:
API production concentrates in domestic German and Swiss facilities serving regional sponsors, while formulation development attracts export-led demand from North American biotechs seeking EMA-aligned dossiers.
- API Production:Synthetic chemistry and biologic drug substance manufacturing require EMA-validated facilities with isolator infrastructure. German sites along the Rhine corridor dominate high-potency API output for oncology pipelines.
- Formulation Development:Complex parenteral and lyophilized dosage forms command premium fees. Swiss contract manufacturers capture disproportionate share of monoclonal antibody formulation work due to Basel's biologics ecosystem density.
- Packaging Services:Serialisation-compliant secondary packaging for EU markets.
- Quality Control:Batch release testing and stability studies under EMA frameworks.
API production holds the largest share; momentum sits with formulation development.
Product Type:
Margin structures diverge sharply across product categories, with biologics and injectables capturing value premiums that oral solid doses cannot match.
- Biologics:Mammalian cell culture and microbial fermentation for monoclonal antibodies, recombinant proteins, and cell therapies. Basel-Lörrach facilities lead mammalian platform capacity; demand from German biotechs is climbing the fastest.
- Injectable Products:Aseptic fill-finish and lyophilization for parenteral formulations. Isolator technology mandates under Annex 1 revisions constrain qualified European sites, tightening capacity allocation.
- Oral Drugs:Tablet and capsule manufacturing for mature pharmaceutical portfolios.
- Nutraceuticals:Dietary supplement and functional food ingredient contract production.
Injectable products anchor revenue stability; biologics is gaining share fastest.
End User:
Customer scale determines project fragmentation patterns, with large pharmas favoring integrated platforms and emerging biotechs accepting multi-vendor strategies.
- Pharmaceutical Companies:Mid-tier and large-cap sponsors outsourcing mature product lines and capacity overflow. French and Italian facilities capture significant oral solid dose volume from established European pharmas.
- Biotechnology Firms:Virtual and development-stage companies lacking internal manufacturing infrastructure. German biotech clusters in Munich and Heidelberg drive demand for flexible, small-batch biologics services.
- Healthcare Organizations:Hospital and institutional pharmacy compounding partnerships.
- Contract Research Organizations:Integrated CRO-CMO relationships for seamless clinical-to-commercial transitions.
Pharmaceutical companies provide volume foundation; biotechnology firms show steepest expansion trajectory.
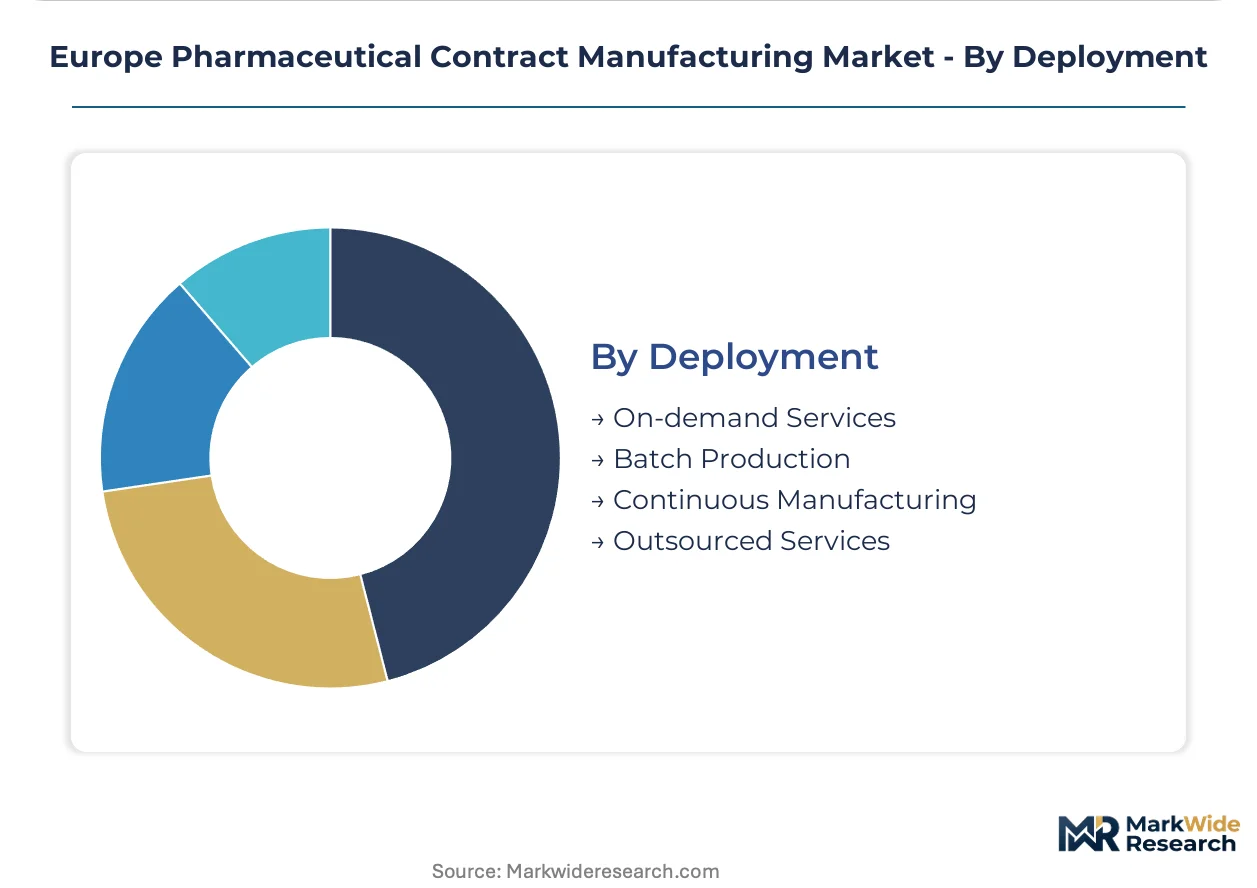
Deployment:
Production modality selection reflects capital intensity tolerance and regulatory risk appetite across sponsor organizations.
- Batch Production:Conventional stainless-steel and single-use bioreactor campaigns with defined scale-up protocols. Dominant model for validated commercial supply across EMA jurisdictions.
- Continuous Manufacturing:Flow chemistry and integrated downstream processing for small-molecule APIs. Adoption accelerates in oral solid dose facilities seeking footprint reduction.
- On-demand Services:Clinical-trial material and adaptive supply for pipeline assets.
- Outsourced Services:Full manufacturing responsibility transfer including quality and regulatory management.
Batch production retains dominant share; continuous manufacturing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European contract manufacturing exports exceed imports in high-complexity biologics, while oral solid dose capacity flows eastward toward lower-cost jurisdictions. Switzerland and Germany generate surplus value in sterile injectables, offsetting API import dependency from Asian suppliers.
Germany
Monoclonal antibody developers in Munich and Heidelberg are expanding outsourcing partnerships for mammalian cell culture campaigns. BfArM enforces EMA-aligned batch-release standards that extend facility qualification timelines. The Rhine-Ruhr corridor concentrates isolator-equipped sterile manufacturing sites serving oncology pipeline sponsors.
Switzerland
Basel-based biotechs are consolidating procurement with integrated drug substance-to-drug product platforms. Swissmedic maintains stringent oversight of biologics manufacturing that exceeds baseline EMA requirements. The Basel-Lörrach cluster anchors high-complexity mammalian cell culture capacity for global biopharma clients.
France
Mid-tier pharmaceutical sponsors are migrating oral solid dose production toward contract manufacturers with serialization-compliant packaging lines. ANSM inspects facilities against EudraLex Volume 4 Annex 1 standards with particular focus on environmental monitoring. The Paris-Saclay biotech cluster generates formulation development demand for complex parenteral projects.
Italy
Specialized injectable manufacturers are retrofitting legacy cleanrooms with restricted access barrier systems to meet Annex 1 compliance deadlines. AIFA coordinates with EMA on facility inspections that prioritize isolator technology validation. Northern Italian sites in Lombardy and Piedmont concentrate lyophilization capacity for European biotech sponsors.
Poland
Western European sponsors are qualifying Central European sites for oral solid dose and secondary packaging operations. The national pharmaceutical regulator enforces EU GMP standards that align with Western European batch-release requirements. Warsaw and Krakow industrial zones attract packaging investments from German and French contract manufacturers seeking cost arbitrage.
Europe Pharmaceutical Contract Manufacturing Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven platforms face agile mid-cap challengers. The market stratifies into three archetypes: integrated biologics platforms spanning drug substance through fill-finish, formulation specialists concentrating on complex parenterals, and regional oral solid dose operators serving mature portfolios. Consolidation pressure intensifies as virtual pharmaceutical companies demand single-accountability partnerships, compressing vendor lists and elevating technical service expectations. Capacity expansion and strategic partnerships dominate competitive moves, with isolator technology deployment and AI-enabled process control emerging as differentiation vectors.
Within the integrated biologics tier, Lonza Group AG and Boehringer Ingelheim BioXcellence exemplify scale-driven platforms with Basel and German infrastructure anchoring high-complexity mammalian services. Patheon Pharmaceuticals occupies a position spanning multiple European regulatory jurisdictions with drug substance-to-drug product capabilities. These entities represent how capital-intensive biologics manufacturing concentrates among entities with validated EMA facilities and closed-system processing expertise.
| Leading Market Players |
|---|
| Patheon Pharmaceuticals |
| Recipharm AB |
| Boehringer Ingelheim BioXcellence |
| FUJIFILM Diosynth Biotechnologies |
| Delpharm |
| Lonza Group AG |
| Siegfried Holding AG |
| AGC Biologics |
| Catalent Pharma Solutions |
| Others |
Supply & Pricing Matrix
Ninety-day isolator equipment lead times from specialized European vendors concentrate pricing power among qualified contract manufacturers with validated sterile infrastructure, while sponsors absorbing Annex 1 compliance costs face compressed project margins across the Rhine-Ruhr and Basel-Lörrach manufacturing clusters.
Pricing Analysis
Large pharmaceutical companies anchor project-based pricing structures that stratify across GMP certification tiers, isolator technology deployment, and batch scale commitments. Price differentiation stems from EMA validation status and closed-system processing capability, with premium tiers commanding substantial fees for monoclonal antibody fill-finish services. Cost compression in oral solid dose manufacturing intensifies as Central European sites compete on operating expense arbitrage. Emerging biotechnology firms exhibit highest price sensitivity, prioritizing flexible campaign structures over per-unit economies.
Supply Chain Analysis
Strategic stockpiling of single-use bioreactor bags and cell culture media is displacing just-in-time preferences as European manufacturers buffer against Asian supplier concentration. Raw material sourcing draws from Germany, Switzerland, and Ireland for high-purity excipients, while specialized films and filtration assemblies feed from concentrated East Asian producers. Single-source vulnerability in isolator technology components exposes commissioning timelines to disruption. Distribution runs through qualified logistics networks with temperature-validated cold chain custody for biologics shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent contract manufacturers face substitution pressure from integrated biologics platforms consolidating sponsor relationships, requiring defensive repositioning around isolator technology and AI-enabled process control capabilities.
For Market Incumbents: Compound isolator technology deployment across legacy cleanroom footprints to defend Annex 1-compliant capacity allocation against modular single-use challengers. Deepen backward integration into specialized cell culture media formulation to reduce Asian supplier dependency. Prioritize EMA batch-release validation maintenance as the primary competitive moat against emerging Central European entrants. For New Entrants and Emerging Players: EMA fast-track certification for isolator-equipped facilities in Poland and Czech Republic opens white-space penetration into oral solid dose and secondary packaging services for Western European sponsors. Target mid-tier pharmaceutical companies migrating mature product lines from higher-cost German and Swiss sites. Lead with serialization-compliant packaging capabilities and EU GMP-aligned quality systems as the primary go-to-market credential. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EMA validation timelines and facility qualification costs create durable barriers protecting incumbent cash flows. Acquisition targets should display existing isolator infrastructure and established relationships with German biotechnology clusters. Monitor EMA inspection backlog clearance rates as the signal indicating capacity constraint relief or intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | Annex 1 compliance mandates retrofitting legacy cleanrooms with restricted access barrier systems to maintain GMP certification. |
| Single-Use Bioreactor Adoption | Modular processing trains reduce cleaning validation burdens and enable multi-product flexibility for mammalian cell culture campaigns. |
| EMA Batch-Release Validation | National competent authority inspections determine market access timelines and revenue recognition for new capacity investments. |
| AI-Enabled Process Control | EU AI Act provisions create regulatory fast-track pathways for automated real-time release testing and predictive maintenance systems. |
| Central European Capacity Expansion | Polish and Czech sites capture oral solid dose migration from Western European sponsors seeking operating cost arbitrage. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, manufacturing site directors, and hospital procurement managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EMA submission databases, BfArM inspection records, ClinicalTrials.gov protocol filings, and EU GMP facility registries. Bottom-up project pipeline assessment and top-down capacity utilization modeling generated convergent demand estimates across the European manufacturing footprint.
Sensitivity analysis tested forecast robustness across alternative Annex 1 enforcement timelines and biologics pipeline progression scenarios over the projection horizon. Segmentation modeling incorporated service type complexity tiers, product category regulatory burden differentials, end-user scale archetypes, and deployment modality capital intensity. CAGRs derived from facility expansion announcements, sponsor outsourcing contract values, and qualified site capacity utilization trajectories. Input assumptions included EMA inspection throughput rates and single-use equipment lead time bands.
Decision-makers should treat outputs as directional under sustained EMA oversight stringency and stable biologics development funding; material deviation would warrant model refresh. Forecasts assume continued REACH framework enforcement and qualified workforce availability in German and Swiss manufacturing clusters. Revision becomes warranted when EMA inspection backlog clearance or single-use supply chain disruption crosses thresholds altering capacity commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Global Non-Alcoholic Fatty Liver Disease (NAFLD) Drug Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Second Generation Cephalosporins Market