
 Bendamustin Market | 2026-2036
Bendamustin Market Size, Share, and Industry Trends Forecast 2026-2036
Bendamustin Market Analysis
Modular vial-and-diluent bundling is restructuring procurement patterns for bendamustine hydrochloride across European and North American hospital networks. Teva Pharmaceutical Industries leverages its integrated sterile injectables footprint to sustain supply continuity for high-volume oncology centers. Eagle Pharmaceuticals differentiates through concentrated formulation technology that reduces infusion bag volumes and pharmacy preparation time.
Bendamustine is a bifunctional mechlorethamine derivative containing a benzimidazole ring and a nitrogen mustard group, formulated as hydrochloride salt for reconstitution in 0.9% sodium chloride or 5% dextrose solution prior to intravenous administration. The agent exerts its antineoplastic effect through DNA crosslinking and purine analogue-like metabolic disruption, primarily indicated for chronic lymphocytic leukemia and indolent B-cell non-Hodgkin lymphoma. The injection segment anchors current revenue due to its established reimbursement in hospital outpatient settings, while oral tablets represent the fastest-expanding configuration as homecare protocols gain acceptance in hematologic malignancies. Hematologic malignancies occupy the dominant therapy area position, though lymphoma applications are deepening as combination regimens with rituximab achieve broader protocol adoption.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for bendamustine injectables, while the EMA's updated good manufacturing practice Annex 1 standards for sterile products are elevating barrier-isolation expectations for European suppliers. Japan's PMDA imposes additional local stability testing that extends registration timelines for foreign manufacturers seeking market access. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs for bendamustine hydrochloride, as divergence in impurity thresholds could fragment batch-release protocols across major markets.
Market Dynamics
The FDA's updated bioequivalence guidelines for generic oncology injectables are forcing hospital procurement offices to requalify suppliers against stricter chemistry, manufacturing, and controls benchmarks, compressing vendor lists and elevating barrier-isolation investments across sterile manufacturing networks.
Growth Catalysts
- EMA Annex 1 GMP Standards:Elevated barrier-isolation requirements for sterile products are accelerating facility upgrades among European manufacturers, creating capacity constraints that favor qualified incumbents with validated isolator lines.
- Homecare Protocol Expansion:Oral bendamustine tablets are gaining protocol inclusion for chronic lymphocytic leukemia maintenance therapy, extending treatment duration beyond hospital infusion centers into ambulatory settings.
- Rituximab Combination Regimens:Protocol adoption of bendamustine plus rituximab in indolent B-cell non-Hodgkin lymphoma is deepening oncology clinic utilization across Germany and the United States.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for bendamustine hydrochloride concentrates among a limited base of specialized chemical synthesis houses, exposing formulations to single-source disruption risk.
- PMDA Stability Testing Burden:Japan's local stability testing requirements extend registration timelines for foreign manufacturers, delaying market access and fragmenting batch-release protocols across major pharmacopeias.
- Infusion Bag Volume Constraints:Large-volume diluent requirements for standard bendamustine formulations strain pharmacy compounding capacity and cold-chain logistics in high-throughput oncology centers.
Strategic Opportunities
- Concentrated Formulation Technology:Reduced infusion bag volumes are enabling pharmacy workflow compression and cold-chain efficiency gains in United States hospital outpatient settings.
- Pharmacopeial Harmonization Gaps:Divergence between USP, EP, and JP impurity thresholds creates batch-release arbitrage opportunities for manufacturers with multi-compendial testing capabilities.
- Modular Vial-and-Diluent Bundling:Unit-of-use packaging configurations are restructuring procurement patterns across European hospital networks, favoring integrated suppliers with sterile injectables footprints.
Industry Challenges
- Isolator Technology Talent Scarcity:Qualified aseptic processing engineers with barrier-isolation expertise command premium compensation, constraining facility expansion timelines for sterile oncology injectables.
- Multi-Compendial Release Complexity:Simultaneous compliance with divergent USP, EP, and JP monograph specifications requires redundant analytical method validation, extending quality control cycles.
- Legacy Lyophilization Capacity:Existing freeze-dryer footprints at contract manufacturing organizations were sized for earlier oncology portfolios, creating bottlenecks for high-potency cytotoxic batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bendamustin Market |
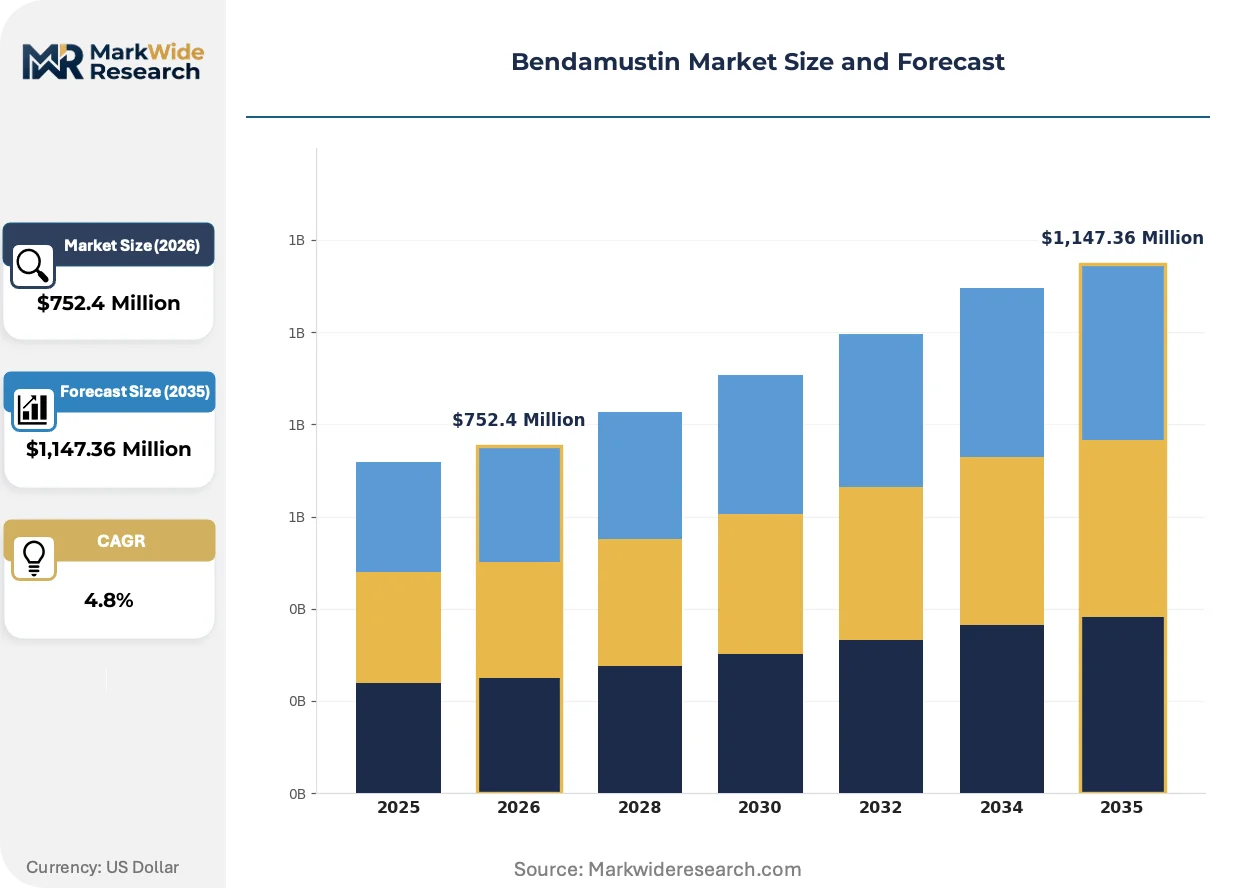
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $1,147.36 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Oral Tablets, Infusion, Solution Therapy Area: Hematologic Malignancies, Solid Tumors, Lymphoma, Leukemia End User: Hospitals, Clinics, Homecare, Research Institutions Delivery Mode: IV Administration, Oral Administration, Subcutaneous, Intramuscular |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Eagle Pharmaceuticals, Inc., Mundipharma International Limited, Eisai Co., Ltd., Sandoz International GmbH, Natco Pharma Limited, Dr. Reddy's Laboratories Ltd., Fresenius Kabi AG, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bendamustin Market Emerging Trajectories
Formulation technology, regulatory harmonization pressure, and site-of-care migration are converging to reshape how bendamustine reaches hematologic malignancy patients, with implications for manufacturing investment and distribution architecture.
Concentrated bendamustine formulations are electrifying pharmacy operations in high-volume oncology centers by reducing reconstitution volumes from 500 mL to 50 mL infusion bags. Hospital outpatient departments in the United States are adopting these configurations to compress preparation time and free compounding capacity for other agents. This technology is electrifying competitive positioning among suppliers capable of delivering stability-validated concentrated presentations.
REACH chemical registration requirements in Europe are tightening scrutiny on residual solvent profiles in bendamustine API manufacturing processes. EMA good manufacturing practice inspections now prioritize supplier qualification documentation for starting materials and intermediates. Contract manufacturers serving European hospital networks are responding by backward-integrating into captive API sourcing or securing exclusive supply agreements with qualified synthesis houses.
Homecare administration protocols for oral bendamustine tablets are displacing traditional infusion-centered revenue models in chronic lymphocytic leukemia maintenance settings. Hematology practices in Germany are restructuring pharmacy service contracts to accommodate take-home dispensing, with reimbursement pathways adapting to support ambulatory oral oncology. This behavioral shift is most visible in integrated cancer networks with established oral oncology pharmacy infrastructure.
Bendamustin Market Segmentation
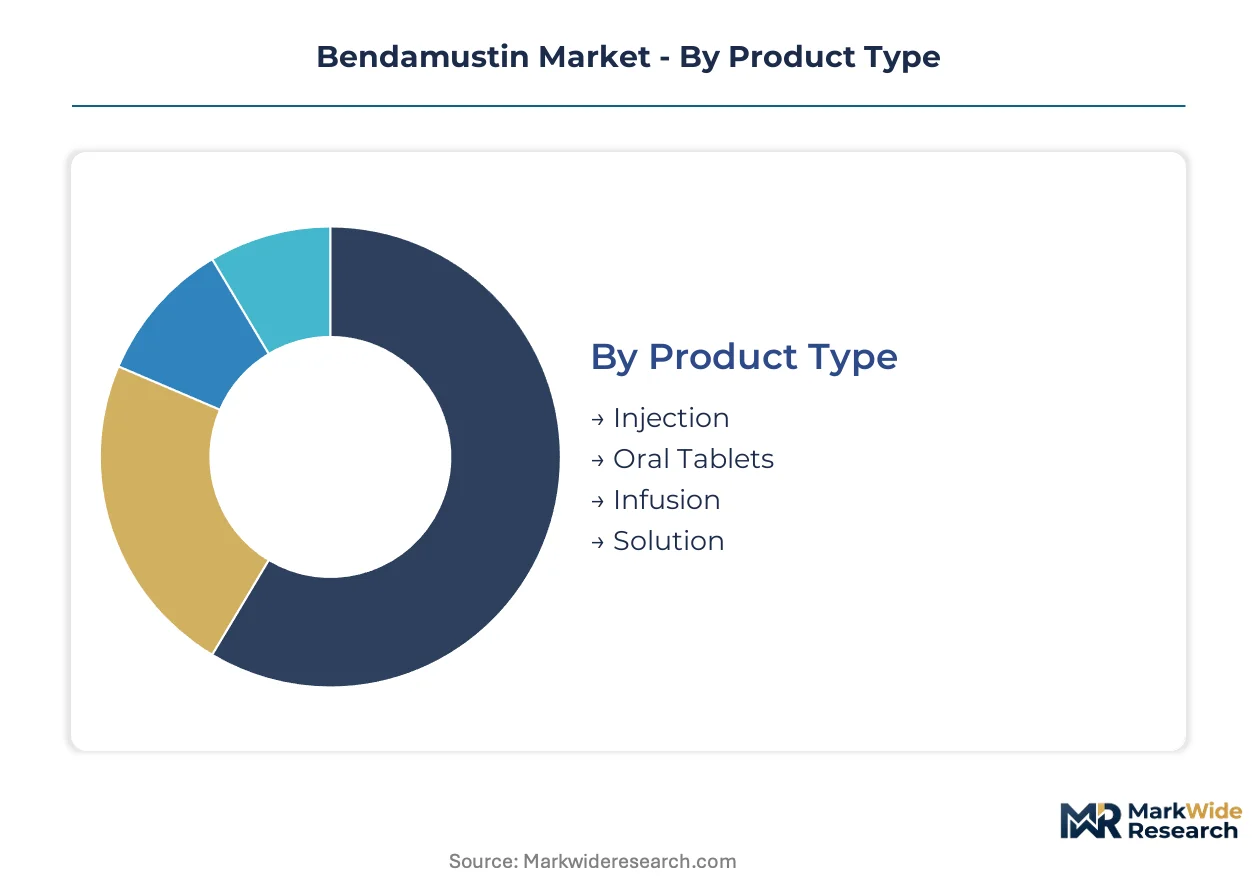
Bendamustine's market architecture reflects a tension between established hospital infusion protocols and emerging ambulatory care models. Product configuration and site-of-care decisions increasingly determine procurement patterns, reimbursement pathways, and manufacturing investment priorities across oncology supply chains.
Product Type:
Volume concentration sits with injection formats serving high-throughput hospital outpatient departments, while premium positioning attaches to configurations that reduce pharmacy preparation burden or enable home administration.
- Injection:Lyophilized powder for reconstitution in 0.9% sodium chloride or 5% dextrose, supplied in single-dose vials requiring aseptic compounding. Demand concentrates in United States hospital outpatient settings where established reimbursement codes and cold-chain infrastructure support high-volume rituximab combination protocols.
- Oral Tablets:Immediate-release formulations enabling chronic lymphocytic leukemia maintenance therapy outside infusion centers. Germany's integrated cancer networks are restructuring pharmacy service contracts to accommodate take-home dispensing, with reimbursement pathways adapting to support ambulatory oral oncology.
- Infusion:Pre-mixed presentations in ready-to-hang bags reduce pharmacy compounding steps for standard-dose regimens. Japanese hospital networks favor these configurations to minimize occupational exposure during cytotoxic preparation.
- Solution:Liquid presentations requiring fewer reconstitution steps than lyophilized counterparts. Research institutions in the United States utilize these for investigator-initiated trials requiring dose flexibility.
Mature deployment sits with Injection. Newer deployment is concentrated in Oral Tablets.
Therapy Area:
Application intensity varies sharply across malignancy types, with hematologic indications commanding manufacturing priority due to protocol penetration and reimbursement security.
- Hematologic Malignancies:Chronic lymphocytic leukemia and indolent B-cell non-Hodgkin lymphoma constitute the core commercial footprint. United States oncology clinics are expanding bendamustine use in front-line and salvage regimens, with EMA Annex 1 GMP standards elevating barrier-isolation requirements for sterile supply to European hematology centers.
- Lymphoma:Rituximab combination protocols are deepening utilization across Germany and the United States. FDA bioequivalence guidelines for generic oncology injectables are forcing hospital procurement offices to requalify suppliers against stricter chemistry, manufacturing, and controls benchmarks.
- Leukemia:Maintenance therapy applications are gaining protocol inclusion as oral formulations extend treatment duration. Homecare administration models are displacing traditional infusion-centered revenue structures in this segment.
- Solid Tumors:Investigational applications in selected carcinoma types remain confined to clinical trial settings. Research institutions represent the primary demand source pending regulatory pathway clarification.
Established revenue concentration sits with Hematologic Malignancies. Protocol expansion is accelerating fastest in Lymphoma combination regimens.
End User:
Customer type determines packaging configuration, distribution architecture, and service intensity requirements across the value chain.
- Hospitals:High-volume IV administration anchors current revenue, with modular vial-and-diluent bundling restructuring procurement patterns across European and North American networks. Concentrated formulation technology is electrifying competitive positioning among suppliers capable of delivering stability-validated presentations that reduce infusion bag volumes.
- Clinics:Community oncology practices in Germany and the United States are deepening bendamustine utilization as combination regimens achieve broader protocol adoption. Pharmacy workflow compression drives preference for reduced preparation time configurations.
- Homecare:Oral tablet dispensing for chronic lymphocytic leukemia maintenance is extending treatment duration beyond hospital infusion centers. Reimbursement pathways are adapting to support ambulatory oral oncology in integrated cancer networks.
- Research Institutions:Investigator-initiated trials and compassionate use programs generate demand for flexible-dose presentations. PMDA stability testing requirements extend registration timelines for foreign manufacturers supplying Japanese academic medical centers.
Procurement scale concentrates with Hospitals. Site-of-care migration is shifting volume fastest toward Homecare.
Delivery Mode:
Administration route selection reflects a trade-off between clinical efficacy, patient convenience, and healthcare system cost structure.
- IV Administration:Intravenous infusion in 0.9% sodium chloride or 5% dextrose over specified durations remains the standard for acute treatment phases. United States hospital outpatient departments maintain dominant utilization due to reimbursement coding and supervision requirements.
- Oral Administration:Tablet formulations enable chronic lymphocytic leukemia maintenance without infusion center dependency. Germany's hematology practices are restructuring service contracts to accommodate take-home dispensing.
- Subcutaneous:Limited investigational applications explore alternative delivery for selected patient populations. Research protocols in Japanese academic centers are evaluating pharmacokinetic equivalence.
- Intramuscular:No established clinical role in approved indications; confined to preclinical or early-phase investigation. Regulatory pathway uncertainty constrains development investment.
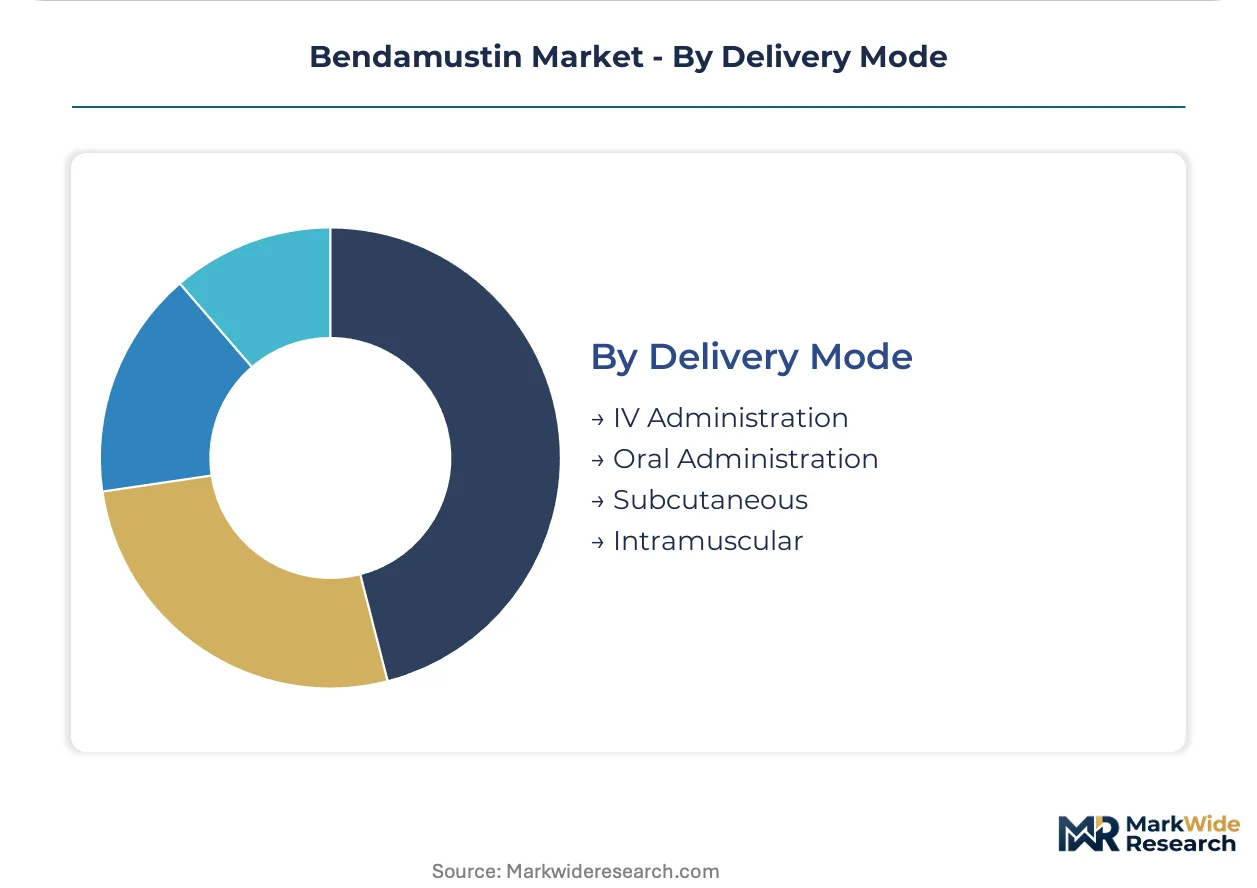
Clinical standardization sits with IV Administration. Patient convenience priorities are driving fastest uptake in Oral Administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of bendamustine active pharmaceutical ingredient concentrates among specialized chemical synthesis houses in India and China, while consumption gravity sits with hospital-based IV administration networks across the United States, Germany, and Japan.
United States
Oncology clinics in Texas and Florida are expanding bendamustine use in chronic lymphocytic leukemia front-line regimens. FDA bioequivalence guidelines for generic oncology injectables are forcing hospital procurement offices to requalify suppliers against stricter chemistry, manufacturing, and controls benchmarks. The Greater Boston cluster anchors investigator-initiated trials requiring flexible-dose presentations.
Germany
Integrated cancer networks in Bavaria and North Rhine-Westphalia are restructuring pharmacy service contracts to accommodate oral bendamustine tablet dispensing for maintenance therapy. EMA Annex 1 GMP standards for sterile products are elevating barrier-isolation expectations for European suppliers. Heidelberg's hematology centers are deepening rituximab combination protocol adoption.
Japan
Hospital networks in Tokyo and Osaka favor pre-mixed infusion configurations to minimize occupational exposure during cytotoxic preparation. PMDA local stability testing requirements extend registration timelines for foreign manufacturers seeking market access. The Kansai region's academic medical centers are evaluating subcutaneous delivery pharmacokinetic equivalence in research protocols.
India
API manufacturing clusters in Hyderabad and Ahmedabad supply specialized chemical synthesis for global formulation networks. CDSCO alignment with ICH Q3D guidelines on elemental impurities is tightening starting material qualification documentation. Gujarat's contract manufacturing organizations are backward-integrating into captive API sourcing to secure supply continuity.
United Kingdom
Hematology units in London and Manchester are adopting concentrated formulation technology to compress pharmacy preparation time. MHRA post-Brexit regulatory divergence from EU pharmacopeial standards is creating batch-release complexity for multi-market suppliers. The Cambridge oncology corridor is piloting homecare administration models for chronic lymphocytic leukemia maintenance.
Bendamustin Market Vendor Landscape
The competitive structure tilts toward integrated sterile injectables specialists with validated isolator capacity and multi-compendial testing capabilities. Hospital procurement consolidation is compressing vendor lists to qualified incumbents capable of meeting elevated FDA and EMA chemistry, manufacturing, and controls benchmarks. Two strategic archetypes dominate: legacy pharmaceutical conglomerates with oncology portfolios and mid-cap injectables specialists with concentrated formulation technology. Capacity expansion and pharmacopeial harmonization investments constitute the dominant competitive moves across manufacturing networks.
Among Israel and United States-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd. and Eagle Pharmaceuticals, Inc. exemplify contrasting positioning archetypes within the bendamustine supply base. Teva represents the integrated sterile injectables model with established hospital network relationships, while Eagle occupies the concentrated formulation technology tier reducing infusion bag volumes. Switzerland's Sandoz International GmbH and Germany's Fresenius Kabi AG anchor European supply continuity through multi-market regulatory registrations. India's Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. sit within the generic oncology injectables expansion segment, leveraging API manufacturing proximity for cost-positioned supply.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Eagle Pharmaceuticals, Inc. |
| Mundipharma International Limited |
| Eisai Co., Ltd. |
| Sandoz International GmbH |
| Natco Pharma Limited |
| Dr. Reddy's Laboratories Ltd. |
| Fresenius Kabi AG |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive API sourcing from Hyderabad and Ahmedabad synthesis houses anchors supply security for European and North American formulation networks, translating directly into pricing power for manufacturers with backward-integrated positions. Hospital procurement offices in the United States and Germany are compressing vendor lists to qualified incumbents, reinforcing the cost advantage of integrated sterile injectables specialists.
Pricing Analysis
Cost-down pressure on standard lyophilized vials accelerates because concentrated formulation technology reduces pharmacy preparation burden and commands premium positioning. Pricing stratifies across concentrated presentations, standard infusion configurations, and economy generic injectables, with differentiation driven by barrier-isolation certification tier and cold-chain service bundling. Margin tightening in economy-tier supply traces to API supply concentration among Indian and Chinese synthesis houses. Community oncology clinics exhibit highest price sensitivity, while academic medical centers prioritize preparation-time reduction over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for cytotoxic injectables constrain distribution radius from European and North American manufacturing hubs. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing in Germany, Switzerland, and the United States. Finished goods distribution runs through hospital procurement consortia and oncology GPOs in the United States, integrated cancer networks in Germany, and regional hospital federations in Japan. Single-source vulnerability in specialized chemical synthesis for bendamustine hydrochloride exposes formulation networks to disruption risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bendamustine supply base is consolidating around vertical-integration races, with manufacturers pursuing captive API sourcing to defend margin positions against procurement consolidation.
For Market Incumbents: Anchor supply continuity through exclusive agreements with Hyderabad and Ahmedabad synthesis houses, insulating against CDSCO regulatory tightening on starting material documentation. Invest in isolator line validation to meet EMA Annex 1 GMP barrier-isolation standards, compressing competitor access to European hospital networks. Defend against concentrated formulation technology displacement by licensing or developing reduced-infusion-volume presentations. For New Entrants and Emerging Players: Hospital pharmacy service contracts in Germany's integrated cancer networks represent the most penetrable channel for oral bendamustine tablet distribution. Target homecare administration protocols for chronic lymphocytic leukemia maintenance therapy, where reimbursement pathway adaptation is creating white-space opportunity. Enter through co-development partnerships with established oral oncology infrastructure providers rather than direct hospital contracting. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap injectables specialists with validated isolator capacity and multi-compendial testing capabilities. Long-term viability hinges on pharmacopeial harmonization execution and concentrated formulation technology adoption rates. Watch FDA bioequivalence guideline enforcement intensity as the inflection signal for supplier qualification cost escalation and vendor list compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive API Sourcing | Backward integration into Hyderabad synthesis houses secures supply continuity against CDSCO regulatory tightening. |
| Isolator Line Validation | EMA Annex 1 GMP compliance elevates barrier-isolation requirements, favoring qualified incumbents with validated capacity. |
| Concentrated Formulation Development | Reduced infusion bag volumes compress pharmacy preparation time in United States hospital outpatient departments. |
| Homecare Distribution Partnership | Oral tablet dispensing contracts with German integrated cancer networks extend treatment duration beyond infusion centers. |
| Multi-Compendial Testing Investment | Simultaneous USP, EP, and JP compliance enables batch-release arbitrage across fragmented pharmacopeial standards. |
Methodological Framework
FDA filings, EMA inspection reports, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced against primary interviews with sterile manufacturing executives, hospital procurement managers, and regulatory affairs leads at oncology formulation companies. Bottom-up and top-down triangulation validated volume estimates across dosage form, therapy area, and end-user segments.
Bottom-up modeling aggregated patient flow through chronic lymphocytic leukemia and lymphoma treatment protocols, while top-down analysis tracked manufacturer capacity and batch-release data across major pharmacopeial jurisdictions. Segmentation dimensions included product type, therapy area, end user, and delivery mode, with CAGRs derived from protocol adoption curves and reimbursement pathway evolution. Forecast inputs incorporated EMA Annex 1 GMP implementation timelines and PMDA stability testing burden effects on market access.
Caveats apply where pharmacopeial harmonization delays or API supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Sustained Release Drugs Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Levofloxacin Lactate Injection Market