
 Grand Mal Seizure Market | 2026-2036
Grand Mal Seizure Market Size, Share, and Industry Trends Forecast 2026-2036
Grand Mal Seizure Market Outlook
Aftermarket service revenue from chronic patient monitoring and dose-optimization programs is rewriting how epilepsy therapy economics work. Sanofi leverages its established neurology franchise to sustain high-touch patient support models across European markets. Pfizer Inc. anchors its position through manufacturing scale in parenteral benzodiazepine production, while UCB S.A. differentiates via specialized biologic therapies for drug-resistant grand mal presentations.
Grand mal seizures constitute generalized tonic-clonic episodes characterized by bilateral cortical involvement, loss of consciousness, and synchronous neuronal discharge exceeding 30 seconds in duration, with primary clinical purpose being emergency termination of status epilepticus and long-term prophylaxis against recurrence. Antiepileptic drugs occupy the dominant product category by volume, though intravenous delivery modes command premium pricing in acute hospital settings where rapid bioavailability determines clinical outcomes. Homecare end users represent the fastest-expanding channel as oral maintenance therapies shift post-stabilization from institutional to residential administration under remote neurology supervision.
FDA orphan drug designations and EMA accelerated assessment pathways for refractory epilepsy therapies are tightening clinical evidence requirements while compressing development timelines for novel mechanisms. The EU MDR and FDA 21 CFR Part 11 standards govern device-drug combination products used in seizure monitoring and emergency intervention, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor how decentralized clinical trial designs and real-world evidence mandates reshape competitive entry dynamics for next-generation antiepileptic formulations.
Market Dynamics
FDA orphan drug incentives for refractory epilepsy therapies are compressing development timelines while tightening clinical evidence requirements, forcing manufacturers to restructure R&D portfolios around accelerated assessment pathways and real-world evidence mandates.
Growth Catalysts
- EMA Accelerated Assessment:The EU's fast-track designation for drug-resistant seizure therapies reduces regulatory review periods, incentivizing biologics investment across European neurology markets.
- Homecare Channel Expansion:Post-stabilization patients in the United States and Japan are migrating from hospital-based maintenance to residential oral therapy administration under remote supervision.
- Aging Demographics:Germany's expanding geriatric population generates sustained demand for long-term prophylaxis against recurrent grand mal episodes.
Market Restraints
- API Supply Concentration:Parenteral benzodiazepine active pharmaceutical ingredients rely on concentrated Asian manufacturing, exposing formulators to geopolitical disruption risk.
- EU MDR Compliance Burden:Device-drug combination products for seizure monitoring face extended certification timelines and elevated quality system costs.
- Generic Substitution Pressure:Patent-expired antiepileptic molecules face aggressive pricing erosion from multi-source competitors in oral maintenance segments.
Strategic Opportunities
- Decentralized Clinical Trials:Remote patient monitoring technologies enable trial participation from residential settings, expanding recruitment pools for refractory epilepsy studies.
- Real-World Evidence Pathways:FDA's expanded use of post-market surveillance data creates alternative approval routes for novel antiepileptic mechanisms.
- Biologics White Space:Drug-resistant grand mal presentations in Japan lack targeted biologic options, presenting first-mover potential for specialized therapy developers.
Industry Challenges
- Specialized Neurology Talent Scarcity:Clinical trial design for status epilepticus interventions requires expertise in emergency pharmacology and neurocritical care, limiting qualified investigator pools.
- Legacy System Integration:Hospital electronic health record architectures often lack interoperability with modern seizure monitoring devices, complicating device-drug combination deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grand Mal Seizure Market |
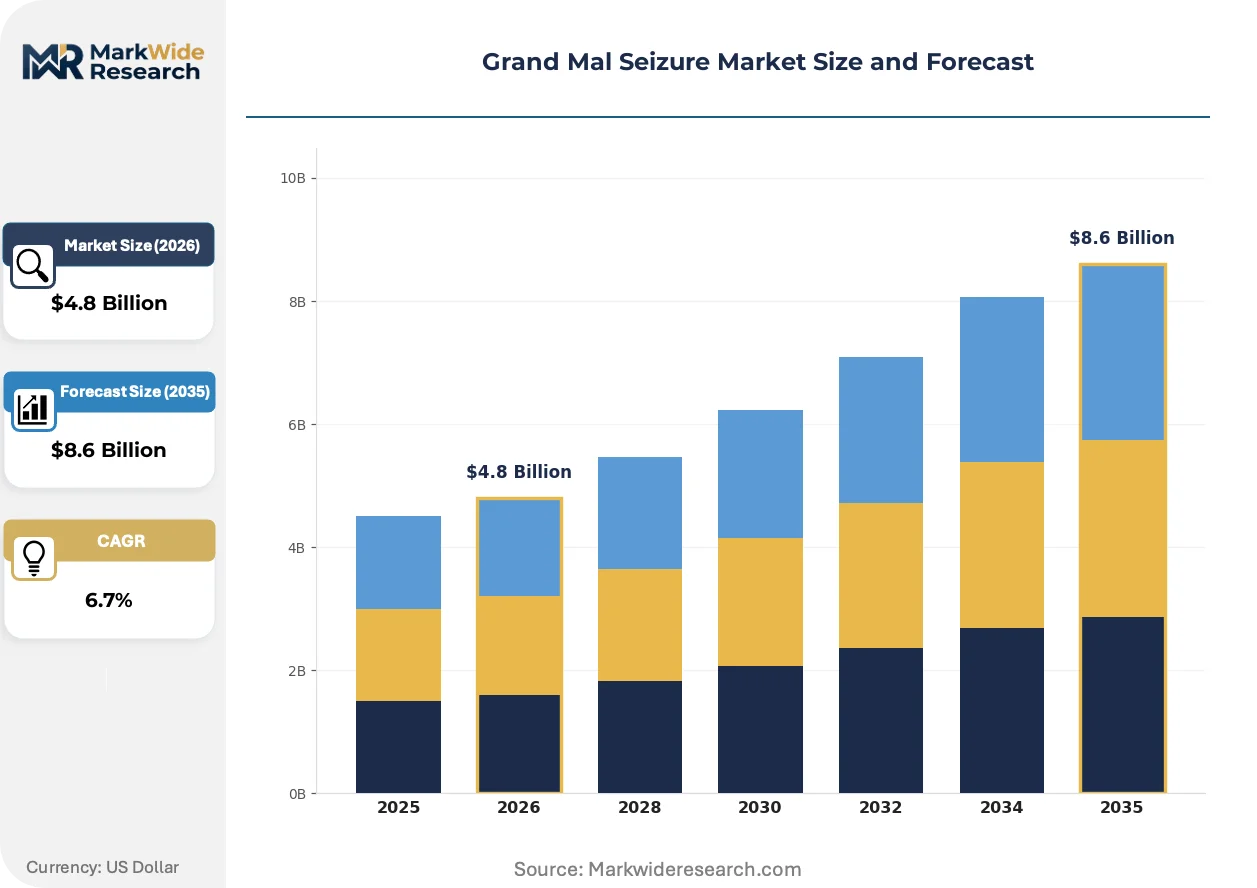
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiepileptic Drugs, Benzodiazepines, Barbiturates, Others Delivery Mode: Oral, Intravenous, Rectal, Topical End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Therapy Area: Neurology, Psychiatry, Pain Management, Others |
| Companies Covered | Sanofi, GSK plc, Pfizer Inc., Eisai Co. Ltd., Abbott Laboratories Inc., Novartis AG, Johnson & Johnson Services Inc., Takeda Pharmaceutical Company Limited, UCB S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grand Mal Seizure Market Strategic Shifts
Neurology therapy economics are pivoting toward continuous patient engagement models that monetize chronic disease management beyond acute intervention, with digital biomarkers and remote titration protocols redefining value capture.
Subcutaneous rescue formulations for seizure termination are hybridizing emergency pharmacology with patient-administered delivery, enabling ambulatory intervention outside institutional settings. Neurology practices in Germany and the United States are piloting these auto-injector platforms for high-risk patients. This convergence is hybridizing acute and chronic care revenue models, compressing traditional hospital admission economics.
EMA's Medical Device Regulation (MDR) is elevating clinical evidence requirements for implantable seizure detection systems, mandating extended follow-up periods and post-market performance monitoring. Manufacturers must now maintain active implant registries spanning multiple member states. The regulatory burden falls most heavily on mid-scale neurology device developers lacking dedicated regulatory affairs infrastructure.
Hospital procurement committees are unbundling emergency benzodiazepine supply contracts from broader anesthesia formulary agreements, creating standalone sourcing categories with distinct technical specifications. This fragmentation is displacing incumbent pharmaceutical distributors who previously leveraged portfolio breadth. The pattern is most pronounced in United States academic medical centers consolidating neurology service lines.
Grand Mal Seizure Market Segmentation
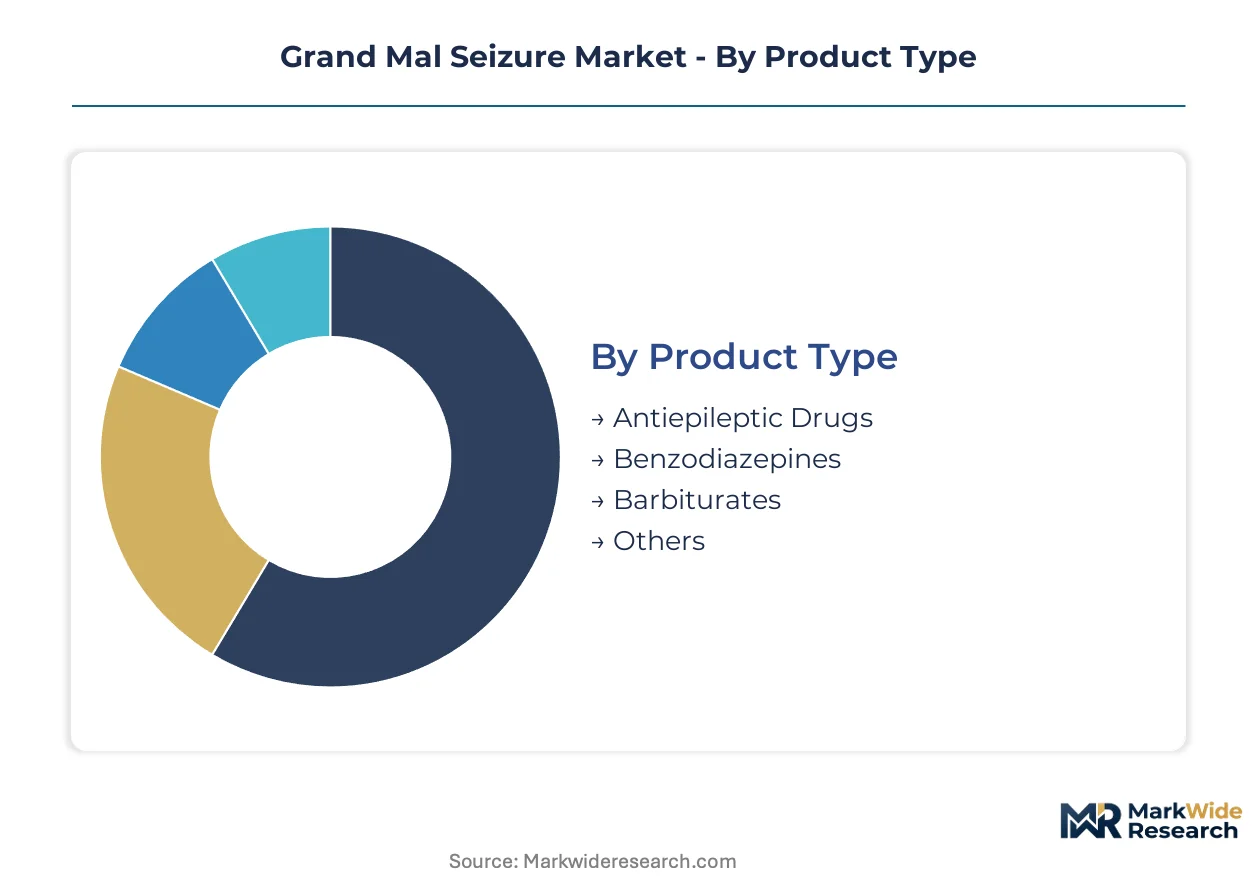
Grand mal seizure therapeutics fragment across pharmacological mechanisms, administration routes, and care settings that each impose distinct regulatory, reimbursement, and clinical evidence requirements on manufacturers.
Product Type:
Pharmacological diversity spans legacy small molecules to emerging biologics, with each class carrying differentiated development timelines and patent exposure profiles.
- Antiepileptic Drugs:Sodium channel blockers, GABA enhancers, and glutamate antagonists constitute the maintenance therapy backbone for recurrent seizure prophylaxis. Demand concentrates in Germany and Japan where long-term oral regimens dominate geriatric patient management under national reimbursement formularies.
- Benzodiazepines:GABA-A receptor agonists deliver rapid seizure termination through enhanced inhibitory neurotransmission, with intravenous lorazepam and diazepam anchoring emergency department protocols. United States hospital systems drive volume through status epilepticus treatment pathways that prioritize speed of bioavailability.
- Barbiturates:Pentobarbital and phenobarbital retain niche utility in refractory cases requiring induced coma for neuroprotection.
- Others:Ketamine, propofol, and investigational biologics address drug-resistant presentations unresponsive to first-line agents.
The dominant share belongs to antiepileptic drugs, while benzodiazepines are closing the gap fastest through expanded emergency department adoption.
Delivery Mode:
Route selection hinges on seizure acuity, patient consciousness, and care setting infrastructure capabilities.
- Oral:Tablets and extended-release formulations enable chronic maintenance therapy with patient-administered convenience. Post-stabilization patients in Japan and the United States increasingly transition to home-based oral regimens under remote neurology supervision.
- Intravenous:Direct vascular administration achieves therapeutic plasma concentrations within minutes, making this route mandatory for status epilepticus intervention. United States academic medical centers unbundle benzodiazepine procurement from anesthesia formularies, creating standalone sourcing categories.
- Rectal:Diazepam gel provides caregiver-administered rescue therapy for out-of-hospital seizure clusters when intravenous access is unavailable.
- Topical:Transdermal patches and gels remain investigational for seizure prophylaxis with limited commercial penetration.
Oral formulations command the largest patient volume, though intravenous delivery generates the steepest expansion trajectory through hospital emergency protocol standardization.
End User:
Care setting migration from institutional to residential environments is reshaping distribution economics and patient monitoring requirements.
- Hospitals:Emergency departments and neurocritical care units manage acute presentations requiring immediate intravenous intervention and continuous EEG monitoring. Germany's established neurology infrastructure supports sustained therapeutic uptake across academic medical centers.
- Homecare:Residential administration of oral maintenance therapies and subcutaneous rescue auto-injectors enables chronic disease management outside institutional settings. United States and Japanese reimbursement policies increasingly cover remote neurology supervision for high-risk patients.
- Clinics:Outpatient neurology practices handle diagnosis, medication titration, and transition coordination between acute and chronic care phases.
- Rehabilitation Centers:Post-acute facilities address seizure recurrence risk during recovery from traumatic brain injury or stroke.
Hospitals retain the dominant share, while homecare is gaining share fastest through decentralized care model adoption.
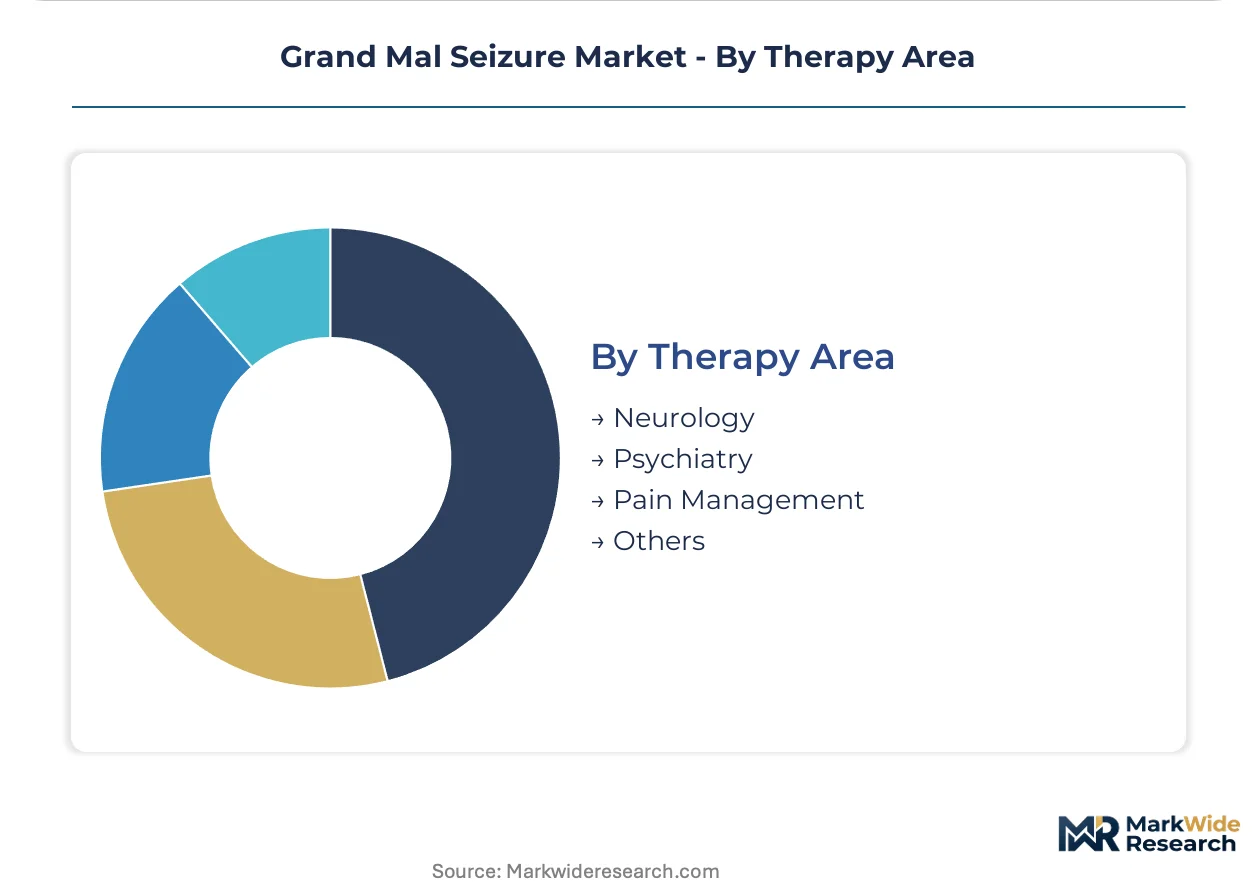
Therapy Area:
Clinical specialization determines prescriber access patterns and continuing medical education requirements for manufacturer field forces.
- Neurology:Epileptologists and general neurologists direct comprehensive seizure management from diagnosis through long-term prophylaxis. United States neurology practices pilot subcutaneous rescue formulations that hybridize emergency pharmacology with patient-administered delivery.
- Psychiatry:Psychiatric comorbidity management addresses depression, anxiety, and psychosis that frequently accompany refractory epilepsy.
- Pain Management:Neuropathic pain syndromes in seizure patients create overlapping therapeutic targets for sodium channel modulators.
- Others:Emergency medicine, pediatrics, and geriatrics contribute specialized intervention protocols for distinct patient populations.
Neurology commands the dominant share, while psychiatry is expanding most quickly through integrated mental health service line development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. United States hospital systems absorb premium intravenous benzodiazepine pricing for emergency protocols, while Indian and Southeast Asian markets face acute substitution pressure toward oral generics. Germany and Japan occupy intermediate positions where reimbursement formularies balance clinical efficacy against long-term prophylaxis costs.
United States
Academic medical centers unbundle emergency benzodiazepine procurement from anesthesia formularies, creating standalone sourcing categories with distinct technical specifications. FDA orphan drug incentives compress development timelines for refractory epilepsy therapies while tightening clinical evidence requirements. Neurology service line consolidation in major metropolitan hospital systems concentrates demand among integrated delivery networks.
Germany
Expanding geriatric populations generate sustained demand for long-term seizure prophylaxis under statutory health insurance reimbursement. EMA accelerated assessment pathways incentivize biologics investment across European neurology markets. Bavaria's established neurology infrastructure anchors therapeutic uptake through academic medical centers with specialized epileptology units.
Japan
Aging demographics and established neurology infrastructure support sustained therapeutic uptake for maintenance therapies. PMDA regulatory frameworks govern approval pathways for novel antiepileptic mechanisms while national reimbursement policies increasingly cover remote neurology supervision. Tokyo-Osaka medical corridors concentrate specialized epilepsy treatment capacity.
India
Generic substitution pressure dominates oral maintenance segments as patent-expired antiepileptic molecules face aggressive pricing erosion from multi-source competitors. The country's national pharmaceutical regulator maintains bioequivalence standards that shape competitive entry dynamics. Maharashtra and Gujarat pharmaceutical clusters concentrate active pharmaceutical ingredient manufacturing for benzodiazepine formulations.
United Kingdom
NHS England's specialized commissioning frameworks direct funding toward drug-resistant epilepsy interventions through designated tertiary centers. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways that diverge from EMA timelines. London-Southeast and Manchester neuroscience clusters concentrate clinical trial infrastructure for novel therapeutic mechanisms.
Grand Mal Seizure Market Competitive Environment
Established neurology franchises and specialized biologic developers split the market between maintenance therapy scale and targeted intervention depth. The competitive structure tilts toward consolidation among parenteral emergency formulations while fragmenting across oral generic maintenance segments. Three archetypes dominate: diversified pharmaceutical conglomerates with neurology divisions, mid-scale biologic specialists focused on refractory presentations, and generic manufacturers competing on oral antiepileptic volume. Dominant competitive moves include strategic partnerships for decentralized clinical trial execution and backward integration into active pharmaceutical ingredient supply.
Within the diversified pharmaceutical tier, Sanofi leverages its established neurology franchise across European markets while Pfizer Inc. anchors manufacturing scale in parenteral benzodiazepine production. UCB S.A. occupies a specialized position through biologic therapies for drug-resistant grand mal presentations. These three exemplify how competitive positioning diverges between emergency pharmacology scale and targeted biologic development.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| Pfizer Inc. |
| Eisai Co. Ltd. |
| Abbott Laboratories Inc. |
| Novartis AG |
| Johnson & Johnson Services Inc. |
| Takeda Pharmaceutical Company Limited |
| UCB S.A. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility directly compresses margins on parenteral benzodiazepine formulations sourced from concentrated Asian API manufacturers, forcing United States hospital procurement committees to unbundle emergency supply contracts and creating price differentiation between institutional and homecare delivery channels.
Pricing Analysis
Aftermarket service revenue from chronic patient monitoring and dose-optimization programs drives lifetime value capture beyond acute intervention. Three-tier pricing structure across premium biologic therapies, standard branded antiepileptics, and economy oral generics stratifies the market, with United States academic medical centers absorbing premium intravenous pricing for emergency protocols while Indian markets face aggressive substitution toward multi-source competitors. Cost compression in patent-expired oral maintenance segments is intensifying because of generic manufacturer consolidation, making geriatric patients in Germany and Japan the least price-sensitive segment due to statutory reimbursement formularies.
Supply Chain Analysis
Export-control restrictions on pharmaceutical manufacturing equipment limit technology transfer to emerging production hubs, constraining capacity expansion outside established centers. Active pharmaceutical ingredient supply concentrates in India and China for benzodiazepine precursors, with Germany and Japan hosting downstream formulation and packaging operations. Parenteral drug production rests on concentrated sodium channel blocker intermediates, GABA-agonist raw materials, and specialized sterile fill-finish equipment. Single-source vulnerability in Asian API manufacturing exposes formulators to geopolitical disruption risk. Distribution runs through hospital procurement committees, specialized neurology distributors, and direct-to-pharmacy channels for oral maintenance therapies.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as subcutaneous rescue auto-injectors and remote neurology supervision protocols penetrate post-stabilization patient populations previously managed through institutional readmission.
For Market Incumbents: Build regulatory affairs infrastructure as a moat against EMA MDR compliance burdens that disproportionately burden mid-scale competitors lacking dedicated quality systems. Sanofi and Pfizer should anchor backward integration into parenteral benzodiazepine API supply to mitigate Asian manufacturing concentration risk, while UCB S.A. must defend its biologic positioning through accelerated assessment pathway investments before generic substitution pressure reaches drug-resistant segments. For New Entrants and Emerging Players: Build out decentralized clinical trial capabilities to access refractory epilepsy patient pools in Japan's Tokyo-Osaka medical corridor, where drug-resistant grand mal presentations lack targeted biologic options. White-space targets include subcutaneous rescue formulations for United States homecare channels and real-world evidence platforms for FDA post-market surveillance data. The most penetrable entry point lies in specialized biologics for status epilepticus interventions, with go-to-market execution through neurology service line partnerships at academic medical centers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates spinning off legacy neurology divisions facing generic erosion pressure. Long-term viability hinges on exposure to biologics pipelines and device-drug combination products rather than commoditized oral maintenance molecules. Acquisition archetypes include mid-scale biologic specialists with EMA accelerated assessment designations and remote patient monitoring technology platforms. Watch FDA orphan drug designation velocity as the inflection signal for refractory epilepsy R&D prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Accelerated Assessment Pathway | Compresses review timelines for biologics targeting drug-resistant presentations in European neurology markets. |
| Decentralized Clinical Trial Infrastructure | Expands recruitment pools for refractory epilepsy studies through residential monitoring technologies. |
| Backward Integration into API Supply | Captures upstream control over parenteral benzodiazepine precursors concentrated in Asian manufacturing. |
| Subcutaneous Rescue Formulation Development | Hybridizes emergency pharmacology with patient-administered delivery outside institutional settings. |
| Real-World Evidence Platform Investment | Creates alternative FDA approval routes using post-market surveillance data from chronic patient monitoring. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings, while secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling and top-down therapeutic class spend analysis triangulate market sizing across the projection horizon.
Calibration against historical antiepileptic drug launch trajectories and reimbursement adoption curves refines the analytical framework. Segmentation dimensions modeled include pharmacological mechanism, administration route, care setting, patient population severity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions, incorporating FDA orphan drug designation velocity and EMA accelerated assessment throughput as epilepsy-specific forecast inputs.
Practitioners should monitor geopolitical disruption in Asian API manufacturing, EMA MDR certification timeline extensions, and generic substitution intensity in oral maintenance segments for early signals requiring forecast revision. Cross-checking against CMS Medicare Part D spending data and Japan's national health insurance reimbursement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market