
 Menstrual Cup Market | 2026-2036
Menstrual Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Menstrual Cup Market Intelligence
Capital-intensity divergence between medical-grade silicone processors and commodity elastomer assemblers is rotating competitive advantage toward vertically integrated manufacturers. Diva International Inc. leverages its North American distribution infrastructure to sustain pharmacy shelf presence across Canada and the United States. Me Luna GmbH anchors European demand through precision thermoplastic elastomer engineering and localized German production. Lune Group Oy Ltd. competes in Nordic markets with minimalist design specialization and direct-to-consumer channel control.
A menstrual cup is a bell-shaped, flexible receptacle typically molded from medical-grade silicone, thermoplastic elastomer, or natural rubber, designed for intravaginal collection and retention of menstrual fluid during menstruation. Wall thickness generally ranges from 0.3 to 1.0 millimeters, with rim diameters spanning 38 to 47 millimeters to accommodate anatomical variation, and the device serves as a reusable alternative to disposable tampons and pads for menstrual management. Silicone formulations dominate the material segment due to biocompatibility certification requirements and extended product lifespan claims, while thermoplastic elastomer variants are gaining traction in price-sensitive European markets. Online distribution channels now capture the fastest-growing share of unit volume, though pharmacies retain margin concentration through clinician endorsement and insurance reimbursement pathways in regulated healthcare systems.
FDA 510(k) clearance requirements and Health Canada Medical Device Establishment Licensing govern silicone menstrual cup commercialization in North America, with both regulators mandating biocompatibility testing under ISO 10993 standards to ensure patient safety. The EU Medical Device Regulation and REACH chemical compliance frameworks shape European market access, requiring notified body involvement for higher-risk product classifications and restricting certain plasticizer additives in elastomer compounds. Stakeholders must monitor evolving state-level menstrual equity legislation in the United States, where tax exemption and school distribution mandates are reshaping procurement channels and consumer subsidy structures.
Market Dynamics
University health clinic procurement programs across Canada, Germany, and the United Kingdom are redirecting institutional purchasing power toward reusable silicone devices, compressing traditional disposable product channels while creating volume anchors for certified manufacturers.
Growth Catalysts
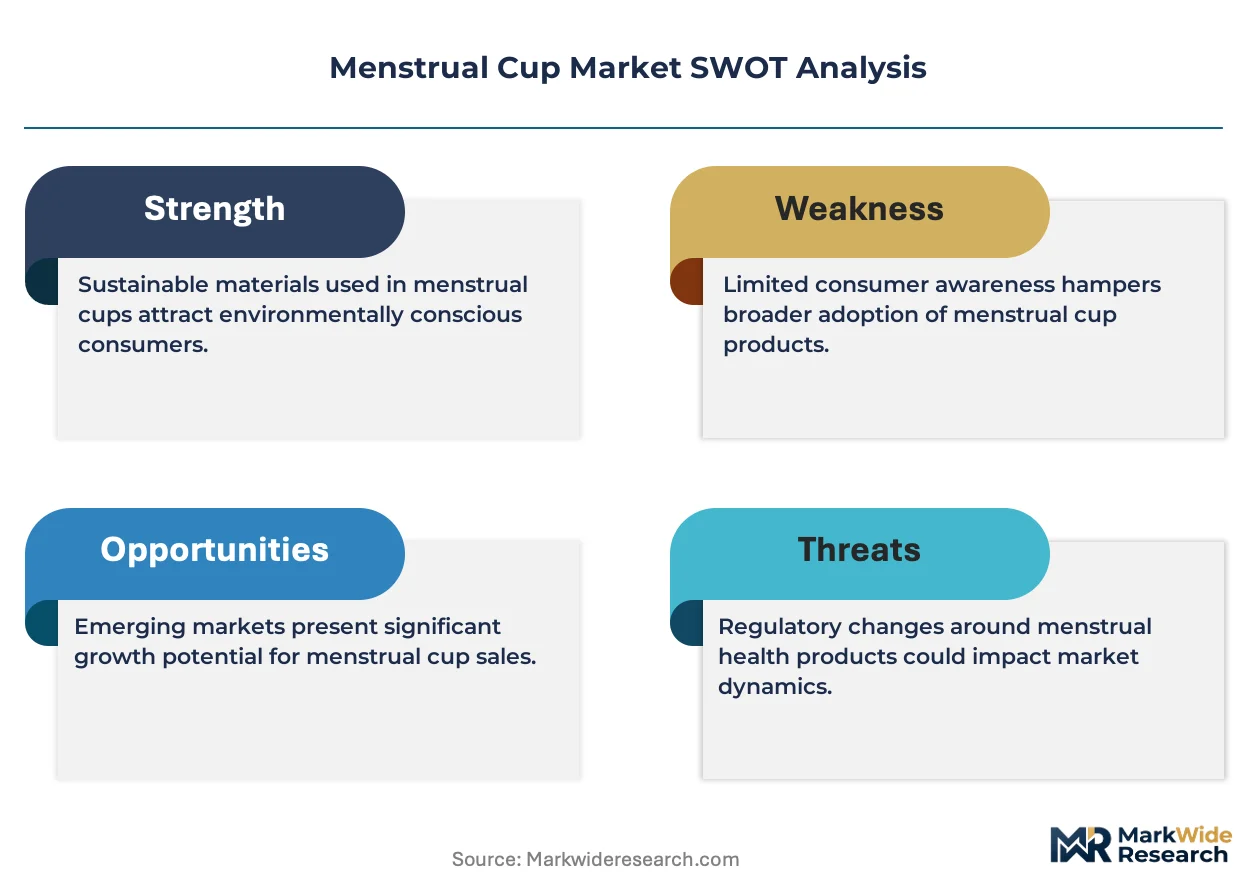
- ISO 10993 biocompatibility certification:Standardized testing frameworks reduce regulatory duplication across FDA and Health Canada pathways, accelerating commercial entry for medical-grade silicone formulations.
- German environmental policy:Extended producer responsibility mandates and single-use plastic restrictions redirect consumer preference toward reusable menstrual management solutions.
- Thermoplastic elastomer engineering:Precision molding advances lower unit economics for price-sensitive European segments without sacrificing medical device compliance.
Market Restraints
- Medical-grade silicone supply concentration:Specialty polymer production clusters in limited chemical processing regions, exposing assemblers to input cost volatility and qualification delays.
- EU Medical Device Regulation classification friction:Notified body involvement requirements for higher-risk classifications extend certification timelines and inflate compliance expenditure for new entrants.
- Cultural substitution barriers:Intravaginal product unfamiliarity in certain demographics sustains tampon and pad preference, limiting addressable market expansion despite environmental messaging.
Strategic Opportunities
- United States state-level menstrual equity legislation:Tax exemption mandates and school distribution programs create subsidized procurement channels previously inaccessible to premium-priced reusable devices.
- Direct-to-consumer subscription models:Digital-native distribution bypasses pharmacy margin compression while capturing lifetime value through accessory and replacement cycles.
- Silicone-thermoplastic hybrid formulations:Material convergence enables tiered product portfolios spanning premium medical-grade and accessible elastomer variants from unified manufacturing platforms.
Industry Challenges
- Biocompatibility testing talent scarcity:ISO 10993 specialized laboratory capacity constraints delay product validation for manufacturers without captive testing infrastructure.
- Legacy pharmacy shelf space negotiation:Incumbent disposable product manufacturers defend retail positioning through volume rebates, compressing margin recovery for reusable device entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menstrual Cup Market |
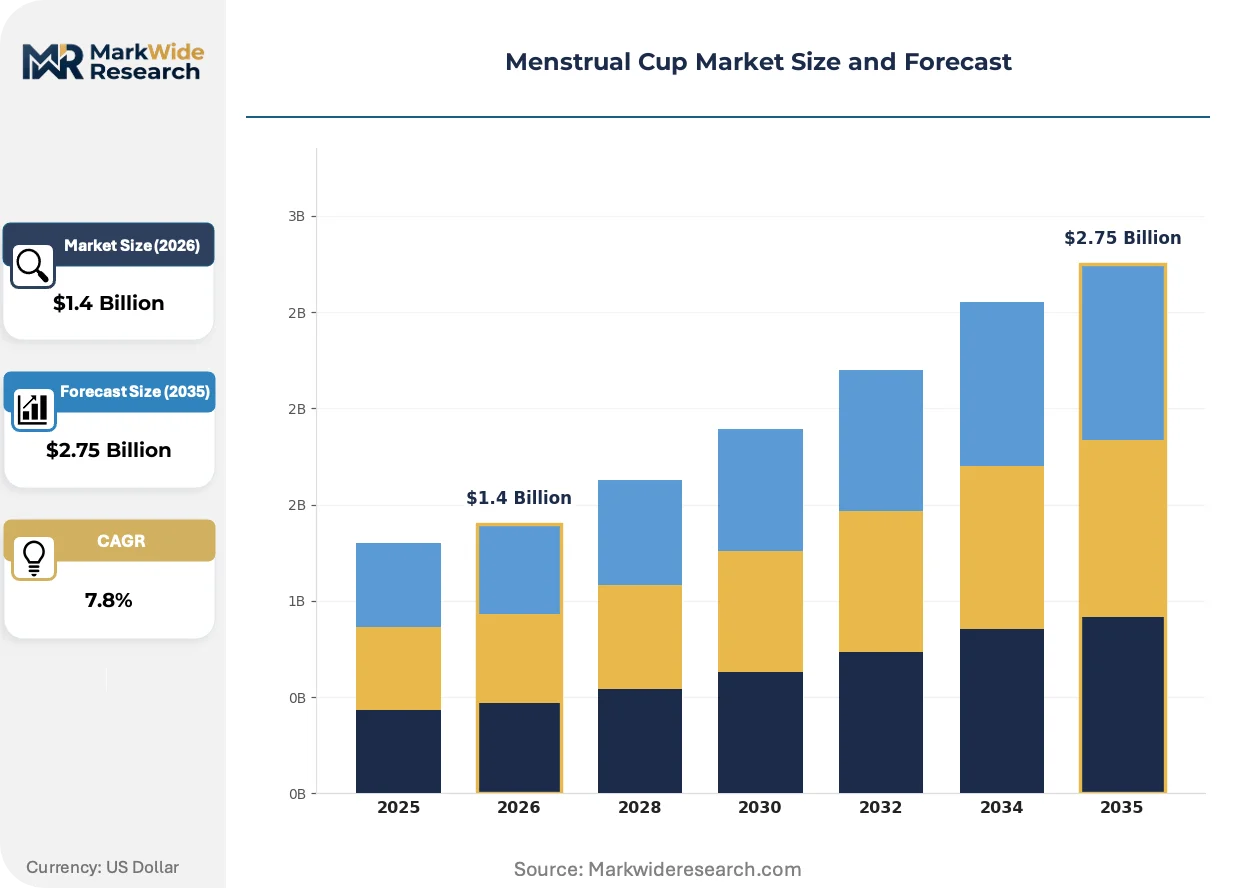
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable, Disposable, Organic, Non-toxic Material: Silicone, Rubber, Latex, Thermoplastic Elastomer Distribution Channel: Online, Retail, Pharmacies, Healthcare Providers End User: Women, Teens, Athletes, Postpartum |
| Companies Covered | Diva International Inc., Mooncup Ltd., Me Luna GmbH, The Flex Company, Lena Cup LLC, Saalt, Lune Group Oy Ltd., LELOi AB (Intimina), Blossom Cup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menstrual Cup Market Strategic Shifts & Innovations
Material science differentiation and regulatory pathway optimization are compressing product development cycles while fragmenting competitive advantage between premium medical-grade specialists and agile direct-to-consumer brands.
Silicone formulation technology is bifurcating competitive positioning across the menstrual cup landscape. Medical-grade platinum-cured silicone dominates premium segments requiring extended lifespan certification and hypoallergenic claims. University health clinics in Canada and the United Kingdom prioritize these formulations for institutional procurement. Thermoplastic elastomer alternatives capture price-sensitive volume in German and Nordic markets, compressing average selling prices while expanding unit penetration.
Health Canada Medical Device Establishment Licensing requirements are tightening quality system expectations for silicone feminine hygiene commercialization. Manufacturers must demonstrate ISO 13485 compliance alongside biocompatibility testing under ISO 10993 standards. European notified bodies under the EU Medical Device Regulation are extending review timelines for higher-risk classifications, forcing smaller assemblers toward partnership or acquisition.
Subscription-based direct-to-consumer channels are displacing pharmacy retail as the primary growth vector for established brands. Digital-native entrants in Nordic markets leverage minimalist design specialization and social proof mechanisms to bypass traditional clinician endorsement pathways. Germany and the United Kingdom exhibit the strongest channel rotation, where environmental certification transparency drives online purchase decisions ahead of in-shelf availability.
Menstrual Cup Market Segmentation
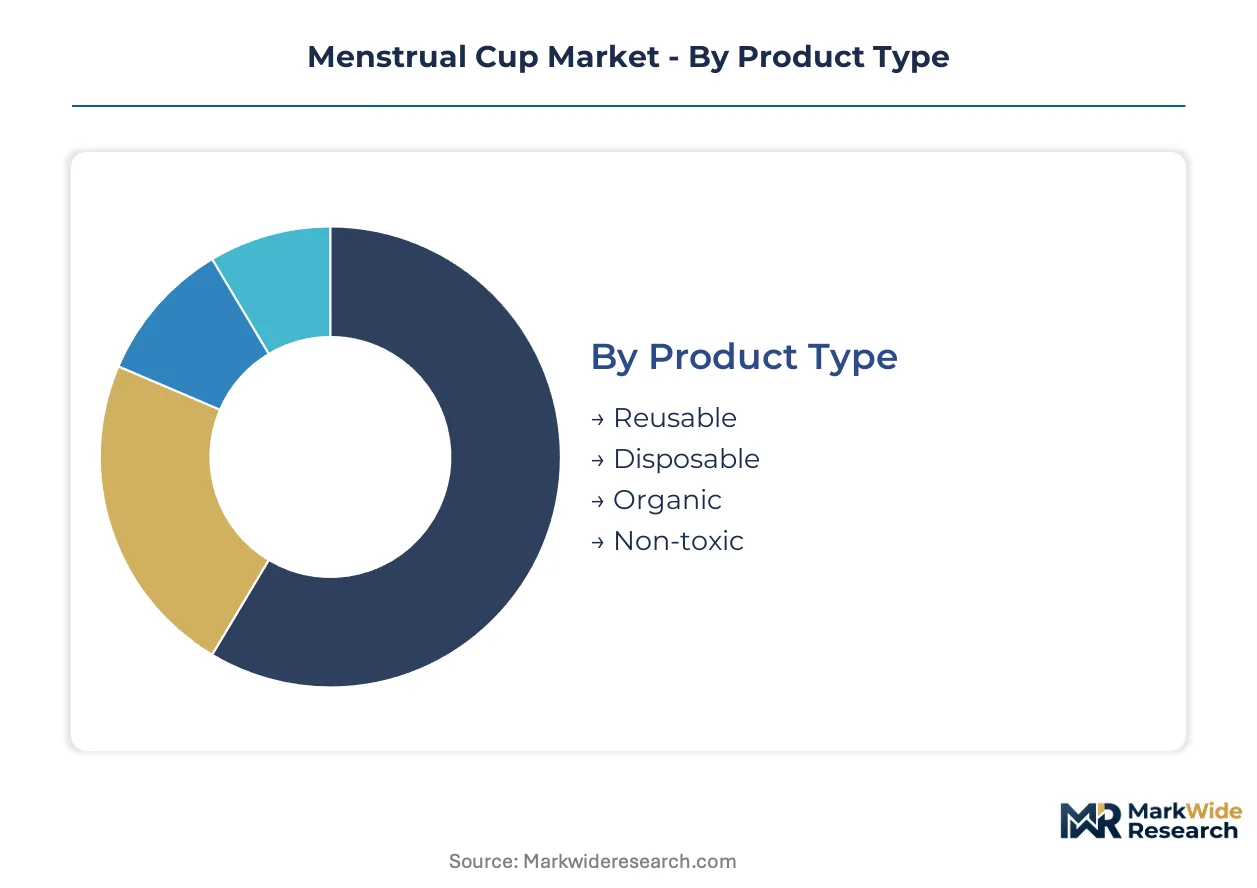
Segmentation in the menstrual cup market reveals how material science, channel economics, and user physiology intersect to create distinct competitive battlegrounds. Manufacturers must align formulation investments with the substitution pressures each segment faces from incumbent disposable products.
Product Type:
Reusable designs confront the steepest substitution threat from conventional tampons and pads, while disposable variants compete directly against established single-use infrastructure in retail and institutional procurement channels.
- Reusable:Medical-grade silicone or thermoplastic elastomer construction enables 5-10 year product lifespans. University health clinics in Canada and Germany prioritize these for procurement programs seeking to reduce campus waste streams and long-term menstrual product expenditure.
- Disposable:Single-use formulations target travelers, emergency preparedness kits, and users transitioning from tampons. Demand concentrates in airport retail and subscription box inserts where convenience overrides environmental calculus.
- Organic:Natural rubber or plant-based polymer variants appeal to chemical-sensitive demographics. German environmental policy and REACH compliance frameworks favor these formulations in European markets.
- Non-toxic:Certifications against phthalates, BPA, and synthetic dyes drive premium positioning. Health Canada and FDA biocompatibility pathways validate these claims for North American pharmacy channels.
Reusable cups anchor the volume base while disposable variants gain share at the steepest rate among convenience-oriented user cohorts.
Material:
Cost tier differentiation separates medical-grade specialists from commodity elastomer assemblers, with supply concentration in German and North American chemical processing clusters shaping competitive access.
- Silicone:Platinum-cured medical-grade formulations dominate premium positioning through ISO 10993 biocompatibility certification and hypoallergenic claims. FDA 510(k) clearance and Health Canada Medical Device Establishment Licensing requirements reinforce silicone's institutional procurement advantage.
- Rubber:Natural latex variants serve price-sensitive segments and users seeking petroleum-free alternatives. Supply volatility from Southeast Asian rubber plantations constrains formulation consistency for European manufacturers.
- Latex:Lower-cost synthetic options expand accessibility in developing markets where medical device regulatory pathways remain underdeveloped. Allergy prevalence limits addressable market scope in North American and European segments.
- Thermoplastic Elastomer:Precision molding advances enable thinner wall construction and softer durometer ratings. German engineering capabilities and Nordic design specialization concentrate demand for TPE variants in European markets.
Silicone commands the premium tier while thermoplastic elastomer climbs the fastest as price-sensitive European volume expands.
Distribution Channel:
Channel margin structures diverge sharply between pharmacy networks with clinician endorsement leverage and digital-native platforms capturing lifetime value through subscription mechanics.
- Online:Direct-to-consumer subscription models bypass retail margin compression and capture replacement cycle revenue. Germany and the United Kingdom exhibit the strongest channel rotation toward environmental certification transparency in digital purchase decisions.
- Retail:Mass-market shelf presence requires volume rebates and slotting fee negotiation against incumbent disposable manufacturers. Limited retail space for feminine hygiene constrains reusable product visibility in conventional grocery and drugstore chains.
- Pharmacies:Clinician endorsement and insurance reimbursement pathways in regulated healthcare systems sustain margin concentration. Health Canada and FDA device classification enables pharmacy positioning as medical-grade alternatives.
- Healthcare Providers:University health clinics, midwifery practices, and postpartum care facilities create institutional volume anchors. Procurement programs across Canada, Germany, and the United Kingdom redirect purchasing power toward certified reusable devices.
Pharmacies retain the highest per-unit margins while online channels expand most quickly through subscription mechanics and social proof mechanisms.
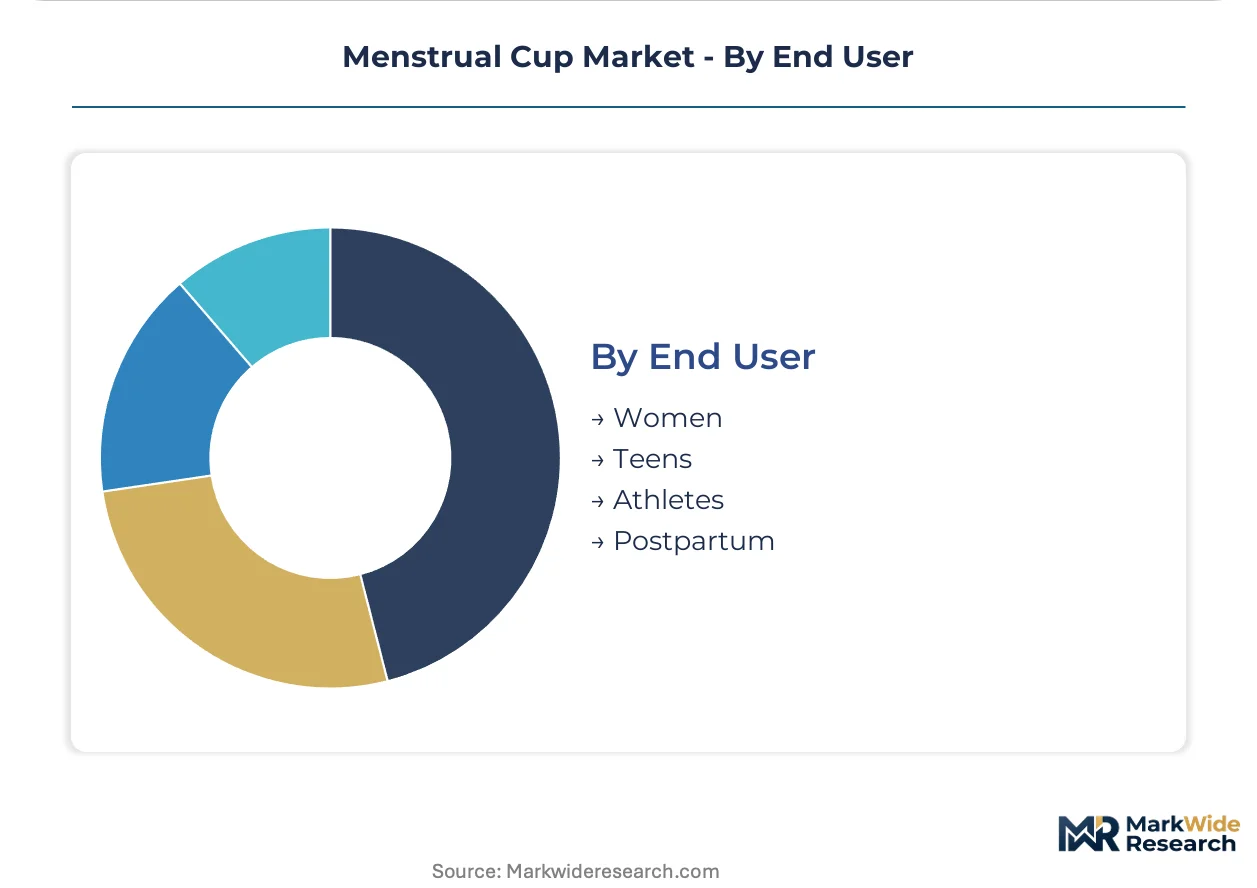
End User:
User physiology and life-stage requirements fragment product specifications across rim diameter, stem length, and firmness gradients, with athletic and postpartum segments driving specialized design innovation.
- Women:The core demographic spans ages 18-45 with anatomical variation requiring 38-47mm rim diameter options. General-purpose designs dominate unit volume but face commoditization pressure from specialized alternatives.
- Teens:Smaller dimensions and softer durometer ratings accommodate anatomical immaturity and first-time user anxiety. School distribution mandates in select US states create subsidized procurement channels for youth-focused product lines.
- Athletes:High-activity formulations prioritize seal reliability under physical stress and discreet portability. Competitive swimmers and runners drive demand for stemless or adjustable-stem designs that minimize sensation during movement.
- Postpartum:Larger-capacity, softer-construction variants address cervical position changes and heightened sensitivity following childbirth. Midwifery practice recommendations and hospital discharge kit inclusion create trusted introduction pathways.
Women constitute the volume foundation while teens gain share fastest through school-based distribution programs and digital-native brand engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Canadian procurement channels, where institutional buyers leverage volume commitments against premium medical-grade formulations. Price-sensitive volume clusters in Southeast Asian manufacturing zones and select Latin American markets, compressing margins for commodity elastomer variants.
United States
State-level menstrual equity legislation in California and New York mandates tax exemptions and school distribution programs, redirecting procurement toward certified reusable devices. FDA 510(k) clearance requirements under ISO 10993 standards govern commercial entry for silicone formulations. University health clinics in Massachusetts and the Pacific Northwest anchor institutional volume through campus sustainability initiatives.
Germany
Extended producer responsibility mandates and single-use plastic restrictions accelerate consumer substitution toward reusable menstrual management. EU Medical Device Regulation classification through notified bodies shapes compliance expenditure for higher-risk product tiers. Precision thermoplastic elastomer engineering clusters in Baden-Württemberg and Bavaria supply price-sensitive European segments with thinner-wall construction capabilities.
United Kingdom
NHS procurement frameworks and university clinic programs concentrate demand for biocompatibility-certified silicone devices. REACH chemical compliance restricts certain plasticizer additives in elastomer compounds entering British markets. London and Manchester host direct-to-consumer brand headquarters leveraging environmental certification transparency in digital purchase decisions.
Canada
Health Canada Medical Device Establishment Licensing streamlines commercial pathways for silicone feminine hygiene products alongside ISO 13485 quality system requirements. Provincial menstrual equity policies in British Columbia and Ontario mandate institutional procurement of reusable alternatives. Toronto and Vancouver anchor distribution infrastructure serving North American pharmacy networks.
France
ANSM medical device oversight and environmental labeling requirements shape product positioning for silicone and natural rubber variants. Reimbursement pathway development under national health insurance creates pharmacy channel opportunities for certified devices. Lyon and Paris concentrate direct-to-consumer marketing operations targeting chemical-sensitive demographics with organic formulation claims.
Menstrual Cup Market Key Industry Players
Concentration sits with vertically integrated medical-grade silicone processors and agile direct-to-consumer specialists. The vendor base splits between premium certification-heavy incumbents and digital-native challengers exploiting subscription mechanics. Three archetypes dominate: platinum-cured silicone specialists, thermoplastic elastomer engineers, and minimalist design direct-to-consumer brands. Competitive moves center on backward integration into polymer processing and geographic expansion through regulatory pathway optimization.
Among North American incumbents, Diva International Inc. occupies the pharmacy channel anchor position, while Me Luna GmbH exemplifies European precision manufacturing capabilities. Lune Group Oy Ltd. represents the Nordic direct-to-consumer minimalist archetype, leveraging subscription models to bypass traditional retail margin structures. These three companies illustrate the geographic and channel specialization fracturing competitive advantage across the landscape.
| Leading Market Players |
|---|
| Diva International Inc. |
| Mooncup Ltd. |
| Me Luna GmbH |
| The Flex Company |
| Lena Cup LLC |
| Saalt |
| Lune Group Oy Ltd. |
| LELOi AB (Intimina) |
| Blossom Cup |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between German chemical processors and Nordic device assemblers lock in medical-grade silicone supply access while anchoring price visibility across multi-year procurement cycles. These contractual structures insulate certified manufacturers from spot-market volatility in platinum-cured formulations while compressing margin recovery for smaller assemblers lacking volume commitments.
Pricing Analysis
The customization-premium spread separates configured-to-order medical-grade variants from standard thermoplastic elastomer offerings. Subscription-based direct-to-consumer models capture lifetime value through replacement cycles, while pharmacy channels sustain per-unit premiums via FDA and Health Canada certification requirements. Price differentiation hinges on ISO 10993 biocompatibility tier and clinician endorsement access. Cost compression in the elastomer segment intensifies as precision molding advances lower unit economics. University health clinics and institutional buyers exhibit lowest price sensitivity; price-sensitive volume clusters in developing markets where regulatory pathways remain underdeveloped.
Supply Chain Analysis
Inventory buffers for medical-grade silicone extend lead times to 12-16 weeks, constraining agile response to demand spikes. Supply concentrates in German chemical processing clusters and North American specialty polymer facilities, with secondary sourcing from Southeast Asian rubber plantations for natural latex variants. Raw material dependencies center on platinum catalysts, petroleum-derived elastomer feedstocks, and precision molding equipment. Single-source vulnerability in ISO 10993 certified laboratory capacity delays product validation for manufacturers without captive testing infrastructure. Distribution runs through direct-to-consumer subscription platforms and pharmacy networks with clinician endorsement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biocompatibility testing infrastructure represents the critical chokepoint, with ISO 10993 laboratory capacity constraints separating scaled incumbents from aspirant entrants. Manufacturers lacking captive validation capabilities face extended commercialization timelines and partnership dependency.
For Market Incumbents: Secure backward integration into medical-grade silicone processing to defend margin position against commodity elastomer assemblers. Anchor pharmacy shelf presence through volume commitments against disposable product incumbents while expanding university health clinic procurement programs in Canada and Germany. Certification investment in EU Medical Device Regulation pathways creates defensive moats against digital-native challengers. For New Entrants and Emerging Players: Anchor in teen-focused product lines and school distribution mandates across US states with menstrual equity legislation. Target postpartum segments through midwifery practice partnerships and hospital discharge kit inclusion. Direct-to-consumer subscription models with minimalist design positioning bypass legacy retail margin compression and capture replacement cycle revenue. For Investors and Strategic Acquirers: Direct-to-consumer brands with established subscription mechanics and Nordic design specialization present acquisition targets with channel control assets. Long-term viability centers on regulatory pathway optimization capabilities and material science differentiation rather than pure brand equity. Watch for state-level menstrual equity legislation acceleration as inflection signal for subsidized procurement channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Certification | FDA and Health Canada pathways accelerate commercial entry for medical-grade silicone formulations. |
| Direct-to-Consumer Subscription Launch | Germany and UK channel rotation bypasses pharmacy margin compression through digital-native distribution. |
| University Health Clinic Partnership | Canada and UK institutional procurement programs create volume anchors for certified reusable devices. |
| Thermoplastic Elastomer Product Line Extension | Precision molding advances capture price-sensitive European segments without sacrificing compliance. |
| State-Level Menstrual Equity Lobbying | US tax exemption and school distribution mandates reshape procurement channels toward subsidized access. |
Research Approach
Desk research of FDA 510(k) filings, Health Canada Medical Device Establishment Licensing records, and EU Medical Device Regulation notified body databases preceded structured interviews with regulatory affairs directors, university health clinic procurement officers, and silicone polymer processing engineers. Secondary validation drew from customs trade data, ISO certification registries, and institutional sustainability program disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing across material, channel, and end-user segmentation dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation layer. The analytical framework models reusable versus disposable product substitution dynamics, online versus pharmacy channel migration, and medical-grade silicone versus thermoplastic elastomer material shifts. CAGRs derive from fitted growth curves anchored to university procurement program expansion rates and state-level legislative adoption patterns. Forecast inputs include biocompatibility certification timeline distributions and direct-to-consumer customer acquisition cost trajectories.
Material uncertainties — regulatory reclassification, raw material supply disruptions, and cultural substitution resistance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding institutional procurement acceleration and digital channel penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Menopause Wellness Market
Personal Health
PTBCHA Market
Personal Health
Jet Lag Therapy Market
Personal Health
Health Coaching Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Sleep Mask Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Feminine Hygiene Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Hair Restoration Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Health Check-Up Market
Personal Health
Tick Repellent Market
Personal Health
Reusable Face Mask Market
Personal Health
Earwax Removal Products Market