
 Global Membrane Technology Market | 2026-2036
Global Membrane Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Membrane Technology Market Analysis
Software-defined membrane monitoring is recalibrating how filtration performance gets sold and serviced. DuPont Water Solutions leverages its hollow-fiber manufacturing depth to anchor premium reverse-osmosis contracts. Toray Industries, Inc. dominates seawater desalination through integrated module-to-system design.
Membrane technology encompasses selective-barrier materials—typically polymeric thin films, ceramic alumina, or composite layers with pore sizes from 0.1 micrometers down to sub-nanometer ranges—that separate substances based on size, charge, or solubility differences under applied pressure or concentration gradients. Reverse osmosis modules command the largest installed base for brackish and seawater desalination, while nanofiltration is gaining traction in pharmaceutical solvent recovery where divalent-ion rejection proves critical. Polymeric membranes occupy the volume leadership position due to lower capital cost, though ceramic alternatives are capturing margin pools in high-temperature food-processing applications where thermal sterilization cycles degrade polymer integrity.
The EPA's Clean Water Act enforcement and China's MEE zero-liquid-discharge directives are tightening effluent standards for industrial membrane buyers. REACH compliance in Europe and FDA validation requirements for pharmaceutical-grade filtration are raising barriers to module suppliers without certified material traceability. Stakeholders must weigh ceramic versus polymeric material bets against evolving thermal and chemical durability standards in their target end-use sectors.
Market Dynamics
Zero-liquid-discharge mandates in China's coal-to-chemical corridor are forcing membrane module suppliers to engineer ceramic-polymer hybrid systems capable of withstanding thermal sterilization cycles while meeting sub-ppm effluent standards.
Growth Catalysts
- EU Green Deal water reuse standards:Tightening discharge requirements across member states are compelling semiconductor fabs to deploy tertiary membrane filtration for process water recovery.
- Semiconductor fabrication wastewater reuse:Advanced nodes below 7nm require ultrapure water volumes that reverse osmosis and nanofiltration systems now reclaim at rates exceeding 80 percent.
- China's MEE zero-liquid-discharge directives:Coal-to-chemical clusters in Ningxia and Inner Mongolia must eliminate liquid effluent entirely, driving ceramic membrane installations for high-salinity brine concentration.
Market Restraints
- Polymer feedstock volatility:Polyethersulfone and polyamide resin prices fluctuate with benzene and propylene oxide markets, compressing module margins during energy price spikes.
- Ceramic sintering furnace concentration:High-temperature alumina membrane production concentrates in German and Japanese equipment bases, creating single-source vulnerability for food-grade sterilizable systems.
- REACH material traceability burden:ECHA compliance documentation for per- and polyfluoroalkyl substances in membrane coatings adds 12-18 months to European market entry timelines.
Strategic Opportunities
- India's pharmaceutical API manufacturing expansion:CDSCO and state pollution control mandates for solvent recovery create nanofiltration demand in Hyderabad and Ahmedabad bulk drug clusters.
- Software-defined membrane monitoring convergence:IoT sensor integration with predictive fouling algorithms enables performance-based service contracts displacing traditional capex module sales.
- Japan's METI hydrogen economy roadmap:Electrolyzer water purification specifications open ultrafiltration and reverse osmosis opportunities in Fukushima and Yamanashi green hydrogen pilot zones.
Industry Challenges
- Fouling prediction modeling talent scarcity:Computational fluid dynamics expertise for membrane-specific computational modeling concentrates in academic centers, not module vendors.
- FDA 510(k) validation timelines:Pharmaceutical-grade hollow-fiber bioreactor membranes face 24-36 month approval cycles for single-use system integration.
- Legacy DCS integration complexity:Brownfield chemical plants require custom protocol bridges to connect smart membrane skids to existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Membrane Technology Market |
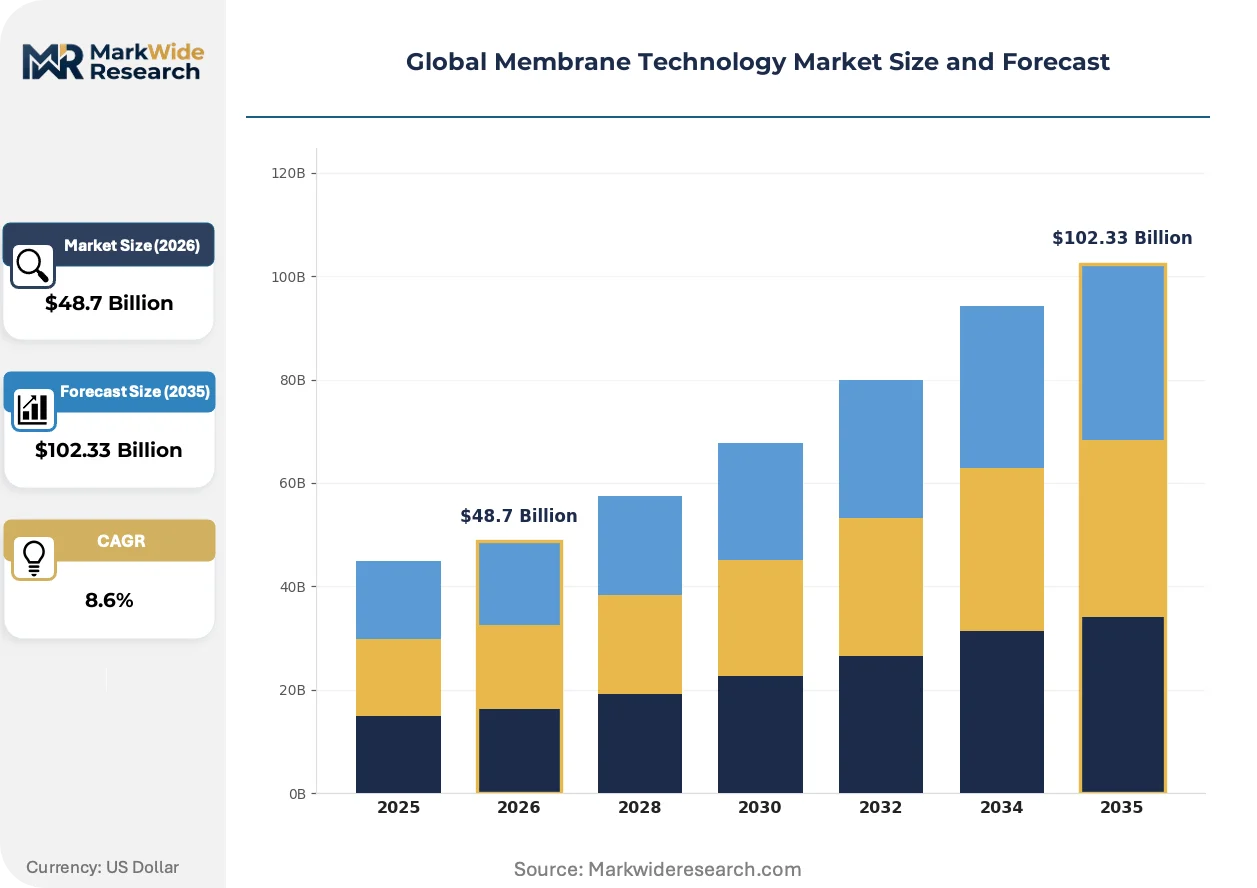
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Water Treatment, Food Processing, Pharmaceutical, Bioprocessing End User: Municipalities, Industrial Users, Residential Customers, Laboratories Membrane Material: Polymeric, Ceramic, Composite, Others |
| Companies Covered | DuPont Water Solutions, Toray Industries, Inc., Veolia Water Technologies & Solutions, Hydranautics (Nitto Denko Corporation), Kovalus Separation Solutions, Pall Corporation, Asahi Kasei Corporation, Pentair, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Membrane Technology Market Emerging Trajectories
Membrane technology is undergoing a platform shift from static barrier materials to adaptive, sensor-integrated systems where performance optimization occurs in real time rather than through scheduled maintenance cycles.
Thin-film composite membrane manufacturing is modularizing around localized electrodeposition and interfacial polymerization units that regional system integrators deploy near end-use sites rather than centralized DuPont or Toray production bases. Food processors in California's Central Valley and dairy cooperatives in the Netherlands now source customized spiral-wound modules from distributed coating facilities, compressing logistics costs and enabling rapid formulation pivots for temperature-specific applications. This geographic decentralization is modularizing the traditional membrane supply chain.
REACH authorization requirements for perfluorinated compounds in membrane manufacturing are forcing reformulation of hydrophobic coating chemistries across European supply chains. ECHA's 2023 restriction proposal on PFAS in industrial applications has triggered substitution programs for polytetrafluoroethylene membrane supports in Belgium and Netherlands water treatment facilities. Module suppliers are accelerating ceramic and polyethersulfone alternatives to maintain access to EU municipal desalination tenders.
Service unbundling is separating membrane module supply from performance guarantees in municipal water contracts. Australian utilities and Singapore's PUB now procure filtration capacity as measured output rather than installed equipment, transferring fouling risk to technology providers. This contractual inversion concentrates vendor selection on predictive maintenance capabilities rather than initial capex, favoring suppliers with embedded sensor networks and regional technical service density over low-cost module manufacturers.
Global Membrane Technology Market Segmentation
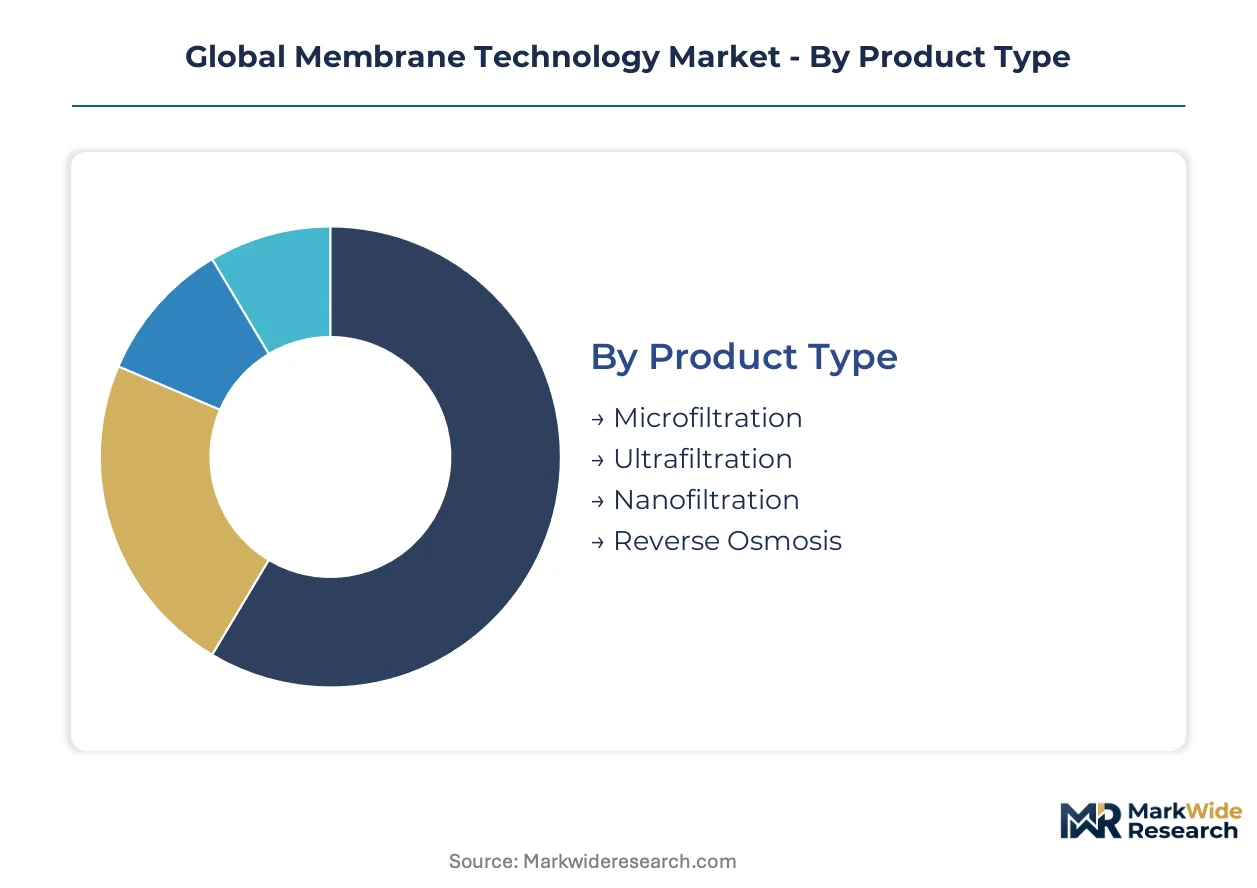
Membrane technology buyers segment sharply by technical performance requirements versus capital constraints. Material selection and pore-size precision determine competitive positioning across wastewater, pharmaceutical, and food-processing verticals.
Product Type:
Buyers in this category differentiate by contaminant size exclusion needs and operating pressure tolerance.
- Reverse Osmosis:Dense polyamide thin-film composites achieve sub-nanometer separation through applied pressures exceeding 15 bar. Semiconductor fabs in Taiwan and South Korea deploy multi-stage RO trains to generate ultrapure water for sub-7nm lithography nodes.
- Nanofiltration:Looser polymeric matrices target divalent ion and small organic rejection at 5-20 bar operating pressure. Pharmaceutical solvent recovery operations in Hyderabad and Ahmedabad specify nanofiltration modules for API manufacturing effluent treatment under CDSCO mandates.
- Ultrafiltration:Porous membranes with 1-100 nanometer cutoff ranges concentrate proteins and remove colloids.
- Microfiltration:0.1-10 micrometer pore structures intercept bacteria and suspended solids in dairy and beverage clarification.
Reverse osmosis leads volumes today; nanofiltration is gaining share fastest.
Application:
End-use sectors impose divergent regulatory validation burdens and thermal durability specifications.
- Water Treatment:Municipal desalination and industrial wastewater reuse dominate installed capacity. Singapore's PUB and Australian utilities now procure membrane capacity as measured output rather than equipment, shifting vendor selection toward predictive maintenance capabilities.
- Pharmaceutical:FDA 510(k) validation and EMA GMP compliance mandate material traceability and sterilization protocol documentation. Single-use hollow-fiber bioreactor membranes face 24-36 month approval cycles for system integration.
- Food Processing:Thermal sterilization cycles in dairy and beverage applications drive ceramic membrane adoption where polymer integrity degrades.
- Bioprocessing:Cell harvest and protein concentration steps require hydrophilic low-fouling surface chemistries.
Water treatment commands the largest installed base; pharmaceutical applications show the steepest expansion trajectory.
End User:
Procurement sophistication and contract structure vary dramatically across customer types.
- Industrial Users:Chemical, power, and electronics manufacturers specify zero-liquid-discharge compliance. Coal-to-chemical plants in China's Ningxia and Inner Mongolia corridors must eliminate liquid effluent entirely under MEE directives.
- Municipalities:Public utilities prioritize lifecycle cost and local service density. EU Green Deal water reuse standards are tightening discharge requirements across member states for municipal tertiary filtration.
- Laboratories:Research and analytical applications demand small-batch modularity and rapid membrane replacement protocols.
- Residential Customers:Point-of-use and point-of-entry systems compete on replacement cartridge convenience and energy consumption.
Industrial users generate the highest revenue per installation; municipalities represent the largest unit volume opportunity.
Membrane Material:
Material selection trades capital cost against chemical and thermal durability requirements.
- Polymeric:Polyethersulfone, polyamide, and cellulose acetate formulations dominate unit economics. Feedstock volatility in benzene and propylene oxide markets compresses module margins during energy price spikes.
- Ceramic:Alumina and zirconia sintered structures withstand thermal sterilization and aggressive chemical cleaning. High-temperature furnace concentration in German and Japanese equipment bases creates single-source vulnerability for food-grade systems.
- Composite:Thin-film polyamide on polysulfone supports optimize flux and rejection in reverse osmosis and nanofiltration.
- Others:Metallic and carbon-based membranes serve niche high-temperature or corrosive applications.
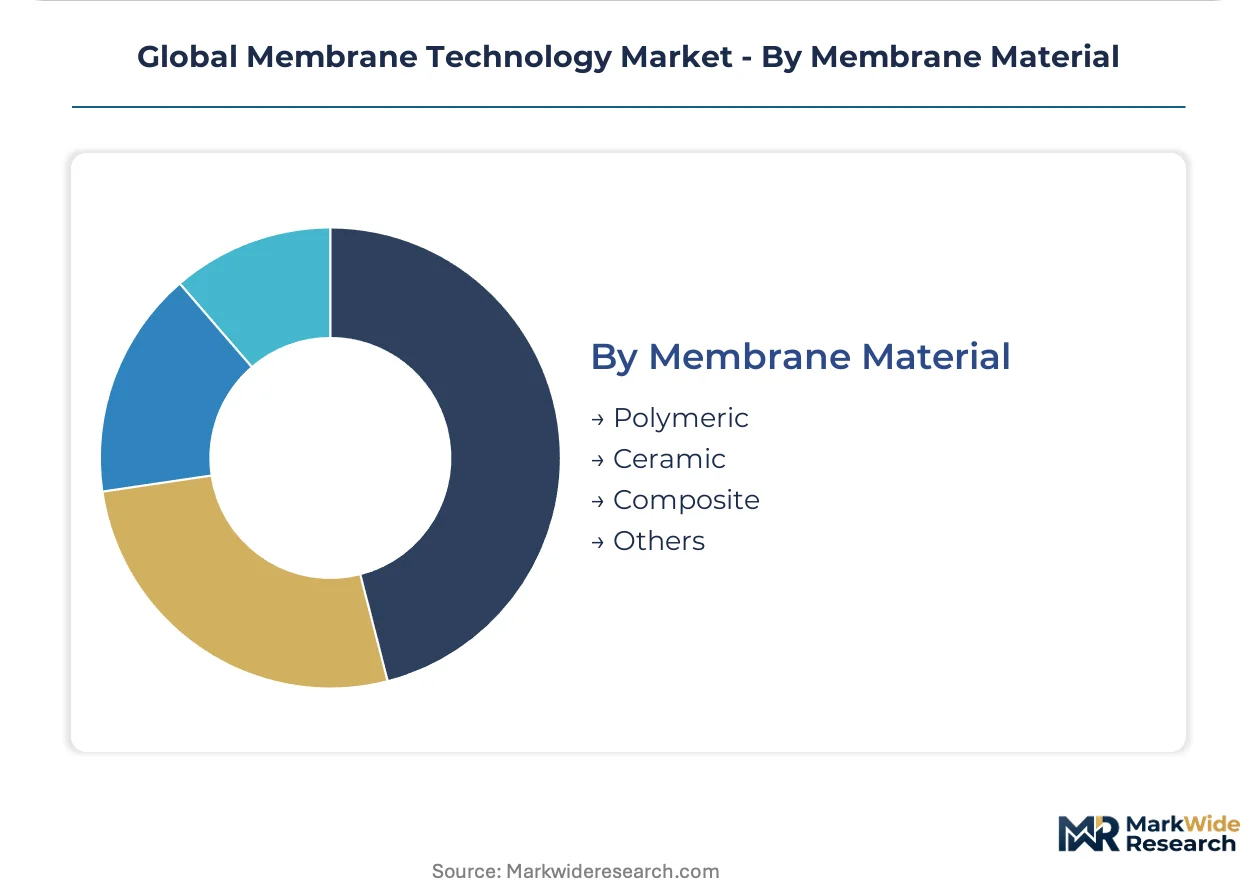
Polymeric membranes lead volumes today; ceramic alternatives are climbing the fastest in high-value sterilizable applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's zero-liquid-discharge mandates are accelerating ceramic membrane deployment faster than the United States' EPA enforcement patterns, creating divergent procurement timelines across the two largest industrial water treatment markets.
China
Coal-to-chemical clusters in Ningxia and Inner Mongolia drive ceramic membrane demand for high-salinity brine concentration. MEE directives require complete liquid effluent elimination from these facilities. Installations concentrate in the Ningxia energy base where membrane suppliers engineer hybrid ceramic-polymer systems.
United States
Semiconductor fabs in Arizona and Texas deploy multi-stage reverse osmosis trains for sub-7nm lithography ultrapure water. EPA Clean Water Act enforcement tightens effluent standards for industrial buyers. Phoenix and Austin corridors host the densest concentration of tertiary membrane filtration for process water recovery.
Germany
Food processors in Bavaria and dairy cooperatives source customized spiral-wound modules from distributed coating facilities. REACH authorization requirements for perfluorinated compounds force reformulation of hydrophobic coating chemistries. Ceramic sintering furnace concentration in southern equipment bases creates single-source vulnerability for sterilizable systems.
Japan
Electrolyzer water purification specifications under METI's hydrogen economy roadmap open ultrafiltration opportunities in Fukushima and Yamanashi green hydrogen pilot zones. Seawater desalination module production anchors integrated module-to-system design capabilities. Osaka-based manufacturers dominate high-rejection membrane exports.
Singapore
PUB procurement now contracts filtration capacity as measured output rather than installed equipment. Municipal utilities transfer fouling risk to technology providers through performance-based service contracts. Predictive maintenance capabilities determine vendor selection over initial capital expenditure.
Global Membrane Technology Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hollow-fiber and thin-film composite producers commanding premium positions in desalination while regional system integrators capture service revenue. The vendor base organizes into three tiers: integrated material-to-module manufacturers, specialty coating houses, and distributed system assemblers. Consolidation pressure concentrates among ceramic furnace operators and polymeric resin compounders. Competitive moves center on backward integration into polymer feedstock and predictive algorithm licensing for fouling management.
Within the integrated material-to-module tier, DuPont Water Solutions and Toray Industries, Inc. occupy positions that exemplify divergent geographic anchoring strategies. DuPont leverages hollow-fiber manufacturing depth to secure premium reverse-osmosis contracts across semiconductor and municipal verticals. Toray anchors seawater desalination through integrated module-to-system design capabilities concentrated in Japanese production bases. Veolia Water Technologies & Solutions represents the service-unbundling archetype where performance guarantees displace traditional equipment sales in Australian and Singaporean utility contracts.
| Leading Market Players |
|---|
| DuPont Water Solutions |
| Toray Industries, Inc. |
| Veolia Water Technologies & Solutions |
| Hydranautics (Nitto Denko Corporation) |
| Kovalus Separation Solutions |
| Pall Corporation |
| Asahi Kasei Corporation |
| Pentair |
| 3M |
| Others |
Supply Flow & Price Mechanics
Polyethersulfone resin costs trace from benzene and propylene oxide feedstock markets through polymeric membrane module pricing tiers, with ceramic alternatives commanding premium positioning where thermal sterilization cycles degrade polymer integrity.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade polymeric modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical membranes from municipal desalination units and point-of-use residential cartridges. Cost compression in standard polymeric tiers is intensifying because feedstock volatility compresses module margins during energy price spikes. Municipal utilities show highest price sensitivity due to lifecycle cost procurement mandates, while semiconductor fabs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight cost spikes from German and Japanese ceramic sintering furnace bases to food-processing customers in the Netherlands and California compress margins for sterilizable membrane systems. Polymeric membrane production draws from China, the United States, and Japan; ceramic manufacturing rests on German and Japanese equipment bases. Raw material dependencies span polyethersulfone resins, alumina powders, and polyamide thin-film composites. Single-source vulnerability concentrates in high-temperature furnace capacity for food-grade ceramic systems. Distribution runs through regional system integrators and direct municipal utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane technology margins expand through predictive fouling algorithm licensing displacing traditional capex module sales, with service-unbundling contracts transferring fouling risk to technology providers.
For Market Incumbents: Deploy backward integration into polymer feedstock to defend against resin price volatility compressing module margins. Ceramic-polymer hybrid system engineering for China's zero-liquid-discharge mandates protects market position in coal-to-chemical corridors. Certification investment for REACH PFAS compliance maintains EU municipal desalination tender access against reformulating competitors. For New Entrants and Emerging Players: India's pharmaceutical API manufacturing clusters in Hyderabad and Ahmedabad present white-space targets for nanofiltration solvent recovery systems under CDSCO mandates. Japan's METI hydrogen economy pilot zones in Fukushima and Yamanashi offer electrolyzer water purification entry points with lower incumbent density. Software-defined membrane monitoring partnerships with IoT sensor providers enable performance-based service contracts without captive manufacturing assets. For Investors and Strategic Acquirers: Consolidation pressure builds where ceramic sintering furnace concentration creates single-source vulnerability for food-grade sterilizable systems. Long-term viability centers on predictive maintenance capabilities determining vendor selection in Australian and Singaporean utility contracts. Acquisition targets include regional coating houses with distributed manufacturing footprints and embedded sensor network capabilities. Watch for ECHA PFAS restriction enforcement as inflection indicator accelerating ceramic substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Polymer Hybrid System Development | Engineered systems for China's MEE zero-liquid-discharge mandates in Ningxia and Inner Mongolia coal-to-chemical plants. |
| Backward Integration into Polymer Feedstock | Captive polyethersulfone and polyamide resin supply shields margins from benzene and propylene oxide volatility. |
| Predictive Fouling Algorithm Licensing | IoT sensor-integrated software enables performance-based service contracts displacing traditional capex module sales. |
| REACH PFAS Compliance Certification | ECHA material traceability documentation maintains EU municipal desalination tender access against reformulating competitors. |
| Distributed Coating Facility Expansion | Localized thin-film composite manufacturing near California Central Valley and Netherlands dairy processors compresses logistics costs. |
Methodological Framework
Multiple input streams — primary interviews with membrane module procurement managers, plant engineers at coal-to-chemical facilities, and regulatory compliance officers; secondary validation through EPA enforcement records, ECHA restriction proposals, and MEE directive documentation; plus customs trade data and SEC filings from listed materials suppliers — were reconciled through bottom-up installation tracking and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon applied segmentation modeling by membrane material type, pore-size precision tier, end-use vertical, and geographic regulatory cluster. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated zero-liquid-discharge mandate enforcement timelines in China, EU Green Deal water reuse standard adoption curves, and semiconductor node migration patterns driving ultrapure water demand.
Underlying measurement precision varies by segment; pharmaceutical FDA-validation timelines and ceramic furnace capacity constraints carry tighter precision than residential point-of-use adoption assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock price normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Nafion Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Liquid Roofing Market