
 Membrane Air Dryers Market | 2026-2036
Membrane Air Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Air Dryers Market Intelligence
Multi-source procurement for membrane elements is restructuring supply relationships across the compressed-air treatment sector. Atlas Copco leverages captive production of desiccant cartridges and membrane bundles to control lead times for integrated compressor-dryer packages. Parker Hannifin Corporation anchors its position through deep distribution in North American industrial automation channels, while SMC Corporation dominates pneumatic component bundling in Japanese and Southeast Asian factory-equipment markets.
Membrane air dryers are pressure-driven separation devices that strip water vapor from compressed air streams using selective permeation through hollow-fiber or flat-sheet polymer barriers, typically achieving pressure dew points between -20°C and -40°C for instrument-grade air. Their primary purpose is protecting pneumatic controls, analytical instruments, and electronics manufacturing equipment from corrosion and contamination caused by moisture in compressed air systems. Compact and modular product types lead current volume shipments due to space constraints in retrofitted plant floors and mobile service rigs, while high-capacity industrial units capture disproportionate margin pools in natural gas processing and large-scale packaging lines. Hollow-fiber polymeric membranes represent the dominant technology platform, though composite membranes with engineered surface layers are gaining traction in semiconductor fabs demanding sub-ppb moisture levels.
ISO 8573-1 air quality classes and OSHA compressed-air safety standards shape product certification requirements and market access thresholds in the United States, while REACH and the EU F-Gas Regulation drive substitution away from refrigerated dryers toward membrane-based alternatives in European manufacturing. FDA compliance for food-contact compressed air and EPA emissions rules for natural gas dehydration further segment regulatory compliance burdens by end-use. Stakeholders must monitor evolving dew-point specifications from semiconductor equipment OEMs and assess backward-integration risks as compressor manufacturers deepen captive membrane production.
Market Dynamics
Semiconductor capital intensity is compressing specification cycles for membrane air dryers, as fabs demand sub-ppb moisture thresholds that hollow-fiber manufacturers must now engineer into standard product lines rather than custom builds.
Growth Catalysts
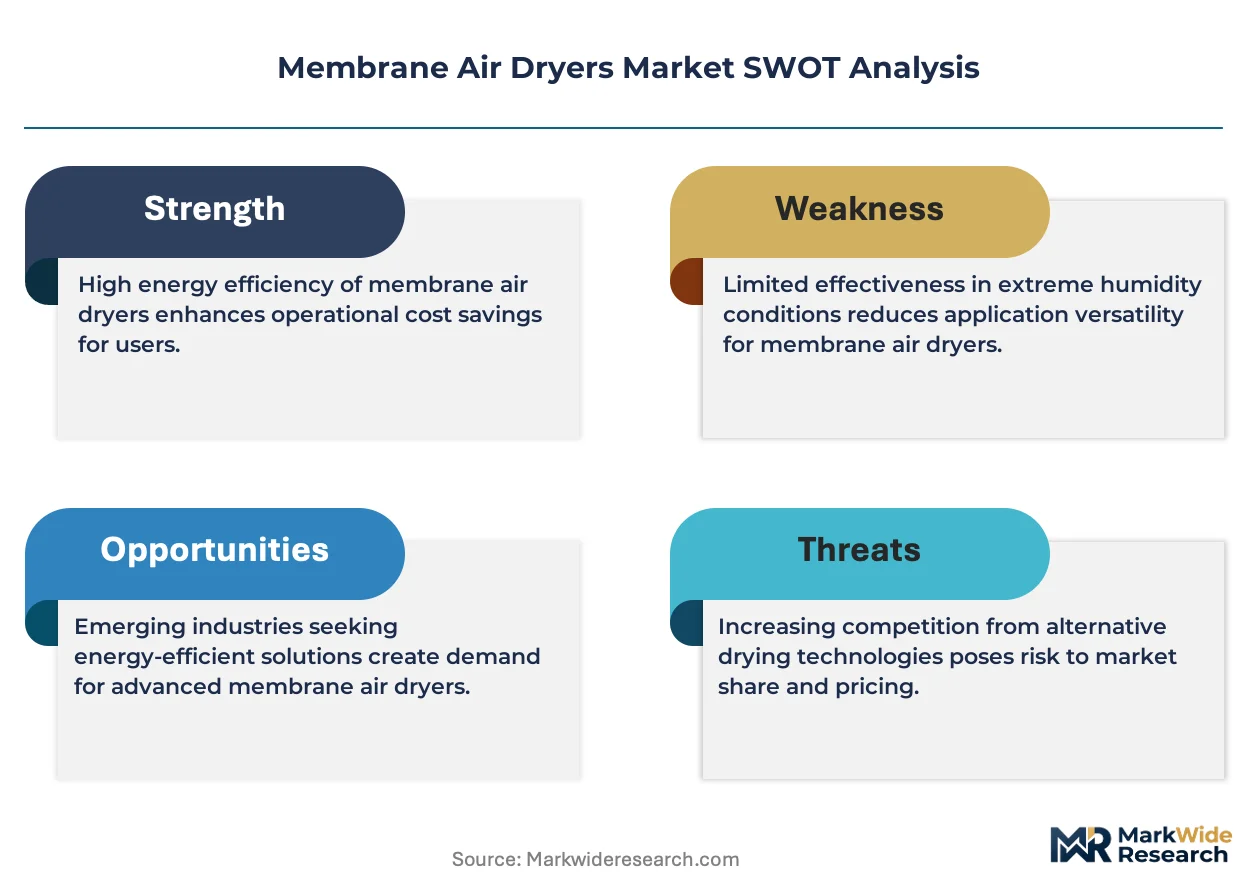
- EU F-Gas Regulation:Phase-down of high-GWP refrigerants in compressed-air treatment is redirecting industrial buyers toward membrane-based dehydration systems for instrument air applications.
- Lithography tool OEMs:Extreme ultraviolet lithography systems require pressure dew points below -70°C, creating specification pull-through for advanced composite membrane bundles in front-end semiconductor fabs.
- Polyimide hollow-fiber advances:Improved selectivity ratios in asymmetric membrane structures are extending service intervals and reducing purge-air losses in continuous-duty manufacturing environments.
Market Restraints
- Polymer resin supply concentration:Specialty polyimide and polysulfone precursor production clusters in Japan and Germany, exposing membrane manufacturers to feedstock bottlenecks and extended lead times.
- Performance ceiling versus desiccant:Membrane systems cannot achieve the -100°C pressure dew points required for certain cryogenic and aerospace applications, capping addressable market scope.
- REACH registration burdens:Novel fluoropolymer surface treatments face extended ECHA evaluation timelines, delaying commercialization of next-generation moisture-selective barriers.
Strategic Opportunities
- Biopharma cleanroom expansion:Aseptic filling lines and isolator technologies in India and South Korea are adopting membrane air dryers for ISO 8573-1 Class 1 instrument air without oil contamination risks.
- Natural gas dehydration:EPA methane emissions rules and pipeline moisture specifications are opening mid-scale field gas processing to modular membrane skids as alternatives to glycol contactors.
- Digital twin integration:Convergence of membrane performance sensors with predictive analytics platforms enables condition-based maintenance contracts and remote dew-point optimization.
Industry Challenges
- Membrane module replacement forecasting:Variable inlet air quality and operating pressure complicate predictive algorithms for hollow-fiber end-of-life, frustrating maintenance scheduling in multi-site industrial fleets.
- ISO 8573-1 Class 0 certification timelines:Third-party validation of oil-free and moisture-compliant air streams requires extended testing protocols that delay product launches and customer qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Air Dryers Market |
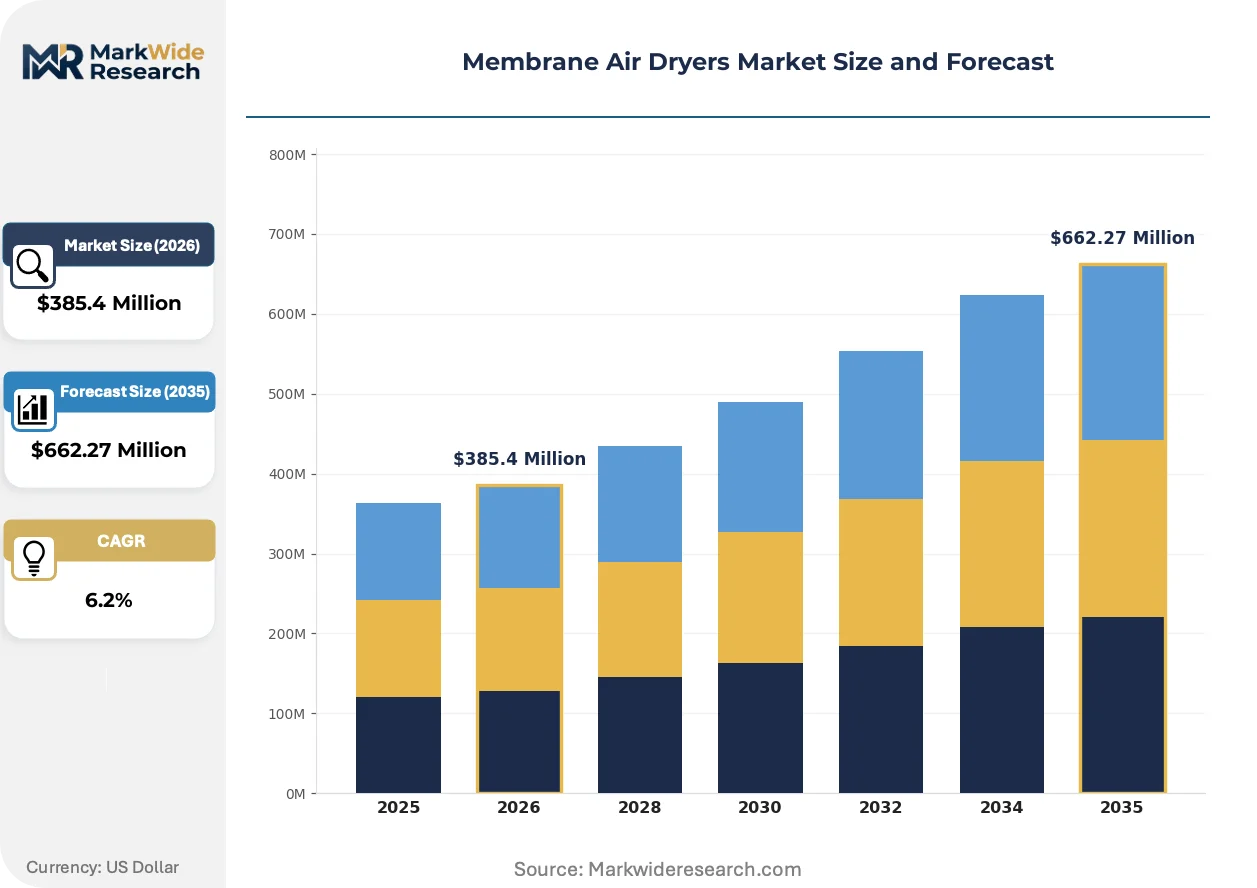
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Modular, Portable, Bench-top, Industrial, High-Capacity Technology: Polymeric Membranes, Ceramic Membranes, Hollow Fiber, Spiral Wound, Flat Sheet, Composite Membranes Application: Pneumatic Systems, Instrument Air, Natural Gas Processing, Food & Beverage, Packaging, Electronics Manufacturing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Food Processing Firms, Semiconductor Manufacturers |
| Companies Covered | Atlas Copco, Parker Hannifin Corporation, Donaldson Company, SMC Corporation, Ingersoll Rand, Pentair, SPX Flow, Mikropor, Kaeser Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Air Dryers Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are jointly redefining membrane air dryer architectures, with performance specifications now set by semiconductor equipment OEMs rather than compressed-air industry standards.
Composite membranes with engineered surface-selective layers are unifying the previously separate functions of particulate filtration and moisture removal into single-stage hollow-fiber bundles. ASML and Nikon lithography tool manufacturers specify these integrated elements for their wafer-handling pneumatic subsystems. This unification is compressing supplier tier structures as membrane manufacturers assume filtration media responsibilities previously held by discrete filter OEMs.
REACH authorization requirements for per- and polyfluoroalkyl substances are accelerating substitution programs for PTFE-based membrane substrates across European pharmaceutical and food packaging lines. ECHA's restriction roadmap is forcing membrane producers to validate polyetherimide and sulfonated polysulfone alternatives that match fluoropolymer selectivity without persistent organic pollutant classification. German and French compressed-air system integrators now prioritize non-fluorinated membrane certificates in their vendor qualification scorecards.
Specification authority has migrated from plant engineering departments to semiconductor equipment OEMs, who embed membrane air dryer performance requirements directly into tool purchase agreements. Equipment procurement teams at fabs in Taiwan and Arizona now accept only pre-qualified membrane suppliers named in lithography system documentation. This concentration of buying influence is marginalizing independent distributor channels and compressing price negotiation leverage for end-user facilities.
Membrane Air Dryers Market Segmentation
Segmentation in membrane air dryers reveals how specification authority has migrated from plant engineering to equipment OEMs. Buyers now select based on embedded tool requirements rather than standalone compressed-air standards.
Product Type:
Space constraints and retrofit complexity drive buyer decisions across product formats.
- Compact:These units integrate directly into point-of-use pneumatic circuits with minimal footprint. Electronics manufacturing clusters in Taiwan and Arizona specify compact formats for lithography tool integration where floor space commands premium valuations.
- Modular:Stackable configurations allow capacity expansion without system replacement. German automotive Tier-1 suppliers favor modular architectures for flexible production lines that reconfigure between model generations.
- Portable:Service rigs and mobile maintenance operations deploy these for field compressed-air treatment.
- Bench-top:Laboratory and analytical instrument applications specify these for controlled environment validation.
- Industrial:Continuous-duty manufacturing lines in natural gas processing and packaging rely on these for baseline dehydration capacity.
- High-Capacity:Pipeline-scale dehydration and large fab central air systems require these for bulk moisture removal upstream of precision polishing stages.
Volume sits with Industrial; growth tilts toward Compact.
Technology:
Material selectivity ratios determine replacement intervals and purge-air economics.
- Hollow Fiber:Asymmetric polymeric structures achieve pressure dew points between -20°C and -40°C through selective permeation. Japanese and German precursor supply concentration shapes cost structures for this dominant platform.
- Composite Membranes:Engineered surface layers unify particulate filtration with moisture removal. ASML and Nikon lithography specifications now mandate these for sub-ppb moisture thresholds in EUV wafer-handling systems.
- Polymeric Membranes:Standard polyimide and polysulfone substrates serve general instrument air applications.
- Ceramic Membranes:Thermal stability advantages position these for high-temperature process gas applications.
- Spiral Wound:Flat-sheet membrane configurations in spiral geometry suit lower-pressure feed streams.
- Flat Sheet:Planar membrane geometries enable custom module configurations for specialized industrial processes.
Commercial gravity centers on Hollow Fiber; specification pull concentrates in Composite Membranes.
Application:
Moisture sensitivity of downstream equipment sets dew-point requirements and certification burdens.
- Electronics Manufacturing:Front-end semiconductor fabs require sub-ppb moisture levels for EUV lithography and wafer transport. Taiwan Semiconductor Manufacturing and Intel Arizona facilities drive specification cycles through direct tool-embedded procurement.
- Natural Gas Processing:EPA methane emissions rules and pipeline moisture specifications redirect mid-scale field processing toward membrane skids. Texas and North Dakota shale plays deploy modular units as glycol contactor alternatives.
- Pneumatic Systems:General industrial automation relies on these for corrosion protection of control valves and actuators.
- Instrument Air:Analytical and laboratory equipment requires ISO 8573-1 compliant streams without oil contamination.
- Food & Beverage:FDA-compliant compressed air for packaging and processing lines specifies oil-free membrane alternatives.
- Packaging:High-speed filling lines use dried air for pneumatic actuation and product protection.
Revenue pools concentrate in Electronics Manufacturing; expansion rates peak in Natural Gas Processing.
End User:
Procurement authority fragmentation determines channel strategy and pricing leverage.
- Semiconductor Manufacturers:Direct fab engineering teams negotiate pre-qualified supplier lists embedded in lithography tool purchase agreements. TSMC, Samsung Austin, and Intel Arizona procurement specifications now override independent distributor channels.
- OEMs:Compressor and pneumatic system manufacturers integrate membrane bundles into packaged offerings. Atlas Copco captive production controls lead times for integrated compressor-dryer configurations.
- Tier-1 Suppliers:Automotive and industrial automation component suppliers specify membrane dryers for subassembly testing and production equipment.
- Aftermarket Providers:Replacement module sales and service contracts capture recurring revenue in installed base maintenance.
- Vehicle Assemblers:Paint shop and assembly line pneumatic systems require instrument-grade air for quality-critical operations.
- Food Processing Firms:Aseptic packaging and processing lines specify FDA-compliant membrane systems for product-contact air streams.
Contract value aggregates with Semiconductor Manufacturers; aftermarket volume scales with OEM installed base expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty polyimide and polysulfone precursor production clusters in Japan and Germany anchor membrane manufacturing economics, while precision manufacturing demand concentrates in semiconductor fabrication corridors across Taiwan, Arizona, and Bavaria.
United States
Extreme ultraviolet lithography installations at Intel Arizona and TSMC Phoenix drive sub-ppb moisture specifications for instrument air systems. EPA methane emissions rules redirect Texas and North Dakota shale plays toward modular membrane skids as glycol dehydration alternatives. Austin and Phoenix metropolitan areas concentrate semiconductor capital equipment procurement teams who pre-qualify membrane suppliers for fab construction.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich specify modular membrane architectures for flexible production lines. REACH authorization timelines for fluoropolymer surface treatments delay next-generation moisture-selective barrier commercialization. Bavaria and Baden-Württemberg host compressed-air system integrators who prioritize non-fluorinated membrane certificates in vendor scorecards.
Japan
ASML and Nikon lithography tool specifications emanating from Yokohama and Kyoto engineering centers mandate composite membrane bundles for wafer-handling systems. METI industrial technology roadmaps support hollow-fiber selectivity ratio improvements. Chubu and Kansai regions concentrate pneumatic component bundling for Southeast Asian factory equipment markets.
Taiwan
TSMC Hsinchu and Taichung facilities embed pre-qualified membrane supplier lists directly into lithography tool purchase agreements. ISO 8573-1 Class 0 certification requirements compress third-party validation timelines for oil-free air streams. The Hsinchu Science Park anchors front-end fab concentration where procurement specifications override independent distributor channels.
South Korea
Samsung Austin and domestic Pyeongtaek fabs drive specification cycles through direct tool-embedded procurement. Biopharma cleanroom expansion in Incheon and Songdo adopts membrane dryers for aseptic filling lines. The Seoul Capital Area concentrates both semiconductor equipment OEM engineering and pharmaceutical manufacturing investment.
Membrane Air Dryers Market Key Industry Players
Global majors compete with regional champions across distribution depth and captive membrane production integration. The vendor base separates into three tiers: integrated compressor manufacturers with captive membrane supply, specialized pneumatic component bundlers, and independent membrane module specialists. Strategic moves concentrate on backward integration into hollow-fiber precursor supply and predictive maintenance platform development.
Among diversified industrial conglomerates, Atlas Copco exemplifies the integrated-architecture archetype through captive desiccant and membrane bundle production. Parker Hannifin Corporation occupies a position anchoring North American industrial automation channel density. SMC Corporation represents the pneumatic-component-bundling specialist model dominant in Japanese and Southeast Asian factory equipment markets.
| Leading Market Players |
|---|
| Atlas Copco |
| Parker Hannifin Corporation |
| Donaldson Company |
| SMC Corporation |
| Ingersoll Rand |
| Pentair |
| SPX Flow |
| Mikropor |
| Kaeser Kompressoren |
| Others |
Cost & Logistics Intelligence
Composite membrane manufacturing with engineered surface-selective layers is compressing cost structures for sub-ppb moisture specifications while simultaneously concentrating supply relationships around ASML and Nikon qualified supplier lists. This dual transformation reshapes pricing power toward equipment OEMs and away from standalone compressed-air system vendors.
Pricing Analysis
Warranty bundling separates premium membrane suppliers from economy-tier competitors, with extended service contracts and predictive maintenance platforms commanding 15-25% price premiums over transactional module sales. Price differentiation rests on ISO 8573-1 Class 0 certification status and REACH-compliant non-fluorinated material validation, particularly for European pharmaceutical and food packaging buyers. Pricing pressure intensifies in standard hollow-fiber segments as captive production at Atlas Copco and Ingersoll Rand compresses margins for independent module specialists. Semiconductor manufacturers exhibit lowest price sensitivity due to tool-embedded procurement specifications, while general industrial pneumatic users retain highest elasticity.
Supply Chain Analysis
Domestic-content requirements in South Korea and India's PLI-linked manufacturing incentives are reshaping sourcing patterns for membrane module assembly, pressuring Japanese and German precursor suppliers to establish local compounding facilities. Polyimide and polysulfone resin production concentrates in Japan, Germany, and the United States, drawing from specialty chemical feedstocks with limited qualified alternative sources. Single-source vulnerability runs through ASML-qualified composite membrane suppliers for EUV lithography tool integration. Distribution runs through direct OEM procurement channels for semiconductor applications and industrial automation distributors for general pneumatic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The membrane air dryer sector is transitioning from commodity compressed-air treatment toward precision gas separation, with composite membrane technology displacing standard hollow-fiber architectures in high-specification applications.
For Market Incumbents: Lock in lithography tool OEM qualification status through joint development agreements with ASML and Nikon engineering centers, while accelerating backward integration into polyimide precursor supply to mitigate Japanese resin concentration risk. Prioritize predictive maintenance platform deployment to capture recurring service revenue and defend against compressor manufacturer captive bundle competition. For New Entrants and Emerging Players: Enter via natural gas dehydration modular skid supply for Texas and North Dakota shale plays, where EPA methane rules are displacing glycol contactors and incumbent membrane suppliers maintain limited field service presence. Target biopharma cleanroom expansion in India and South Korea with FDA-compliant membrane configurations, leveraging local manufacturing incentives to bypass established distribution channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated compressor manufacturers seeking membrane technology capabilities, with private equity roll-up opportunities in regional aftermarket service providers. Five-to-ten year viability favors suppliers with demonstrated EUV lithography qualification and REACH-compliant material portfolios. Watch for ECHA fluoropolymer restriction finalization as inflection signal for non-fluorinated membrane substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive polyimide resin production reduces exposure to Japanese supply concentration and extends margin capture. |
| EUV Lithography Qualification Partnership | ASML and Nikon supplier certification locks in semiconductor fab procurement specifications for tool-embedded membrane bundles. |
| Predictive Maintenance Platform Launch | Sensor-enabled condition monitoring enables recurring service contracts and remote dew-point optimization for multi-site industrial fleets. |
| REACH-Compliant Material Substitution | Polyetherimide and sulfonated polysulfone validation secures European pharmaceutical and food packaging market access against fluoropolymer restrictions. |
| Natural Gas Dehydration Skid Deployment | Modular membrane systems capture EPA methane compliance-driven substitution from glycol contactors in mid-scale field processing. |
Research Approach
Multi-period observation of semiconductor capital equipment procurement cycles, REACH regulatory filing timelines, and hollow-fiber membrane replacement intervals anchored the trend analysis, supplemented by interviews with fab engineering directors, compressed-air system integrators, and aftermarket service managers. Secondary validation drew from SEC filings of integrated compressor manufacturers, ECHA substance registration databases, and ISO 8573-1 certification body records. Bottom-up segment sizing triangulated against top-down macro indicators including pneumatic equipment production indices and natural gas processing capacity additions.
Segment-weighting across product type, technology platform, application moisture specification, and end-user procurement authority shaped the analytical framework. CAGRs were derived from elasticity-adjusted demand projections and replacement cycle dynamics throughout the forecast period. Industry-specific inputs included lithography tool OEM specification roadmaps, EPA methane emissions rule implementation schedules, and biopharma cleanroom construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended REACH evaluation timelines for novel fluoropolymer alternatives and semiconductor capital expenditure volatility. Forecasts reflect documented assumptions regarding membrane selectivity improvement trajectories and regulatory chemistry restriction scope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market