
 Lyophilization Services Market | 2026-2036
Lyophilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Lyophilization Services Market Analytics
cGMP qualification cycles for aseptic processing is unwinding the competitive landscape for lyophilization service providers. Thermo Fisher Scientific Inc. leverages its integrated CDMO footprint to capture multi-site pharmaceutical contracts. GEA Group anchors European freeze-drying equipment and service demand through its process technology leadership. Millrock Technology Inc. specializes in pilot-scale lyophilization systems that bridge clinical and commercial manufacturing transitions.
Lyophilization services encompass controlled sublimation of frozen aqueous formulations under vacuum to preserve biological activity and extend shelf life, typically operating at shelf temperatures between -40°C and +40°C with chamber pressures below 200 millitorr. Contract lyophilization now captures the largest value share as pharmaceutical developers outsource capital-intensive freeze-drying operations. Batch lyophilization retains dominant installed capacity, though continuous lyophilization is gaining traction for high-volume vaccine production where throughput economics favor integrated process lines.
FDA cGMP regulations and EMA Annex 1 guidance on sterile manufacturing constrain which service providers qualify for commercial biologics production, effectively raising barriers to market entry. ISO 14644 cleanroom classifications and EU GMP Chapter 3 requirements further dictate facility investment thresholds for lyophilization suites. Stakeholders must weigh capacity expansion timing against evolving regulatory expectations for real-time release testing and process analytical technology integration in freeze-drying operations.
Market Dynamics
Biologics manufacturers now outsource freeze-drying operations to avoid capital expenditure on cGMP-qualified lyophilization suites, tightening FDA and EMA compliance timelines for parenteral formulations.
Growth Catalysts
- mRNA vaccine production:Cold-chain-independent stabilization requirements for lipid nanoparticle formulations pull contract lyophilization demand from developers in Germany, the United States, and Japan.
- EMA Annex 1 revisions:Stricter sterile manufacturing guidance forces biologics sponsors toward qualified CDMO partners with validated aseptic processing capabilities.
- Continuous freeze-drying:Integrated process lines for high-volume vaccine output compress batch cycle times and improve throughput economics for pandemic preparedness stockpiles.
Market Restraints
- Stainless steel equipment lead times:Chamber and shelf fabrication from specialized European foundries now extends 18-24 months, constraining capacity expansion velocity.
- Qualified personnel scarcity:cGMP aseptic processing certification requirements limit the available talent pool for lyophilization suite operations in concentrated biopharma clusters.
- Real-time release testing validation:FDA process analytical technology mandates require substantial upfront investment in spectroscopic and calorimetric sensors, elevating facility qualification thresholds.
Strategic Opportunities
- India CDMO expansion:CDSCO regulatory alignment with ICH Q5A guidelines creates white space for Western-qualified Indian manufacturers to capture biologics outsourcing from cost-sensitive sponsors.
- Cell and gene therapy:Viral vector and CAR-T product stabilization requirements extend lyophilization service demand into advanced therapy medicinal products with limited cold-chain tolerance.
- ISO 14644-1 Class 5 suites:Cleanroom infrastructure gaps in secondary biopharma markets enable first-mover facility investments in Switzerland, Singapore, and South Korea.
Industry Challenges
- Scale-up validation gaps:Cycle transfer from pilot to commercial lyophilizers demands extensive design-of-experiment work, delaying product launches and consuming technical resources.
- Legacy equipment integration:Brownfield sites struggle to retrofit 1990s-era freeze-dryers with modern process analytical technology sensors without chamber requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lyophilization Services Market |
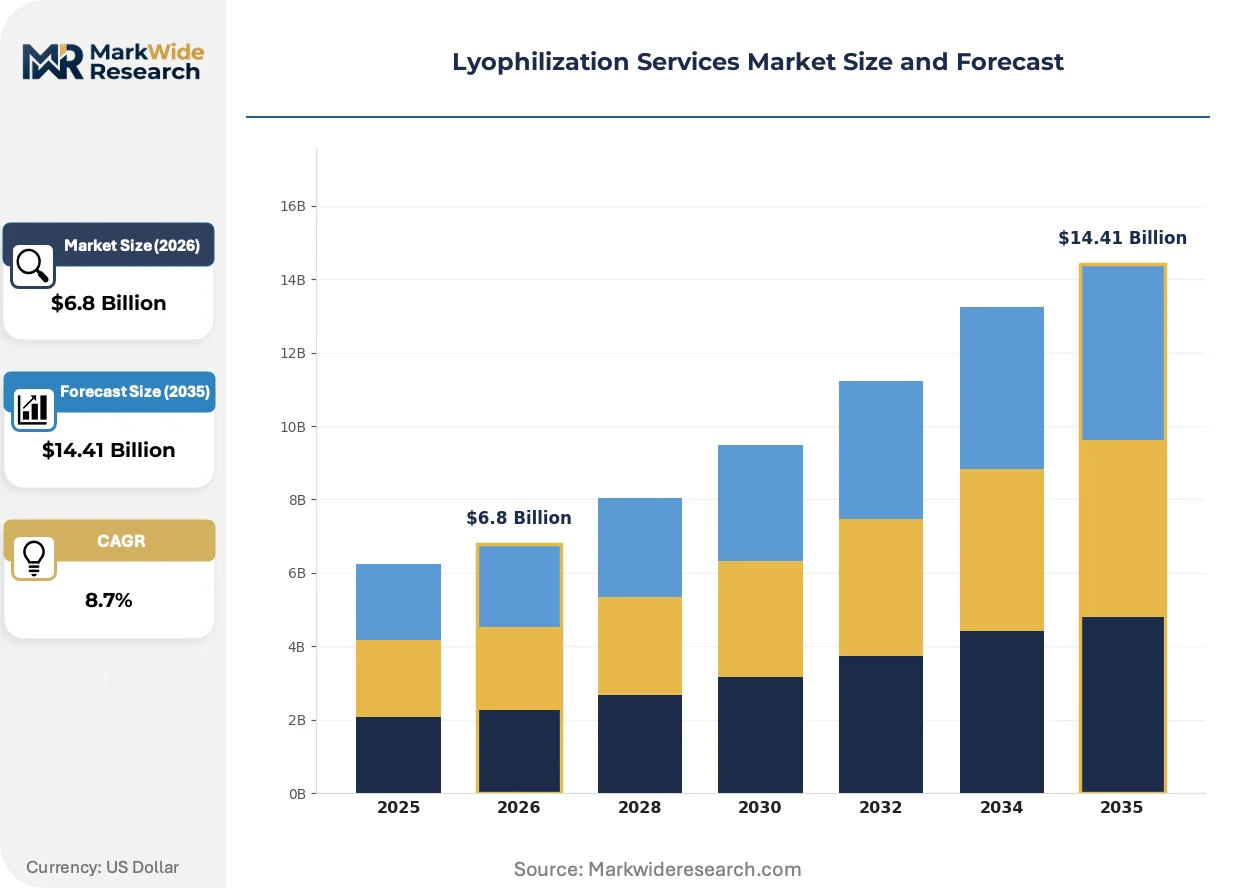
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Batch Lyophilization, Continuous Lyophilization, Contract Lyophilization, Customized Lyophilization End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Laboratories Product Type: Biologics, Small Molecule Drugs, Vaccines, Diagnostics Application: Pharmaceutical Development, Nutraceutical Production, Vaccination Storage, Diagnostic Testing |
| Companies Covered | Thermo Fisher Scientific Inc., Azbil Corporation, SP Industries, Millrock Technology Inc., IMA Industria Macchine Automatiche S.p.A., GEA Group, Martin Christ Freeze-Drying Systems GmbH, OPTIMA Packaging Group GmbH, Labconco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lyophilization Services Market Evolving Landscape
Freeze-drying operations are converging with continuous manufacturing paradigms and digital process control systems, compressing development timelines while elevating regulatory scrutiny on data integrity.
Single-use lyophilization chamber liners and disposable product contact surfaces are miniaturizing cleaning validation burdens for multi-product CDMO facilities. Biologics developers in early-phase clinical trials adopt these systems to accelerate campaign changeovers. The technology is miniaturizing capital barriers for emerging biotech sponsors without dedicated freeze-drying infrastructure.
EMA's 2022 Annex 1 revision on sterile medicinal products mandates barrier technology and isolator integration for aseptic processing suites. Lyophilization service providers now face facility retrofit deadlines to maintain commercial manufacturing authorizations. European CDMOs with legacy open-manifold designs confront substantial capital programs to achieve compliance.
Biopharma procurement teams now unbundle lyophilization from integrated fill-finish contracts, selecting specialized freeze-drying partners based on cycle development expertise rather than geographic proximity. This pattern concentrates volume with technology-leading providers in Germany and Massachusetts while compressing margins for generalist CDMOs. The shift is most visible among mid-cap biotech sponsors with complex biologic formulations requiring customized cycle optimization.
Lyophilization Services Market Segmentation
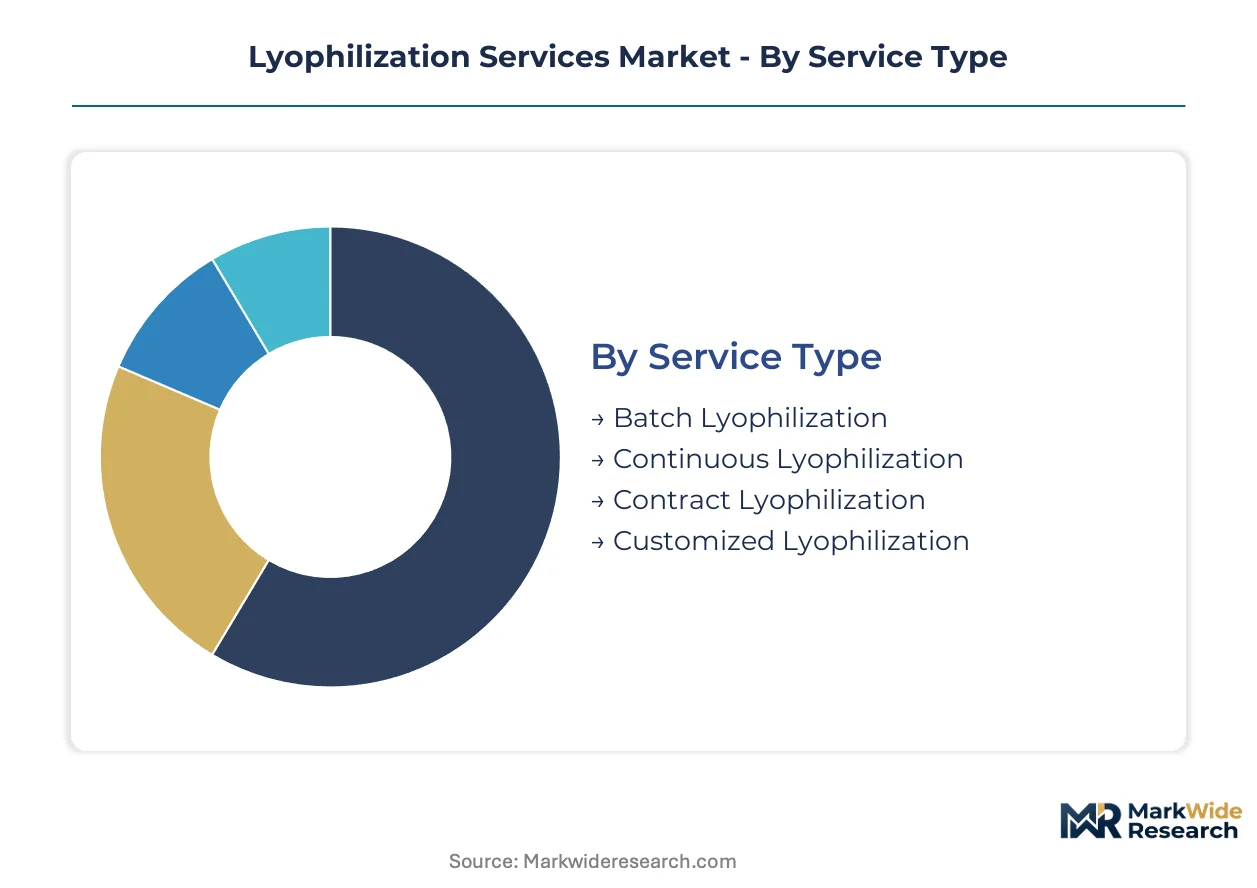
Segmentation in lyophilization services reveals how capital intensity, regulatory compliance burdens, and formulation complexity concentrate value across distinct service tiers. Pharmaceutical sponsors select providers based on scale requirements, therapeutic modality, and geographic proximity to manufacturing networks.
Service Type:
Margin pools concentrate in contract arrangements where sponsors outsource capital expenditure and regulatory risk, while continuous processing commands premium pricing for high-volume vaccine programs.
- Batch Lyophilization:Traditional chamber-based freeze-drying operates at shelf temperatures between -40°C and +40°C with chamber pressures below 200 millitorr. Pharmaceutical developers in Germany and the United States favor established batch infrastructure for monoclonal antibody formulations where cycle flexibility outweighs throughput speed. FDA cGMP qualification timelines for batch suites now extend 18-24 months, constraining new market entrants.
- Continuous Lyophilization:Integrated process lines compress cycle times through rotary or tunnel configurations that move frozen product through sequential drying zones. Vaccine manufacturers in Japan deploy continuous systems for pandemic preparedness stockpiles where throughput economics favor dedicated high-volume lines. EMA Annex 1 barrier technology requirements complicate retrofit of legacy batch facilities with continuous modules.
- Contract Lyophilization:CDMO partners assume capital burden and regulatory liability for freeze-drying operations, capturing the largest value share as biologics sponsors avoid facility ownership.
- Customized Lyophilization:Tailored cycle development for complex formulations including lipid nanoparticles and viral vectors demands specialized formulation scientists and extended design-of-experiment protocols.
The dominant share belongs to Contract Lyophilization, while Continuous Lyophilization is closing the gap fastest.
End User:
Demand intensity varies sharply by R&D maturity and manufacturing scale, with commercial-stage sponsors driving recurring volume while research institutions generate episodic pilot-scale campaigns.
- Pharmaceutical Companies:Large-cap sponsors with approved parenteral products outsource freeze-drying to avoid capital lock-up in cGMP suites, concentrating volume with multi-site CDMOs.
- Biotechnology Firms:Mid-cap developers of monoclonal antibodies and mRNA therapeutics represent the steepest expansion trajectory, as pipeline maturation pulls demand from clinical into commercial-scale lyophilization.
- Academic Institutions:University research programs require pilot-scale capacity for proof-of-concept formulation studies, typically sourcing through shared core facilities or regional CDMO partnerships.
- Research Laboratories:Government and private labs engaged in diagnostic development generate demand for small-batch lyophilization of reagent panels and control materials.
Pharmaceutical Companies anchor current revenue, though Biotechnology Firms are expanding most quickly as pipeline assets advance to registrational trials.
Product Type:
Biological complexity determines technical service requirements, with living-derived products demanding stringent process control that elevates pricing power for qualified providers.
- Biologics:Protein-based therapeutics including monoclonal antibodies and recombinant proteins require precise thermal control to preserve tertiary structure and binding activity. Manufacturers in Massachusetts and Bavaria concentrate demand for biologics lyophilization as FDA and EMA stability guidelines tighten for parenteral formulations.
- Vaccines:Attenuated live virus and subunit formulations benefit from freeze-drying to eliminate cold-chain dependency, with mRNA-lipid nanoparticle stabilization emerging as a specialized subsegment.
- Small Molecule Drugs:Chemical APIs with moisture sensitivity utilize lyophilization for reconstitutable injectables, though simpler stability profiles reduce technical barriers and compress service margins.
- Diagnostics:Lyophilized reagents and calibrators for molecular and immunoassay platforms require batch consistency and rapid moisture content verification.
Biologics command the dominant position, while Vaccines are gaining share fastest on mRNA platform expansion.
Application:
Regulatory pathway intensity shapes procurement behavior, with commercial pharmaceutical applications demanding full cGMP compliance while nutraceutical and diagnostic segments tolerate lower certification tiers.
- Pharmaceutical Development:Clinical and commercial manufacturing of injectable drugs drives the majority of contract lyophilization revenue, governed by FDA cGMP and EMA Annex 1 sterile processing mandates.
- Vaccination Storage:Stockpile stabilization for national immunization programs requires validated long-term stability data, with Germany and Japan maintaining dedicated capacity for strategic reserves.
- Nutraceutical Production:Probiotic and enzyme formulations utilize freeze-drying for shelf-life extension, typically operating under food-grade rather than pharmaceutical GMP standards.
- Diagnostic Testing:Point-of-care and laboratory assay components demand lyophilization for room-temperature distribution, with COVID-19 test kit production having accelerated capacity investments.
Pharmaceutical Development holds the dominant share, while Vaccination Storage is climbing the fastest on pandemic preparedness commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP alignment incentives and EMA Annex 1 sterile manufacturing mandates are concentrating lyophilization capacity investments in jurisdictions with established biologics infrastructure. National pandemic preparedness programs and mRNA vaccine supply chain localization policies further shape geographic demand patterns.
United States
Massachusetts and North Carolina biotech clusters drive contract lyophilization demand as mid-cap sponsors advance monoclonal antibody pipelines toward commercial scale. FDA process analytical technology guidance for real-time release testing elevates facility qualification thresholds for new market entrants. Greater Boston CDMOs now specialize in lipid nanoparticle formulation stabilization for mRNA therapeutics.
Germany
Bavarian pharmaceutical manufacturers anchor European freeze-drying service demand through integrated fill-finish operations for parenteral biologics. EMA Annex 1 barrier technology mandates force facility retrofits among legacy open-manifold operators in the Rhine-Main region. Baden-Württemberg equipment fabricators supply stainless steel lyophilization chambers with 18-24 month lead times.
Japan
PMDA stability requirements for cold-chain-independent vaccine formulations pull continuous lyophilization investments from national immunization program suppliers. METI pandemic preparedness stockpiling directives prioritize high-throughput freeze-drying lines for influenza and mRNA platform vaccines. Kansai region CDMOs specialize in rotary continuous systems for dedicated high-volume production.
India
CDSCO regulatory alignment with ICH Q5A guidelines creates outsourcing opportunities for Western-qualified manufacturers in Hyderabad and Bengaluru biotech corridors. Cost-sensitive biologics sponsors now unbundle lyophilization from integrated contracts to capture pricing advantages. Maharashtra-based CDMOs invest in ISO 14644-1 Class 5 suites to serve advanced therapy medicinal product demand.
Switzerland
Swissmedic manufacturing authorization requirements for sterile processing attract specialized freeze-drying service investments from global biologics sponsors. Basel-region pharmaceutical clusters generate demand for customized cycle development of complex protein formulations. Cleanroom infrastructure gaps in secondary European markets enable first-mover facility positioning for multi-product CDMOs.
Lyophilization Services Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory qualification dimensions. The vendor base stratifies between integrated CDMO platforms with multi-site pharmaceutical contracts and equipment-focused specialists serving pilot-scale clinical transitions. Three archetypes dominate: integrated service platforms, process technology equipment suppliers, and specialized pilot-scale system providers. Competitive positioning depends on cGMP suite availability, cycle development expertise, and geographic proximity to biologics manufacturing clusters.
Within the integrated service platform tier, Thermo Fisher Scientific Inc. and GEA Group occupy positions spanning equipment supply through contract manufacturing. Millrock Technology Inc. exemplifies the specialized pilot-scale archetype, bridging clinical and commercial manufacturing transitions for emerging biotech sponsors. These three anchors demonstrate how scale specialization and regulatory qualification depth determine competitive differentiation in freeze-drying services.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Azbil Corporation |
| SP Industries |
| Millrock Technology Inc. |
| IMA Industria Macchine Automatiche S.p.A. |
| GEA Group |
| Martin Christ Freeze-Drying Systems GmbH |
| OPTIMA Packaging Group GmbH |
| Labconco Corporation |
| Others |
Value Network & Pricing Analysis
Disposable single-use chamber liners replacing stainless steel product contact surfaces redraws supply geography toward polymer fabrication hubs in China and Germany while compressing pricing economics for multi-product CDMO campaign changeovers.
Pricing Analysis
Certification level (FDA-grade, EMA-Annex 1, ISO 14644-1 Class 5) creates the primary spread between premium contract lyophilization suites and standard pilot-scale operations. Three-tier pricing structure across premium, standard, and economy levels reflects cGMP qualification depth, with after-sales cycle development bundling commanding additional margin. Cost compression in standard-tier batch services is intensifying because qualified personnel scarcity extends project timelines. Mid-cap biotechnology firms with complex biologic formulations show least price sensitivity, while diagnostic reagent manufacturers prioritize economy-tier capacity.
Supply Chain Analysis
Germany and Japan anchor precision stainless steel lyophilization chamber fabrication, with Baden-Württemberg foundries and Kansai region metalworkers supplying specialized shelf assemblies and vacuum vessel components. Equipment manufacturing draws from European specialty steel mills, precision machining centers, and high-vacuum pump producers. Single-source vulnerability concentrates in specialized European foundry capacity for cGMP-qualified chamber fabrication. Distribution runs through direct OEM sales for large-scale pharmaceutical sponsors and regional distributor networks for pilot-scale research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated aseptic processing expertise now functions as the scarce capability gatekeeping commercial biologics contracts, with cGMP certification timelines extending far faster than qualified technical talent pipelines can fill.
For Market Incumbents: Secure multi-year cycle development partnerships with mid-cap biotechnology firms before EMA Annex 1 retrofit deadlines concentrate volume with barrier-technology-compliant competitors. Deepen backward integration into stainless steel chamber fabrication through offtake agreements with German and Japanese foundries to defend against equipment lead time extension. Prioritize isolator technology deployment in legacy open-manifold facilities to maintain commercial manufacturing authorizations. For New Entrants and Emerging Players: Pilot-to-commercial scale-up validation services represent the most penetrable white space where integrated CDMOs under-serve emerging sponsors with complex lipid nanoparticle formulations. Target ISO 14644-1 Class 5 suite investments in Switzerland and Singapore where cleanroom infrastructure gaps enable first-mover positioning for advanced therapy medicinal products. Lead with specialized cycle development expertise rather than geographic proximity to capture biologics procurement teams unbundling lyophilization from fill-finish contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology-leading contract manufacturers with validated barrier technology and multi-site pharmaceutical networks. Long-term viability hinges on regulatory qualification depth rather than capacity scale alone, positioning EMA- and FDA-compliant CDMOs for sustained margin capture. Watch CDSCO regulatory alignment progress in India as the signal indicating when Western-qualified Indian manufacturers become viable acquisition targets for cost-sensitive biologics outsourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Retrofit | EMA Annex 1 compliance preserves commercial manufacturing authorizations for European CDMOs with legacy open-manifold designs. |
| Continuous Lyophilization Scale-Up | Rotary tunnel systems compress cycle times for pandemic preparedness stockpiles demanded by Japan's METI directives. |
| Single-Use Chamber Adoption | Disposable liners miniaturize cleaning validation burdens for multi-product facilities serving early-phase clinical trials. |
| Process Analytical Technology Integration | FDA real-time release testing mandates elevate facility qualification thresholds and concentrate volume with technology leaders. |
| India CDMO Capacity Expansion | CDSCO alignment with ICH Q5A guidelines positions Western-qualified Indian manufacturers for biologics outsourcing growth. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with contract manufacturing executives, regulatory affairs specialists, biologics formulation scientists, and pharmaceutical procurement directors; and secondary validation through FDA cGMP inspection records, EMA manufacturing authorization databases, CDSCO regulatory filings, and stainless steel equipment trade flow data. Bottom-up triangulation across service provider capacity announcements and top-down reconciliation against biologics pipeline maturation curves anchored volume estimates.
Across the projection horizon, the analytical framework modeled demand through segmentation by service type (batch, continuous, contract, customized), end user maturity (pharmaceutical, biotechnology, academic, research), and product biological complexity (biologics, vaccines, small molecule, diagnostic). CAGRs derived from regression against biologics approval velocity and pandemic preparedness stockpiling commitments. Industry-specific inputs included mRNA platform expansion trajectories and EMA Annex 1 retrofit investment cycles.
Underlying assumptions cover sustained FDA and EMA sterile manufacturing stringency, with deviation risk concentrated in continuous processing technology adoption rates and qualified personnel availability in concentrated biopharma clusters. Recalibration cycles align with material shifts in regulatory guidance revisions and national immunization program localization policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Chemical Absorbent Pads Market