
 Brine Concentration Technology Market | 2026-2036
Brine Concentration Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Brine Concentration Technology Market Intelligence
A focus on Zero Liquid Discharge (ZLD) compliant systems is rotating the market toward higher-specification and higher-value installations. Veolia Water Technologies leverages its global footprint to serve large-scale municipal and industrial projects. Koch Separation Solutions specializes in advanced membrane technologies for complex industrial waste streams. Saltworks Technologies differentiates with its expertise in thermal and electrochemical systems for the most challenging brines.
Brine concentration technology encompasses processes designed to increase solute concentration in saline water, often achieving total dissolved solids (TDS) levels above 70,000 ppm. Its primary purpose is to minimize waste volume for disposal and recover valuable solids or reusable water. Among technology segments, thermal methods like Mechanical Vapor Recompression dominate high-salinity applications. The mining operations and chemical processing sectors represent the fastest-growing application areas due to stringent discharge limits.
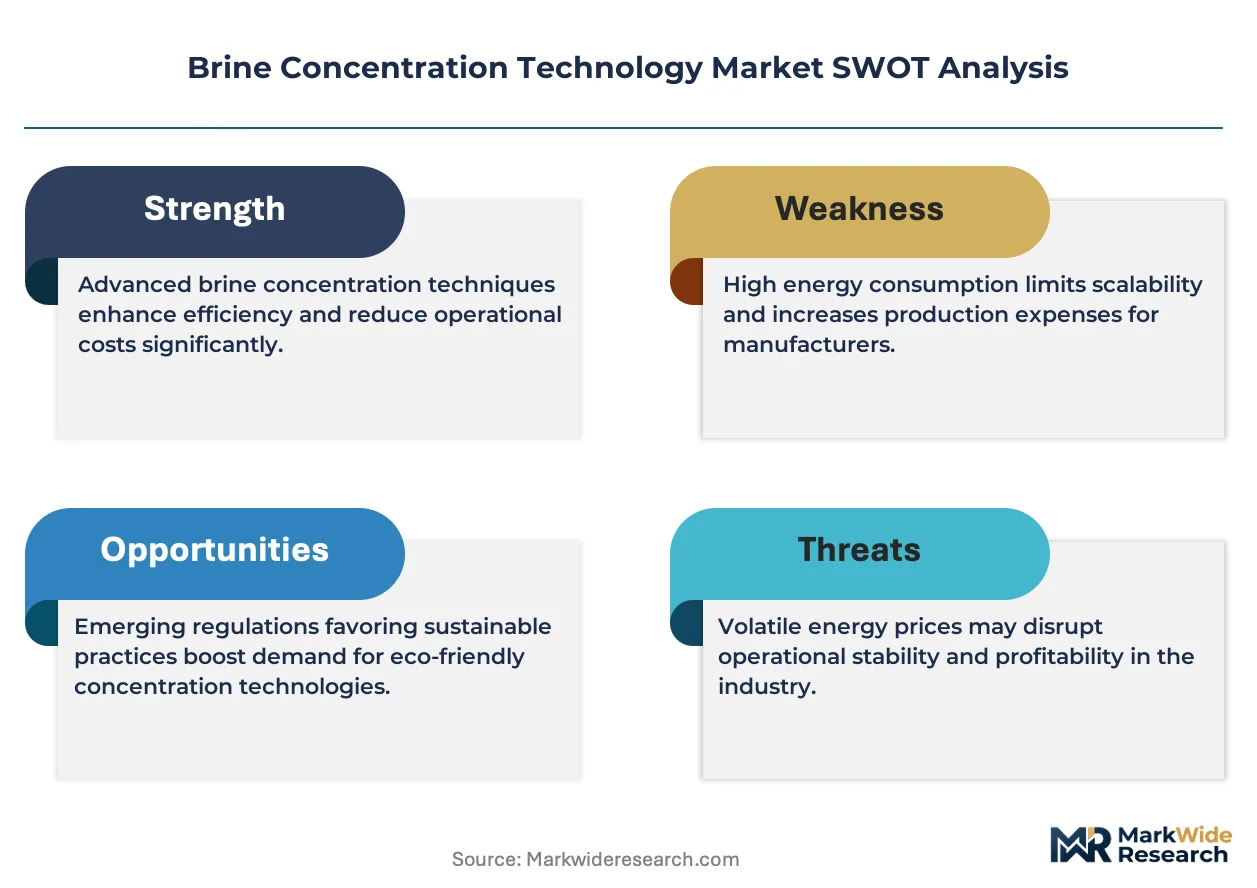
Regulations like the US EPA's Effluent Limitation Guidelines and the EU's Industrial Emissions Directive mandate stricter control over industrial wastewater discharge. In parallel, China's MEE policies promoting resource circularity are creating new incentives for brine treatment. Stakeholder decisions will hinge on balancing the high capital cost of ZLD systems against the rising financial and regulatory risks of brine disposal.
Market Dynamics
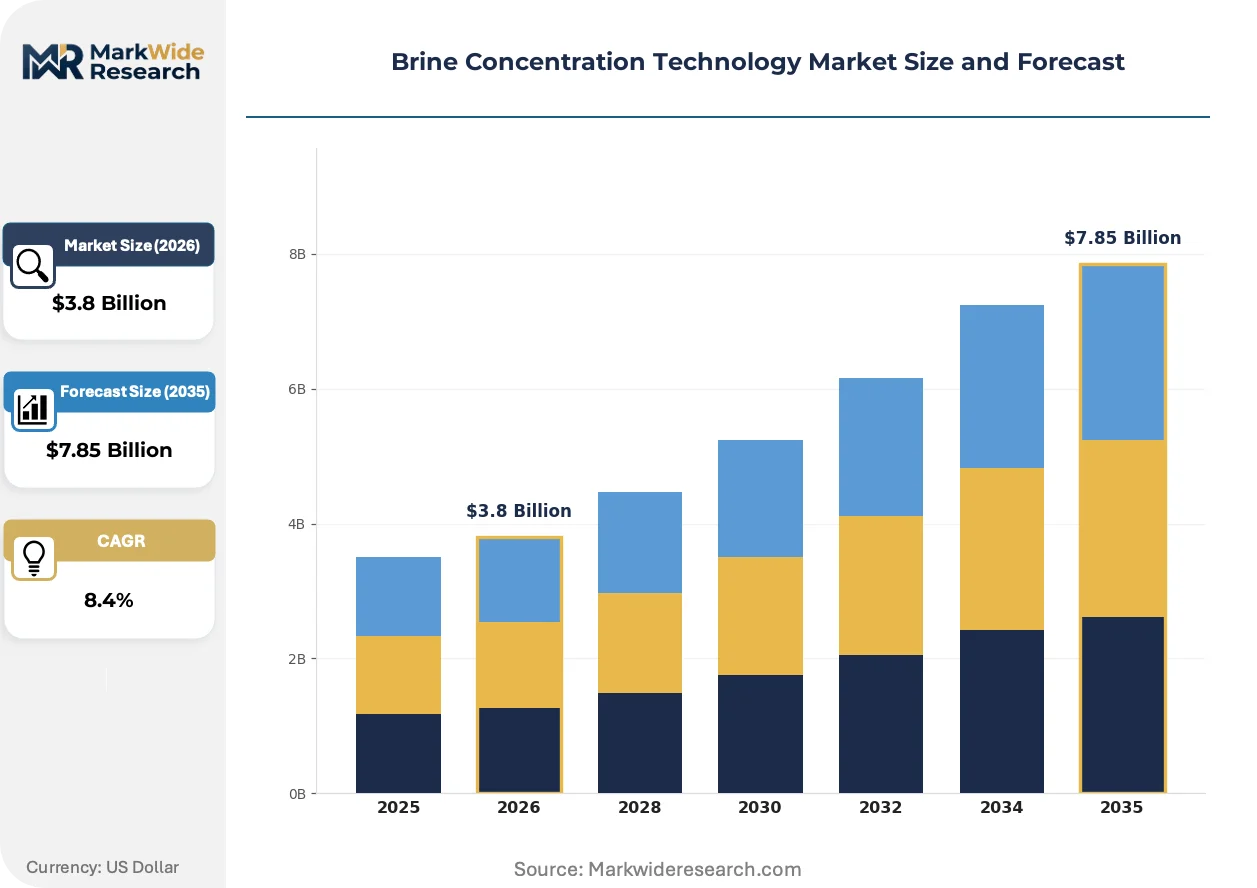
The market's core dynamic is the tension between the high capital cost of Zero Liquid Discharge systems and increasingly strict environmental regulations. This forces industrial operators to balance immediate financial outlay against long-term compliance risks and resource recovery opportunities.
Growth Catalysts
- Regulatory Mandates:Zero Liquid Discharge (ZLD) regulations from bodies like the US EPA and China's MEE compel industrial facilities to adopt brine concentration for compliance.
- Critical Mineral Extraction:The mining sector is using these technologies to recover valuable materials like lithium from brine, creating a strong economic pull in regions like Chile.
- Improved Process Economics:Advances in Mechanical Vapor Recompression (MVR) technology are reducing energy consumption, making treatment more financially viable for chemical plants.
Market Restraints
- High Capital Outlay:The significant upfront cost of ZLD systems, especially thermal crystallizers, is a major hurdle for operators without immediate regulatory drivers.
- Energy Consumption:Energy-intensive thermal processes like MVR lead to high operational costs, challenging the economics of projects with low-value waste streams.
- Feed Water Variability:Inconsistent brine chemistry from mining plants requires costly, custom-engineered systems and robust pre-treatment to prevent fouling and failure.
Strategic Opportunities
- Semiconductor Wastewater:Treating wastewater from semiconductor fabs in South Korea presents a high-value opportunity due to strict water reuse requirements and high water costs.
- Modular System Deployment:Containerized brine units can serve smaller industrial sites and remote mining operations that cannot support large-scale, centralized infrastructure.
- Waste Heat Integration:Retrofitting plants to use waste heat to power thermal concentrators can drastically reduce energy costs and improve project payback periods.
Industry Challenges
- Skilled Operator Scarcity:Operating and maintaining complex, multi-stage ZLD systems requires specialized engineering expertise that is in short supply across many industrial sectors.
- Legacy System Integration:Retrofitting brine concentration technologies into existing industrial facilities with established infrastructure presents significant engineering and operational disruption challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brine Concentration Technology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Distillation, Evaporation, Crystallization, Zero Liquid Discharge, Thermal Vapor Compression, Mechanical Vapor Recompression Application: Power Generation, Water Treatment Plants, Chemical Processing, Mining Operations, Oil & Gas Extraction, Food & Beverage Processing Installation Type: Fixed Installations, Modular Units, Containerized Systems, Skid-Mounted Systems End User: Municipal Utilities, Industrial Facilities, Desalination Plants, Chemical Manufacturers, Mining Companies |
| Companies Covered | IDE Technologies, Koch Separation Solutions, Veolia Water Technologies, Advent Envirocare Technology Pvt. Ltd., Gradiant, Evoqua Water Technologies, Aquatech International, Fluid Technology Solutions, Saltworks Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brine Concentration Technology Market Strategic Shifts & Innovations
A fundamental shift from waste disposal to resource recovery is redefining the market's trajectory. Technology and regulations are converging to treat brine not as a liability for disposal but as a source of valuable minerals and reusable water.
Modular brine concentration systems are designed for decentralized deployment at smaller industrial sites or remote locations. Industries like specialty chemical manufacturing are adopting these containerized units, which offer lower initial capital costs and scalability. This trend is fragmenting the traditional market for large, centralized treatment plants, creating new opportunities for specialized vendors.
The European Union's Industrial Emissions Directive (IED) imposes strict Best Available Techniques (BAT) requirements for managing wastewater. This regulation forces industries like chemical manufacturing and power generation to evaluate and often upgrade their water treatment processes to minimize environmental impact. The chemical processing sector is most affected, investing in advanced membrane and thermal systems to meet compliance.
Industrial customers are increasingly opting for build-own-operate-transfer (BOOT) or leasing models for their brine treatment needs. This shifts the performance risk and capital burden from the end-user to specialized water treatment service providers. This model is gaining significant traction in the North American mining and power generation sectors.
Brine Concentration Technology Market Segmentation
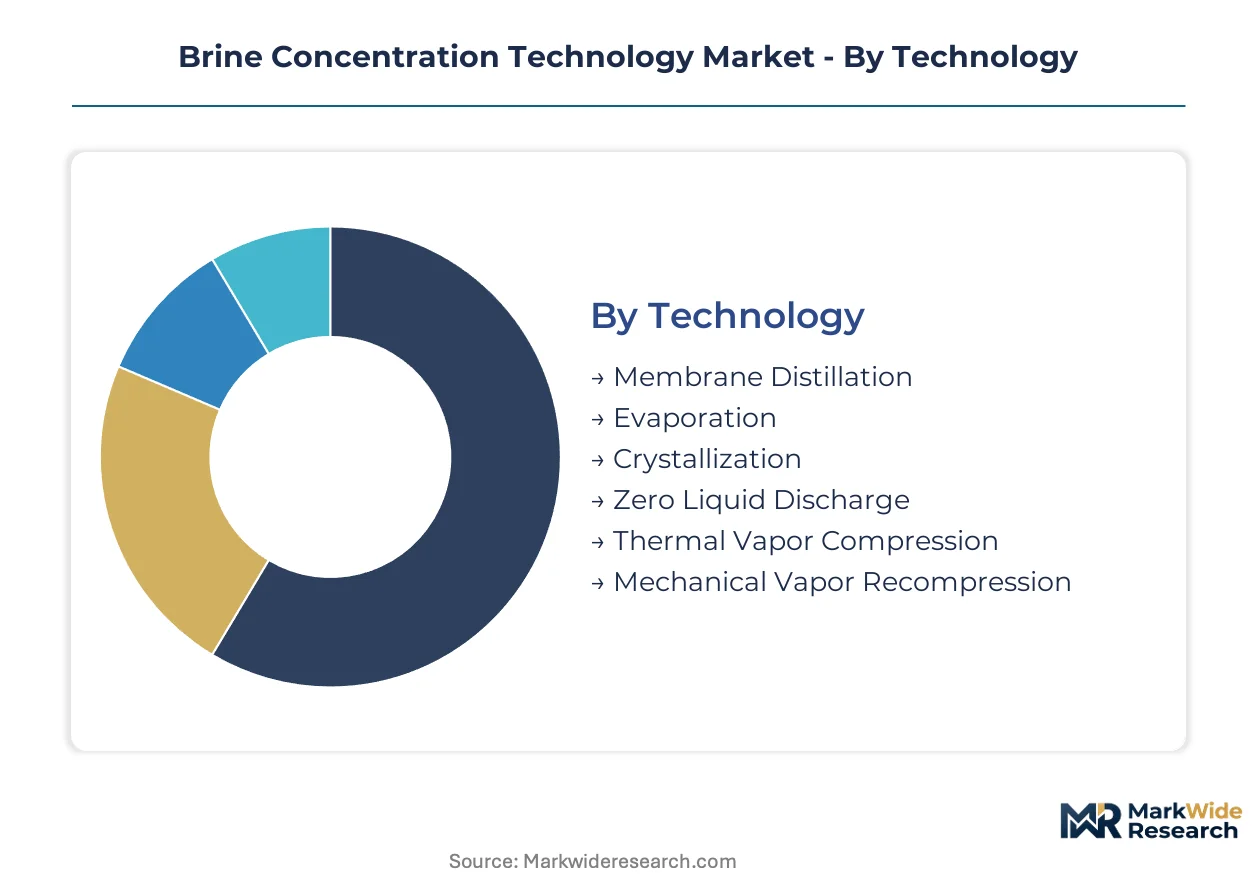
Understanding the segmentation of the Brine Concentration Technology Market reveals the diverse technical approaches and application-specific demands driving its expansion. Each segment addresses distinct challenges in waste minimization and resource recovery, shaping vendor strategies and investment priorities. Regulatory frameworks and economic incentives further influence the adoption patterns across various industrial and municipal end-users.
Technology:
Segments within brine concentration technology face varying substitution pressures depending on brine complexity and desired recovery outcomes.
- Mechanical Vapor Recompression:This thermal technology uses mechanical energy to compress vapor, increasing its temperature and allowing it to be reused as a heat source for evaporation. Advances in MVR technology are reducing energy consumption, making treatment more financially viable for chemical plants.
- Zero Liquid Discharge:ZLD systems aim to recover all water from a waste stream, leaving only solid waste for disposal, driven by stringent environmental regulations. Demand for ZLD systems is particularly strong in mining-intensive regions like Chile due to critical mineral extraction.
- Membrane Distillation:This process uses a hydrophobic membrane to separate water vapor from saline solutions, driven by a temperature difference across the membrane.
- Evaporation:Evaporation processes remove water from brine by boiling, leaving behind concentrated salts, a fundamental method for volume reduction.
- Crystallization:Crystallization extracts dissolved solids from supersaturated brine solutions, producing high-purity solid salts for recovery or disposal.
- Thermal Vapor Compression:This method uses a steam jet ejector to compress vapor, enhancing efficiency in multi-effect evaporators for industrial applications.
Mechanical Vapor Recompression anchors the volume base while Zero Liquid Discharge gains share at the steepest rate.
Application:
The application landscape for brine concentration technology is heavily influenced by sector-specific regulatory mandates and resource recovery objectives.
- Mining Operations:These applications focus on recovering valuable minerals like lithium from brine and managing process water to meet environmental discharge limits. The mining sector represents a fastest-growing application area due to stringent discharge limits and critical mineral extraction.
- Chemical Processing:This sector utilizes brine concentration for product recovery, wastewater volume reduction, and compliance with strict effluent guidelines. Chemical processing represents a fastest-growing application area due to stringent discharge limits.
- Power Generation:Brine concentration technologies treat cooling tower blowdown and flue gas desulfurization wastewater in power plants.
- Water Treatment Plants:Municipal and industrial water treatment facilities use these technologies to manage concentrate from reverse osmosis systems.
- Oil & Gas Extraction:Brine treatment in oil and gas addresses produced water management and disposal challenges in extraction operations.
- Food & Beverage Processing:This industry applies brine concentration for water reuse and byproduct recovery, reducing wastewater disposal costs.
The diversification of brine concentration applications reflects the broad industrial need for water stewardship.
Installation Type:
Deployment flexibility dictates the viability of different installation types across diverse operational scales and geographical constraints.
- Modular Units:These pre-engineered, scalable systems offer flexibility and faster deployment for varied industrial sites. Modular brine concentration systems are designed for decentralized deployment at smaller industrial sites.
- Containerized Systems:Housed within standard shipping containers, these units provide portability and rapid setup for remote or temporary operations. Containerized brine units can serve remote mining operations that cannot support large-scale infrastructure.
- Fixed Installations:Large-scale, permanent structures are designed for high-volume, continuous brine treatment at centralized facilities.
- Skid-Mounted Systems:Compact, pre-assembled units mounted on a frame for easy transport and integration into existing plant infrastructure.
The shift towards decentralized solutions is reshaping the preference for certain installation types.
End User:
Operational complexity and brine chemistry define the specific needs of various end-user segments, driving tailored technology solutions.
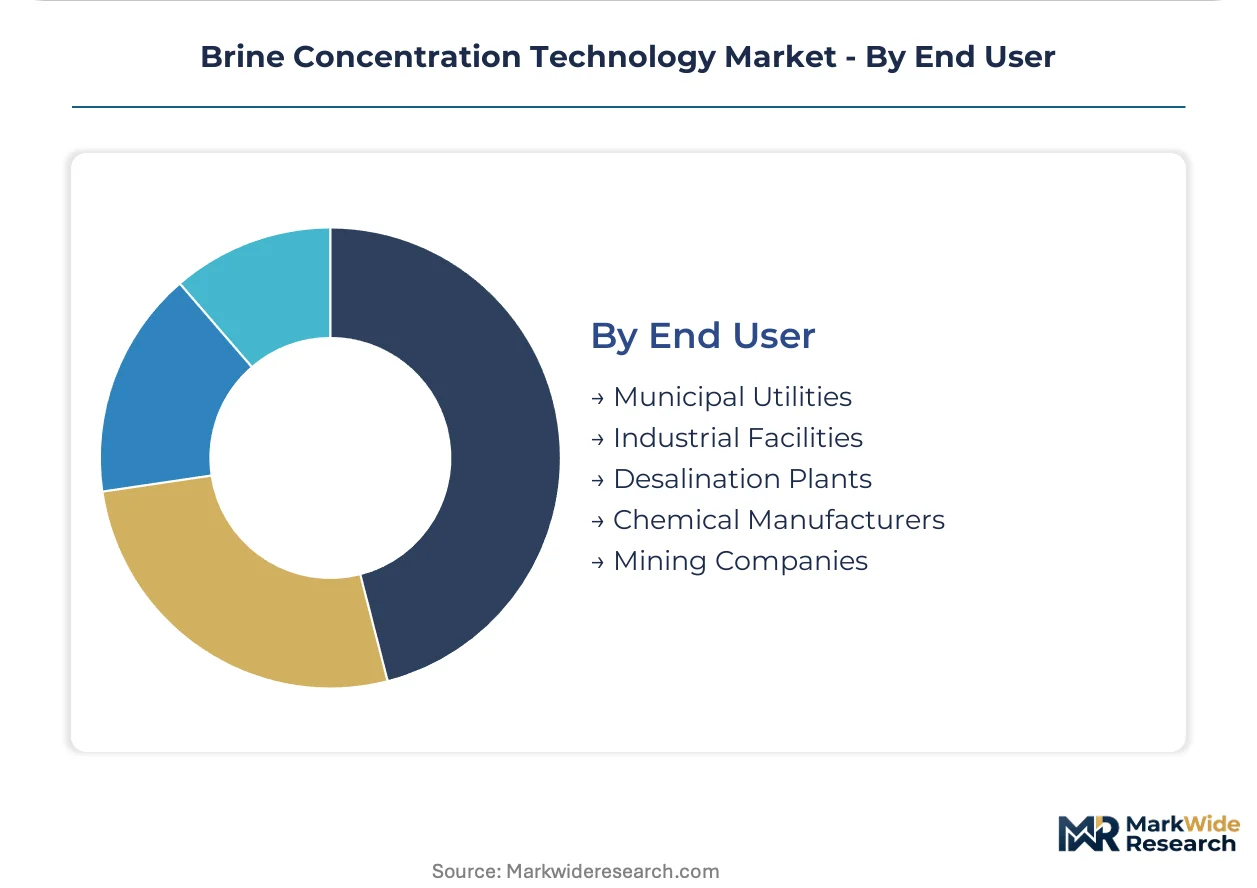
- Industrial Facilities:A broad category encompassing manufacturing, chemical, and power sectors, requiring custom solutions for diverse waste streams. Industrial facilities are compelled by US EPA regulations to adopt advanced water treatment.
- Mining Companies:These users require brine concentration for critical mineral extraction and to meet stringent water discharge limits from regulatory bodies like the Australian TGA. Mining companies are a key driver in regions like Chile due to lithium recovery.
- Municipal Utilities:Public water and wastewater treatment plants utilize these technologies for concentrate management from desalination and purification processes.
- Desalination Plants:Facilities converting seawater or brackish water into potable water manage high-salinity brine reject streams.
- Chemical Manufacturers:Companies in this sector use brine concentration for process optimization, product recovery, and environmental compliance.
Industrial demand from diverse sectors drives the continuous innovation in brine treatment solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology providers from Germany supply advanced brine concentration systems to mining operations in Chile, addressing the complex requirements of critical mineral extraction. This global market for brine concentration technology sees significant activity driven by environmental compliance and resource recovery. Industrial demand shapes regional investment priorities for water treatment infrastructure.
Chile
Chilean mining operations demand brine concentration for lithium extraction and process water management. Local environmental agencies enforce strict discharge limits on industrial wastewater, compelling technology adoption. The Atacama Desert region sees significant investment in advanced systems for mineral recovery.
Australia
Australian mining companies require brine concentration to manage vast volumes of process water in arid regions. State environmental protection agencies mandate stringent controls on water discharge from resource extraction sites. Western Australia's mining hubs, particularly the Pilbara, deploy these technologies to ensure operational sustainability.
United States
United States industrial facilities drive demand for brine concentration to meet stringent environmental regulations. The US EPA's Effluent Limitation Guidelines compel sectors like chemical processing to adopt zero liquid discharge solutions. Semiconductor manufacturing clusters in Arizona and Texas increasingly invest in advanced water reuse systems.
China
China's industrial sector utilizes brine concentration to support its national resource circularity initiatives. The Ministry of Ecology and Environment (MEE) policies promote advanced wastewater treatment and resource recovery across key industrial zones. The Yangtze River Delta region, with its dense chemical processing plants, represents a significant adoption area.
Germany
German chemical manufacturing and power generation sectors require brine concentration for compliance and resource efficiency. The EU's Industrial Emissions Directive (IED) sets Best Available Techniques for industrial wastewater management. The Rhine-Ruhr industrial region actively integrates advanced thermal and membrane systems to meet these standards.
Brine Concentration Technology Market Key Industry Players
Listed leaders compete with private specialists across technological innovation and project delivery scale. The market exhibits a tiered structure, with large global players offering integrated solutions alongside agile technology developers focusing on niche applications. Archetypes include global water treatment conglomerates, specialized membrane technology providers, and thermal/electrochemical system innovators. Companies increasingly engage in portfolio diversification and strategic partnerships to expand their market reach.
Specialists in advanced solutions include Veolia Water Technologies, a French-based global water treatment company known for large-scale municipal and industrial projects, representing the archetype of a comprehensive solution provider. Koch Separation Solutions, a US-based entity, exemplifies expertise in membrane technologies designed for complex industrial waste streams, anchoring the segment of advanced separation specialists. Saltworks Technologies, a Canadian innovator, occupies a position in thermal and electrochemical systems for challenging brines, embodying the niche of high-salinity treatment experts. These companies collectively illustrate the diverse technological approaches defining the competitive landscape.
| Leading Market Players |
|---|
| IDE Technologies |
| Koch Separation Solutions |
| Veolia Water Technologies |
| Advent Envirocare Technology Pvt. Ltd. |
| Gradiant |
| Evoqua Water Technologies |
| Aquatech International |
| Fluid Technology Solutions |
| Saltworks Technologies |
| Others |
Cost & Logistics Intelligence
Project-based contracts for large brine concentration systems lock in both supply access and long-term price visibility for complex industrial installations. These agreements often span several years, reflecting significant capital investment.
Pricing Analysis
The pricing gap between current-generation thermal crystallizers and advanced MVR systems reflects ongoing energy efficiency improvements. Project-based pricing dominates the market, with significant differentiation based on customization level for complex brine chemistries and comprehensive after-sales service. Pricing softness for standard systems stems from high capital outlay, while ZLD-compliant solutions command a premium due to strict regulatory mandates. Smaller industrial facilities exhibit higher price sensitivity compared to large mining operations driven by critical mineral recovery.
Supply Chain Analysis
Access to specialized components for advanced membrane and thermal systems represents a critical chokepoint in the supply chain. Key technology providers are concentrated in Germany, the United States, and Canada, while component manufacturing sources from East Asia. Raw material dependencies include high-grade alloys for corrosion resistance and specialized membrane polymers, creating single-source vulnerability for some advanced media. Distribution primarily runs through direct sales channels and specialized engineering-procurement-construction (EPC) contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brine concentration technology market is undergoing high-growth disruption, driven by stringent Zero Liquid Discharge (ZLD) regulations. This regulatory inflection compels industrial facilities to adopt advanced treatment solutions for compliance and resource recovery.
For Market Incumbents: Shield core thermal technology revenues by aggressively investing in R&D for next-generation energy-efficient Mechanical Vapor Recompression (MVR) systems. Acquire modular system specialists to counter fragmentation from smaller, agile competitors. Focus on robust after-sales service and long-term BOOT contracts to lock in client relationships against emerging entrants. Certification investment in ZLD compliance reinforces market leadership.
For New Entrants and Emerging Players: Differentiate on rapid deployment and lower upfront capital costs through modular and containerized systems. Target underpenetrated segments like smaller industrial facilities and remote mining operations in regions such as Australia. A go-to-market strategy emphasizing flexible leasing or BOOT models can overcome high capital outlay restraints. Focus on niche applications like semiconductor wastewater treatment for high-value opportunities.
For Investors and Strategic Acquirers: Capital is best deployed toward companies specializing in advanced membrane or thermal technologies with proven ZLD capabilities. Long-term viability remains strong, driven by global water scarcity and escalating environmental regulations. Target acquisition archetypes include agile developers of modular units and innovators in waste heat integration. Watch for increased M&A activity among traditional players seeking to expand their modular solution portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced MVR R&D | Reduces energy consumption, making high-salinity brine treatment more economically viable for chemical processing. |
| Expand Modular System Offerings | Addresses demand from smaller industrial sites and remote mining operations, broadening market access. |
| Form Strategic Partnerships | Combines expertise in thermal and membrane technologies, offering comprehensive solutions for varied brine streams. |
| Focus on BOOT/Leasing Models | Lowers capital burden for end-users, accelerating adoption of ZLD systems in mining and power generation. |
| Target Semiconductor Wastewater | Leverages high-value opportunity in South Korea due to strict water reuse requirements and high water costs. |
Research Approach
Desk research of regulatory filings from the US EPA and China MEE, industry association reports, and academic literature preceded structured interviews with plant managers, environmental compliance officers, R&D directors, and procurement leads. This approach combined primary insights with secondary validation. Bottom-up data collection from specific projects and top-down market sizing provided robust triangulation.
Variance decomposition underpins the analytical framework, assessing market drivers and restraints across the analysis window. Segmentation dimensions modeled include technology, application, installation type, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected adoption rates. Critical mineral demand and ZLD system capital costs served as key industry-specific forecast inputs.
Forecasts assume regulatory continuity in US EPA and China MEE regimes; material policy shifts would require re-modeling. Unforeseen technological breakthroughs or significant economic downturns affecting industrial capital expenditure could alter projections. Practitioners should keep alternative scenarios live as global environmental policy and industrial investment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Lyophilization Services Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Sludge Dryer Machine Market