
 Freeze-Dried Powder Market | 2026-2036
Freeze-Dried Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Dried Powder Market Analytics
Continuous lyophilization technology is reshaping pharmaceutical powder production by replacing batch cycles with real-time process control. Nestlé S.A. leverages its dairy powder heritage to dominate consumer-facing applications, while Kerry Group plc anchors pharmaceutical-grade supply through specialized excipient portfolios. DSM-Firmenich differentiates via integrated biotechnology platforms that streamline upstream fermentation to downstream freeze-drying.
Freeze-dried powder consists of biologically active or nutritional substances preserved through sublimation-driven dehydration, typically retaining moisture below 3% to ensure structural integrity during ambient storage. The primary commercial purpose centers on extending shelf life without refrigeration for pharmaceuticals, specialty foods, and probiotic formulations. Fruits and vegetables represent mature volume pools where margin compression is common, whereas protein segments command premium positioning due to sports nutrition and clinical nutrition demand. Continuous process technology is displacing tray-based systems in large-scale pharmaceutical operations, though batch manifold configurations persist in multi-product contract facilities.
FDA process analytical technology mandates and EMA Annex 1 sterile manufacturing revisions are tightening validation requirements for freeze-dried injectables, directly shaping capital expenditure timelines for equipment replacement. The EU Green Deal's energy efficiency directives are pressuring European operators to retrofit vacuum systems and adopt heat recovery mechanisms in lyophilization suites. Stakeholders must weigh the trade-off between continuous technology capital intensity and batch flexibility when configuring capacity for multiproduct versus dedicated product lines.
Market Dynamics
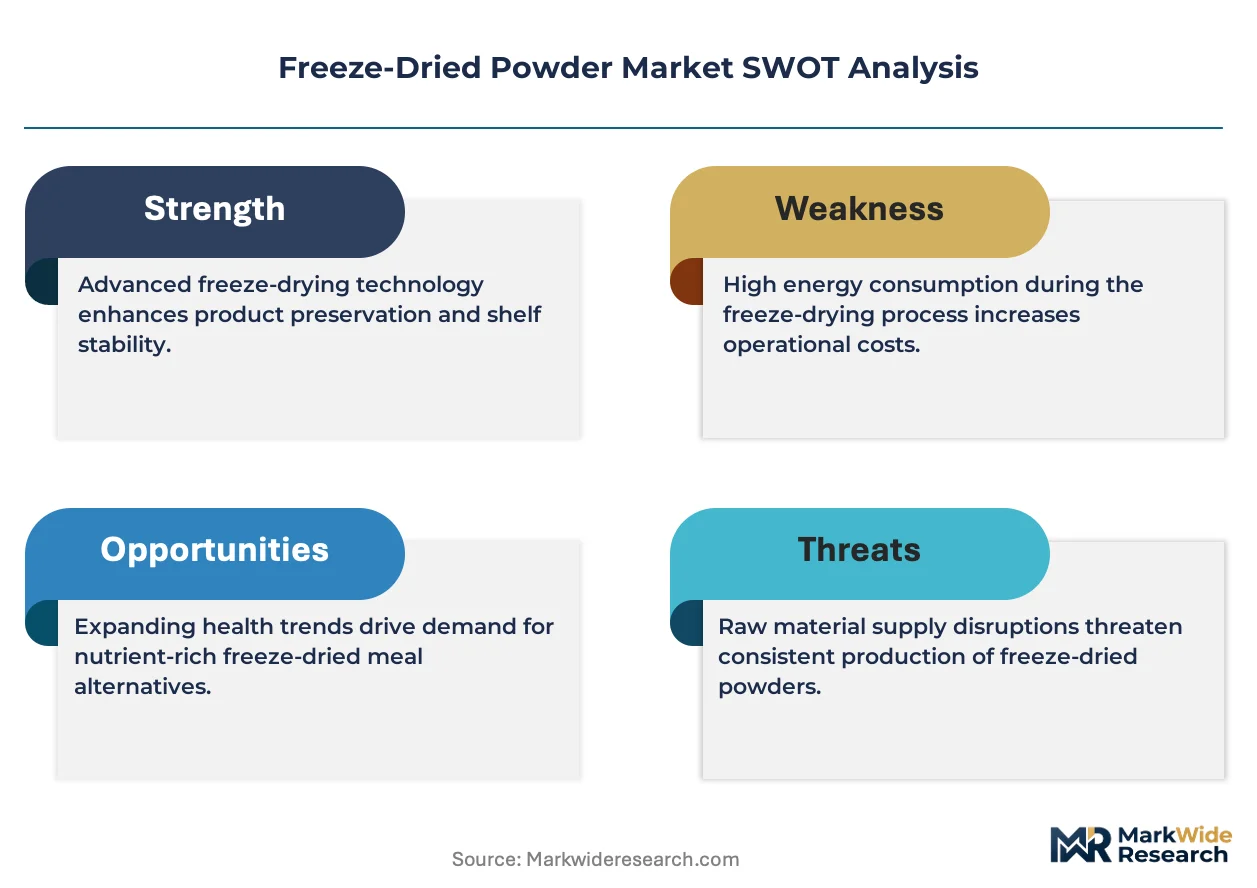
Continuous lyophilization technology is compressing batch cycle times and forcing capital reallocation across pharmaceutical manufacturing suites, while FDA process analytical technology mandates accelerate equipment obsolescence timelines for legacy tray-based systems.
Growth Catalysts
- Biologics stability requirements:Monoclonal antibodies and mRNA vaccines require sublimation preservation to maintain tertiary structure during ambient distribution, pulling freeze-dried formats into standard formulation pipelines.
- FDA process analytical technology guidelines:Real-time release testing mandates are compelling equipment upgrades toward continuous monitoring architectures with embedded spectroscopic sensors.
- Sports nutrition protein demand:Whey and plant protein isolates in ambient-stable powder form are displacing refrigerated ready-to-drink formats in North American and European gym-channel distribution.
Market Restraints
- Energy intensity of vacuum sublimation:Lyophilization cycles consume 1.5-2.5 kWh per kilogram of water removed, exposing European operators to EU Green Deal carbon pricing and electricity cost volatility.
- Specialized equipment supply concentration:Production-scale freeze-dryer manufacturing concentrates among German and Italian engineering houses, creating 18-24 month delivery backlogs for pharmaceutical-grade units.
- Thermal degradation of heat-sensitive actives:Protein denaturation during primary drying limits applicable molecule classes, constraining addressable biologics to those with glass transition temperatures above collapse thresholds.
Strategic Opportunities
- Indian contract manufacturing expansion:CDMOs in Hyderabad and Bangalore are building dedicated lyophilization suites to capture biologics fill-finish work migrating from Western cost bases.
- Probiotic strain stabilization:Freeze-dried bacterial concentrates for functional foods and veterinary applications represent underpenetrated demand outside human pharmaceutical channels.
- EU Green Deal retrofit incentives:Heat recovery vacuum systems and alternative refrigerant upgrades qualify for national green industrial transformation funds in Germany, France, and the Netherlands.
Industry Challenges
- Lyophilization process engineer scarcity:The intersection of thermodynamics, sterile manufacturing, and regulatory validation requires specialized talent pools concentrated in Switzerland, Germany, and Massachusetts.
- Legacy batch record system integration:Continuous process analytical technology platforms must interface with validated electronic batch record systems, creating data architecture complexity and validation timeline extension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Dried Powder Market |
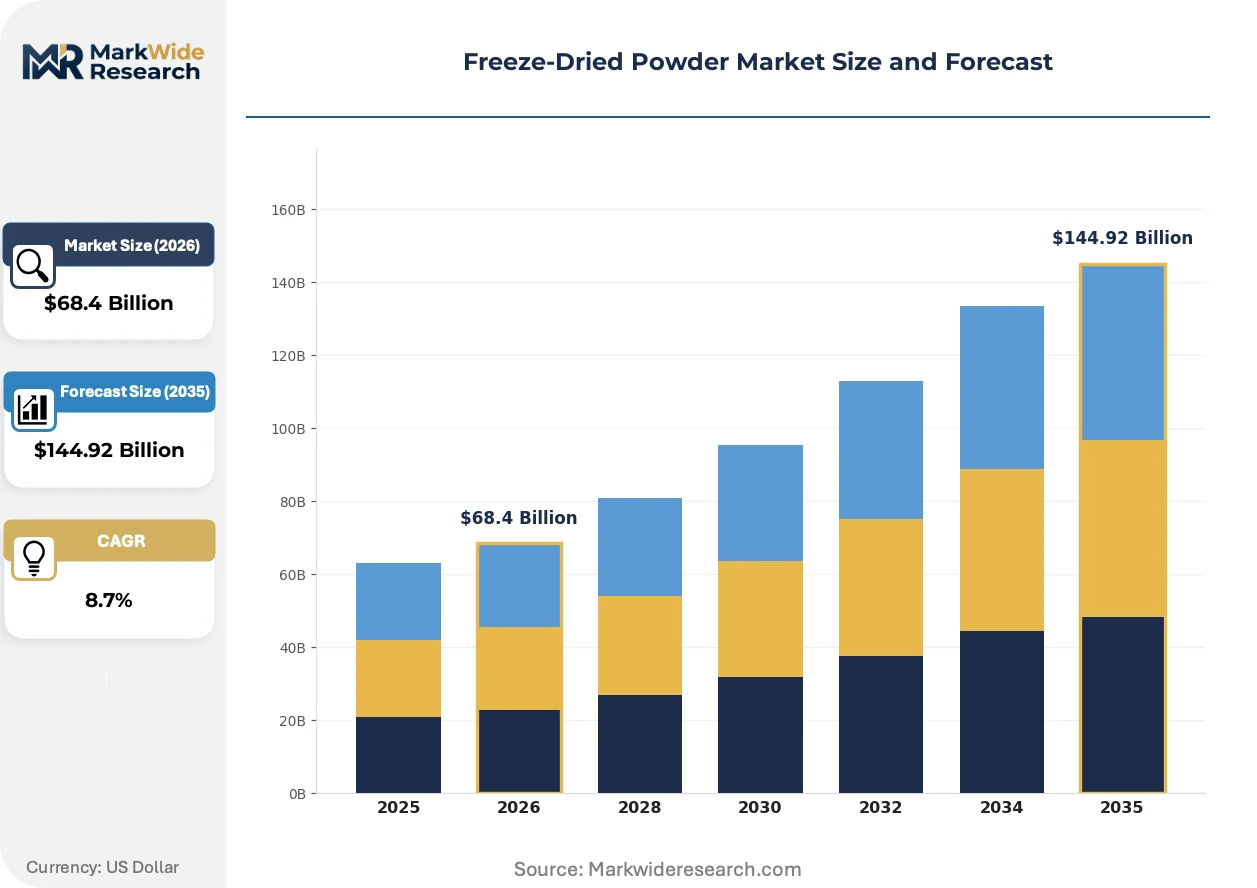
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Protein Application: Food & Beverage, Pharmaceuticals, Cosmetics, Pet Food Process Technology: Manifold, Batch, Continuous, Tray End User: Food Manufacturers, Retailers, Restaurants, Households |
| Companies Covered | Nestlé S.A., Mercer Foods LLC, European Freeze Dry Ltd., Chaucer Foods Ltd., Van Drunen Farms, Döhler GmbH, Kerry Group plc, DSM-Firmenich, Thrive Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Dried Powder Market Evolving Landscape
Process intensification and regulatory digitization are converging to redefine how freeze-dried powders are manufactured, validated, and released to market, with implications spanning equipment architecture through distribution logistics.
Single-use containment technologies for freeze-dryer loading and unloading are migrating from isolator-based manual operations toward robotic aseptic transfer systems. Biologics manufacturers with high-potency or cytotoxic portfolios are adopting these systems fastest. This migration from stainless-steel fixed equipment is compressing cleaning validation timelines and enabling faster product changeovers in multi-suite facilities.
EMA Annex 1 sterile manufacturing revisions mandate barrier technology and continuous environmental monitoring for all aseptic processing including lyophilization. European operators face 2024-2025 compliance deadlines for facility upgrades. Small-molecule injectable specialists in Italy and Spain are consolidating production into fewer, higher-capacity suites to amortize retrofit capital across larger volumes.
Hospital and clinic procurement of freeze-dried reconstitutable injectables is consolidating through centralized pharmacy frameworks and group purchasing organizations. This channel compression is displacing traditional wholesaler relationships in the United States and Germany. Specialty infusion centers and ambulatory surgery chains now specify powder presentations to reduce cold-chain burden and waste from expired refrigerated stock.
Freeze-Dried Powder Market Segmentation
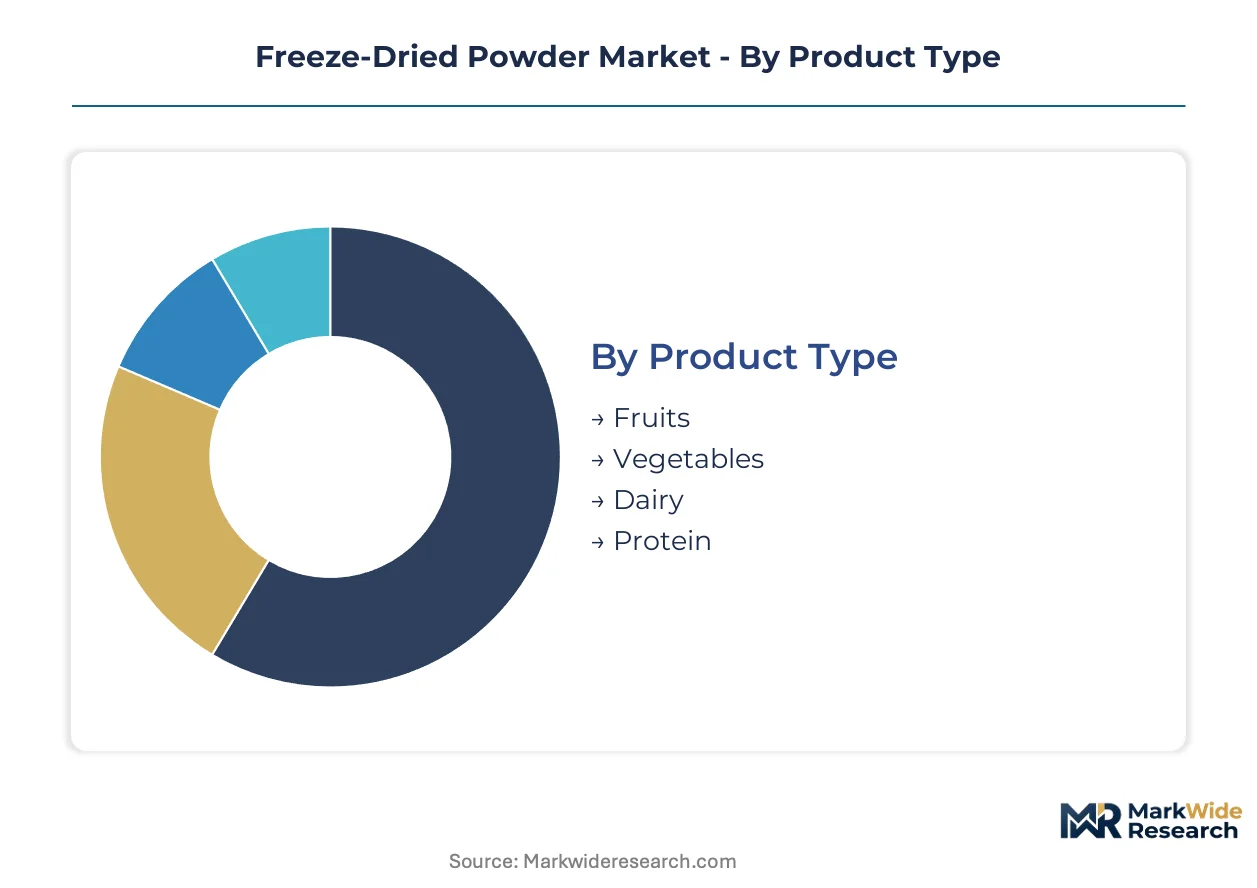
Freeze-dried powder markets fragment across preservation objectives, equipment architectures, and channel economics. Understanding these divisions clarifies where capital concentrates versus where margin erodes.
Product Type:
Mature commodity segments dominate volume throughput while protein isolates command premium positioning through sports nutrition channels.
- Fruits:Strawberries, blueberries, and tropical varieties undergo sublimation to preserve cellular structure for cereal inclusions and snack coatings. Demand concentrates in North American breakfast food manufacturing, though margin compression is acute due to Vietnamese and Thai supply expansion.
- Protein:Whey and plant-based isolates retain bioactive peptide fractions through controlled primary drying protocols. Sports nutrition brands in the United States and Germany specify ambient-stable powder formats to displace refrigerated ready-to-drink logistics.
- Vegetables:Peas, corn, and bell pepper segments serve soup and sauce manufacturers seeking clean-label ingredient declarations.
- Dairy:Milk powders and cheese cultures target emergency food programs and specialty baking applications with extended shelf-life requirements.
Fruits and vegetables handle the majority of throughput; protein is the fastest mover on share.
Application:
Regulatory intensity separates pharmaceutical-grade requirements from food-grade processing economics.
- Pharmaceuticals:Monoclonal antibodies and mRNA vaccines require validated lyophilization cycles with real-time release testing under FDA process analytical technology guidelines. Fill-finish contractors in Massachusetts and Switzerland anchor demand for isolator-integrated continuous systems.
- Food & Beverage:Instant coffee, probiotic cultures, and meal replacement powders drive volume through spray-dried and freeze-dried hybrid facilities. Nestlé and Kerry Group procurement specifications favor suppliers with dual-certification capabilities.
- Cosmetics:Hyaluronic acid and peptide powders for active skincare formulations utilize smaller-batch manifold equipment due to low-volume, high-value production runs.
- Pet Food:Raw-coated kibble and freeze-dried toppers for premium pet nutrition brands represent emerging demand outside human consumption channels.
Food and beverage absorbs the greatest raw material tonnage; pharmaceuticals deliver the steepest expansion trajectory.
Process Technology:
Equipment selection balances capital intensity against batch flexibility for multi-product versus dedicated manufacturing.
- Continuous:Real-time process analytical technology integration enables pharmaceutical manufacturers to compress cycle times from 72 hours to sub-24-hour residence. FDA guidance on real-time release testing accelerates adoption among biologics specialists with stable, high-volume product portfolios.
- Batch:Tray-based systems with validated cleaning protocols persist in contract manufacturing organizations serving orphan drug and clinical trial material production. Multi-suite facilities in Hyderabad and Bangalore leverage batch flexibility to capture fragmented biologics demand.
- Manifold:Research-scale and pilot operations utilize flask-based configurations for formulation development and stability screening.
- Tray:Legacy stainless-steel shelf systems dominate fruit and vegetable processing where equipment age exceeds 15 years and replacement capital is constrained.
Batch configurations retain the largest installed base; continuous systems are climbing the fastest on new capital deployment.
End User:
Channel structure determines packaging specifications, order minimums, and technical service requirements.
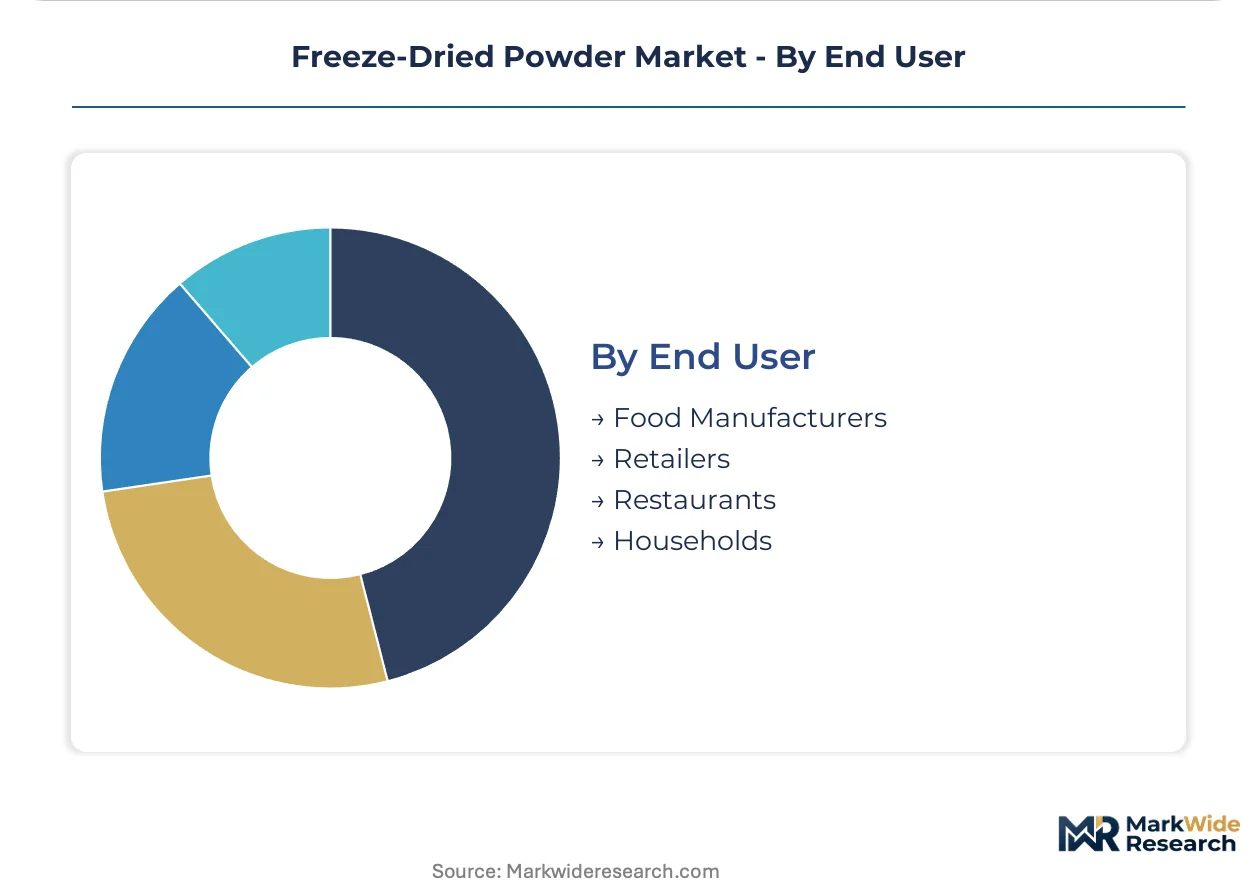
- Food Manufacturers:Cereal, confectionery, and prepared meal producers specify bulk super-sacks with moisture specifications below 3% for 24-month ambient stability. Procurement contracts typically run 12-36 months with volume commitments.
- Retailers:Private-label freeze-dried fruit snacks and emergency food kits require consumer-portion pouches with oxygen scavenger integration. Costco and REI category managers prioritize suppliers with SQF certification and domestic warehousing.
- Restaurants:Fine-dining and fast-casual chains utilize freeze-dried powders for sauce bases and garnish applications where kitchen labor constraints favor just-add-water reconstitution.
- Households:Direct-to-consumer camping meals and home food preservation systems represent niche demand through specialty outdoor retailers and e-commerce platforms.
Food manufacturers command the greatest procurement volume; retailers are expanding shelf space allocation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing organizations and pharmaceutical fill-finish specialists concentrate procurement authority across distinct national clusters, each shaped by local regulatory enforcement and energy pricing regimes.
United States
Massachusetts and North Carolina host the densest biologics fill-finish contractor networks, with FDA process analytical technology compliance timelines accelerating equipment replacement cycles. The FDA's real-time release testing guidance forces legacy tray-system retirement. Greater Boston CMOs are consolidating multi-suite facilities to amortize continuous lyophilization capital.
Germany
Specialty chemical and dairy powder processors drive demand for heat-recovery vacuum systems under EU Green Deal retrofit deadlines. The country's national energy efficiency directives pressure operators in Lower Saxony and Bavaria to adopt alternative refrigerants. Stuttgart-area engineering houses dominate production-scale freeze-dryer manufacturing, creating 18-month order backlogs.
Switzerland
Basel-region biologics manufacturers anchor premium pharmaceutical-grade demand, with Swissmedic validation requirements exceeding EMA baseline standards. The country's sterile manufacturing regulations mandate barrier technology upgrades through 2025. Vaud and Basel-Stadt cantons concentrate specialized lyophilization process engineering talent pools.
India
Hyderabad and Bangalore CDMOs are constructing dedicated lyophilization suites to capture biologics work migrating from Western cost bases. CDSCO fill-finish guidelines are tightening documentation requirements for export-bound freeze-dried injectables. Telangana's pharmaceutical cluster is attracting continuous technology equipment vendors seeking localized service presence.
Netherlands
Food-grade powder specialists in Noord-Brabant leverage dairy processing heritage for sports nutrition contract manufacturing. National green industrial transformation funds subsidize vacuum system heat recovery retrofits. Wageningen-area research institutions partner with equipment manufacturers on process intensification pilots.
Freeze-Dried Powder Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three strategic archetypes: diversified nutrition conglomerates with captive powder demand, specialized freeze-dryer engineering houses with equipment-service bundling, and contract manufacturers with multi-product batch flexibility. Competitive moves concentrate on capacity expansion in Indian pharmaceutical corridors and strategic partnerships between dairy processors and sports nutrition brands.
Within the diversified nutrition tier, Nestlé S.A. and Kerry Group plc represent integrated demand anchors spanning food-grade and pharmaceutical-grade specifications. DSM-Firmenich occupies a biotechnology-integrated position that streamlines upstream fermentation through downstream preservation. European Freeze Dry Ltd. exemplifies the specialist contract manufacturer archetype, serving fragmented demand across fruit, vegetable, and probiotic segments without captive brand volume.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Mercer Foods LLC |
| European Freeze Dry Ltd. |
| Chaucer Foods Ltd. |
| Van Drunen Farms |
| Döhler GmbH |
| Kerry Group plc |
| DSM-Firmenich |
| Thrive Life |
| Others |
Value Network & Pricing Analysis
Stuttgart-area engineering houses anchor pharmaceutical-grade freeze-dryer manufacturing, creating 18-24 month delivery backlogs that compress downstream pricing power for contract manufacturers competing on equipment access. Their dominance in production-scale vacuum systems allows selective order book management, pushing CMOs toward longer-term offtake commitments to secure capacity slots.
Pricing Analysis
Cost-plus contracts with energy indexation dominate pharmaceutical lyophilization services, linking fill-finish pricing to EU electricity benchmarks and refrigerant cost curves. Price differentiation separates FDA-validated isolator suites from standard batch configurations, with Swissmedic and EMA Annex 1 compliance tiers commanding substantial premia. Pricing pressure stems from Vietnamese and Thai fruit powder expansion eroding commodity segment returns. Food manufacturers exhibit acute price sensitivity, while biologics sponsors prioritize technical validation over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with European Freeze Dry Ltd., Kerry Group plc, and Hyderabad-based CDMOs building dedicated lyophilization suites. Supply draws from Germany, Italy, and India for equipment fabrication, with vacuum pump assemblies and stainless-steel shelf systems as critical components. Single-source vulnerability runs through German engineering houses for production-scale units. Distribution runs through centralized pharmacy frameworks and group purchasing organizations in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA process analytical technology mandates and EMA Annex 1 sterile manufacturing revisions create compliance barriers that favor incumbents with validated continuous systems and established quality dossiers.
For Market Incumbents:Pre-empt Indian CDMO encroachment by accelerating continuous technology deployment in Massachusetts and North Carolina biologics corridors. Secure orphan drug and clinical trial material volumes through batch flexibility in multi-suite configurations, insulating against pure-play continuous competitors. Prioritize backward integration into specialized excipient supply to capture margin pools currently held by DSM-Firmenich and Kerry Group.
For New Entrants and Emerging Players:Indian probiotic strain stabilization for veterinary and functional food channels offers the most penetrable white space, with demand migrating outside human pharmaceutical validation requirements. Target sports nutrition contract manufacturing in the Netherlands and Germany, where dairy processing heritage enables dual-certification capabilities that Nestlé and Kerry procurement specifications favor. Lead with EU Green Deal retrofit incentives as a capital-light entry mechanism.
For Investors and Strategic Acquirers:Long-term, this sits as a consolidation play because specialized lyophilization process engineering talent concentrates in Switzerland, Germany, and Massachusetts, creating acquisition scarcity for technical capabilities. Target mid-cap contract manufacturers with validated multi-product batch suites and established biologics sponsor relationships. Watch for CDSCO documentation requirement tightening as the signal for Indian export-bound freeze-dried injectable quality tiering.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Lyophilization Technology Deployment | FDA process analytical technology mandates accelerate real-time release testing adoption among biologics specialists. |
| Indian Contract Manufacturing Expansion | Hyderabad and Bangalore CDMOs capture biologics fill-finish work migrating from Western cost bases. |
| EU Green Deal Vacuum System Retrofit | German and Dutch operators qualify for national green industrial transformation funds through heat recovery upgrades. |
| Probiotic Strain Stabilization Diversification | Freeze-dried bacterial concentrates for veterinary applications access underpenetrated demand outside human pharma channels. |
| Centralized Pharmacy Framework Penetration | Group purchasing organizations in the United States and Germany displace traditional wholesaler relationships for reconstitutable injectables. |
Research Methodology
A standing panel of lyophilization process engineers, pharmaceutical fill-finish contractors, sterile manufacturing validation specialists, and sports nutrition procurement directors provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA process analytical technology guidance documents, EMA Annex 1 sterile manufacturing revisions, EU Green Deal implementation reports, and CDSCO fill-finish export guidelines. Bottom-up capacity assessments across Stuttgart engineering houses and Hyderabad CDMOs triangulated against top-down biologics pipeline forecasts.
Scenario bracketing anchored projections across regulatory compliance timelines, energy price volatility bands, and equipment delivery backlog variations. Segmentation modeling spanned product type, application, process technology, and end-user channel, with additional granularity on pharmaceutical-grade versus food-grade certification tiers. CAGRs derived from installed base turnover rates and new capital deployment patterns, with specific inputs including monoclonal antibody pipeline volumes and sports nutrition protein powder demand trajectories.
Practitioners should monitor EU electricity benchmark movements, FDA real-time release testing enforcement intensity, and Indian CDSCO documentation requirement evolution for early signals of forecast revision. Quarterly review of German engineering house order backlogs, Swissmedic validation timeline extensions, and centralized pharmacy framework procurement consolidation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Chemical Absorbent Pads Market