
 Coke Dry Quenching Market | 2026-2036
Coke Dry Quenching Market Size, Share, and Industry Trends Forecast 2026-2036
Coke Dry Quenching Market Analytics
Aftermarket service revenue for refractory lining replacement and waste-heat boiler refurbishment is reconfiguring margin pools away from initial equipment sales. Thyssenkrupp Industrial leverages its European installed base to sustain long-term service contracts. Nippon Steel Engineering anchors its position through captive engineering ties to parent steelworks. Paul Wurth competes on blast furnace-coke plant integration expertise across emerging market deployments.
Coke dry quenching (CDQ) is a steelmaking auxiliary process wherein hot coke from ovens is cooled inertly using nitrogen circulated through a closed chamber, recovering sensible heat at temperatures exceeding 800°C to generate steam or power rather than quenching with water. The technology eliminates phenolic wastewater discharge while improving coke mechanical strength for blast furnace burden. Closed cycle systems dominate existing installations due to mature reliability, though hybrid cycle configurations claim the fastest-growing segment as operators seek flexible heat export to district heating or power grids. Steel manufacturers represent the deepest end-user pool, with waste heat recovery applications capturing expanding margin share as energy prices elevate payback economics.
China's MEE enforces GB standards on coking emissions that effectively mandate CDQ retrofits for legacy wet quenching plants. The EU F-Gas Regulation and ETS carbon pricing framework shape equipment specifications for European steelmakers pursuing Scope 1 reductions. India's CEA technical standards for coke oven batteries increasingly reference dry quenching as benchmark practice for new capacity. Stakeholders must monitor how carbon border adjustment mechanisms redefine project feasibility across import-dependent steel economies.
Market Dynamics
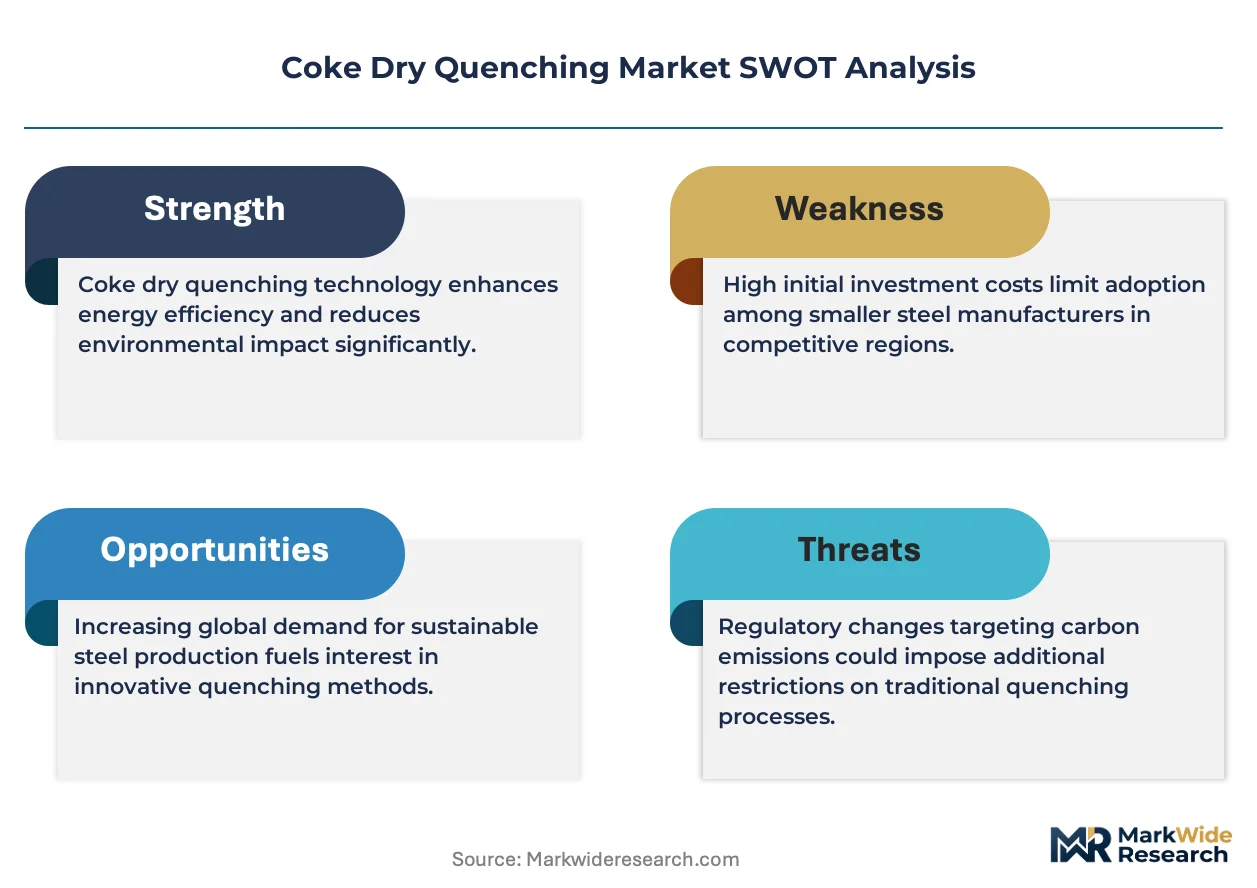
Steelmakers face binding deadlines to eliminate wet quenching as China's MIIT dual carbon goals and EU ETS carbon pricing force capital redeployment toward heat recovery infrastructure. This regulatory compression is accelerating replacement cycles for legacy coke oven batteries across integrated blast furnace corridors.
Growth Catalysts
- China's GB Emission Standards:The MEE enforces particulate and phenol discharge limits that effectively prohibit wet quenching retrofits, mandating CDQ installation for operating licenses in Shanxi and Hebei steel clusters.
- Blast Furnace Burden Quality:Dry-quenched coke delivers superior mechanical strength and lower moisture content, enabling coke rate reductions of 10-15 kg per tonne of hot metal in high-productivity furnaces.
- Energy Recovery Economics:Waste heat boilers generating steam for power or district heating now achieve payback periods under five years where natural gas prices exceed regional baselines.
Market Restraints
- Refractory Input Volatility:High-alumina brick and silicon carbide prices fluctuate with bauxite export restrictions from Guinea and Chinese smelter capacity curbs, compressing project margins.
- Engineering Concentration:CDQ system design and commissioning expertise concentrates among three European and two Japanese licensors, creating bottleneck risks for concurrent project waves.
- Biomass Coke Substitution:Pilot injection of biocarbon at blast furnace tuyeres in European steelworks threatens long-term coke demand intensity per tonne of crude steel.
Strategic Opportunities
- India's CEA Technical Standards:New coke oven battery guidelines reference dry quenching as benchmark practice, opening greenfield deployment at JSW and Tata expansion sites.
- Hybrid Cycle Configurations:Systems exporting heat to municipal district heating networks in Rhine-Ruhr and Nordic industrial zones capture premium pricing for seasonal flexibility.
- Aftermarket Service Contracts:Refractory lining replacement and waste-heat boiler refurbishment generate recurring revenue streams from Europe's installed base of 1980s-vintage units.
Industry Challenges
- Specialized Welding Certification:ASME Section IX and EN ISO 9606 qualifications for high-temperature pressure vessel fabrication face acute shortage in emerging market construction pools.
- Legacy System Integration:Retrofitting CDQ into 1960s-era coke oven batteries requires custom chamber geometry adaptation, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coke Dry Quenching Market |
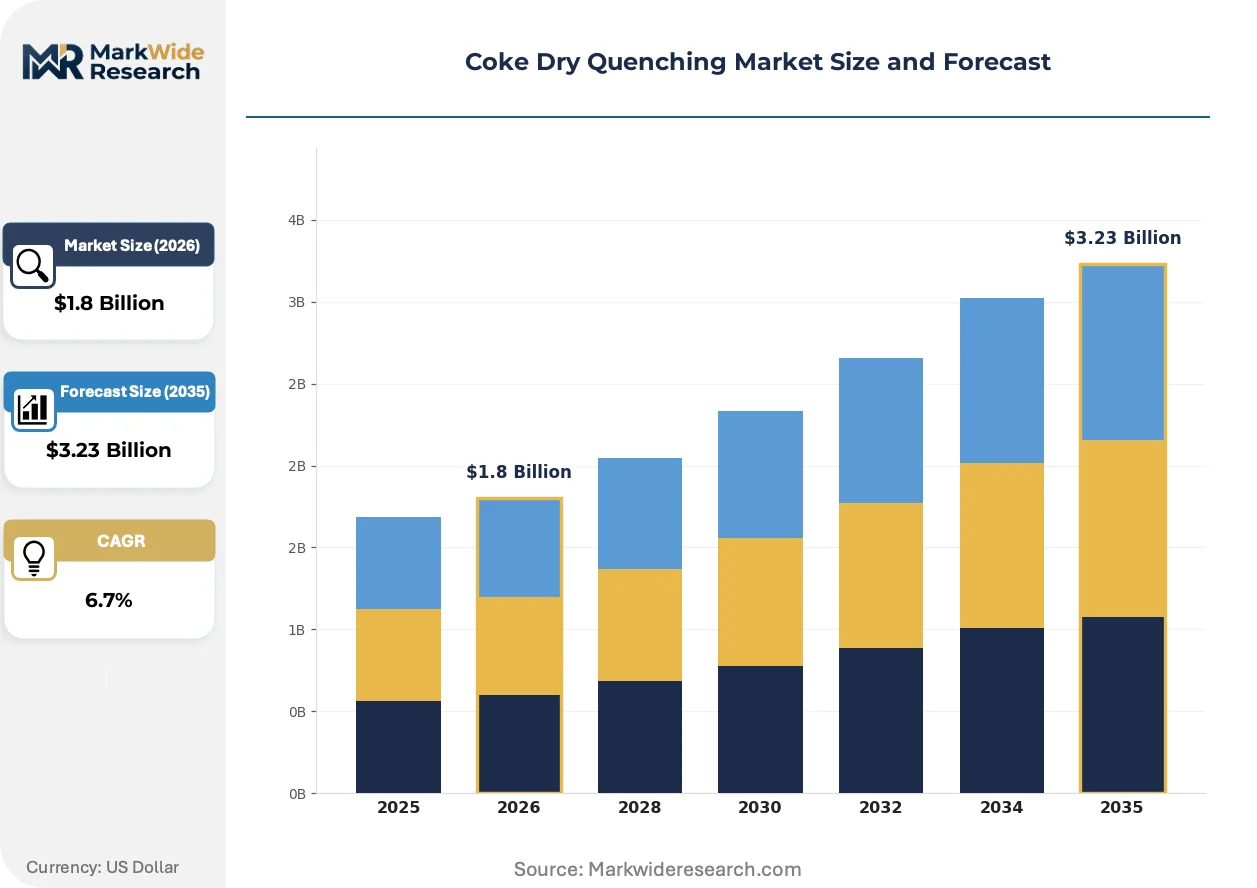
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Closed Cycle, Open Cycle, Hybrid Cycle, Heat Recovery End User: Steel Manufacturers, Aluminum Producers, Foundries, Cement Plants Application: Coke Production, Energy Generation, Waste Heat Recovery, Process Heating Installation Type: On-site, Off-site, Modular, Centralized |
| Companies Covered | Thermax Global, Thyssenkrupp Industrial, Nippon Steel Engineering, JFE Engineering Corporation, Danieli Corus, JP Steel Plantech, FUJI ELECTRIC, ACRE Coking & Refractory Engineering, Paul Wurth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coke Dry Quenching Market Evolving Landscape
Equipment architecture and service delivery models are converging around modular, export-flexible configurations that decouple coke production from captive power generation. This shift responds to grid interconnection opportunities and carbon accounting pressures.
Closed-cycle nitrogen cooling systems are migrating from standard steam-generation configurations toward hybrid architectures with variable heat export to district heating networks. Scandinavian steelmakers in Oxelösund and Luleå pioneer this flexibility. The technology is migrating from single-purpose energy recovery toward multi-commodity output platforms that arbitrage seasonal power and heat price spreads.
The EU F-Gas Regulation and ETS carbon pricing framework now shape CDQ equipment specifications for Scope 1 reduction commitments. Steelmakers must document verified emission reductions to maintain free allocation quotas. European integrated producers in the Netherlands and Germany are responding by specifying higher-efficiency waste heat boilers with guaranteed steam output coefficients.
Steelmakers increasingly unbundle after-sales service contracts from initial equipment procurement, creating standalone multi-year agreements for refractory management and boiler tube replacement. Equipment vendors now compete on predictive maintenance platforms rather than capital cost alone. This pattern concentrates in East Asian coastal clusters where operating cost discipline outweighs first-cost minimization.
Coke Dry Quenching Market Segmentation
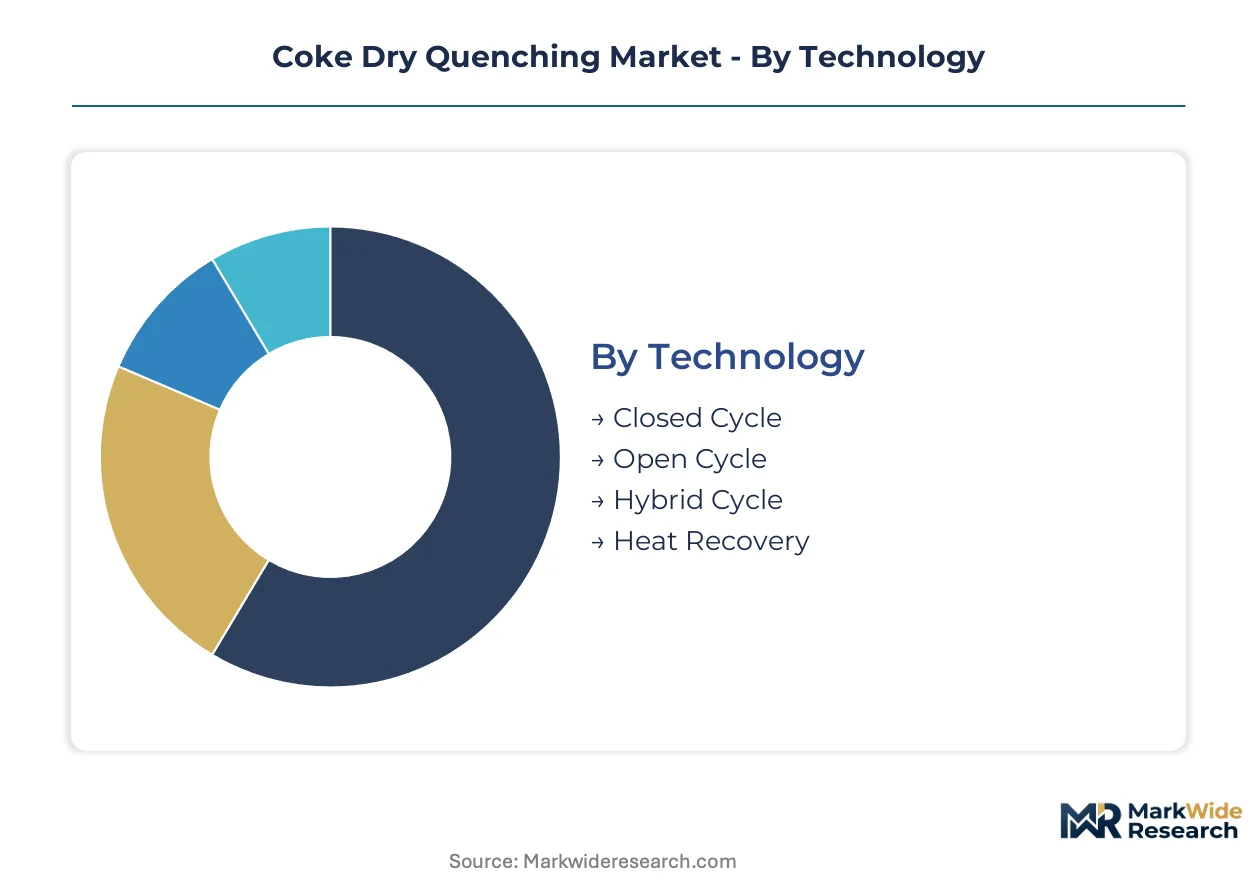
Segmentation reveals how CDQ technology providers capture value across divergent customer economics. Steelmakers prioritize heat recovery efficiency while aluminum producers and cement operators seek modular retrofit solutions for captive power generation.
Technology:
After-sales service intensity varies sharply across technology types, with closed-cycle systems demanding scheduled refractory replacement every 4-6 years while hybrid configurations require continuous calibration of heat export valves.
- Closed Cycle:Nitrogen circulates through sealed cooling chambers to recover coke sensible heat above 800°C for steam generation. Demand concentrates in China's Shanxi and Hebei steel clusters where MIIT emission standards mandate wet quenching replacement. Refractory lining replacement cycles generate predictable aftermarket revenue streams.
- Hybrid Cycle:Configurations enable variable heat export to district heating networks or power grids through switchable heat exchanger arrays. Scandinavian steelmakers in Oxelösund and Luleå pioneer this flexibility to arbitrage seasonal energy price spreads. This architecture commands premium pricing for operational adaptability.
- Open Cycle:Direct nitrogen venting to atmosphere simplifies system design for smaller coke oven batteries with limited heat recovery infrastructure.
- Heat Recovery:Dedicated waste heat boiler subsystems optimize steam output coefficients for European steelmakers documenting Scope 1 reductions under EU ETS frameworks.
By volume, Closed Cycle leads. By growth pace, Hybrid Cycle is climbing the fastest.
End User:
Customer type determines project scale and contracting structure, with steel manufacturers driving multi-unit deployments while foundries and cement plants favor phased modular installations.
- Steel Manufacturers:Integrated blast furnace operators represent the deepest demand pool, deploying CDQ to improve coke mechanical strength and eliminate phenolic wastewater discharge. Rhine-Ruhr and Nordic industrial corridors face binding EU Green Deal compliance deadlines.
- Aluminum Producers:Smelters with captive anode production integrate CDQ for process heat integration and carbon footprint reduction in emissions-intensive primary metal production.
- Foundries:Cupola furnace operators in India deploy compact CDQ units for metallurgical coke quality improvement under CEA technical standards.
- Cement Plants:Kiln operators explore co-processing applications where dry-quenched coke residual heat supplements clinker production energy requirements.
Steel Manufacturers dominate current installations. Aluminum Producers show the steepest expansion trajectory as smelter decarbonization accelerates.
Application:
Application focus shifts with energy economics, where waste heat recovery now captures expanding margin share as natural gas price volatility improves project payback calculations.
- Coke Production:Core application ensuring metallurgical coke quality for blast furnace burden through controlled inert cooling.
- Energy Generation:Waste heat boilers producing steam for captive power or grid export achieve sub-five-year payback where regional gas prices exceed baselines.
- Waste Heat Recovery:District heating integration in German and Dutch industrial zones generates seasonal revenue premiums through flexible heat export contracts.
- Process Heating:Direct thermal integration with adjacent industrial processes reduces primary fuel consumption in integrated steel and chemical complexes.
Coke Production anchors installed base. Waste Heat Recovery is gaining share fastest as energy price arbitrage opportunities expand.
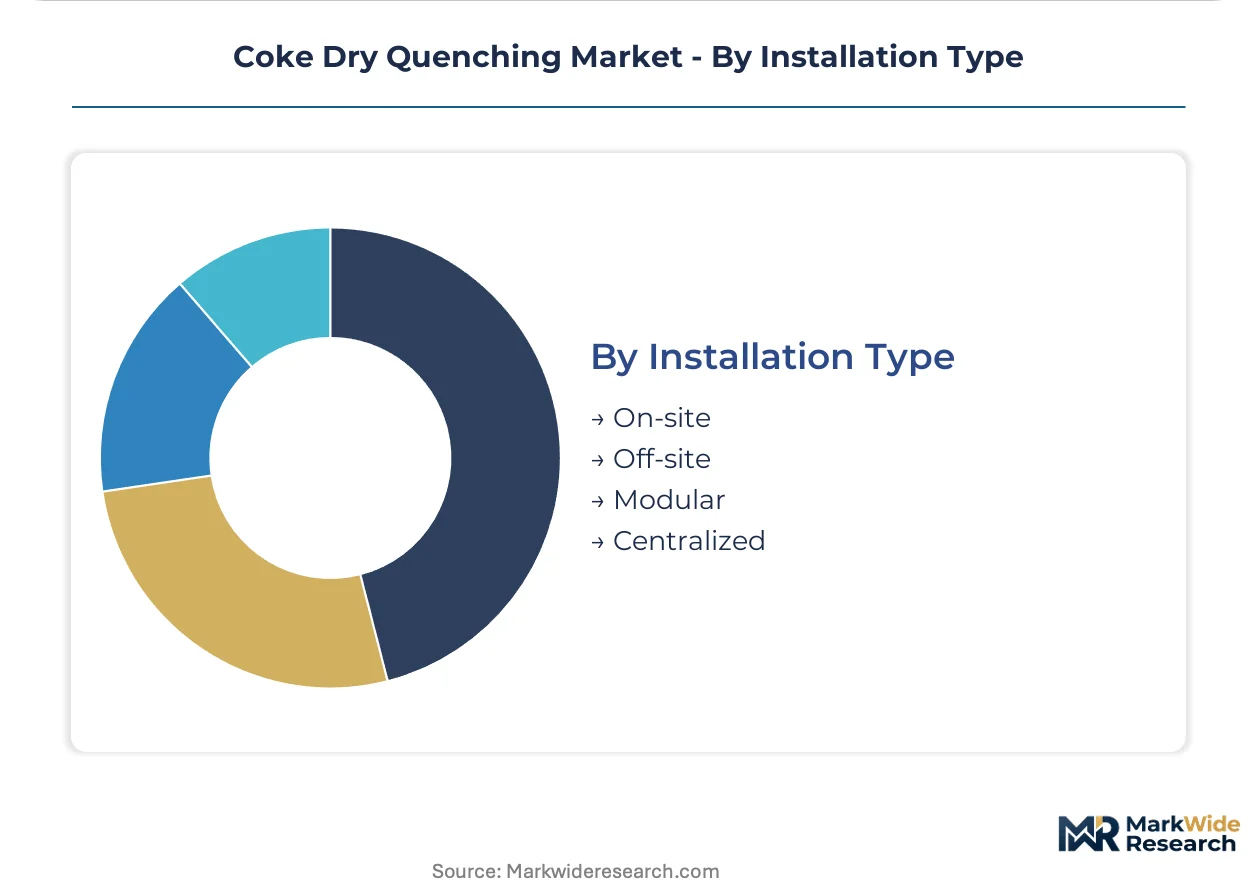
Installation Type:
Installation configuration reflects site constraints and capital deployment preferences, with modular systems penetrating brownfield sites where legacy coke oven geometry limits standard equipment fit.
- On-site:Integrated construction adjacent to existing coke oven batteries minimizes coke transport distance and heat loss.
- Off-site:Centralized cooling facilities serve multiple coke oven batteries through insulated conveyor systems in sprawling steelworks complexes.
- Modular:Pre-fabricated chamber and boiler skids reduce commissioning timelines for 1960s-era battery retrofits requiring custom geometry adaptation.
- Centralized:Shared infrastructure serving multiple steelmakers concentrates specialized welding certification requirements and maintenance expertise.
On-site deployment leads by volume. Modular installation is expanding most quickly as retrofit activity accelerates across aging European and East Asian coke oven fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys CDQ primarily for regulatory compliance and wastewater elimination, while European steelmakers emphasize heat export flexibility and carbon accounting documentation. This consumption-mix differential shapes equipment specification priorities across geographies.
China
Shanxi and Hebei steel clusters drive equipment demand as MIIT dual carbon goals force wet quenching replacement. MEE enforcement of GB emission standards mandates CDQ installation for operating license renewal. Tangshan and Taiyuan industrial corridors face binding deadlines for legacy coke oven battery modernization.
Germany
Rhine-Ruhr steel producers prioritize hybrid cycle configurations for district heating arbitrage. EU F-Gas Regulation and ETS carbon pricing framework shape waste heat boiler specifications. Duisburg and Dortmund integrated works document Scope 1 reductions to maintain free allocation quotas.
Japan
Coastal steelworks in Chiba and Kawasaki anchor closed-cycle demand for blast furnace burden quality improvement. METI industrial efficiency standards reinforce heat recovery infrastructure investment. Nagoya and Kitakyushu clusters sustain aftermarket service intensity from 1980s-vintage installations.
India
JSW and Tata expansion sites at Jamshedpur and Hazira open greenfield deployment opportunities. CEA technical standards for new coke oven batteries reference dry quenching as benchmark practice. Gujarat and Maharashtra industrial zones face emerging environmental compliance pressure for coking capacity.
South Korea
Posco and Hyundai Steel operations at Pohang and Dangjin integrate CDQ for energy security and coke quality optimization. MFDS-aligned industrial emissions frameworks shape equipment procurement criteria. Yeosu petrochemical-steel complexes explore process heating integration for captive thermal demand.
Coke Dry Quenching Market Competitive Landscape
Capability concentration sits with engineering licensors holding blast furnace-coke plant integration expertise; scale advantage sits with diversified industrial conglomerates leveraging captive steelworks relationships. The vendor base stratifies across three tiers: European-Japanese technology licensors, steelmaker-affiliated engineering subsidiaries, and emerging Chinese fabricators. Dominant competitive moves include strategic partnerships for emerging market deployment and technology licensing agreements that transfer operational know-how.
Among steelmaker-affiliated engineering subsidiaries, Nippon Steel Engineering and JFE Engineering Corporation exemplify the captive engineering model where parent steelworks relationships anchor project pipelines. Thyssenkrupp Industrial occupies a position within the European licensor tier, leveraging installed base proximity for aftermarket service contract renewal. These three companies represent distinct archetypes: Japanese vertical integration, German service-depth positioning, and technology licensing specialization.
| Leading Market Players |
|---|
| Thermax Global |
| Thyssenkrupp Industrial |
| Nippon Steel Engineering |
| JFE Engineering Corporation |
| Danieli Corus |
| JP Steel Plantech |
| FUJI ELECTRIC |
| ACRE Coking & Refractory Engineering |
| Paul Wurth |
| Others |
Value Network & Pricing Analysis
Commodity volatility in high-alumina refractories determines both project margin compression and supplier consolidation patterns across CDQ procurement tiers. Bauxite export restrictions from Guinea and Chinese smelter capacity curbs simultaneously widen pricing spreads between premium European-Japanese licensors and emerging fabricators while forcing engineering buyers toward long-term offtake structures.
Pricing Analysis
Long-term engineering-procurement-construction contracts dominate CDQ system acquisition, with steelmakers locking in fixed-price arrangements across 18-36 month project horizons to hedge refractory input volatility. Price differentiation rests on welding certification density and heat recovery efficiency guarantees, with EU-specified systems commanding premiums over baseline configurations. Cost compression in mid-tier equipment is intensifying because Chinese fabricators are absorbing margin erosion to secure installed base footholds. Foundry operators in India exhibit highest price sensitivity due to limited capital deployment flexibility, while integrated European steelmakers prioritize total cost of ownership over first-cost minimization.
Supply Chain Analysis
Extended payment terms from European engineering licensors to Chinese pressure-vessel fabricators are restructuring working capital flows across the CDQ equipment pipeline. Manufacturing concentration centers on Germany, Japan, and China for specialized chamber fabrication and waste-heat boiler assembly. Raw material sourcing draws from Guinean bauxite corridors for refractory alumina, Chinese silicon carbide smelters for high-turance linings, and Nordic specialty steel mills for pressure-grade alloys. Single-source vulnerability concentrates in ASME-certified welding labor pools for high-temperature pressure vessel construction. Distribution runs through steelmaker-affiliated engineering subsidiaries and independent EPC contractors serving emerging market greenfield deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CDQ market sits at an early-cycle expansion phase as regulatory mandates in China and the EU force replacement waves across legacy wet quenching infrastructure. Penetration tailwinds from India's CEA technical standards and hybrid cycle adoption in European district heating corridors justify capacity positioning ahead of project pipeline maturation.
For Market Incumbents: Insulate service revenue streams by converting European 1980s-vintage installed base into captive refractory replacement contracts before independent maintenance providers capture aftermarket share. Biocarbon substitution threats at European blast furnace tuyeres demand accelerated R&D into heat recovery efficiency guarantees that document Scope 1 reductions for ETS compliance. Backward integration into high-alumina refractory recycling capabilities secures margin defense against bauxite supply disruptions. For New Entrants and Emerging Players: Build out modular CDQ skids for 1960s-era battery retrofits in Germany and Japan where legacy chamber geometry forces custom adaptation timelines that incumbent licensors disfavor. India's JSW and Tata expansion corridors offer the most penetrable greenfield geography given CEA technical standard enforcement gaps that favor flexible equipment suppliers. Go-to-market positioning should emphasize commissioning speed over capital cost to capture brownfield retrofit urgency. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors engineering licensors with captive welding certification pipelines and blast furnace-coke plant integration expertise. Long-term viability over the coming decade rests on aftermarket service intensity rather than equipment shipment volumes. Acquisition targets should display dense European installed base proximity for refractory contract renewal. The signal to watch is carbon border adjustment mechanism implementation timelines across import-dependent steel economies, which would accelerate CDQ retrofit feasibility calculations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cycle Configuration Development | Enables seasonal heat arbitrage for Rhine-Ruhr steelmakers under EU ETS frameworks. |
| Refractory Recycling Capability Investment | Reduces bauxite dependency exposure for European CDQ service providers. |
| Modular Skid Pre-fabrication Scale-up | Compresses commissioning timelines for aging Japanese and German battery retrofits. |
| Aftermarket Service Contract Unbundling | Captures recurring revenue from predictive maintenance platforms in East Asian clusters. |
| District Heating Integration Partnership | Secures premium pricing for Scandinavian steelmakers in Oxelösund and Luleå corridors. |
Research Methodology
Desk research of engineering licensor technical documentation, national emission standard filings with China's MEE and India's CEA, and EU ETS allocation records preceded structured interviews with CDQ procurement directors at integrated steelworks, aftermarket service heads at European engineering subsidiaries, and refractory supply managers at high-alumina brick manufacturers. Primary fieldwork with plant engineers in Shanxi and Hebei steel clusters, blast furnace operations specialists in the Rhine-Ruhr corridor, and EPC contractors serving Indian greenfield sites was validated against customs data for pressure vessel imports, SEC filings from diversified industrial conglomerates, and project announcement databases tracking coke oven battery modernization timelines. Bottom-up unit deployment counts across technology configurations were triangulated against top-down steel production forecasts and regulatory compliance deadline schedules.
The analytical framework held carbon pricing trajectories and emission standard enforcement intensity as fixed boundary conditions across the projection horizon while varying technology adoption curves by regional energy price environments and district heating infrastructure maturity. Segmentation modeling incorporated technology type, end-user industry, application focus, and installation configuration dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from installed base replacement cycles and greenfield capacity addition schedules. Industry-specific forecast inputs included MIIT dual carbon goal implementation pacing, EU F-Gas Regulation equipment specification evolution, and biomass coke substitution pilot program outcomes at European steelworks.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fabricators or accelerated biocarbon substitution at European blast furnaces would shift outcomes beyond modeled ranges. Specific risk factors encompass refractory input cost spikes from Guinean supply disruptions, ASME welding certification labor shortages in emerging market construction pools, and carbon border adjustment mechanism implementation that redefines project feasibility across import-dependent steel economies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Paper Drying Systems Market