
 Chemical Absorbent Pads Market | 2026-2036
Chemical Absorbent Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Absorbent Pads Market Outlook
A shift from single-source to multi-source supply of meltblown polypropylene is rebalancing procurement strategies across the chemical absorbent pads sector. New Pig Corporation leverages its direct-channel model to sustain pricing transparency for industrial buyers. 3M Company anchors its position through backward integration into nonwoven substrate production. Oil-Dri Corporation of America specializes in mineral-based absorbents, competing against synthetic alternatives in refinery applications.
Chemical absorbent pads are engineered nonwoven or woven media, typically constructed from polypropylene meltblown fibers or cellulose matrices, designed to selectively capture hydrocarbons, corrosive chemicals, or universal spills through capillary action and surface retention. Their primary industrial purpose is to contain and recover liquid spills in compliance with workplace safety and environmental discharge protocols. Heavy-duty pads dominate margin pools in petrochemical and aviation maintenance settings where saturation capacity determines replacement frequency. Polypropylene-based materials lead volume production due to oleophilic selectivity and incineration disposal compatibility, while cellulose alternatives occupy price-sensitive maintenance tasks in food processing environments.
EPA SPCC regulations mandate secondary containment and prompt spill response, directly shaping absorbent pad specifications for facilities storing oil above threshold quantities. OSHA 29 CFR 1910.1200 hazard communication standards require employers to maintain appropriate absorbents for chemical classifications present on-site. FDA food contact regulations govern cellulose pad compositions deployed in food processing end uses. Stakeholders must monitor evolving state-level PFAS restrictions that could disqualify certain fluorinated treatments from absorbent pad surface coatings.
Market Dynamics
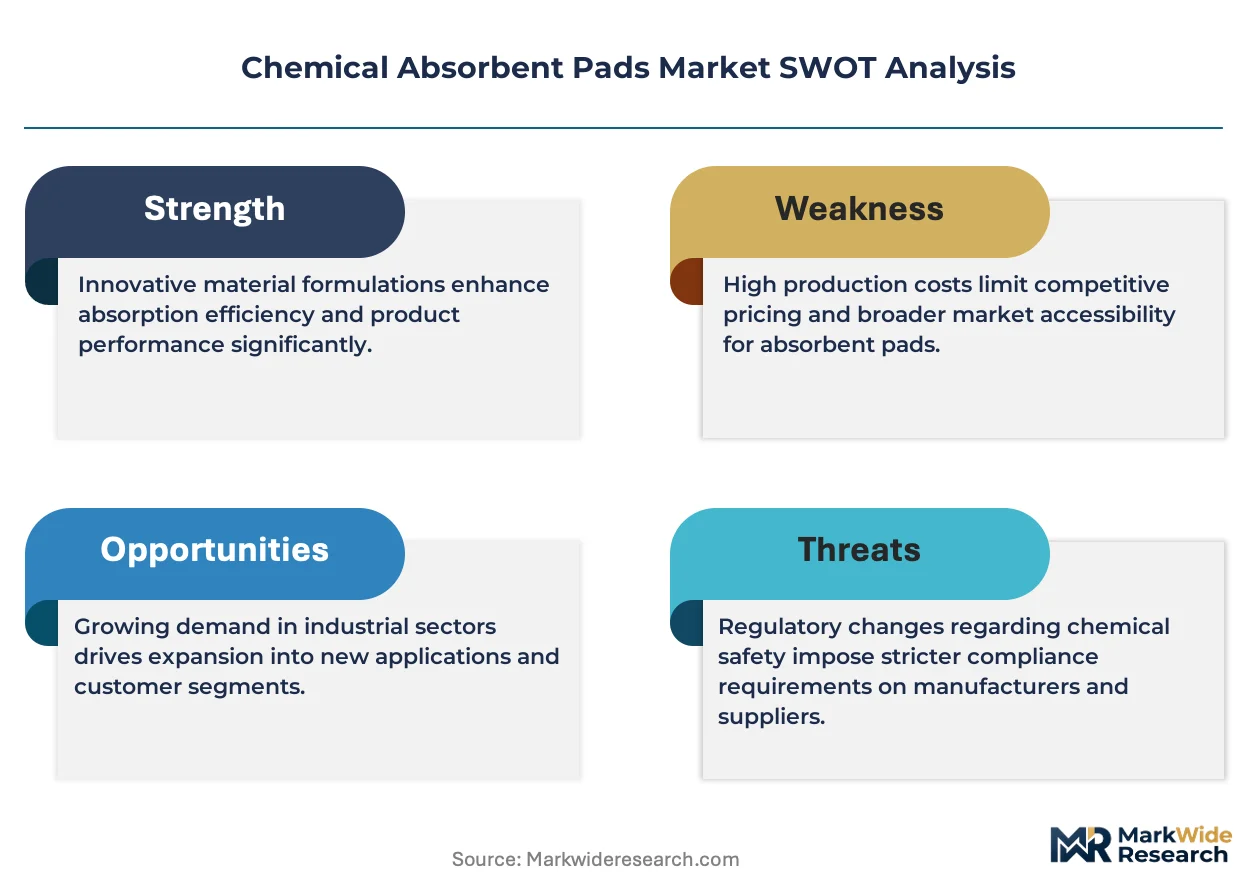
Polypropylene meltblown fiber supply concentration is forcing chemical absorbent pad manufacturers to diversify substrate sourcing as single-source dependencies expose procurement teams to allocation risk during resin price volatility cycles.
Growth Catalysts
- EPA SPCC spill prevention mandates:Facilities storing oil above threshold quantities must maintain secondary containment and prompt response absorbents, creating baseline demand for hydrocarbon-selective pads.
- Rhine-Ruhr chemical corridor expansion:Germany's concentrated petrochemical processing clusters drive absorbent pad procurement for maintenance and emergency response protocols.
- Incineration-compatible disposal pathways:Polypropylene-based absorbents align with waste-to-energy infrastructure, reducing landfill dependency for saturated materials.
Market Restraints
- Propylene monomer price volatility:Feedstock cost swings compress margin stability for meltblown polypropylene converters serving the absorbent pad supply chain.
- Mineral-based absorbent substitution:Oil-Dri Corporation's clay and diatomite alternatives compete on price in refinery maintenance applications where selectivity requirements are less stringent.
- REACH substance restriction timelines:ECHA evaluation of surface treatment chemistries creates formulation uncertainty for European-manufactured pads with fluorinated coatings.
Strategic Opportunities
- Aviation MRO aftermarket penetration:Aircraft maintenance facilities represent underpenetrated demand for aviation-grade absorbent pads with high saturation-to-weight ratios.
- Food processing cellulose pad upgrading:FDA food contact compliance positions cellulose alternatives for premium positioning against synthetic competitors in sanitary applications.
- Direct-channel procurement platforms:New Pig Corporation's transparent pricing model demonstrates how industrial buyers bypass distributor markups through manufacturer-direct relationships.
Industry Challenges
- PFAS contamination liability exposure:State-level restrictions on fluorinated compounds in Massachusetts and Maine force rapid reformulation of surface-treated pads.
- Nonwoven substrate qualification timelines:New meltblown suppliers require 12-18 month validation cycles before securing placement in safety-critical spill response specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Absorbent Pads Market |
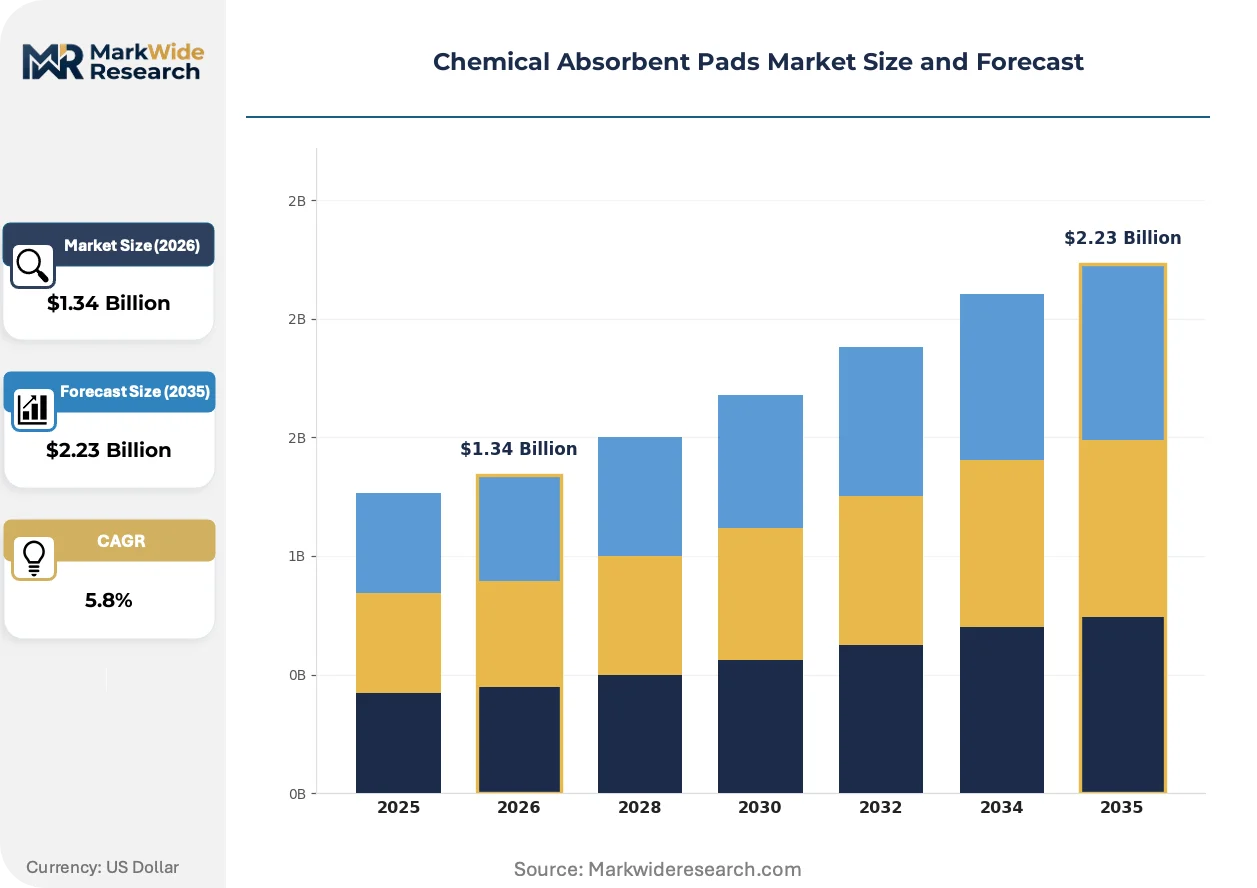
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Pads, Medium-Duty Pads, Light-Duty Pads, Utility Pads Material: Polypropylene, Cellulose, Compressed Wool, Fibre Application: Industrial Spills, Laboratory Use, Oil Spills, Maintenance Tasks End User: Manufacturing, Healthcare, Automotive, Food Processing |
| Companies Covered | Novipax LLC, New Pig Corporation, 3M Company, Johnson Matthey, Ansell Ltd., Brady Corporation, Oil-Dri Corporation of America, Meltblown Technologies Inc., Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Absorbent Pads Market Strategic Shifts
Bio-based absorbent formulations and smart saturation indicators are reshaping product development priorities as buyers demand verifiable sustainability credentials alongside functional performance in spill containment applications.
Multilayer composite absorbent structures are consolidating technical performance advantages by bonding meltblown polypropylene capture layers to spunbond reinforcement substrates. Petrochemical terminals and aviation fueling operations are accelerating adoption of these laminates to extend pad service life in high-volume leak scenarios. The technology is consolidating supplier power toward converters with in-house lamination capabilities and away from single-layer commodity producers.
OSHA 29 CFR 1910.1200 hazard communication enforcement is intensifying absorbent pad specification requirements at multi-site industrial facilities. Employers must now maintain absorbents matched to specific chemical classifications present on-site, expanding SKU complexity for distributors. Refinery and chemical processing operators in Texas and Louisiana are responding by consolidating vendor relationships with suppliers offering classification-matched product portfolios.
Industrial buyers are compressing switching cycles as direct procurement platforms displace traditional distribution channels. Maintenance supervisors at manufacturing facilities now compare real-time pricing and technical specifications through manufacturer portals rather than relying on distributor sales representatives. This behavioral shift concentrates most visibly in the automotive assembly sector, where just-in-time spill response inventory management favors transparent, rapid-replenishment supply relationships.
Chemical Absorbent Pads Market Segmentation
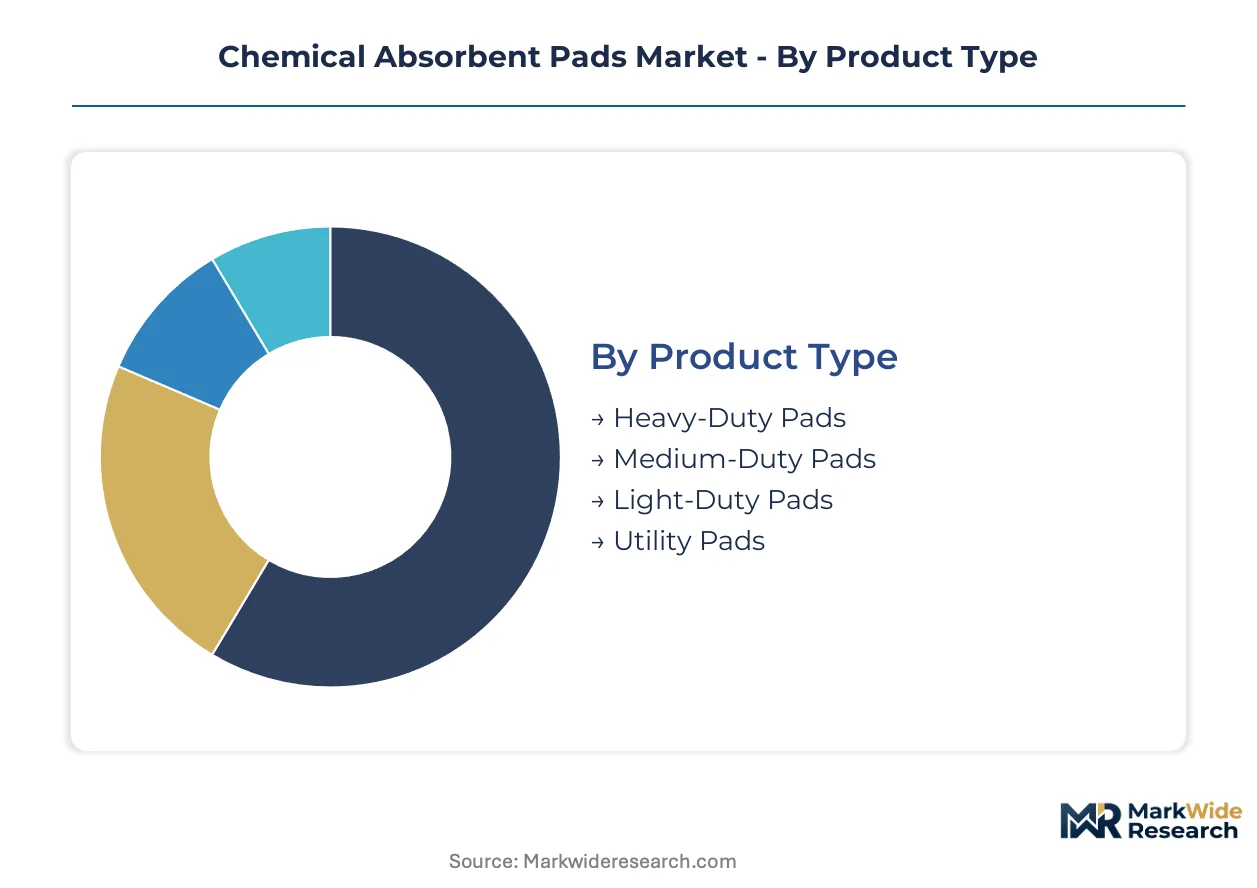
Segmentation in the chemical absorbent pads market tracks how material science, duty specifications, and end-use compliance requirements split procurement patterns. Buyers select pads based on saturation capacity, chemical selectivity, and disposal pathway compatibility rather than commodity pricing alone.
Product Type:
Polypropylene meltblown density and fiber diameter specifications determine the duty classification hierarchy across industrial procurement specifications.
- Heavy-Duty Pads:Constructed from high-basis-weight meltblown polypropylene with reinforced spunbond backing, these pads absorb 20-30 times their dry weight in hydrocarbons. Petrochemical terminals in Texas and aviation fueling operations at Hartsfield-Jackson Atlanta International Airport specify these for high-volume leak scenarios where extended service life reduces labor replacement costs.
- Medium-Duty Pads:Standard meltblown construction targets general manufacturing maintenance where moderate saturation capacity balances unit cost against replacement frequency. Automotive assembly plants in Michigan and Ohio standardize on this tier for routine hydraulic fluid containment.
- Light-Duty Pads:Lower-density polypropylene or cellulose blends for incidental drip control in low-risk environments.
- Utility Pads:General-purpose absorbent sheets without chemical selectivity, deployed in janitorial and non-critical maintenance settings.
Heavy-duty pads lead on scale; medium-duty pads lead on momentum as manufacturing facilities optimize inventory carrying costs.
Material:
Substrate chemistry governs selectivity, disposal compliance, and total cost of ownership across spill response protocols.
- Polypropylene:Oleophilic thermoplastic fibers manufactured through meltblown extrusion deliver selective hydrocarbon capture with water repellency. Incineration compatibility with waste-to-energy infrastructure in Germany and the Netherlands positions this material for facilities seeking landfill diversion, though propylene monomer price volatility compresses converter margins.
- Cellulose:Recycled paper pulp matrices offer universal absorbency at lower unit cost, with biodegradation pathways suited to food processing environments. FDA food contact compliance enables deployment in USDA-inspected poultry and dairy facilities where synthetic fiber contamination risks trigger regulatory scrutiny.
- Compressed Wool:Natural protein fiber pads with high initial absorbency for marine and coastal spill applications.
- Fibre:Synthetic or natural fiber blends occupying price-sensitive maintenance segments with lower performance requirements.
Polypropylene dominates volume throughput; cellulose gains share fastest in food safety-regulated environments.
Application:
Spill scenario severity and regulatory trigger thresholds determine pad specification requirements across facility types.
- Industrial Spills:EPA SPCC-mandated secondary containment drives procurement for facilities storing oil above 1,320-gallon thresholds. Refinery operators in Louisiana and chemical processors along the Rhine-Ruhr corridor maintain stocked inventories sized to worst-case discharge volumes, with pad specifications tied to facility response plan approvals.
- Oil Spills:Marine and pipeline rupture response requires high-buoyancy pads with rapid deployment packaging. Coast Guard-certified absorbents for Prince William Sound and Gulf of Mexico response stockpiles emphasize weight-to-saturation ratios for helicopter transport.
- Laboratory Use:Small-format pads for chemical fume hood and benchtop containment in research institutions.
- Maintenance Tasks:Routine equipment servicing in non-regulated environments with minimal chemical exposure risk.
Industrial spills anchor procurement volume; oil spill response represents the steepest expansion trajectory as pipeline infrastructure ages.
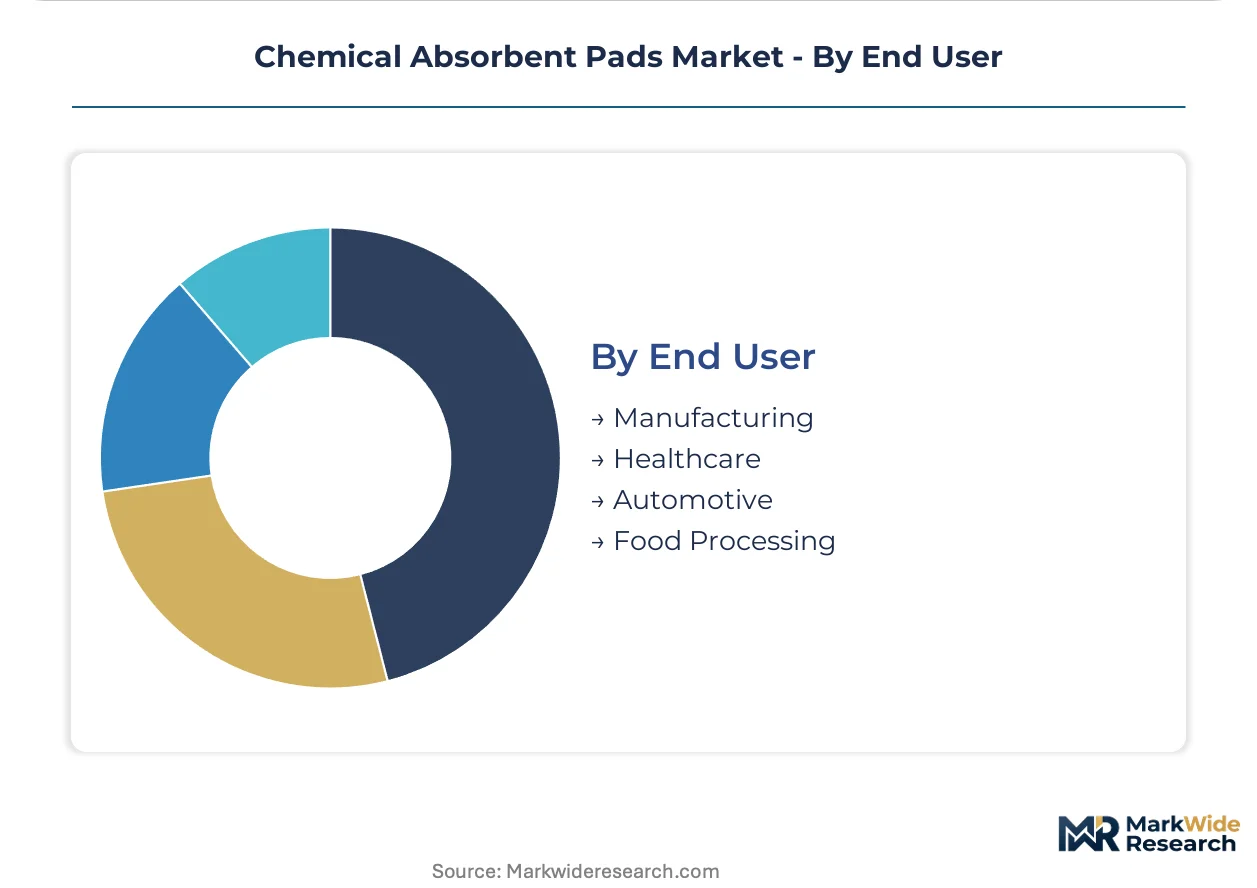
End User:
Facility type determines regulatory overlay, chemical exposure profiles, and inventory turnover velocity for absorbent pad suppliers.
- Manufacturing:OSHA 29 CFR 1910.1200 hazard communication compliance requires employers to stock absorbents matched to specific chemical classifications present on-site. Multi-site industrial operators in the US Midwest consolidate vendor relationships with suppliers offering classification-matched product portfolios and direct-channel replenishment.
- Food Processing:FDA food contact regulations and USDA facility inspection protocols govern cellulose pad compositions. Sanitary design requirements in meatpacking plants and dairy processing facilities position absorbent procurement within broader hygiene supply contracts.
- Automotive:Assembly and aftermarket maintenance operations with just-in-time inventory management favoring rapid-replenishment supply relationships.
- Healthcare:Pharmaceutical manufacturing and hospital laboratory settings with stringent chemical handling protocols.
Manufacturing leads on absolute consumption; food processing climbs fastest as FDA enforcement intensifies sanitary facility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors procurement intensity for chemical absorbent pads, with petrochemical clusters driving maintenance and emergency response inventory cycles across Germany's industrial heartland.
United States
EPA SPCC spill prevention mandates and OSHA workplace safety standards create baseline demand from refineries in Texas and Louisiana. Facilities storing oil above threshold quantities maintain stocked inventories sized to worst-case discharge volumes. Hartsfield-Jackson Atlanta International Airport specifies aviation-grade pads for fueling operations.
Germany
Waste-to-energy infrastructure in the Netherlands and Germany positions polypropylene-based absorbents for landfill diversion. ECHA evaluation of fluorinated surface treatments creates formulation uncertainty for domestic manufacturers. The Rhine-Ruhr corridor's concentrated chemical processing clusters drive absorbent pad procurement for maintenance protocols.
China
Industrial expansion along the Yangtze River Delta generates demand for spill containment materials in chemical manufacturing facilities. MEE environmental discharge protocols tighten compliance requirements for facilities handling hazardous liquids. Shanghai and Ningbo port operations stock marine response absorbents for pipeline and vessel rupture scenarios.
Japan
METI industrial safety guidelines shape absorbent pad specifications for precision manufacturing facilities. Automotive assembly plants in Toyota City and Yokohama standardize on medium-duty pads for hydraulic fluid containment. JIS standards govern product quality benchmarks for domestic suppliers.
India
Petrochemical complexes in Gujarat and Maharashtra drive procurement for refinery maintenance and emergency response. Central Pollution Control Board discharge regulations mandate secondary containment systems at facilities storing hazardous chemicals. Reliance Industries' Jamnagar complex represents concentrated demand for high-saturation capacity pads.
Chemical Absorbent Pads Market Competitive Environment
Global majors compete with regional champions across substrate sourcing and direct-channel distribution strategies. The vendor base organizes around meltblown polypropylene converters, mineral-based absorbent specialists, and diversified nonwoven manufacturers serving safety-critical applications. Three archetypes dominate: backward-integrated resin producers, direct-channel industrial distributors, and specialty mineral absorbent formulators. Capacity expansion and strategic partnerships represent the primary competitive moves as manufacturers secure qualified substrate supply.
Within the direct-channel tier, New Pig Corporation exemplifies pricing transparency models that bypass traditional distributor markups. 3M Company anchors the backward-integrated archetype through captive nonwoven substrate production. Oil-Dri Corporation of America occupies the mineral-based specialist position, competing against synthetic alternatives in refinery maintenance segments where selectivity requirements vary.
| Leading Market Players |
|---|
| Novipax LLC |
| New Pig Corporation |
| 3M Company |
| Johnson Matthey |
| Ansell Ltd. |
| Brady Corporation |
| Oil-Dri Corporation of America |
| Meltblown Technologies Inc. |
| Kimberly-Clark Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up industrial distributors have consolidated regional absorbent pad suppliers across the US Midwest and Germany's Rhine-Ruhr corridor, tightening pricing discipline through volume aggregation while pressing converters for exclusive supply terms that lock out competing distributors.
Pricing Analysis
Propylene monomer cost pass-through dominates pricing dynamics for polypropylene-based pads, with converters adjusting contract rates quarterly to protect margin stability against resin volatility. Three-tier pricing structure across heavy-duty aviation-grade, standard industrial, and light-duty maintenance levels reflects certification grade and saturation capacity differentiation. Cost compression in medium-duty segments is intensifying because mineral-based alternatives from Oil-Dri Corporation compete aggressively on unit price in refinery maintenance. Food processing buyers exhibit highest price sensitivity due to cellulose pad commoditization, while aviation MRO operators accept premium positioning for weight-optimized performance.
Supply Chain Analysis
Meltblown polypropylene fiber supply rests on concentrated extrusion capacity in Germany, the United States, and China, with Rhineland-Palatinate and Texas Gulf Coast petrochemical corridors feeding specialized nonwoven converters. Raw material dependencies span propylene monomer, spunbond reinforcement substrates, and fluorinated surface treatment chemistries. Single-source vulnerability persists where 12-18 month qualification timelines lock buyers into incumbent substrate relationships. Distribution runs through direct-channel procurement platforms displacing traditional industrial distributors, with New Pig Corporation's transparent pricing model demonstrating manufacturer-direct capture of automotive and aviation maintenance accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA SPCC spill prevention mandates and OSHA hazard communication standards create durable baseline demand that expands with enforcement intensity.
For Market Incumbents: Anchor market position through backward integration into meltblown substrate production, mirroring 3M Company's captive nonwoven strategy that insulates margin stability from propylene monomer volatility. Secure exclusive supply partnerships with Rhineland-Palatinate resin producers to block competitor access to qualified fiber sources. Counter mineral-based substitution threats by emphasizing incineration disposal advantages in waste-to-energy corridors. For New Entrants and Emerging Players: Smart saturation indicator technology offers a technology-first wedge into aviation MRO aftermarket segments where real-time pad replacement signaling commands premium positioning. Target food processing cellulose pad upgrading opportunities where FDA compliance certification barriers favor nimble specialists over legacy synthetic producers. Pursue direct-channel procurement platform partnerships with automotive assembly facilities seeking transparent, rapid-replenishment supply relationships. For Investors and Strategic Acquirers: Diversified nonwoven manufacturers with safety-critical applications expertise are the most active acquirer in this space, seeking absorbent pad specialists to deepen industrial portfolio exposure. The 5-10 year viability window favors targets with in-house lamination capabilities and established aviation certification. Monitor PFAS restriction enforcement in Massachusetts and Maine as the critical signal for reformulation investment cycles and stranded asset risk in surface-treated pad inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Meltblown Substrate Production | Captive fiber supply from Rhineland-Palatinate resin corridors locks in margin stability against propylene volatility. |
| Aviation MRO Certification Investment | FAA-compliant saturation-to-weight ratios at Hartsfield-Jackson Atlanta operations open premium aftermarket positioning. |
| Direct-Channel Procurement Platform Launch | Manufacturer-transparent pricing displaces distributor markups in automotive just-in-time inventory relationships. |
| PFAS-Free Surface Treatment Reformulation | ECHA REACH evaluation timelines and state-level restrictions in Maine force rapid coating chemistry transitions. |
| Food Contact Compliance Certification | FDA cellulose pad approvals enable premium positioning in USDA-inspected poultry and dairy facility contracts. |
Study Parameters
Coverage spans the United States, Germany, China, and India, with primary inputs from each market combining interviews with plant managers at petrochemical terminals, procurement leads at aviation MRO facilities, distribution channel partners serving industrial maintenance accounts, and technical R&D directors at nonwoven converters. Secondary validation draws from EPA SPCC facility filings, ECHA REACH substance evaluations, customs and trade data tracking polypropylene fiber imports, and SEC 10-K disclosures from diversified industrial suppliers. Bottom-up demand modeling triangulates against top-down market sizing across duty classifications and material chemistries.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with CAGRs derived from segment-level modeling of heavy-duty aviation-grade, medium-duty manufacturing, and light-duty maintenance pad procurement. Segmentation dimensions include material chemistry, duty specification tier, end-use regulatory environment, and geographic waste-to-energy infrastructure availability. Industry-specific forecast inputs incorporate propylene monomer price cycle assumptions and PFAS restriction implementation timelines.
The model holds under stable regulatory enforcement intensity; deviation in EPA SPCC audit frequency or ECHA fluorinated compound restriction acceleration would shift demand trajectories. Forecasts reflect documented assumptions about qualification timeline durations and direct-channel adoption velocity. A small set of triggers—propylene supply disruption, aviation MRO consolidation, and state-level PFAS enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Filtration and Drying Equipment Market