
 Regenerative Thermal Oxidizer [RTO] Market | 2026-2036
Regenerative Thermal Oxidizer [RTO] Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Thermal Oxidizer [RTO] Market Analytics
A capital-intensity divergence between in-house ceramic media production and outsourced regenerative bed sourcing is reorganizing competitive tiers across the RTO landscape. Dürr Aktiengesellschaft leverages captive manufacturing of structured heat-exchange media to command premium positioning in large-format refinery installations. CECO Environmental Corp. anchors its portfolio through aftermarket service contracts that sustain recurring revenue across installed base expansions. John Zink Hamworthy Combustion LLC dominates North American project bundling by integrating burner systems with oxidizer skids.
A regenerative thermal oxidizer is an air pollution control device that destroys volatile organic compounds and hazardous air pollutants through high-temperature combustion, typically operating between 760°C and 1100°C with ceramic media beds that recover 85-97% of combustion energy. Its primary industrial purpose is to enable process facilities to meet emission limits while minimizing supplemental fuel consumption through thermal recovery. Gas-fired systems occupy the largest installed base due to lower operating costs where natural gas infrastructure exists, while electric configurations are gaining traction in jurisdictions with carbon pricing mechanisms that penalize direct combustion. Chemical processing applications generate the most intensive specification requirements because stream variability demands adaptive control architectures, whereas waste management deployments prioritize throughput reliability over precision modulation.
The US EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act that mandate RTO deployment for specific source categories, while the EU Industrial Emissions Directive imposes Best Available Techniques benchmarks that shape product design for European installations. China's MEE administers increasingly stringent VOC emission limits in key manufacturing zones that redirect procurement toward higher-efficiency regenerative systems. Stakeholders must monitor how diverging carbon border adjustment mechanisms between trading blocs alter the total cost of ownership calculus for cross-border facility operators.
Market Dynamics
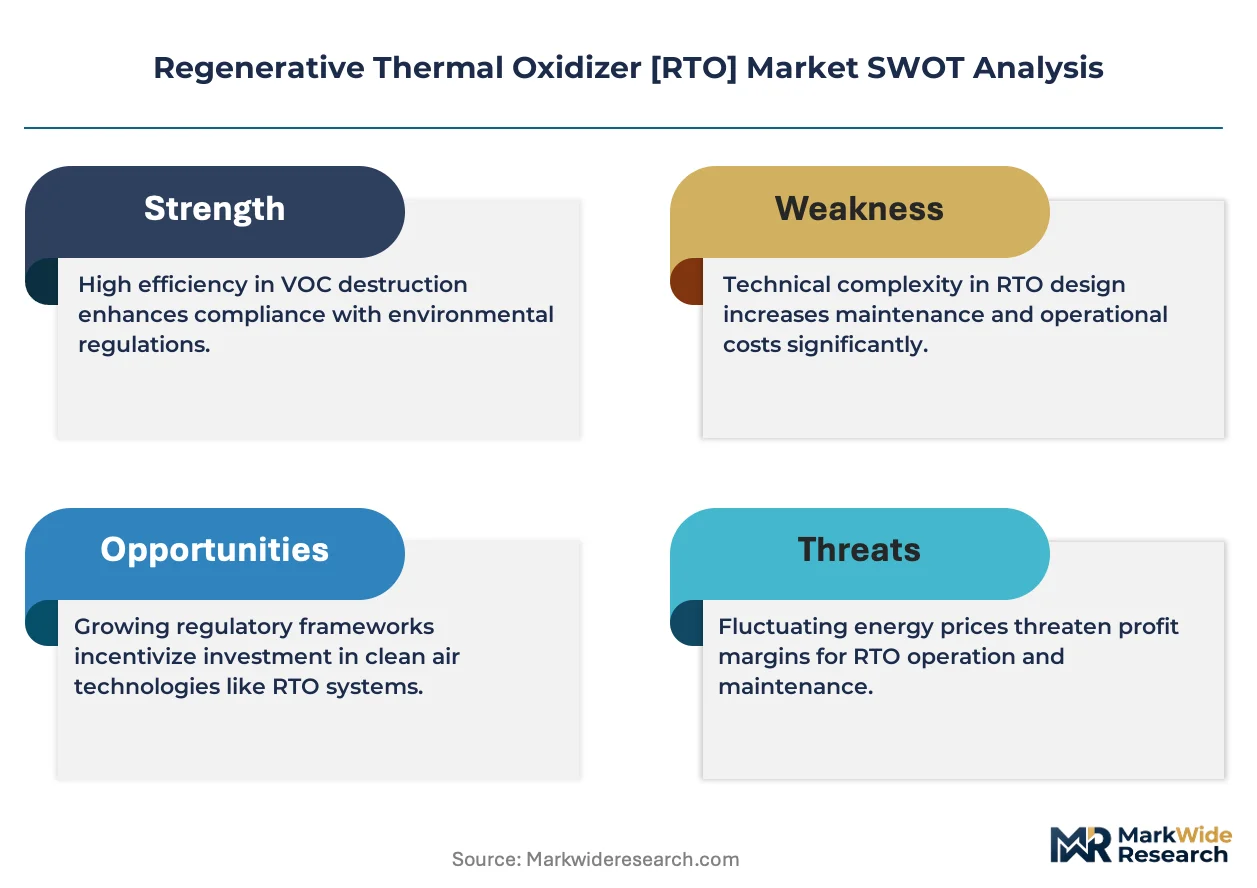
EPA Maximum Achievable Control Technology mandates are compressing procurement timelines for chemical processors, forcing simultaneous capacity expansion and efficiency upgrades that favor modular RTO architectures over custom-built systems.
Growth Catalysts
- EPA MACT enforcement:The Clean Air Act's Maximum Achievable Control Technology standards mandate RTO deployment for specific VOC-emitting source categories, creating non-discretionary demand across petrochemical and coating operations.
- Ceramic media thermal efficiency:Structured heat-exchange materials now recover 95 percent-plus of combustion energy, slashing supplemental fuel requirements and shortening payback periods for capital-intensive installations.
- US Gulf Coast cluster density:Concentrated petrochemical corridor development generates economies of scale for aftermarket service networks, lowering lifecycle ownership costs and accelerating replacement cycles.
Market Restraints
- Refractory ceramic supply concentration:High-purity alumina and silicon carbide sourcing concentrates among limited specialty ceramic producers, exposing project timelines to raw material allocation constraints.
- Natural gas price volatility:Gas-fired RTO operating economics fluctuate with North American Henry Hub pricing, compressing margin predictability for continuous-process operators.
- Electric configuration capex premiums:Grid-powered oxidizer systems carry 40-60 percent higher installed costs versus gas-fired equivalents, limiting penetration in jurisdictions without carbon pricing mechanisms.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU and prospective US carbon tariffs on embedded emissions create competitive pressure for export-oriented manufacturers to adopt lower-carbon abatement technologies.
- Modular skid-mounted systems:Pre-engineered RTO packages reduce field construction duration and enable redeployment across multi-site operators, opening mid-market chemical processing segments.
- Aftermarket service unbundling:Independent service providers are capturing ceramic media replacement and burner refurbishment contracts previously held by original equipment manufacturers.
Industry Challenges
- Combustion control systems integration:Adaptive control architectures for variable VOC stream composition require scarce process automation expertise, extending commissioning timelines.
- Refractory degradation prediction:Ceramic media lifecycle forecasting lacks standardized diagnostic protocols, forcing conservative replacement schedules that inflate maintenance spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Thermal Oxidizer [RTO] Market |
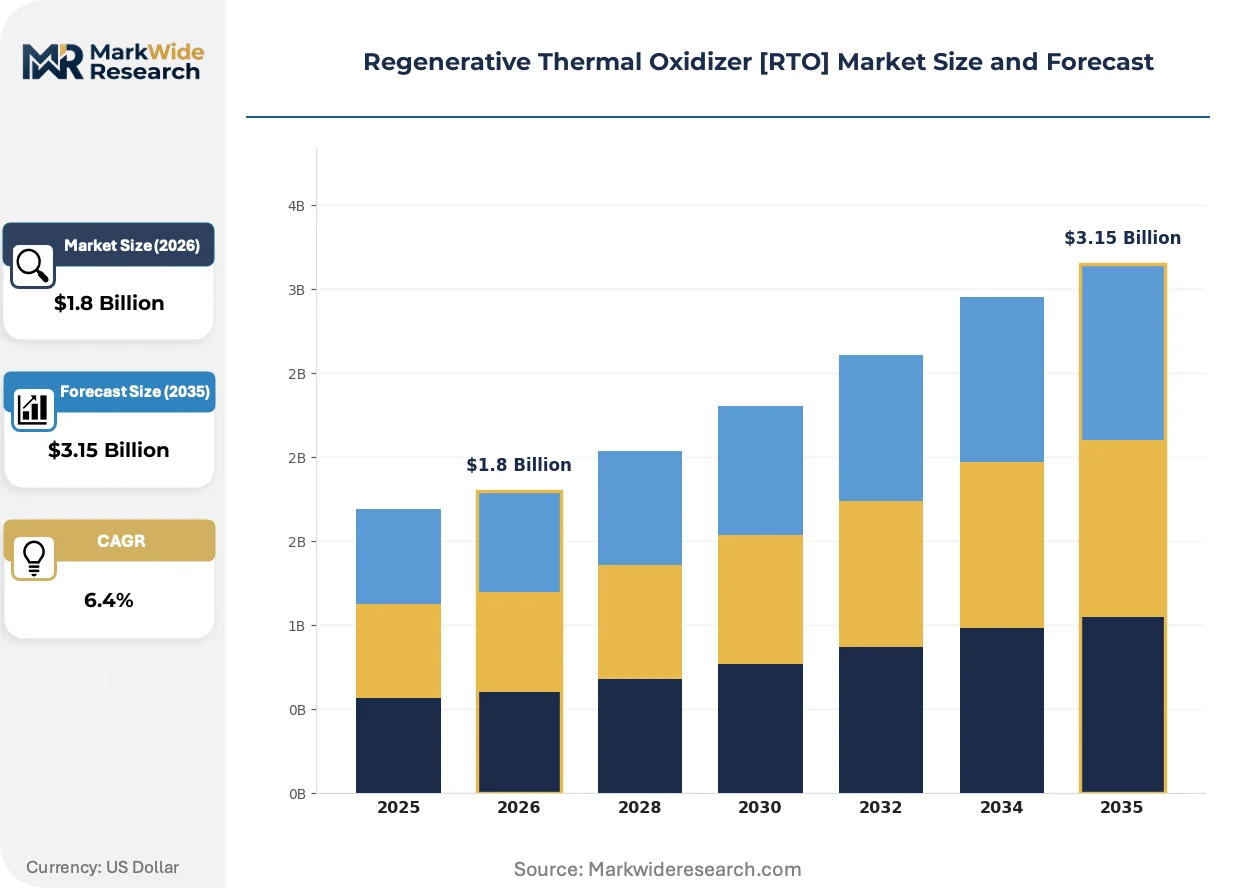
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gas-Fired, Electric, Dual-Fuel, Thermal Oxidizers Application: Chemical Processing, Oil Refining, Waste Management, Food Production End User: Manufacturing, Pharmaceuticals, Aerospace, Automotive Technology: Catalytic Oxidation, Direct Flame, Mixed Mode, Air Pollution Control |
| Companies Covered | TANN Corporation, Air Clear LLC, Anguil Environmental Systems, Inc., Eisenmann SE, Alliance Corporation, CECO Environmental Corp., John Zink Hamworthy Combustion LLC, Catalytic Products International, Dürr Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Thermal Oxidizer [RTO] Market Evolving Landscape
Ceramic heat-exchange media innovations and control system digitization are compressing the performance gap between standardized and engineered-to-order RTO systems, enabling new procurement models across process industries.
Structured ceramic media with engineered channel geometries is supplanting random-packed saddles and spheres in regenerative beds. Refinery operators in the US Gulf Coast corridor are specifying these materials for new-build projects exceeding 50,000 scfm capacity. The shift is compressing thermal recovery system footprints by 30 percent while enabling higher cycle frequencies that reduce NOx formation.
China's Ministry of Ecology and Environment (MEE) is tightening VOC emission limits in the Yangtze River Delta and Pearl River Delta manufacturing zones. The regulatory pressure is redirecting procurement toward higher-efficiency regenerative systems with dual-chamber configurations. Domestic chemical producers are responding by pre-qualifying European and North American RTO suppliers for technology transfer partnerships.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-market coating and printing operations. Third-party financiers are acquiring RTO assets and charging per-ton VOC destruction fees, transferring operational risk from processors to specialized lessors. The model is gaining traction in Germany and the Netherlands where environmental liability regulations incentivize outsourced compliance management.
Regenerative Thermal Oxidizer [RTO] Market Segmentation
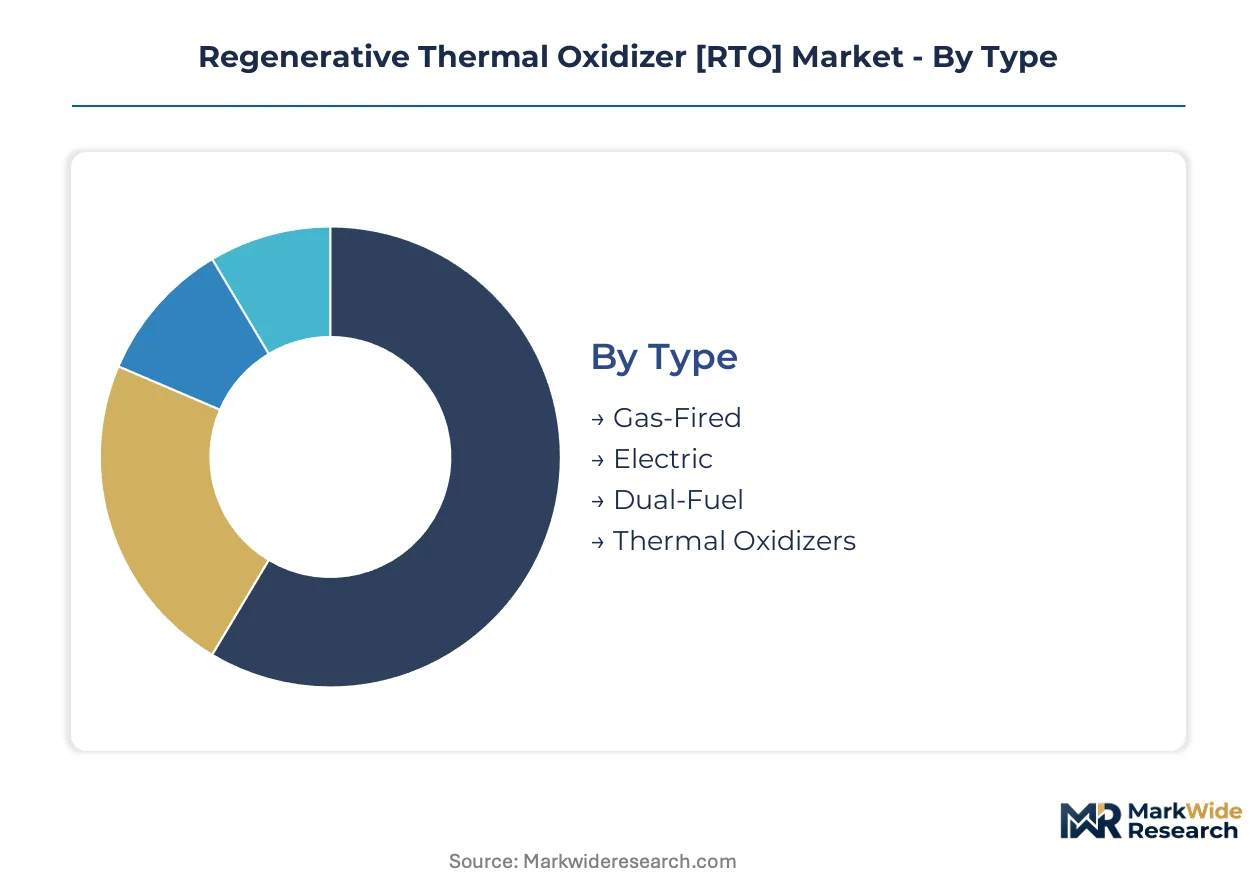
RTO procurement patterns diverge sharply across fuel types, applications, and end-user industries, with each segment presenting distinct thermal efficiency requirements and regulatory compliance pressures. Understanding these divisions enables targeted positioning for modular versus custom-engineered system architectures.
Type:
Gas-fired configurations dominate domestic installations across the US Gulf Coast petrochemical corridor, while electric systems find stronger traction in export-oriented European markets subject to carbon border adjustment mechanisms.
- Gas-Fired:Natural gas burners deliver the lowest operating cost per ton of VOC destroyed where pipeline infrastructure exists. Chemical processors in Texas and Louisiana specify these systems for continuous-duty refinery applications, though Henry Hub price volatility compresses margin predictability for operators.
- Electric:Grid-powered heating elements eliminate direct combustion emissions and qualify for renewable energy credits in jurisdictions with aggressive decarbonization mandates. German automotive coating facilities are procuring these units ahead of prospective EU carbon tariffs on embedded emissions.
- Dual-Fuel:Configurations allow fuel switching between natural gas and propane or fuel oil for redundancy in critical applications.
- Thermal Oxidizers:Non-regenerative designs serve intermittent-duty applications where capital constraints outweigh thermal efficiency priorities.
Gas-fired holds the largest share; momentum sits with electric configurations in carbon-priced markets.
Application:
Specification intensity varies by process variability, with chemical processing demanding adaptive control architectures while waste management prioritizes throughput reliability over precision modulation.
- Chemical Processing:Variable VOC stream composition from batch reactors and distillation columns requires sophisticated combustion control systems with real-time oxygen trim. EPA MACT enforcement for petrochemical source categories is compressing procurement timelines and favoring modular architectures over custom builds.
- Oil Refining:Sulfur-laden streams and high particulate loads necessitate corrosion-resistant refractory materials and integrated scrubber stages. Refinery operators in the US Gulf Coast corridor are specifying structured ceramic media for new-build projects exceeding 50,000 scfm capacity.
- Waste Management:Landfill gas and digester biogas applications emphasize uptime reliability over thermal efficiency optimization.
- Food Production:Bakeries and snack processing facilities generate lower-concentration ethanol and oil vapor streams suitable for compact regenerative units.
Chemical processing commands premium pricing; waste management applications are climbing fastest on biogas infrastructure expansion.
End User:
Customer scale and compliance liability exposure determine contracting models, with pharmaceutical and aerospace buyers favoring equipment-as-a-service arrangements while automotive manufacturers bundle RTO procurement with broader environmental compliance programs.
- Manufacturing:Mid-market coating and printing operations are adopting third-party financed RTO assets with per-ton VOC destruction fee structures. The model transfers operational risk to specialized lessors in Germany and the Netherlands where environmental liability regulations incentivize outsourced compliance management.
- Pharmaceuticals:Solvent recovery from active pharmaceutical ingredient synthesis generates high-value waste streams that justify capital-intensive regenerative systems with heat recovery for process integration.
- Aerospace:Paint hangar emissions and composite curing operations require explosion-proof configurations with LEL monitoring.
- Automotive:Assembly plant paint shops generate large-volume, low-concentration streams suited to three-chamber RTO designs with minimal pressure fluctuation.
Manufacturing represents the broadest installed base; pharmaceuticals show the steepest expansion trajectory on solvent-intensive biologics manufacturing growth.
Technology:
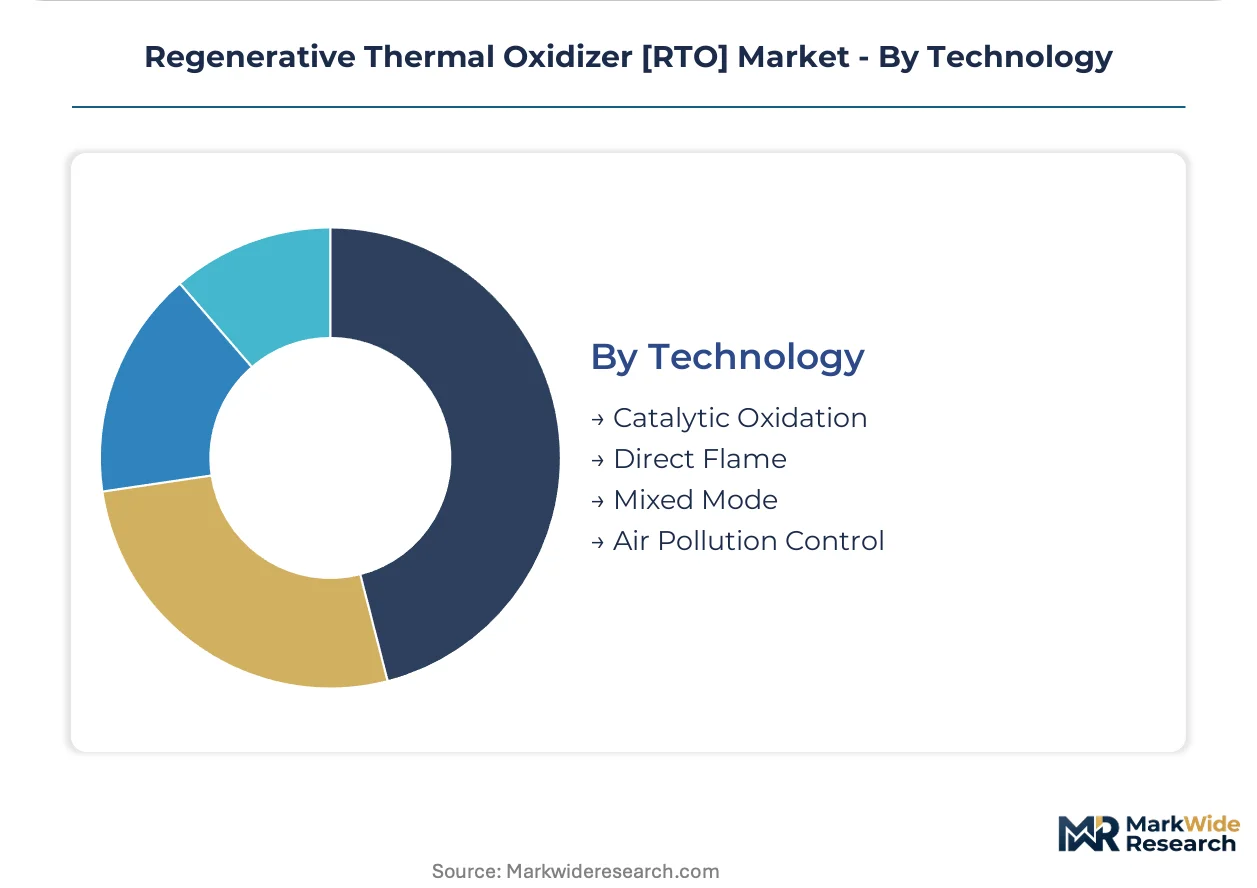
Thermal recovery efficiency thresholds and catalyst degradation risks differentiate technology selection, with direct flame systems dominating high-concentration applications and catalytic oxidation preferred for temperature-sensitive compounds.
- Catalytic Oxidation:Precious metal catalysts enable VOC destruction at 300-600°C versus 760-1100°C for thermal systems, slashing supplemental fuel requirements. Catalyst poisoning from silicones and halogenated compounds limits deployment in electronics manufacturing and certain chemical processes.
- Direct Flame:Thermal oxidizers without heat recovery serve low-volume, high-concentration streams where capital minimization outweighs operating cost concerns.
- Mixed Mode:Hybrid systems switch between catalytic and thermal operation based on inlet concentration to optimize energy recovery across variable loading.
- Air Pollution Control:Integrated scrubber-oxidizer combinations address acid gas co-emissions from sulfur-containing waste streams.
Catalytic oxidation captures efficiency-focused demand; mixed mode configurations are gaining share fastest on stream variability challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands exhibit the lowest price elasticity due to stringent environmental liability frameworks, while operators in India and Southeast Asia remain highly sensitive to capital expenditure thresholds despite tightening emission norms.
United States
Chemical processors along the Texas-Louisiana Gulf Coast corridor are expanding RTO procurement to meet EPA Maximum Achievable Control Technology standards for petrochemical source categories. The EPA enforces non-discretionary deployment timelines that compress project schedules and favor modular system architectures. Houston-area refineries are specifying structured ceramic media for new-build installations exceeding 50,000 scfm capacity.
Germany
Automotive coating facilities are procuring electric RTO configurations ahead of prospective EU carbon border adjustment mechanisms on embedded emissions. The EU Industrial Emissions Directive imposes Best Available Techniques benchmarks that shape product design specifications. Industrial clusters in Baden-Württemberg and Bavaria are piloting equipment-as-a-service contracting models with per-ton VOC destruction fee structures.
China
Domestic chemical producers in the Yangtze River Delta and Pearl River Delta manufacturing zones are pre-qualifying European and North American RTO suppliers for technology transfer partnerships. China's Ministry of Ecology and Environment is tightening VOC emission limits that redirect procurement toward higher-efficiency regenerative systems with dual-chamber configurations. Shanghai-based processors are upgrading from thermal oxidizers to ceramic media-based recovery systems.
Netherlands
Mid-market coating and printing operations are adopting third-party financed RTO assets that transfer operational risk to specialized lessors. Dutch environmental liability regulations incentivize outsourced compliance management through equipment-as-a-service arrangements. Rotterdam-area chemical terminals are bundling oxidizer procurement with integrated scrubber stages for sulfur-laden waste streams.
India
Pharmaceutical manufacturers in Maharashtra and Gujarat are installing regenerative systems for solvent recovery from active pharmaceutical ingredient synthesis operations. The Central Pollution Control Board is enforcing stricter VOC emission standards for chemical processing zones. Mumbai-Pune industrial corridor facilities are prioritizing gas-fired configurations where pipeline infrastructure exists to minimize operating cost premiums.
Regenerative Thermal Oxidizer [RTO] Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the RTO landscape, creating a bifurcated competitive structure. Captive ceramic media manufacturers command premium positioning through thermal efficiency advantages, while aftermarket service specialists sustain recurring revenue through installed base expansion. Three archetypes dominate: integrated system bundlers, component specialists with captive manufacturing, and independent service providers. Consolidation pressures favor acquisition of regional fabricators by multinational environmental technology groups, while technology licensing agreements accelerate geographic expansion without capital-intensive greenfield investments.
Within the integrated system tier, Dürr Aktiengesellschaft and John Zink Hamworthy Combustion LLC exemplify divergent strategic positions—Dürr represents European-engineered thermal recovery systems with structured media capabilities, while John Zink Hamworthy occupies North American project bundling dominance through burner-oxidizer integration. CECO Environmental Corp. anchors the aftermarket service archetype, sustaining revenue through recurring maintenance contracts rather than discrete equipment sales. These three entities collectively illustrate how competitive positioning fragments across technology origin, geographic concentration, and business model differentiation.
| Leading Market Players |
|---|
| TANN Corporation |
| Air Clear LLC |
| Anguil Environmental Systems, Inc. |
| Eisenmann SE |
| Alliance Corporation |
| CECO Environmental Corp. |
| John Zink Hamworthy Combustion LLC |
| Catalytic Products International |
| Dürr Aktiengesellschaft |
| Others |
Value Network & Pricing Analysis
Large-format refinery installations in the US Gulf Coast corridor generate scale economies that compress unit costs for ceramic heat-exchange media while elevating price floors for aftermarket service contracts. Dürr Aktiengesellschaft's captive manufacturing of structured media and CECO Environmental Corp.'s recurring revenue service models illustrate how supply concentration and pricing power interlock across divergent competitive tiers.
Pricing Analysis
Aftermarket service contracts and ceramic media replacement cycles drive lifetime value, with three-tier pricing structure across premium, standard, and economy levels separating OEM-integrated bundles from independent provider offerings. Price differentiation hinges on EPA MACT certification tier and vertical integration depth in ceramic media production. Cost compression in standard-tier equipment is intensifying because modular skid-mounted systems reduce field construction premiums. Mid-market coating operations exhibit highest price sensitivity; pharmaceutical and aerospace buyers accept premium positioning for outsourced compliance liability.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Rotterdam ports to Houston and Antwerp terminals elevate landed costs for European- and Asian-sourced structured ceramic media. High-purity alumina and silicon carbide supply concentrates in Germany, Japan, and China, with regenerative bed assemblies drawing from specialty refractory producers in these markets. Single-source vulnerability from limited high-purity ceramic producers exposes project timelines to raw material allocation constraints. Distribution runs through EPC contractors and environmental technology integrators serving petrochemical and chemical processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across fuel type, application intensity, and regional regulatory stringency creates niche opportunities for specialized positioning. Modular architectures and equipment-as-a-service contracting are splintering procurement patterns away from integrated OEM dominance.
For Market Incumbents: Consolidate aftermarket service networks in the US Gulf Coast corridor to defend against independent providers capturing ceramic media replacement and burner refurbishment contracts. Acquire regional fabricators with EPA MACT pre-certification to compress technology transfer timelines for Chinese market entry. Capacity addition in Yangtze River Delta proximity addresses MEE enforcement expansion. For New Entrants and Emerging Players: EPA MACT fast-track certification for dual-chamber configurations opens procurement pipelines among Texas and Louisiana chemical processors facing compressed deployment timelines. Target mid-market coating operations in Germany and Netherlands with equipment-as-a-service financing partnerships. Go-to-market through third-party lessors charging per-ton VOC destruction fees transfers operational risk from capital-constrained buyers. For Investors and Strategic Acquirers: Independent service providers with installed base visibility and recurring revenue contracts represent the most defensible acquisition archetype over the projection horizon. Ceramic media lifecycle forecasting capabilities and burner refurbishment expertise signal durable competitive positioning. Watch for carbon border adjustment mechanism implementation as inflection indicator for electric configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Media | Dürr's captive structured media production commands premium positioning in large-format refinery installations. |
| Modular Skid-Mounted System Expansion | Pre-engineered packages reduce field construction duration for mid-market chemical processing segments. |
| Equipment-as-a-Service Contracting | Third-party financiers transfer operational risk from processors to specialized lessors in Germany and Netherlands. |
| Aftermarket Service Unbundling | Independent providers capture ceramic replacement contracts previously held by original equipment manufacturers. |
| Technology Transfer Partnership Structuring | European and North American suppliers pre-qualify for MEE-directed procurement in Yangtze River Delta. |
Research Methodology
The analysis maps gas-fired, electric, and dual-fuel system architectures, each validated through plant engineers, EPC contractor procurement teams, aftermarket service directors, and environmental compliance officers across petrochemical and chemical processing facilities. Primary interviews with these stakeholders combined with secondary validation from EPA enforcement databases, EIA energy pricing data, SEC 10-K environmental technology disclosures, and ACC chemical production indices. Bottom-up unit economics and top-down sector sizing triangulate market estimates.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include fuel configuration, application intensity tier, end-user industry vertical, and regional regulatory cluster. CAGRs derived from installed base expansion rates, replacement cycle compression, and efficiency upgrade penetration curves. Henry Hub volatility scenarios and carbon pricing mechanism adoption timelines inform sensitivity bounds.
Decision-makers should treat outputs as directional under base assumptions of continued EPA MACT enforcement, stable ceramic media supply allocation, and gradual carbon border adjustment implementation; material deviation would warrant model refresh. Forecasts reflect these assumptions with acknowledgment that refractory supply disruption, natural gas price spikes, or accelerated EU carbon tariff activation could revise trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Industrial Lyophilizer Market