
 Sludge Dryer Machine Market | 2026-2036
Sludge Dryer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sludge Dryer Machine Market Analytics
Direct equipment procurement by municipal utilities is reshaping how sludge dryer manufacturers reach end users, bypassing traditional EPC intermediaries in favor of long-term service contracts. Evoqua Water Technologies leverages its integrated digital monitoring platforms to anchor recurring revenue streams across North American wastewater districts. Komline-Sanderson competes through specialized paddle dryer designs that dominate pharmaceutical and chemical waste applications. Kilburn Engineering sustains its position in South Asian markets with localized fabrication capabilities and aftermarket parts networks.
A sludge dryer machine reduces moisture content in sewage sludge, industrial slurry, or agricultural waste from typical ranges of 80% down to 10-40% through thermal, mechanical, or hybrid processes, enabling volume reduction, pathogen elimination, and fuel substitution in cement kilns or incinerators. Rotary dryer configurations retain the largest installed base across European power plants due to their tolerance for high throughputs and variable feed consistency, though fluidized bed systems are gaining share where uniform particle drying and lower exhaust gas volumes matter. Thermal drying technology leads value generation because energy recovery integration and exhaust treatment add significant equipment scope, while mechanical dewatering occupies the volume-intensive municipal tier where operating cost sensitivity dominates procurement decisions.
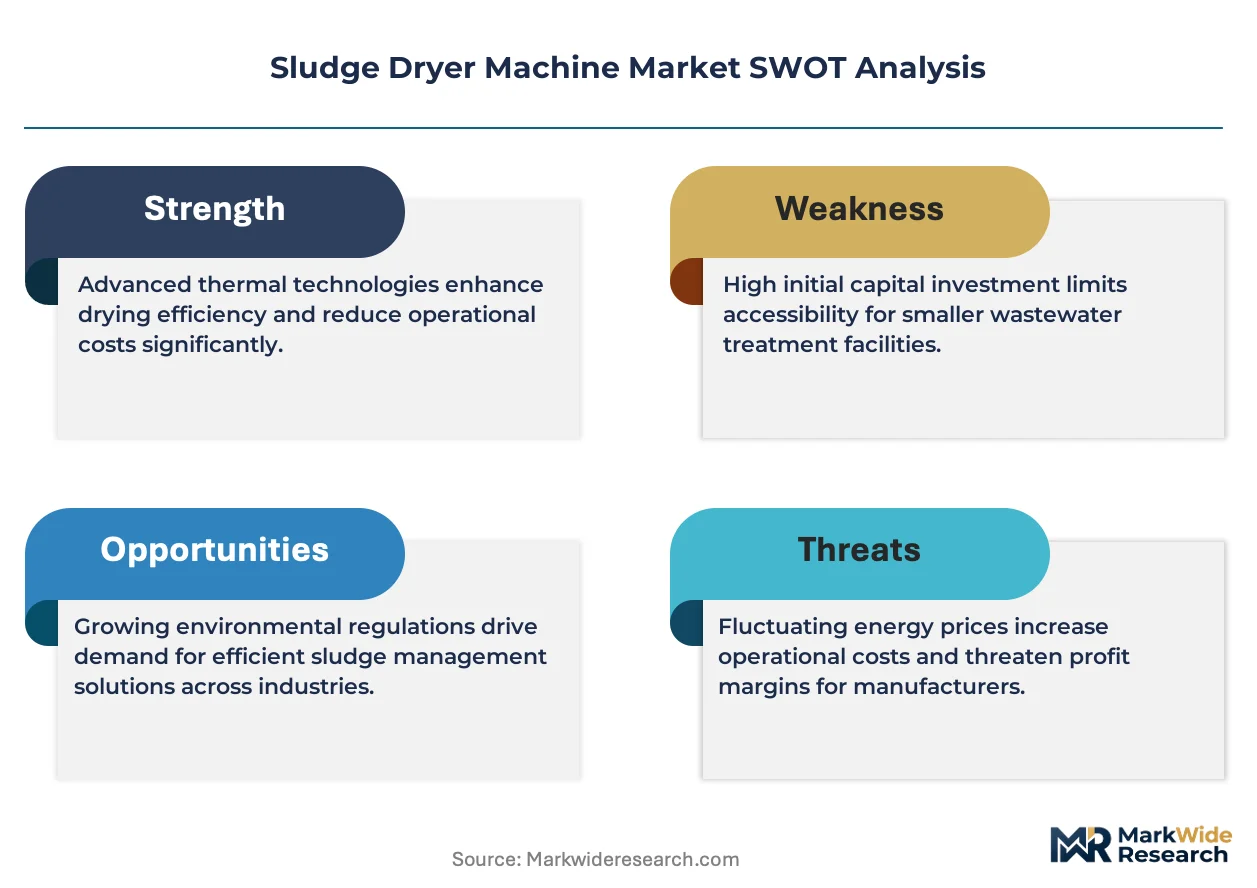
EPA biosolids regulations in the United States restrict land application pathways and push municipalities toward Class A thermal drying or advanced alkaline stabilization, while the EU Urban Wastewater Treatment Directive revision tightens nutrient recovery and phosphorus recycling mandates that alter dryer selection criteria. China’s MEE enforces stricter sludge disposal limits for industrial clusters, forcing upgrades from simple belt presses to energy-recovery drying systems. Stakeholders must monitor how carbon border adjustments and evolving landfill bans in multiple jurisdictions redefine the total cost of ownership for competing dewatering and drying technologies.
Market Dynamics
EU landfill diversion mandates are compressing payback periods for thermal drying investments, forcing municipal utilities to bypass traditional EPC intermediaries and contract directly with equipment vendors for bundled service agreements.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revision:Tightened phosphorus recovery mandates in Germany, France, and the Netherlands are compelling utilities to upgrade from simple dewatering to thermal drying with nutrient extraction capabilities.
- China's dual carbon goals:Industrial clusters near Shanghai and Guangzhou face MEE enforcement of sludge disposal limits, accelerating replacement of belt presses with energy-recovery drying systems in petrochemical and textile sectors.
- Cement kiln co-processing:Rising fuel substitution demand from European cement manufacturers is pulling dried sludge volumes toward thermal drying infrastructure with consistent particle specifications.
Market Restraints
- Natural gas price volatility:Thermal drying operations in Germany and Italy face margin compression from input energy cost swings, slowing capacity expansion decisions among municipal utilities with fixed-rate tariff structures.
- Supply concentration in fabricated metal components:Rotary dryer drum fabrication capabilities cluster in northern Italian and western German industrial zones, creating lead time vulnerability for non-European project developers.
- Mechanical dewatering substitution:Advanced high-pressure screw presses achieve 18-22% dryness without thermal input, capturing municipal tier volume where operating cost sensitivity dominates procurement.
Strategic Opportunities
- India's untreated sludge backlog:Underpenetrated municipal infrastructure in Maharashtra and Tamil Nadu creates openings for localized fabrication partnerships serving wastewater treatment plants with sub-scale thermal or solar-assisted hybrid systems.
- Pharmaceutical waste drying:Containment-grade paddle dryer demand from API manufacturers in Switzerland and Ireland is outpacing specialized vendor capacity, creating white space for equipment platforms with integrated solvent recovery.
- Carbon border adjustment mechanisms:EU CBAM implementation is repositioning dried sludge as a verified low-carbon fuel substitute, incentivizing cement sector procurement from certified thermal drying operations with documented emission profiles.
Industry Challenges
- Process control engineering shortage:Fluidized bed and indirect dryer installations require specialized commissioning expertise in exhaust gas treatment and energy integration, constraining deployment velocity in North American markets.
- Class A pathogen certification timelines:EPA Part 503 compliance documentation for thermal drying systems extends project development cycles by 8-14 months, compressing vendor cash conversion periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sludge Dryer Machine Market |
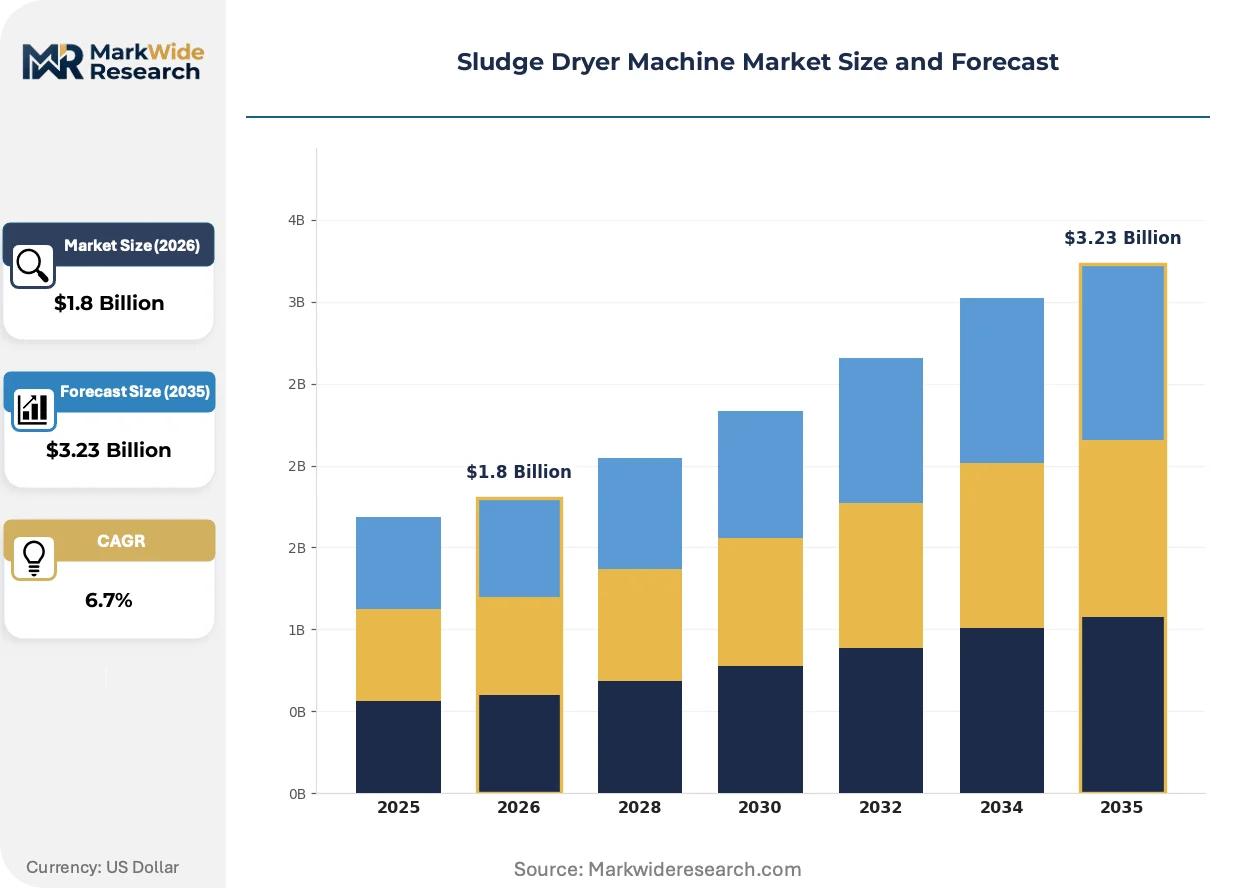
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
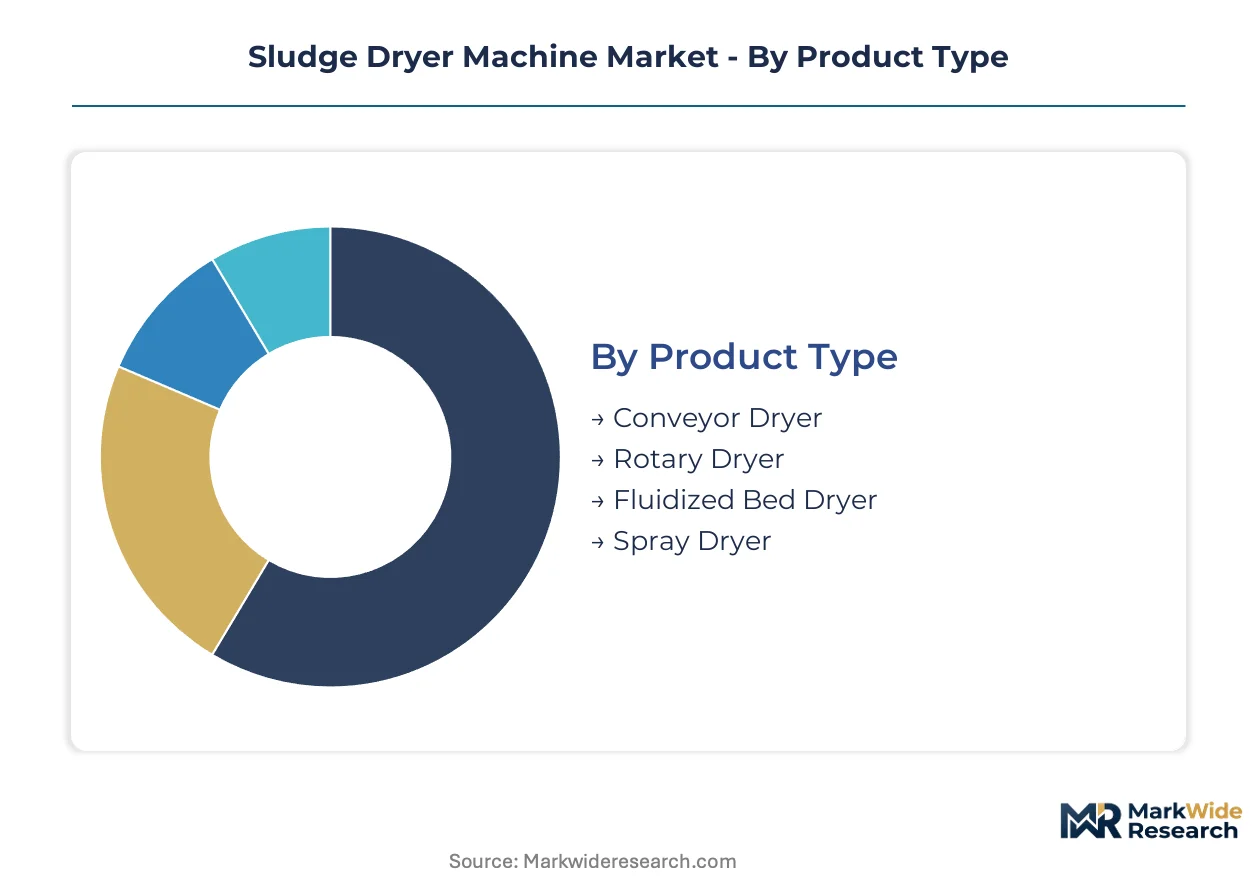
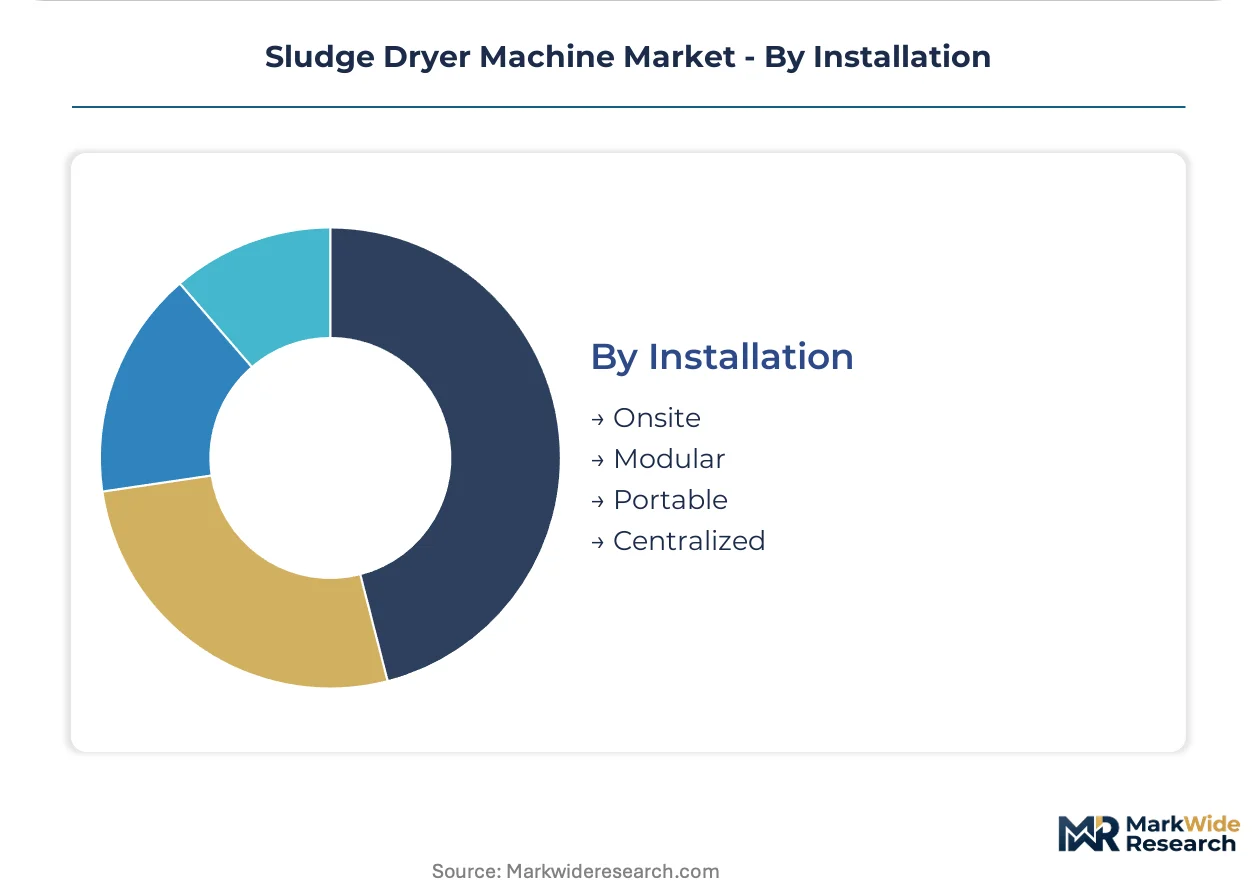
| Segmentation | Product Type: Conveyor Dryer, Rotary Dryer, Fluidized Bed Dryer, Spray Dryer Technology: Thermal Drying, Mechanical Dewatering, Electro-Osmosis, Solar Drying End User: Municipal Treatment Plants, Industrial Wastewater Facilities, Power Plants, Agricultural Sector Installation: Onsite, Modular, Portable, Centralized |
| Companies Covered | Evoqua Water Technologies, Komline-Sanderson, Met-Chem Inc., Kilburn Engineering, GEA Process Engineering, HUBER SE, KENKI, Buss-SMS-Canzler, SUEZ Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sludge Dryer Machine Market Evolving Landscape
Equipment architectures are converging around energy recovery integration and digital monitoring platforms, blurring traditional distinctions between thermal and mechanical dewatering categories while reshaping vendor service models.
Solar-assisted thermal drying is hybridizing conventional rotary and belt dryer designs with photovoltaic-powered air preheating and automated moisture feedback controls. Agricultural waste processors in Spain and Italy are deploying these systems for olive mill and winery sludge, achieving 35-45% fossil energy reduction. The technology is hybridizing project economics in Mediterranean climates where solar irradiance profiles align with seasonal waste generation patterns, compressing payback periods against conventional natural gas-fired alternatives.
EPA biosolids regulations are restricting land application pathways and pushing municipalities toward Class A thermal drying or advanced alkaline stabilization. The industrial consequence is a bifurcation in equipment procurement: larger utilities invest in integrated drying-pelletizing systems while smaller districts pursue mobile thermal processing services. Northeastern US wastewater districts are most affected, responding with cooperative procurement agreements to share capital-intensive drying infrastructure across municipal boundaries.
Direct equipment procurement by municipal utilities is displacing traditional EPC intermediaries in favor of long-term service contracts with performance guarantees. Equipment vendors are unbundling after-sales service from capital sales, creating recurring revenue streams through remote monitoring subscriptions and predictive maintenance programs. This pattern is most visible in German and Dutch municipal markets where procurement frameworks prioritize total cost of ownership over lowest capital expenditure.
Sludge Dryer Machine Market Segmentation
Sludge dryer procurement cycles vary dramatically by segment—thermal systems require 18-36 month capital planning horizons while mechanical dewatering operates on 6-12 month replacement schedules. Understanding these temporal patterns helps vendors align service contracts and inventory strategies with actual customer decision rhythms.
Product Type:
Replacement cycles stretch from 5 years for modular portable units to 25 years for heavy rotary installations, creating distinct aftermarket revenue windows across each configuration.
- Rotary Dryer:Cylindrical drum configurations with direct or indirect heat transfer tolerate high throughputs and variable feed consistency across European power plants. German and Italian cement manufacturers anchor demand for these systems where dried sludge feeds kiln co-processing operations with strict particle specification requirements.
- Fluidized Bed Dryer:Suspended particle drying with hot air distribution achieves uniform moisture reduction and lower exhaust gas volumes than rotary alternatives. Swiss pharmaceutical API manufacturers and Irish chemical processors are concentrating procurement here where containment-grade operations require integrated solvent recovery capabilities.
- Conveyor Dryer:Belt-based continuous systems with multiple drying zones serve mid-scale municipal utilities with moderate throughput requirements and simpler operational profiles.
- Spray Dryer:Atomized feed dispersion into hot gas streams handles liquid slurries with high solids content, finding application in specialized industrial effluent treatment.
Rotary dryer configurations anchor the volume base while fluidized bed systems gain share at the steepest rate.
Technology:
Cost tiers separate capital-intensive thermal infrastructure from operational-expense-focused mechanical alternatives, with hybrid systems occupying an emerging middle position.
- Thermal Drying:Direct-fired or indirect heat application reduces moisture from 80% to 10-40% while enabling pathogen elimination and fuel substitution. EU landfill diversion mandates in Germany, France, and the Netherlands compress payback periods for these systems as utilities seek Class A biosolids certification.
- Mechanical Dewatering:High-pressure screw presses and centrifuges achieve 18-22% dryness without thermal input, dominating municipal tier procurement where operating cost sensitivity outweighs capital availability. China's MEE enforcement near Shanghai and Guangzhou accelerates belt press replacement with energy-recovery drying in petrochemical clusters.
- Electro-Osmosis:Electric field-driven water migration from sludge matrices offers low-temperature moisture reduction for specialized industrial applications with heat-sensitive waste streams.
- Solar Drying:Photovoltaic-powered air preheating hybridized with conventional designs achieves 35-45% fossil energy reduction in Mediterranean climates. Spanish olive mill and Italian winery operations deploy these systems where solar irradiance profiles align with seasonal waste generation.
Mechanical dewatering commands the largest installed base while solar-assisted configurations expand most quickly in agricultural waste processing.
End User:
Customer type determines specification intensity—municipal utilities prioritize total cost of ownership while industrial facilities emphasize integration with existing process lines.
- Municipal Treatment Plants:Public wastewater utilities face EPA Part 503 compliance documentation extending project cycles by 8-14 months. Direct equipment procurement is displacing traditional EPC intermediaries in German and Dutch markets where bundled service agreements with performance guarantees dominate.
- Industrial Wastewater Facilities:Petrochemical, textile, and pharmaceutical processors require containment-grade systems with solvent recovery integration. Switzerland and Ireland anchor specialized paddle dryer demand from API manufacturers outpacing current vendor capacity.
- Power Plants:Coal and biomass facilities utilize dried sludge as auxiliary fuel or disposal pathway, with rotary configurations preferred for tolerance of high throughputs and variable feed consistency.
- Agricultural Sector:Livestock operations and crop processors deploy solar-assisted hybrid systems for manure and organic waste volume reduction, with Mediterranean climates showing strongest adoption.
Municipal treatment plants anchor the volume base while industrial wastewater facilities gain share at the steepest rate.
Installation:
Deployment architecture shapes capital deployment patterns—centralized facilities amortize costs across multiple feed sources while portable units serve distributed or seasonal demand.
- Onsite:Permanently installed systems integrated with existing wastewater treatment infrastructure dominate large utility and industrial applications with predictable waste generation profiles.
- Modular:Pre-fabricated skid-mounted configurations enable phased capacity expansion and faster commissioning timelines, appealing to utilities with constrained capital budgets or uncertain growth trajectories.
- Portable:Trailer-mounted or containerized units serve emergency response, seasonal agricultural processing, or pilot-scale demonstrations with rapid deployment requirements.
- Centralized:Regional drying hubs processing sludge from multiple municipal or industrial sources achieve economies of scale, with cooperative procurement agreements emerging across Northeastern US wastewater districts.
Onsite installations anchor the volume base while modular configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's centrality in sludge processing infrastructure, connecting industrial clusters from Rotterdam to the Black Sea with barge-accessible thermal drying facilities.
Germany
Municipal utilities along the Rhine corridor are expanding thermal drying capacity to meet EU landfill diversion deadlines. The EU Urban Wastewater Treatment Directive revision tightens phosphorus recovery mandates, compelling upgrades from simple dewatering to nutrient-extraction systems. The Ruhr industrial conurbation hosts concentrated cement kiln co-processing demand, pulling dried sludge volumes toward facilities with strict particle specifications.
China
Industrial clusters near Shanghai and Guangzhou face MEE enforcement of sludge disposal limits for petrochemical and textile operations. The country's dual carbon goals accelerate replacement of belt presses with energy-recovery drying systems in designated low-carbon zones. The Yangtze River Delta anchors the steepest capacity expansion, with provincial SOEs contracting directly for bundled equipment-service packages.
United States
Northeastern wastewater districts are forming cooperative procurement agreements to share capital-intensive drying infrastructure across municipal boundaries. EPA Part 503 biosolids regulations restrict land application pathways, pushing utilities toward Class A thermal drying certification. The Delaware River Basin concentration of pharmaceutical API manufacturers generates specialized containment-grade demand outpacing current vendor capacity.
India
Maharashtra and Tamil Nadu present underpenetrated municipal infrastructure openings for localized fabrication partnerships. Central Pollution Control Board enforcement of untreated sludge disposal limits forces upgrades at wastewater treatment plants lacking drying capacity. The Mumbai-Pune industrial corridor attracts skid-mounted modular configurations for utilities with constrained capital budgets and uncertain growth trajectories.
Switzerland
Pharmaceutical API manufacturers in Basel and surrounding cantons are concentrating procurement in fluidized bed systems with integrated solvent recovery. Swissmedic containment requirements for active pharmaceutical ingredient waste exceed standard industrial specifications, creating white space for specialized equipment platforms. The Jura Arc chemical cluster sustains demand for paddle dryer configurations with automated moisture feedback controls.
Sludge Dryer Machine Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated water technology conglomerates with digital service platforms, specialized thermal equipment fabricators with regional fabrication networks, and modular system providers serving capital-constrained municipal segments. Strategic archetypes include full-lifecycle service bundlers, geography-anchored fabrication specialists, and containment-grade pharmaceutical system builders. Dominant competitive moves encompass direct utility procurement relationships displacing EPC intermediaries, and solar-assisted hybrid technology licensing for Mediterranean agricultural applications.
Within the integrated service tier, Evoqua Water Technologies exemplifies the digital platform anchor model, while Komline-Sanderson occupies the specialized thermal design position. Kilburn Engineering represents the geography-anchored fabrication archetype with aftermarket parts network reliance. These three patterns illustrate how vendor strategies diverge across municipal, industrial, and pharmaceutical end-use segments without requiring identical capability stacks.
| Leading Market Players |
|---|
| Evoqua Water Technologies |
| Komline-Sanderson |
| Met-Chem Inc. |
| Kilburn Engineering |
| GEA Process Engineering |
| HUBER SE |
| KENKI |
| Buss-SMS-Canzler |
| SUEZ Water Technologies & Solutions |
| Others |
Value Network & Pricing Analysis
The Rhine-Main-Danube waterway corridor's barge freight cost dynamics amplify pricing power for northern Italian and western German fabricators while compressing margins for utilities in peripheral European markets lacking direct waterway access. This logistics asymmetry forces project developers outside the corridor to absorb premium transport costs or accept extended lead times, creating tiered procurement economics that favor localized supply relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates containment-grade pharmaceutical systems with Swissmedic certification from municipal-tier rotary configurations and modular skid-mounted units. Price differentiation hinges on exhaust gas treatment integration and after-sales service bundling. Cost compression in the municipal tier intensifies because high-pressure screw press substitutes achieve comparable dryness without thermal energy input. Industrial wastewater facilities in pharmaceutical clusters exhibit lowest price sensitivity due to solvent recovery mandates, while capital-constrained Indian utilities face acute budget constraints.
Supply Chain Analysis
Tariff exposure between China and EU member states dominates supply chain risk planning for fabricated metal components and precision control systems. Rotary dryer drum fabrication concentrates in Italy, Germany, and China, drawing from specialty steel grades, refractory linings, and automated welding equipment. Single-source vulnerability in northern Italian industrial zones for large-diameter drum casting creates lead time vulnerability for non-European developers. Distribution runs through direct vendor-utility contracting channels that displace traditional EPC intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across municipal, industrial, and pharmaceutical end-use segments creates multiple niche entry points as direct procurement patterns bypass traditional channel gatekeepers. The dissolution of EPC intermediaries opens specialized service and modular equipment opportunities.
For Market Incumbents: Build switching cost moats through integrated digital monitoring platforms that anchor recurring revenue streams. Cement kiln co-processing partnerships in the Ruhr corridor provide defensive volume anchors against mechanical dewatering substitution. Backward integration into drum fabrication capabilities in South Asia addresses lead time vulnerability while capturing margin from localized Indian demand. For New Entrants and Emerging Players: Build out solar-assisted hybrid configurations for Mediterranean agricultural processors in Spain and Italy where photovoltaic cost profiles align with seasonal waste generation. Pharmaceutical API waste drying in Switzerland and Ireland offers the most penetrable white space given specialized vendor capacity constraints. Target cooperative procurement agreements across Northeastern US wastewater districts as a channel entry mechanism. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital service platform consolidators over pure equipment fabricators. The five-to-ten year viability window rewards vendors with recurring revenue models and energy recovery integration capabilities. Acquisition targets should demonstrate documented emission profiles for EU CBAM compliance. The signal to watch is carbon border adjustment enforcement intensity affecting cement sector fuel substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Contract Bundling | Evoqua's digital platform anchors recurring revenue across North American wastewater districts. |
| Localized Fabrication Partnership | Kilburn Engineering's Indian aftermarket network captures maintenance spend from sub-scale municipal plants. |
| Containment-grade System Development | Swissmedic requirements in Basel exceed standard specifications, creating premium tier pricing power. |
| Solar Hybrid Technology Licensing | Spanish olive mill deployments achieve fossil energy reduction through photovoltaic preheating integration. |
| Direct Utility Procurement Relationship | German and Dutch municipalities bypass EPC intermediaries for performance-guaranteed equipment-service packages. |
Research Methodology
A spread of perspectives from municipal utility procurement officers, industrial plant engineers, EPC contractors, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC equipment vendor filings, EU Urban Wastewater Treatment Directive implementation reports, and China MEE enforcement bulletins. Bottom-up installation database construction triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply-balance framing anchored the quantitative framework throughout the projection horizon. Segmentation dimensions modeled include dryer configuration type, technology category, end-user vertical, and installation architecture. CAGRs derived from historical deployment trajectories adjusted for regulatory enforcement intensity and energy price volatility. Forecast inputs incorporated cement kiln co-processing demand curves and pharmaceutical waste volume projections.
Practitioners should monitor EU CBAM implementation pace and natural gas price volatility for early signals of technology substitution. Forecasts reflect documented assumptions about regulatory enforcement timelines and infrastructure investment cycles. Material shifts in landfill diversion deadlines or carbon border adjustment scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Lyophilization Services Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Paper Drying Systems Market