
 Global Absorbent Pads Market | 2026-2036
Global Absorbent Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Global Absorbent Pads Market Foresight
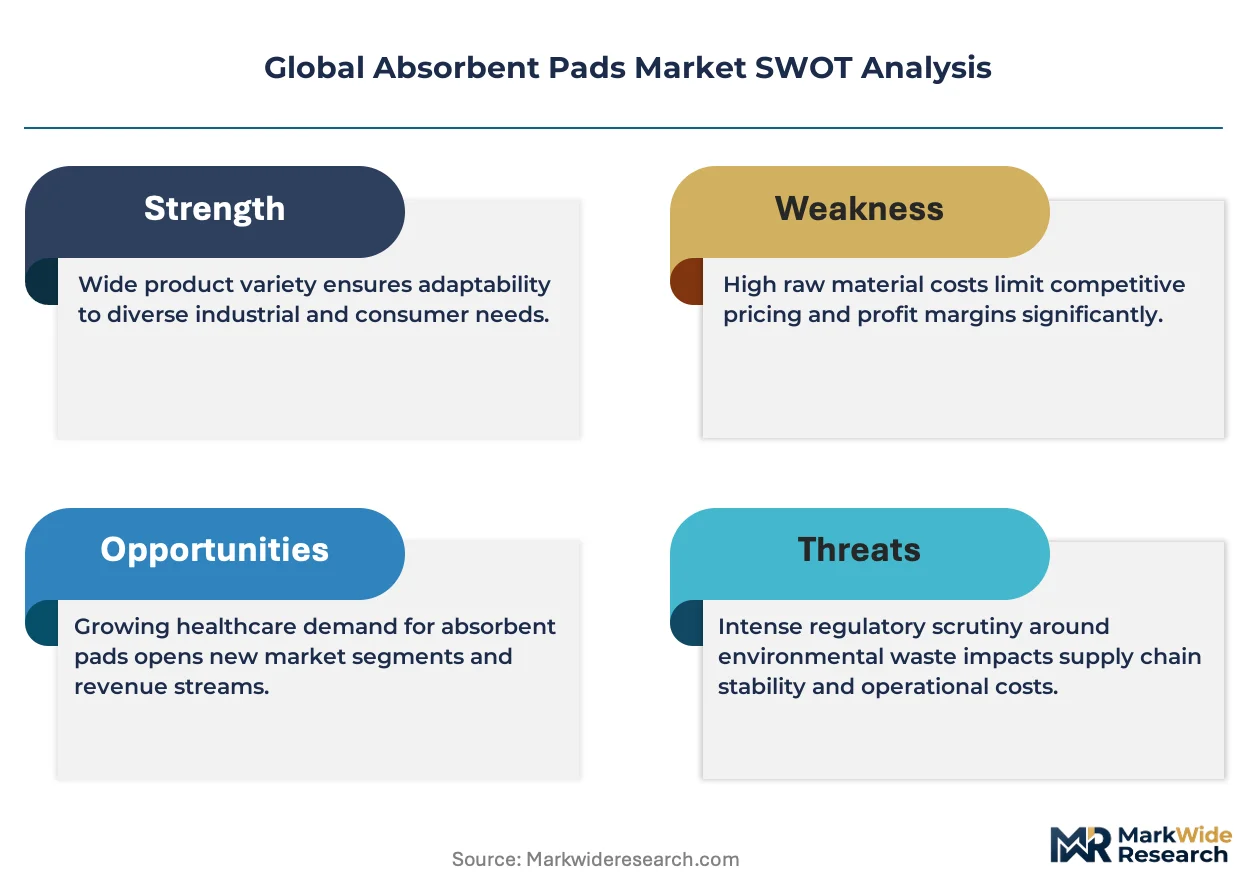
Capital-intensity divergence between integrated polymer producers and converter-dependent specialists is unwinding competitive stability in absorbent pad supply chains. 3M Company leverages captive nonwoven manufacturing capacity to sustain margin control across medical and industrial grades. Pactiv Evergreen Inc. anchors North American food packaging absorbent demand through thermoformed tray integration. Novipax LLC specializes in superabsorbent polymer formulations that differentiate its wound care and leak protection portfolios.
Absorbent pads are engineered fibrous or foam-based structures designed to capture and retain fluids through capillary action, surface energy modulation, and polymer gelation, typically achieving absorption capacities between ten and fifty times their dry weight depending on core composition. These products serve critical functions across healthcare infection control, industrial spill containment, and food safety compliance by preventing cross-contamination and moisture damage. Disposable pads dominate volume throughput in hospital and food service channels where single-use protocols govern procurement, while reusable pads command durable goods positioning in manufacturing plant maintenance cycles where laundering infrastructure exists. Medical wound dressings concentrate margin pools through silicone-adhesive and antimicrobial additive premiums, whereas industrial sorbents compete on bulk pricing and oil-selective polypropylene specifications.
FDA 510(k) clearance pathways and EU MDR conformity assessment procedures shape product development timelines and market access costs for medical-grade absorbent manufacturers. EPA Spill Prevention Control and Countermeasure rules and OSHA workplace exposure limits drive industrial sorbent specifications for oil spill cleanup and chemical containment applications. Stakeholders must monitor evolving bioplastics certification standards and extended producer responsibility frameworks as these will determine material substitution viability and geographic manufacturing placement.
Market Dynamics
EU MDR biocompatibility mandates are compressing product development timelines while polymer feedstock volatility is fragmenting margin structures across converter-dependent manufacturers.
Growth Catalysts
- Surgical procedure volumes:Rising chronic wound prevalence and aging demographics in Germany and Japan are expanding hospital procurement of medical-grade absorbent products with silicone-adhesive premiums.
- REACH-compliant bioplastics:Extended producer responsibility frameworks across France and Italy are accelerating material substitution toward certified compostable nonwoven cores.
- Industrial spill containment mandates:EPA SPCC rules and OSHA workplace exposure limits are standardizing oil-selective polypropylene specifications for chemical plant maintenance cycles.
Market Restraints
- Superabsorbent polymer feedstock concentration:Acrylic acid derivative supply concentrates among integrated petrochemical producers in the US Gulf Coast and Northeast Asia, exposing converters to margin squeeze.
- EU MDR conformity assessment costs:Clinical evaluation requirements and notified body bottlenecks are extending time-to-market for novel wound dressing formats by 12-18 months.
- Reusable industrial sorbents:Manufacturing plant laundering infrastructure in Germany and Switzerland is displacing disposable pad volumes in maintenance applications.
Strategic Opportunities
- Underpenetrated Indian healthcare infrastructure:CDSCO medical device registration pathways and PLI scheme incentives are opening domestic manufacturing placement for antimicrobial wound dressings.
- Food service thermoformed tray integration:Leak-proof absorbent pad-tray combinations are capturing premium positioning in US and Canadian poultry and seafood retail packaging.
- ISO 13485 certification convergence:Quality management system harmonization is enabling single-facility supply to multiple regulatory jurisdictions, reducing geographic fragmentation costs.
Industry Challenges
- Polymer science talent scarcity:Formulation chemistry expertise for superabsorbent gelation control concentrates among aging specialist workforces in Germany and Japan.
- FDA 510(k) predicate device matching:Substantial equivalence determinations for novel core compositions require extensive biocompatibility documentation, compressing R&D throughput.
- Legacy thermoforming equipment retrofitting:Food packaging converters face capital intensity barriers when integrating absorbent pad insertion modules into existing tray lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Absorbent Pads Market |
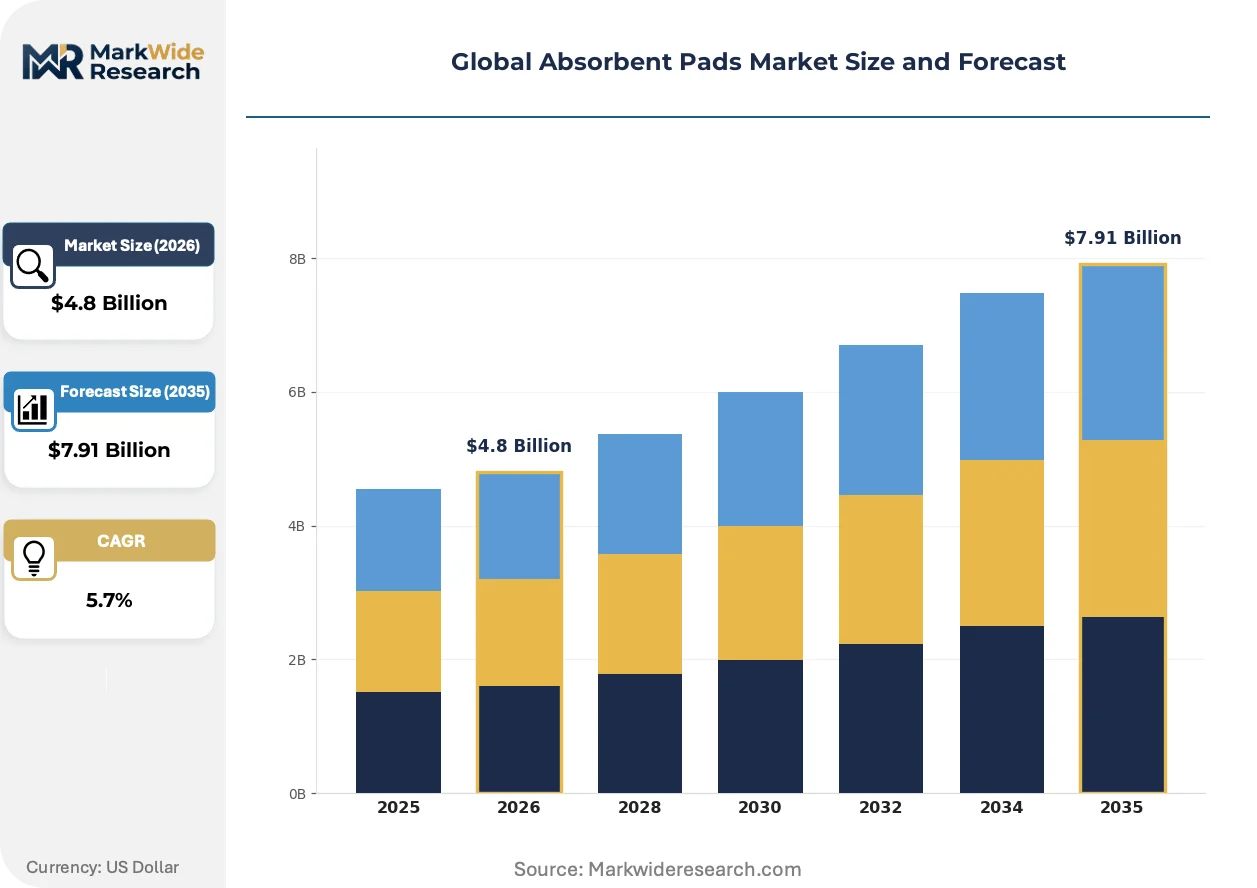
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Pads, Reusable Pads, Medical Wound Dressings, Industrial Sorbents, Sanitary Napkins Application: Wound Care, Leak Protection, Oil Spill Cleanup, Personal Hygiene, Food Packaging End User: Hospitals, Clinics, Manufacturing Plants, Laboratories, Consumer Households Packaging Type: Plastic Pouches, Cardboard Boxes, Blister Packs, Bulk Bags, Flow Wraps |
| Companies Covered | AptarGroup Inc., W. Dimer GmbH, 3M Company, Cellcomb AB, Sirane Limited, Novipax LLC, Pactiv Evergreen Inc., Cocopac Limited, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Absorbent Pads Market Shifts & Advancements
Absorbent pad architectures are converging around functional miniaturization and regulatory pre-certification, with material science advances compressing core thickness while expanding fluid retention capacity.
Silicone-adhesive interface layers are miniaturizing wound dressing profiles while maintaining moisture vapor transmission rates. German hospital procurement teams are specifying sub-2mm total thickness for sacral and heel pressure injury applications. This compression is enabling ambulatory care transition and home-based wound management expansion.
EU MDR Unique Device Identification requirements are mandating lot-level traceability for all sterile absorbent wound dressings sold in member states. Manufacturers must deploy serialized labeling and electronic data capture systems. German and French converters are absorbing compliance costs through premium pricing for Class IIa certified products.
Hospital group purchasing organizations are consolidating supplier panels around dual-source contracting with volume commitment guarantees. US health systems are displacing fragmented distributor relationships with direct manufacturer agreements. This concentration is most visible in IDN-affiliated surgical centers across Texas and Florida.
Global Absorbent Pads Market Segmentation
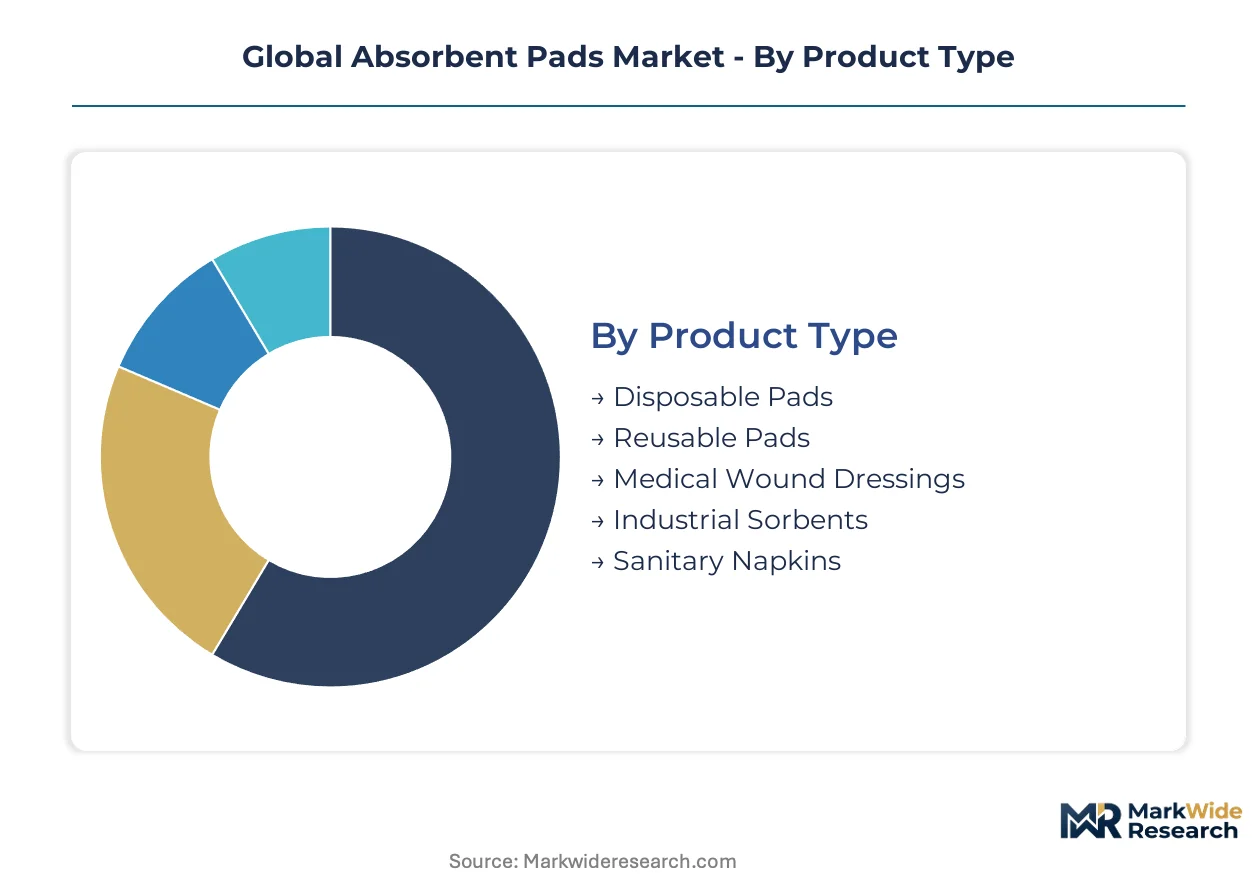
Segmentation in the absorbent pads market reflects divergent regulatory pathways and procurement economics across healthcare, industrial, and consumer channels. FDA 510(k) clearance tiers, EU MDR conformity classes, and EPA spill containment mandates each reshape product specifications and margin structures within their respective segments.
Product Type:
FDA Class I versus Class II device classifications and EU MDR risk stratification differentiate development timelines and notified body requirements across product formats.
- Disposable Pads:Single-use cellulose or synthetic nonwoven cores achieve ten to fifty times dry weight absorption through capillary action and polymer gelation. Hospital infection control protocols in Germany and Japan drive procurement of sterile, individually wrapped formats with lot-level traceability mandated by EU MDR Unique Device Identification requirements.
- Medical Wound Dressings:Silicone-adhesive interface layers with antimicrobial additives command premium positioning through moisture vapor transmission optimization. German hospital procurement teams specify sub-2mm total thickness for sacral and heel pressure injury applications, enabling ambulatory care transition and home-based wound management expansion.
- Reusable Pads:Launderable cotton-polyester blends serve manufacturing plant maintenance cycles where washing infrastructure exists.
- Industrial Sorbents:Oil-selective polypropylene specifications comply with EPA SPCC rules and OSHA workplace exposure limits for chemical containment.
- Sanitary Napkins:Superabsorbent polymer cores with breathable backsheet films target consumer household channels.
Established volume favors disposable pads; emerging adoption favors medical wound dressings.
Application:
End-use concentration determines margin tier and supply chain configuration, with healthcare and food safety applications commanding specification premiums over commodity industrial cleanup.
- Wound Care:Advanced dressing formats with hydrocolloid or foam cores manage exudate in chronic and surgical wounds. Aging demographics in Germany and Japan expand hospital and home health demand for moisture-retentive healing environments.
- Food Packaging:Thermoformed tray-integrated absorbent pads capture leak-proof positioning in US and Canadian poultry and seafood retail. Pactiv Evergreen anchors North American demand through proprietary insertion modules.
- Oil Spill Cleanup:Polypropylene meltblown sorbents achieve oil-water selectivity for EPA-regulated chemical plant maintenance.
- Leak Protection:Superabsorbent cores with odor-neutralizing additives serve incontinence and feminine hygiene applications.
- Personal Hygiene:Breathable film-backed pads target daily use consumer segments.
Margin concentration sits with wound care; volume throughput dominates food packaging.
End User:
Procurement sophistication and compliance burden escalate from consumer self-selection through institutional tender processes.
- Hospitals:Group purchasing organization consolidation around dual-source contracting with volume commitment guarantees displaces fragmented distributor relationships. IDN-affiliated surgical centers across Texas and Florida concentrate procurement power.
- Manufacturing Plants:Laundering infrastructure in Germany and Switzerland sustains reusable sorbent demand for maintenance cycles, though EPA SPCC compliance drives disposable specification in US chemical processing.
- Clinics:Outpatient wound care centers favor cost-optimized dressing formats.
- Laboratories:Biosafety level requirements govern absorbent mat specifications for spill containment.
- Consumer Households:Retail shelf placement and price elasticity drive mass-market absorbent product selection.
Procurement leverage concentrates in hospitals; pricing pressure intensifies in consumer households.
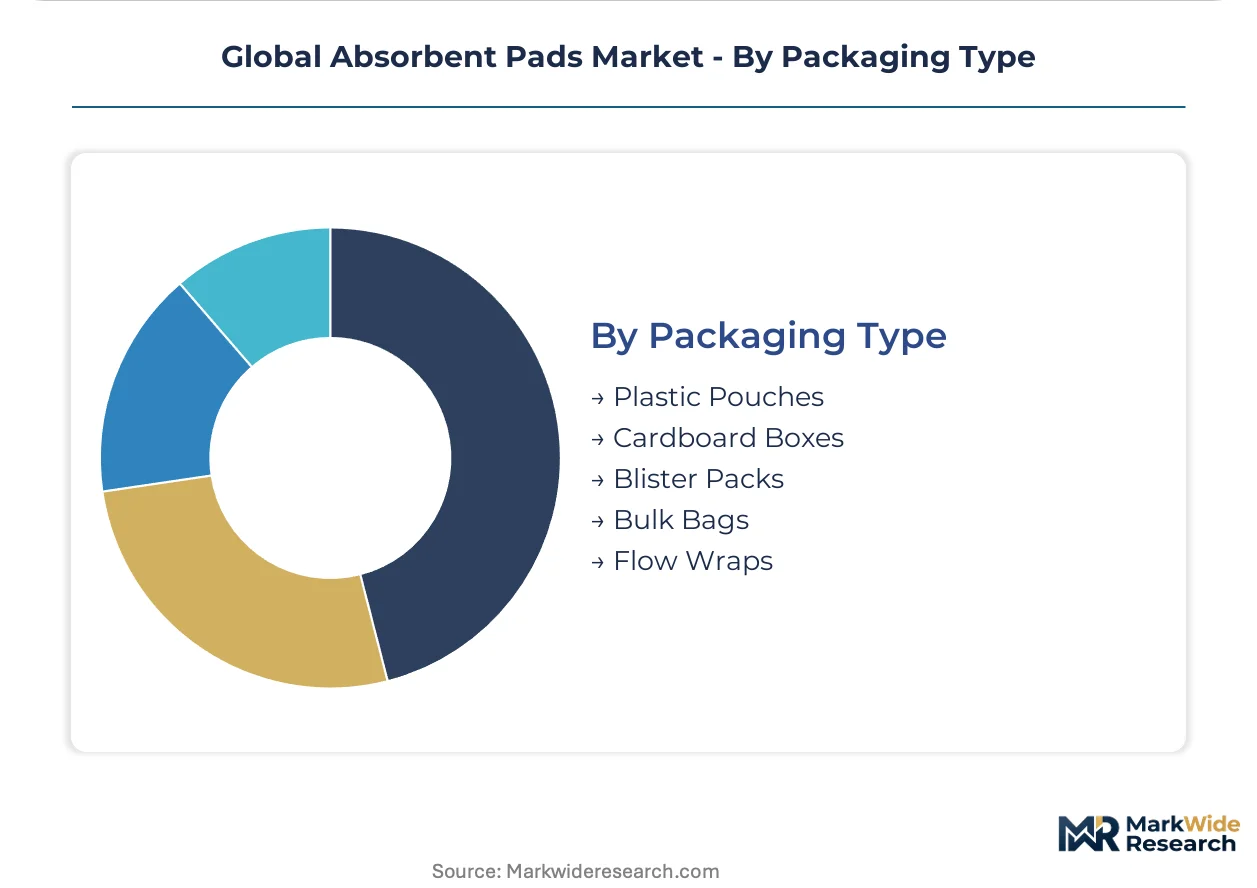
Packaging Type:
Sterility maintenance and shelf-life extension requirements differentiate healthcare formats from industrial bulk economics.
- Blister Packs:Thermoformed trays with Tyvek or foil lidding maintain sterile barrier for surgical wound dressings. EU MDR mandates serialized labeling and electronic data capture systems for lot traceability, with German and French converters absorbing compliance costs through premium pricing.
- Bulk Bags:Woven polypropylene or kraft multiwall constructions serve industrial sorbent procurement where contamination risk permits unpackaged handling. Chemical plant maintenance contracts specify cubic yard capacity for spill response inventory.
- Plastic Pouches:Individually wrapped formats balance sterility with unit cost for high-turnover hospital supply.
- Cardboard Boxes:Secondary containment for retail and institutional distribution channels.
- Flow Wraps:High-speed horizontal form-fill-seal for consumer hygiene products.
Regulatory compliance favors blister packs; cost minimization favors bulk bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German wound care procurement while cost-optimized formats dominate Indian healthcare infrastructure expansion. This asymmetry fragments margin structures across geographies.
Germany
Advanced wound care infrastructure and aging demographics sustain premium product uptake for silicone-adhesive medical dressings. EU MDR biocompatibility mandates tighten traceability standards for disposable materials. The Rhine-Ruhr and Bavarian medical technology clusters concentrate converter operations serving hospital group purchasing organizations.
United States
IDN-affiliated surgical centers across Texas and Florida consolidate procurement around dual-source contracting with volume commitments. FDA 510(k) clearance pathways shape development timelines for novel core compositions. The US Gulf Coast hosts integrated petrochemical producers supplying acrylic acid derivatives for superabsorbent polymer formulations.
India
Underpenetrated healthcare infrastructure and expanding CDSCO medical device registration pathways open domestic manufacturing placement. PLI scheme incentives attract antimicrobial wound dressing production. Maharashtra and Gujarat industrial corridors concentrate emerging converter capacity for hospital and consumer channels.
Japan
Aging demographics and chronic wound prevalence expand hospital and home health demand for moisture-retentive healing environments. PMDA regulatory frameworks align with international standards through MHLW harmonization initiatives. The Kanto and Kansai regions concentrate formulation chemistry expertise for superabsorbent gelation control.
France
Extended producer responsibility frameworks accelerate material substitution toward certified compostable nonwoven cores. REACH-compliant bioplastics certification determines procurement eligibility for public hospital tenders. The Auvergne-Rhône-Alpes region hosts specialty polymer research facilities serving medical and food packaging converters.
Global Absorbent Pads Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated polymer producers commanding margin control while converter-dependent specialists compete on formulation differentiation. The vendor base spans multinational conglomerates with captive nonwoven capacity, regional thermoforming specialists, and superabsorbent polymer formulators. Three archetypes dominate: backward-integrated material producers, tray-integration packaging converters, and SAP formulation specialists. Competitive moves concentrate on ISO 13485 certification convergence for multi-jurisdiction supply and thermoformed equipment retrofitting for absorbent pad insertion modules.
Among Germany-based fabricators, W. Dimer GmbH exemplifies regional converter specialization, while 3M Company anchors the technology-integrated tier with multinational manufacturing scope. Novipax LLC occupies a position within the superabsorbent formulation specialist archetype, representing the polymer science-driven competitive vector.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| W. Dimer GmbH |
| 3M Company |
| Cellcomb AB |
| Sirane Limited |
| Novipax LLC |
| Pactiv Evergreen Inc. |
| Cocopac Limited |
| Brady Corporation |
| Others |
Supply & Pricing Matrix
Bioplastics substitution for petroleum-derived nonwoven cores is simultaneously relocating converter operations toward REACH-certified supply zones in France and Italy while compressing margin structures for acrylic acid-dependent superabsorbent formulations. This material transition bifurcates pricing power between integrated polymer producers with captive bioplastic capacity and converter-dependent specialists exposed to feedstock volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order medical wound dressings from standard industrial sorbents. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU MDR certification grade and silicone-adhesive interface complexity. Cost compression in commodity cellulose pads is intensifying because of group purchasing organization consolidation in Texas and Florida health systems. Consumer household segments exhibit highest price elasticity, while German hospital procurement teams show lowest sensitivity due to specification-driven tender processes.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion are elevating landed costs for US Gulf Coast acrylic acid derivatives and Northeast Asian superabsorbent polymer feedstocks. Supply concentrates in Germany, the United States, and Japan for medical-grade converter operations, with raw material dependencies on acrylic acid derivatives, cellulose pulp, and polypropylene meltblown media. Single-source vulnerability concentrates in integrated petrochemical producers controlling superabsorbent polymer precursor supply. Distribution runs through hospital group purchasing organizations in North America and regional medical device distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Absorbent Pads Market expansion sits in early-cycle territory, with antimicrobial wound dressing penetration in Indian healthcare infrastructure providing sustained adoption tailwinds.
For Market Incumbents: Secure dual-source contracting relationships with IDN-affiliated surgical centers before procurement consolidation hardens supplier panels. Defend margin position by accelerating ISO 13485 certification convergence for multi-jurisdiction supply and investing in thermoformed tray-insertion module retrofitting to capture food packaging premium positioning. For New Entrants and Emerging Players: Post-acute home wound management services represent an under-served layer where incumbents lack dedicated logistics infrastructure. Target Maharashtra and Gujarat industrial corridors for CDSCO-registered domestic manufacturing placement. Pursue direct-to-hospital contracting models bypassing fragmented distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed superabsorbent polymer formulators lacking backward integration into bioplastic feedstocks. Five-to-ten-year viability hinges on material substitution execution capabilities. Monitor EU MDR notified body bottleneck resolution as inflection indicator for novel wound dressing time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Convergence | Enables single-facility supply to German and French hospital systems, reducing geographic fragmentation costs. |
| Bioplastic Feedstock Transition | Positions converters for REACH-compliant tender eligibility in French public hospital procurement. |
| Thermoformed Tray Integration | Captures premium positioning in US and Canadian poultry and seafood retail packaging channels. |
| Antimicrobial Formulation Development | Differentiates wound care portfolios for chronic and surgical exudate management applications. |
| Indian Domestic Manufacturing Placement | Leverages PLI scheme incentives and CDSCO registration pathways for emerging healthcare infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases. Primary interviews engaged wound care clinicians, biomedical engineers, GPO contracts managers, and converter operations directors across Germany, the United States, and Japan. Secondary sources included customs trade data, SEC filings from integrated polymer producers, and CMS Medicare reimbursement schedules. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled encompass product type classification, application end-use, certification tier, and regional regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends by segment. Industry-specific forecast inputs incorporated surgical procedure volume trajectories and chronic wound prevalence demographics.
Underlying assumptions cover stable EU MDR implementation timelines and REACH bioplastics certification continuity, with deviation risk concentrated in notified body capacity constraints and acrylic acid derivative supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Chemical Absorbent Pads Market