
 Dry Powder Refilling Machine Market | 2026-2036
Dry Powder Refilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Powder Refilling Machine Market Foresight
China's pharmaceutical manufacturing corridor is reconfiguring capacity for high-containment powder handling. All-Fill Inc. leverages servo-driven electronic technology for precise dose control in oncology APIs. Marchesini Group anchors European aseptic filling demand through integrated isolator-barrier systems. Bosch Packaging Technology dominates cleanroom-compatible configurations with backward integration into containment engineering.
A dry powder refilling machine is a precision dosing system that transfers measured quantities of free-flowing or cohesive powders into primary containers using auger screws, vacuum pressure, or gravimetric load cells with accuracy typically within one percent of target weight. These systems serve pharmaceutical, food processing, and specialty chemical operations where cross-contamination control and batch traceability are mandatory. Automatic electronic fillers lead unit shipments due to programmable recipe management and reduced operator exposure in potent compound handling. Aseptic fillers command premium positioning as biologics and cytotoxic formulations multiply validation requirements for isolator-integrated lines. Manual and semi-automatic variants retain share in pilot-scale operations and emerging-market contract manufacturers with limited capital budgets.
The US FDA enforces Current Good Manufacturing Practice for Finished Pharmaceuticals under 21 CFR Part 211, mandating validated cleaning protocols and containment verification for multi-product powder lines. The European Medicines Agency applies Annex 1 revisions requiring continuous monitoring of viable and non-viable particle counts during aseptic powder transfer operations. India's Central Drugs Standard Control Organization aligns Schedule M with PIC/S standards, compelling domestic manufacturers to replace open-manual filling with closed automated systems for export eligibility. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting between pneumatic mechanical retrofits and full electronic platform replacements.
Market Dynamics
EU GMP Annex 1 revisions and tightened Indian Schedule M guidelines are forcing pharmaceutical manufacturers to retire open-manual filling stations and install closed automated systems with isolator-barrier integration, compressing replacement cycles from ten years to five.
Growth Catalysts
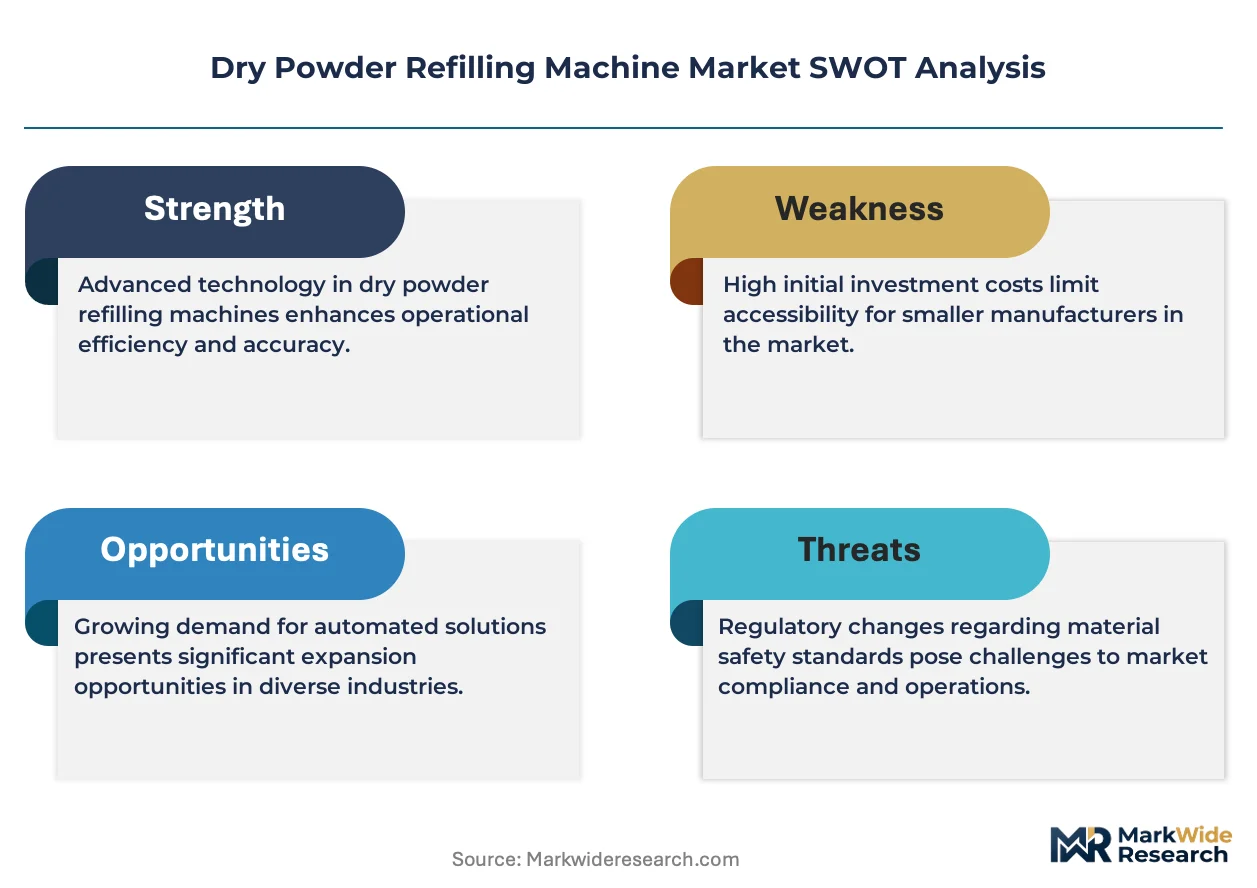
- Oncology API expansion:Cytotoxic and high-potency compound manufacturing is accelerating demand for containment-verified aseptic filling lines with continuous viable particle monitoring.
- CDSCO Schedule M alignment:India's export eligibility requirements are compelling domestic contract manufacturers to replace mechanical fillers with electronic platforms featuring batch traceability systems.
- Servo-driven dose control:Electronic auger technology with gravimetric feedback loops is displacing pneumatic mechanical systems in Bavaria's chemical corridor and Gujarat's pharma cluster.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for pharmaceutical-grade 316L stainless steel and precision servo components are compressing OEM margins and extending quote validity periods.
- Containment engineering concentration:Backward integration into isolator design and HEPA filtration systems concentrates among three European engineering groups, creating supply bottleneck risk.
- Cross-contamination verification complexity:Validated cleaning protocol development for multi-product lines under 21 CFR Part 211 requires six to twelve months of regulatory documentation.
Strategic Opportunities
- Brazilian ANVISA modernization:Latin American pharmaceutical manufacturing expansion under updated GMP frameworks creates first-mover advantage for electronic filler vendors with Portuguese-language validation support.
- Continuous manufacturing integration:Direct compression tableting lines with inline powder refilling are converging with real-time release testing protocols, enabling twenty-four-hour batchless production.
- Modular skid-based delivery:Pre-validated plug-and-play filling modules are opening rental and equipment-as-service channels for emerging-market contract packagers with constrained capex budgets.
Industry Challenges
- Isolator-integrated commissioning:Aseptic filler installation with barrier system qualification demands specialized cleanroom contractors, extending project timelines and inflating site preparation costs.
- Recipe migration complexity:Transferring validated powder flow parameters from legacy mechanical systems to electronic platforms requires extensive DOE studies and regulatory resubmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Powder Refilling Machine Market |
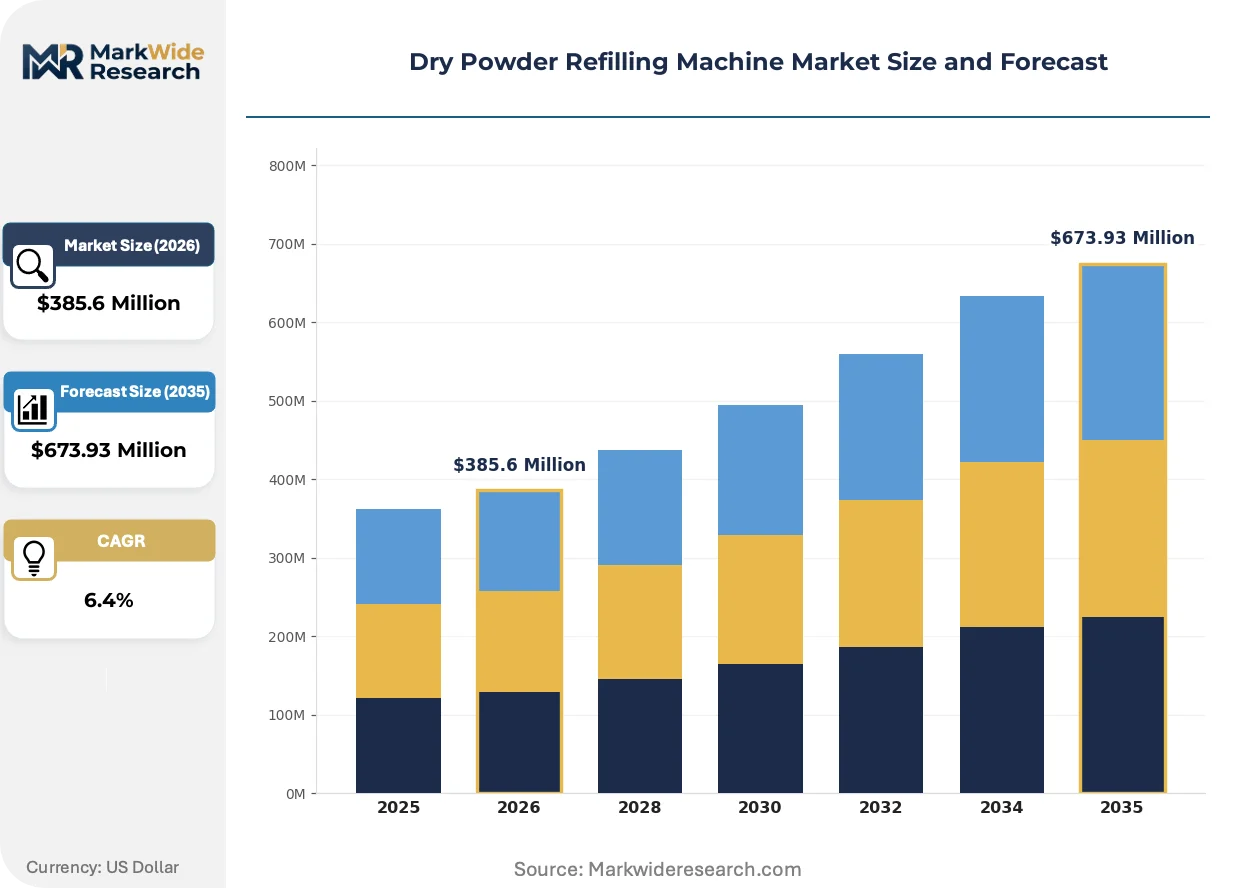
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aseptic Fillers, Manual Fillers, Automatic Fillers, Semi-automatic Fillers End User: Pharmaceuticals, Food & Beverage, Chemicals, Cosmetics Technology: Mechanical, Pneumatic, Electronic, Hydraulic Packaging Type: Bags, Bottles, Pouches, Boxes |
| Companies Covered | Accutek Packaging Equipment Companies, All-Fill Inc., Marchesini Group, IMA Group, Bosch Packaging Technology, Robert Bosch GmbH, Hanningfield Process Systems Ltd., MG2, Cozzoli Machine Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Powder Refilling Machine Market Shifts & Advancements
Machine learning algorithms and real-time spectroscopic feedback are digitizing powder flow characterization, enabling predictive adjustment of auger speeds and compression forces during active filling operations.
Servo-driven electronic auger systems with gravimetric load cells and adaptive speed control are digitizing dose accuracy in oncology API handling. German and Indian pharmaceutical manufacturers are retrofitting legacy pneumatic lines at accelerated pace. This compression of replacement cycles is reshaping competitive positioning toward vendors with captive containment engineering capabilities.
The European Medicines Agency's Annex 1 revisions mandate continuous environmental monitoring during aseptic powder transfer, with viable particle count thresholds enforced through automated sampling systems. Pharmaceutical manufacturers must now integrate isolator-barrier configurations with centralized data logging for batch release documentation. Aseptic filler vendors with pre-validated containment packages are capturing premium positioning in EU and UK tender processes.
Contract packagers in emerging markets are unbundling equipment purchase from validation service contracts, preferring turnkey project delivery with guaranteed regulatory acceptance timelines. This procurement model shift is compressing vendor selection criteria toward integrated engineering groups with in-house protocol development teams. The transformation is most visible in India's CDSCO-inspected facilities upgrading for PIC/S export eligibility.
Dry Powder Refilling Machine Market Segmentation
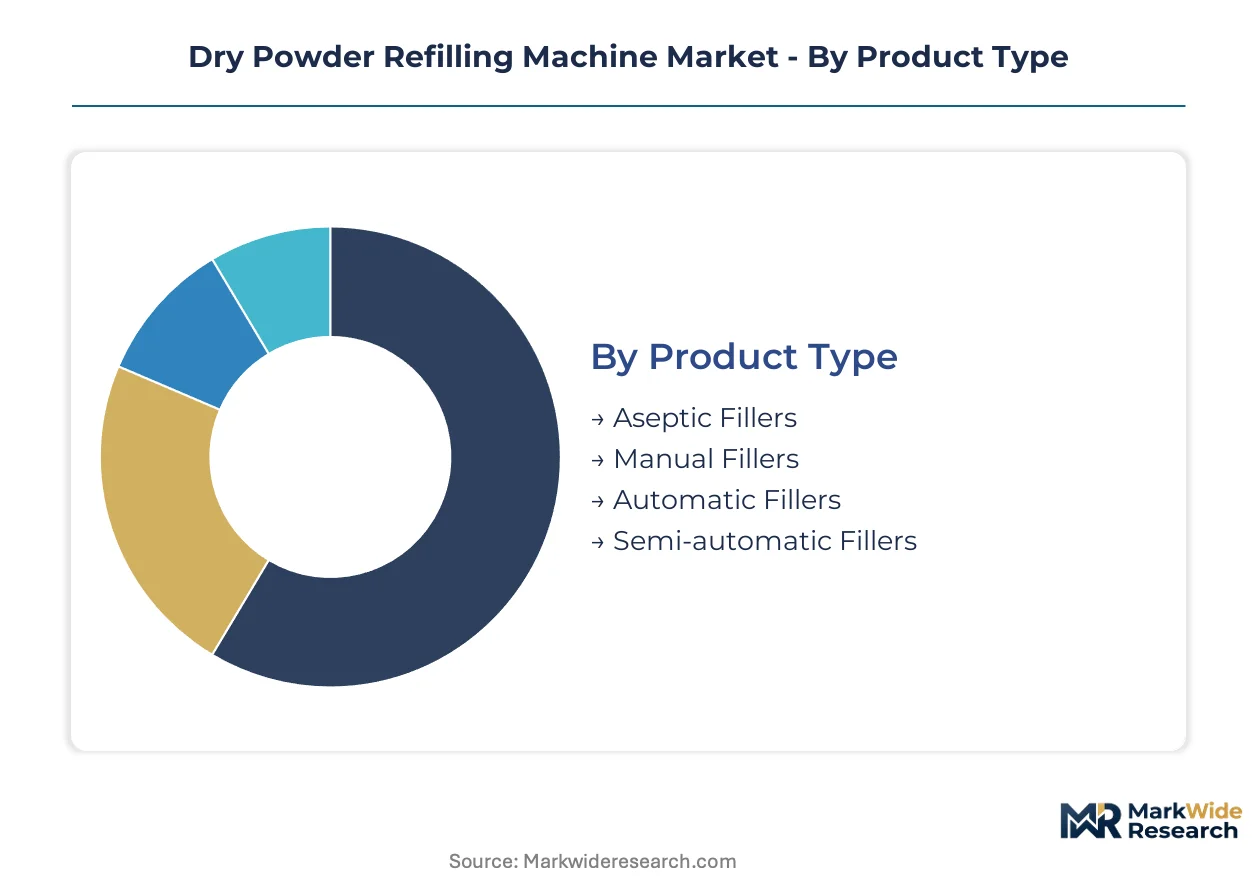
Dry powder refilling machines serve distinct operational regimes where containment requirements, batch volumes, and regulatory exposure determine equipment selection. Segmentation reveals how technology choices cascade through validation complexity, capital deployment, and geographic procurement patterns.
Product Type:
Cost tier structures the equipment landscape from containment-verified aseptic systems to entry-level manual stations.
- Aseptic Fillers:Isolator-integrated barrier systems with continuous viable particle monitoring serve oncology API manufacturing under EMA Annex 1 and FDA 21 CFR Part 211. German pharmaceutical manufacturers in Bavaria's chemical corridor and Indian contract packagers in Gujarat's pharma cluster are compressing replacement cycles to five years for these configurations.
- Automatic Fillers:Servo-driven electronic auger platforms with gravimetric feedback loops enable programmable recipe management and reduced operator exposure. Demand concentrates where CDSCO Schedule M alignment and EU GMP export eligibility require closed automated systems with batch traceability.
- Manual Fillers:Open-manual stations retain position in pilot-scale operations and emerging-market facilities with constrained capital budgets.
- Semi-automatic Fillers:Hybrid configurations bridge mechanical legacy systems and full electronic platforms during phased upgrades.
Automatic fillers command the established base. The steepest expansion runs through aseptic fillers.
End User:
Application severity determines containment engineering specifications and validation protocol intensity.
- Pharmaceuticals:Cytotoxic and high-potency compound handling mandates isolator-barrier integration with HEPA filtration and automated environmental sampling. Brazilian ANVISA modernization and India's PIC/S export alignment are accelerating electronic platform adoption.
- Chemicals:Specialty chemical operations in Germany's chemical corridor require containment-verified systems for reactive powder handling with cross-contamination controls.
- Food & Beverage:Free-flowing ingredient dosing prioritizes throughput and cleanability over containment engineering.
- Cosmetics:Colorant and active powder filling emphasizes batch consistency and operator safety in mid-volume production.
Pharmaceuticals anchor revenue concentration. Chemicals are climbing the fastest on containment upgrade cycles.
Technology:
Volume throughput and dose precision requirements segment the drive mechanism landscape.
- Electronic:Servo motor-driven auger systems with adaptive speed control and real-time gravimetric feedback deliver sub-one-percent dose accuracy. Retrofit demand from pneumatic legacy lines in Gujarat and Bavaria is displacing mechanical platforms.
- Pneumatic:Compressed-air actuated systems face accelerated retirement where regulatory compliance timelines compress replacement decisions.
- Mechanical:Gear-driven auger configurations retain installed base in low-changeover, single-product operations.
- Hydraulic:High-force compression applications in dense powder handling occupy niche positions in specialty chemical processing.
Electronic systems capture the upgrade wave. Pneumatic maintains residual share in cost-constrained procurement.
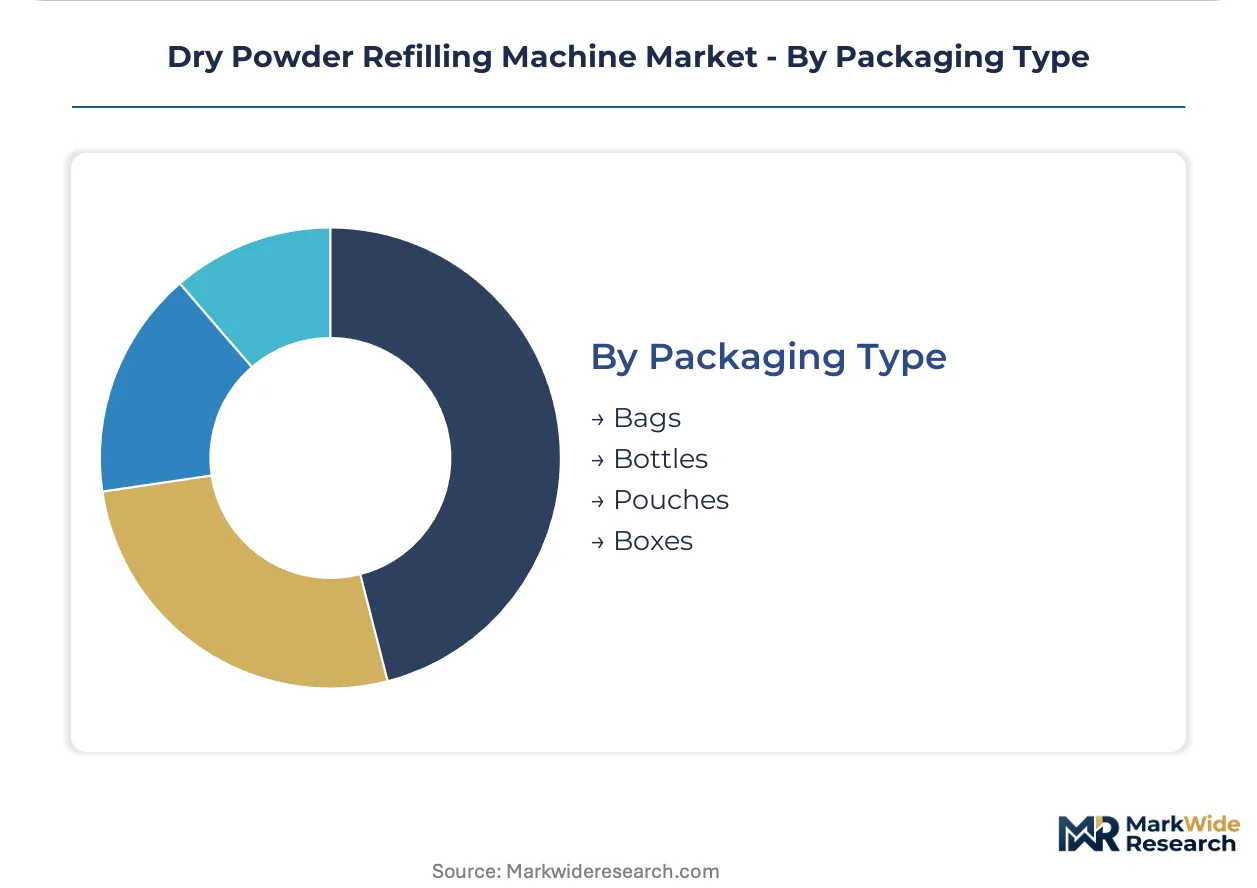
Packaging Type:
Customer type and container geometry dictate filling head configuration and changeover protocol design.
- Bottles:Rigid container handling with screw-cap integration dominates oral solid dosage packaging for pharmaceutical distribution.
- Pouches:Flexible film forming and sealing compatibility serves unit-dose and sample packaging in contract manufacturing.
- Bags:Intermediate bulk container filling with liner systems supports active pharmaceutical ingredient transfer operations.
- Boxes:Cartoning integration for retail-ready packaging occupies food processing and cosmetics finishing lines.
Bottles hold the installed base. Pouches are gaining share fastest on unit-dose demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturers deploy aseptic fillers for oncology APIs under EMA Annex 1, while Indian contract packagers prioritize electronic platforms for PIC/S export eligibility. This divergence shapes procurement patterns across developed and emerging manufacturing corridors.
Germany
Bavaria's chemical corridor drives containment-verified aseptic system demand for high-potency compound handling. EMA Annex 1 revisions mandate continuous viable particle monitoring during powder transfer operations. Bosch Packaging Technology anchors European supply through backward integration into isolator engineering.
India
Gujarat's pharma cluster concentrates automatic electronic filler procurement for Schedule M compliance and export market access. CDSCO alignment with PIC/S standards compels replacement of open-manual stations with closed automated systems. Contract packagers in Ahmedabad and Vadodara compress replacement cycles to five years.
United States
Oncology API manufacturing expansion accelerates demand for containment-verified filling lines with HEPA filtration. FDA 21 CFR Part 211 enforces validated cleaning protocols for multi-product powder operations. New Jersey and Massachusetts biotech corridors lead isolator-integrated line installations.
China
Yangtze River Delta pharmaceutical manufacturers reconfigure capacity for high-containment powder handling under NMPA GMP guidelines. Domestic producers upgrade mechanical legacy systems to servo-driven electronic platforms. Shanghai and Suzhou clusters prioritize batch traceability systems for international contract manufacturing.
Brazil
São Paulo pharmaceutical manufacturers modernize under ANVISA GMP framework updates. Electronic filler vendors with Portuguese-language validation support capture first-mover positioning. Local contract packagers shift from manual stations toward semi-automatic configurations as regulatory timelines compress.
Dry Powder Refilling Machine Market Competitive Landscape
Capability concentration sits with engineering-intensive tier; scale advantage sits with diversified packaging conglomerates. The vendor base stratifies across three tiers: integrated isolator specialists, diversified machinery conglomerates, and regional electronic platform fabricators. Dominant competitive moves include backward integration into containment engineering and pre-validated modular system development.
Among diversified European machinery groups, Marchesini Group and IMA Group exemplify integrated engineering capabilities spanning isolator-barrier systems and aseptic filling platforms. Bosch Packaging Technology occupies a position at the premium tier through captive supply of containment engineering and cleanroom-compatible configurations. All-Fill Inc. represents servo-driven electronic specialists competing on dose precision in oncology API applications.
| Leading Market Players |
|---|
| Accutek Packaging Equipment Companies |
| All-Fill Inc. |
| Marchesini Group |
| IMA Group |
| Bosch Packaging Technology |
| Robert Bosch GmbH |
| Hanningfield Process Systems Ltd. |
| MG2 |
| Cozzoli Machine Company |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade 316L stainless steel cost volatility determines both tiered pricing spreads and supply chain resilience strategies across OEM procurement desks. Servo motor price swings compress margins on electronic platforms while extending quote validity periods, forcing buyers to choose between pneumatic mechanical retrofits and full system replacements.
Pricing Analysis
German and Indian markets exhibit the widest price spreads, with Bavaria's chemical corridor commanding premium positioning for isolator-integrated aseptic systems against Gujarat's cost-optimized electronic platforms. Three-tier pricing structure across premium containment-verified, standard closed-automated, and economy manual configurations separates CDSCO-inspected export facilities from domestic-only operations. Pricing pressure stems from input cost volatility in precision servo components and pharmaceutical-grade alloys. Contract packagers in emerging markets show highest price sensitivity, while oncology API manufacturers in New Jersey and Massachusetts absorb premiums for HEPA filtration and continuous monitoring capabilities.
Supply Chain Analysis
Tariff exposure between China and Western pharmaceutical equipment buyers dominates supply chain risk calculations for precision servo motors and HEPA filtration media. Manufacturing concentration rests on Germany, Italy, and China for isolator-barrier systems, auger screw assemblies, and control electronics respectively. Raw material dependencies draw from Japanese servo motor suppliers, Swedish specialty steel producers, and domestic Chinese HEPA filter manufacturers. Single-source vulnerability concentrates in isolator engineering among three European engineering groups. Distribution runs through direct OEM sales for large pharmaceutical accounts and specialized equipment distributors serving contract packagers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validation service contracts now expand faster than hardware shipments as Brazilian ANVISA modernization and Indian PIC/S alignment compress procurement timelines. Equipment-as-service and modular rental channels capture emerging-market contract packagers with constrained capex budgets.
For Market Incumbents: Build captive containment engineering capabilities to defend against specialized isolator vendors encroaching on aseptic filler tenders. Backward integration into HEPA filtration system production secures supply bottleneck protection. Pre-validated modular skid offerings counter rental-channel disruption from emerging entrants. Certification investment in Portuguese-language validation protocols captures ANVISA modernization first-mover positioning. For New Entrants and Emerging Players: Establish a beachhead in Brazil's São Paulo pharmaceutical corridor where ANVISA GMP framework updates create vendor selection windows. Semi-automatic configurations for mid-tier contract packagers shifting from manual stations represent the most penetrable segment. Portuguese-language validation support and guaranteed regulatory acceptance timelines differentiate against established European vendors with slower localization. For Investors and Strategic Acquirers: EU GMP Annex 1 implementation deadlines reshape the acquisition landscape toward isolator-integrated platform specialists over standalone filler manufacturers. Five-to-ten year viability favors engineering-intensive mid-caps with captive containment capabilities over diversified machinery conglomerates facing margin compression. The signal to monitor is CDSCO inspection pass rates for PIC/S export eligibility, indicating which Indian contract packagers will accelerate replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containment Engineering | Bosch Packaging Technology anchors European supply through captive isolator design capabilities. |
| Pre-Validated Modular Skid Development | Equipment-as-service channels open rental markets for emerging-market contract packagers. |
| Portuguese-Language Validation Support | ANVISA modernization creates first-mover advantage for localized regulatory documentation. |
| Servo-Driven Electronic Platform Migration | All-Fill Inc. competes on dose precision as pneumatic legacy lines face accelerated retirement. |
| Continuous Manufacturing Integration | Direct compression tableting convergence enables twenty-four-hour batchless production with inline powder refilling. |
Research Methodology
A standing panel of pharmaceutical manufacturing directors, validation engineers, contract packaging procurement leads, and CDSCO regulatory consultants provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EMA Annex 1 revision texts, CDSCO Schedule M circulars, and Indian pharmaceutical export association filings. Bottom-up equipment shipment tracking triangulated against top-down pharmaceutical capex surveys across Bavaria, Gujarat, New Jersey, and São Paulo corridors.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled included product type tier, end-use severity, technology drive mechanism, and regional regulatory cluster alignment. CAGRs derived from weighted average of historical replacement cycle compression rates and forward regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporated isolator-integrated line commissioning duration data and servo motor cost trajectory indices.
Sensitivities concentrate around stainless steel alloy price volatility, EU GMP Annex 1 enforcement timing, and ANVISA inspection capacity expansion rates. Forecasts reflect documented assumptions on replacement cycle compression and export eligibility-driven procurement acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Global Absorbent Pads Market