
 High Voltage Electric Insulators Market | 2026-2036
High Voltage Electric Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Electric Insulators Market Insights
The capital-intensity divergence between in-house ceramic processing and outsourced polymer assembly is redrawing competitive boundaries in high voltage electric insulators. NGK Insulators leverages captive alumina mines and tunnel-kiln networks to sustain cost leadership in porcelain cores. Siemens Energy anchors its position through integrated silicone rubber compounding and automated injection molding for composite designs.
High voltage electric insulators are passive electrical components engineered to mechanically support and electrically isolate energized conductors from grounded structures, typically rated above 1 kV AC or 1.5 kV DC, with creepage distances and lightning impulse withstand voltages calibrated to IEC 60060-1 and IEEE C29.11 standards. They prevent flashover, leakage current, and mechanical failure across transmission towers, substation buswork, and transformer bushings in environments spanning desert contamination to coastal salt fog. Composite insulators incorporating silicone rubber housings and fiber-reinforced polymer rods represent the fastest-expanding material technology segment, displacing porcelain in compact transmission designs where weight reduction and vandalism resistance command premium positioning. Ceramic formulations retain dominance in ultra-high voltage substation applications where decades of in-service data validate long-term hydrophobic stability and structural integrity under mechanical load.
IEC 60383, IEEE C29, and China's GB/T 7253 standards govern dimensioning, testing protocols, and contamination class ratings that determine product qualification for grid tenders and utility procurement cycles. India's Central Electricity Authority mandates type-testing adherence for 400 kV and above installations, creating regulatory moats for certified manufacturers. Stakeholders must track evolving composite material aging validation protocols and sulfur hexafluoride-free switchgear insulation requirements that will redefine material selection criteria across transmission and distribution architectures.
Market Dynamics
Composite insulator technology is compressing procurement cycles as utilities rewrite material specifications to favor silicone rubber housings over porcelain for new transmission corridors, forcing ceramic specialists to defend substation positions through accelerated type-testing investments.
Growth Catalysts
- Offshore wind interconnection mandates:China's coastal provinces and India's Tamil Nadu are mandating 66 kV and 132 kV collector systems that demand compact, lightweight composite designs for offshore platforms.
- IEC 60383 contamination class upgrades:Grid operators in desert and coastal zones are re-specifying creepage distances, triggering replacement waves across 220 kV and 400 kV lines installed under older standards.
- Silicone rubber compounding advances:In-house polymer formulation capabilities now enable manufacturers to tailor hydrophobicity profiles for specific climatic zones, shortening qualification timelines.
Market Restraints
- Alumina supply concentration:Premium-grade calcined alumina for porcelain cores concentrates in Chinese and Guyanese mining jurisdictions, exposing ceramic insulator producers to export quota volatility.
- Polymer raw material cost structure:Silicone rubber and fiber-reinforced epoxy rod prices track petrochemical feedstock indices, compressing margins for composite specialists during crude oil spikes.
- Long-term aging data gaps:Composite insulators lack 30-year service records in ultra-high voltage substations, slowing adoption beyond 420 kV where porcelain's empirical reliability dominates tender evaluations.
Strategic Opportunities
- SF6-free switchgear insulation convergence:Vacuum interrupter and dry air insulation designs require redesigned bushing interfaces, creating specification windows for modular composite insulator assemblies.
- India's transmission buildout acceleration:Green Energy Corridors and inter-regional HVDC links are expanding addressable demand for 800 kV DC wall bushings and converter station hardware.
- Digital twin integration:Embedded fiber optic sensors for leakage current monitoring and mechanical load tracking enable predictive maintenance contracts, shifting revenue toward lifecycle service models.
Industry Challenges
- Type-testing backlog compression:India's CEA certification queue for 400 kV and above installations stretches 18-24 months, delaying project commissioning and working capital recovery.
- Multi-standard harmonization friction:Simultaneous compliance with IEC 60383, IEEE C29.11, and China's GB/T 7253 requires parallel test programs that fragment R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Electric Insulators Market |
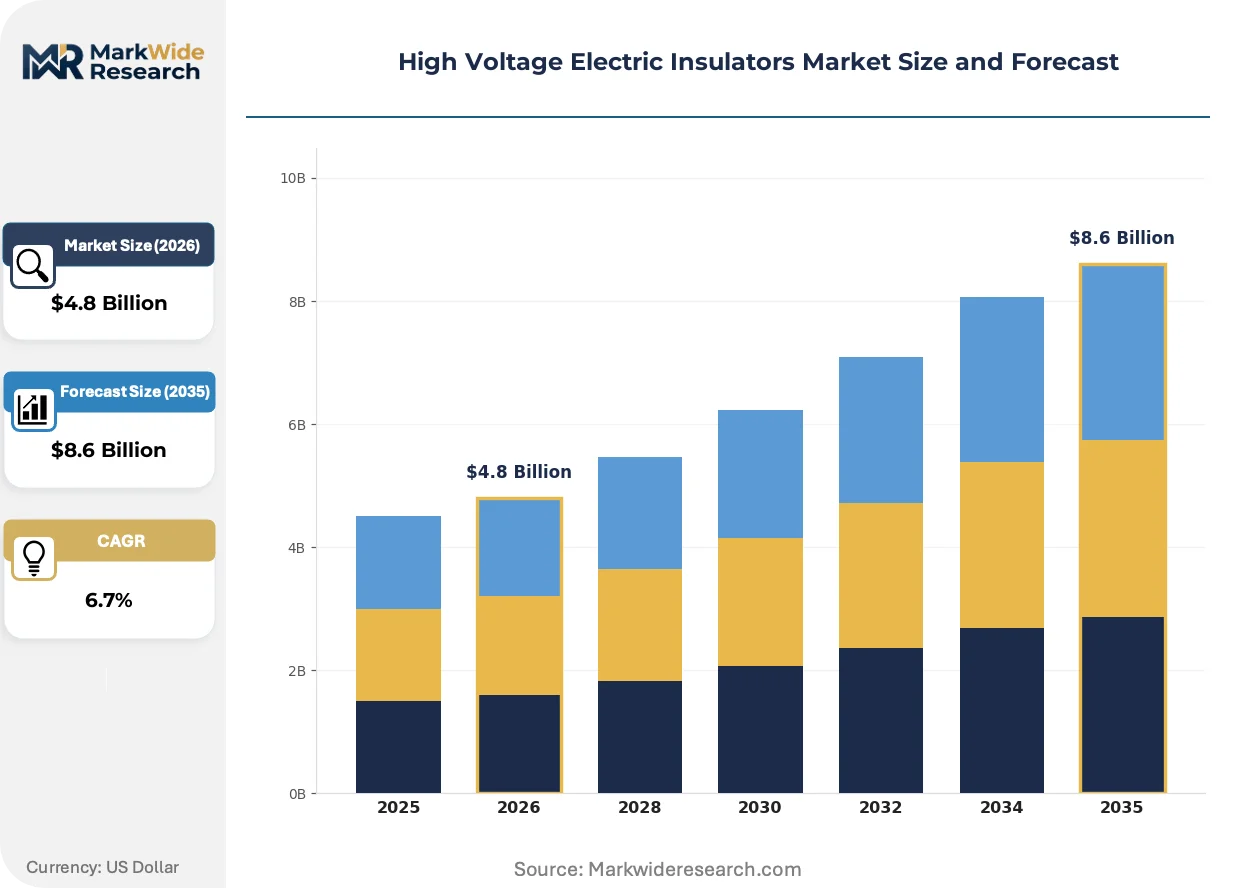
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain, Glass, Polymer, Composite Application: Transmission Lines, Substations, Switchgear, Transformers End User Industry: Utilities, Renewable Energy, Heavy Manufacturing, Telecommunication Material Technology: Ceramic, Silicone Rubber, Epoxy Resin, Fiber Reinforced Polymer |
| Companies Covered | NGK Insulators, Siemens Energy, Hitachi Energy, Hubbell, Sediver, Aditya Birla Insulators, CYG Insulator, PFISTERER, LAPP Insulators, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Electric Insulators Market Trends and Innovations
Material science advances and digital instrumentation are rewriting performance benchmarks for outdoor insulation systems, compressing the traditional porcelain-composite reliability gap while embedding intelligence into passive components.
Silicone rubber housing formulations with enhanced UV and tracking resistance are supplanting traditional porcelain in compact 132 kV and 220 kV transmission designs where tower loading constraints and helicopter live-line maintenance protocols favor reduced weight. European and Chinese utilities are accelerating composite adoption for corridor upgrades, enabling narrower right-of-way specifications that accelerate permitting timelines.
China's GB/T 7253 revisions and India's CEA technical standards are tightening contamination performance verification protocols, mandating accelerated aging tests that extend qualification cycles by 12-18 months. Manufacturers with captive testing laboratories in Tianjin and Bengaluru are securing first-mover advantage in tender pre-qualification rounds.
Utility procurement departments are consolidating supplier panels around certified manufacturers with integrated composite compounding and injection molding capabilities, displacing merchant-market porcelain distributors. This concentration is most visible in China's State Grid and Southern Power Grid consolidated tender frameworks, where multi-year framework agreements now cover 60-70% of annual composite insulator volume.
High Voltage Electric Insulators Market Segmentation
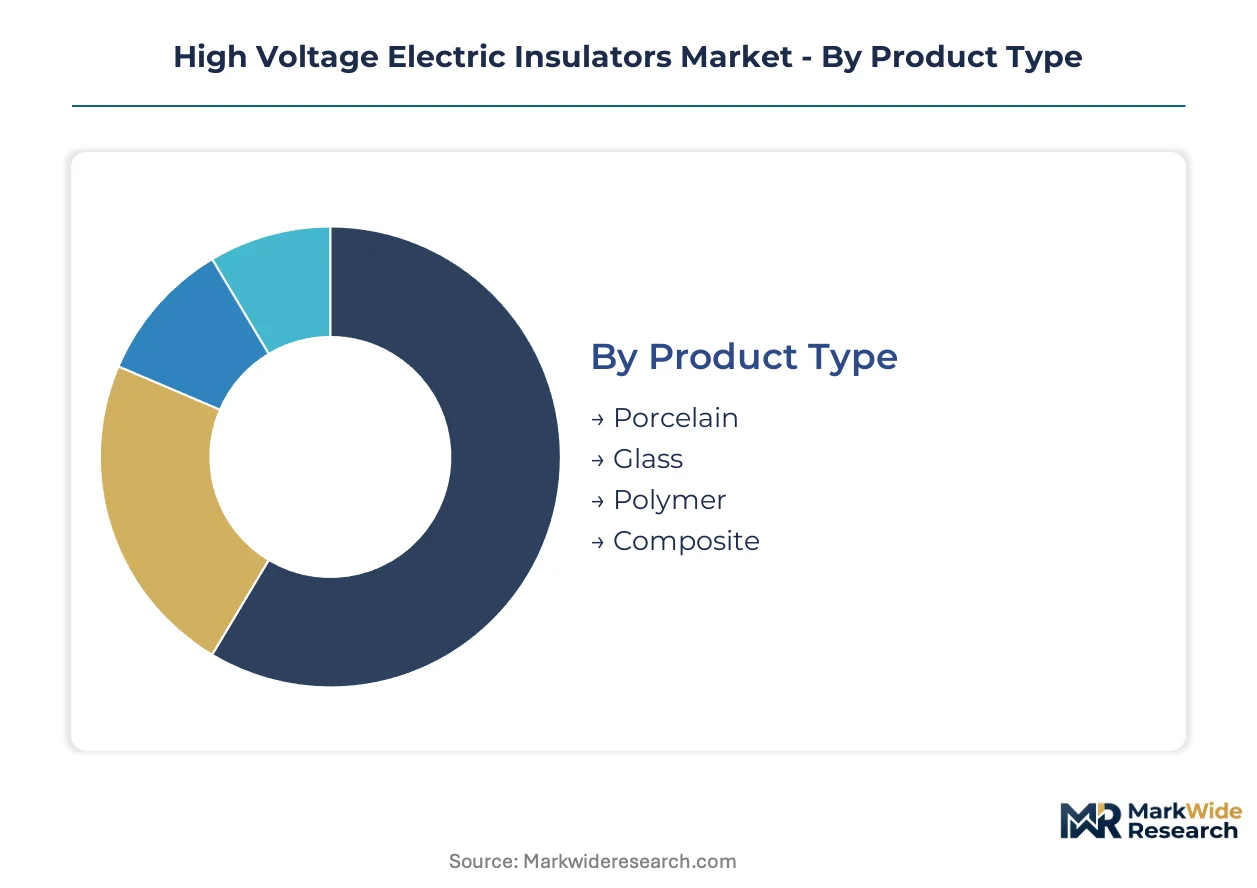
Segmentation in high voltage electric insulators reveals divergent margin structures across material technologies and application contexts. Procurement patterns in utilities versus renewable developers create distinct performance specifications that reshape supplier positioning.
Product Type:
Premium margin pools concentrate in polymer and composite formulations where proprietary compounding capabilities create defensible positions.
- Composite:Silicone rubber housings bonded to fiber-reinforced polymer rods deliver sub-10% weight reduction versus porcelain. Demand clusters in China's offshore wind collector systems and India's Green Energy Corridors where helicopter live-line maintenance protocols favor lightweight designs. IEC 60383 contamination class upgrades accelerate substitution in coastal zones.
- Polymer:Thermoplastic and elastomeric formulations target medium-voltage distribution with injection-molded cost structures. German and US utilities specify these for compact urban substations where space constraints override porcelain's thermal endurance.
- Porcelain:Alumina-based ceramic cores retain dominance in 420 kV+ substation applications where decades of in-service data validate hydrophobic stability.
- Glass:Toughened glass discs persist in legacy transmission corridors across Eastern Europe and Russia where existing tower hardware resists material conversion.
The dominant share belongs to Porcelain, while Composite is closing the gap fastest.
Application:
Volume concentration tracks transmission infrastructure buildout cycles, with substation and switchgear applications commanding higher unit margins due to qualification complexity.
- Transmission Lines:Suspension and tension assemblies for 66 kV through 800 kV corridors constitute the highest-volume deployment channel. China's State Grid and Southern Power Grid consolidated tenders drive procurement consolidation around certified composite suppliers.
- Substations:Post and bushing insulators for 400 kV and above installations face India's CEA type-testing backlog, creating 18-24 month qualification delays that favor incumbents with captive laboratory capacity.
- Switchgear:SF6-free vacuum interrupter designs require redesigned bushing interfaces, opening specification windows for modular composite assemblies.
- Transformers:Oil-immersed and dry-type transformer bushings demand tailored creepage distances for high-altitude installations in the Andes and Himalayas.
Transmission Lines capture the largest volume position, with Switchgear expanding most quickly amid insulation gas transition mandates.
End User Industry:
Customer-type segmentation exposes divergent procurement sophistication, with utilities emphasizing lifecycle cost and renewable developers prioritizing installation speed.
- Utilities:State-owned grid operators in China, India, and the United States dominate tender volumes. These buyers mandate IEC 60383 and IEEE C29.11 compliance with multi-year framework agreements covering 60-70% of composite insulator volume.
- Renewable Energy:Offshore wind developers in China's coastal provinces and India's Tamil Nadu specify 66 kV and 132 kV collector systems with accelerated delivery timelines.
- Heavy Manufacturing:Steel and aluminum smelters require specialized contamination-resistant designs for high-pollution industrial zones.
- Telecommunication:Antenna line hardware for broadcast and cellular towers represents a fragmented, price-sensitive channel.
Utilities retain the dominant procurement share, while Renewable Energy is gaining share fastest amid interconnection buildout mandates.
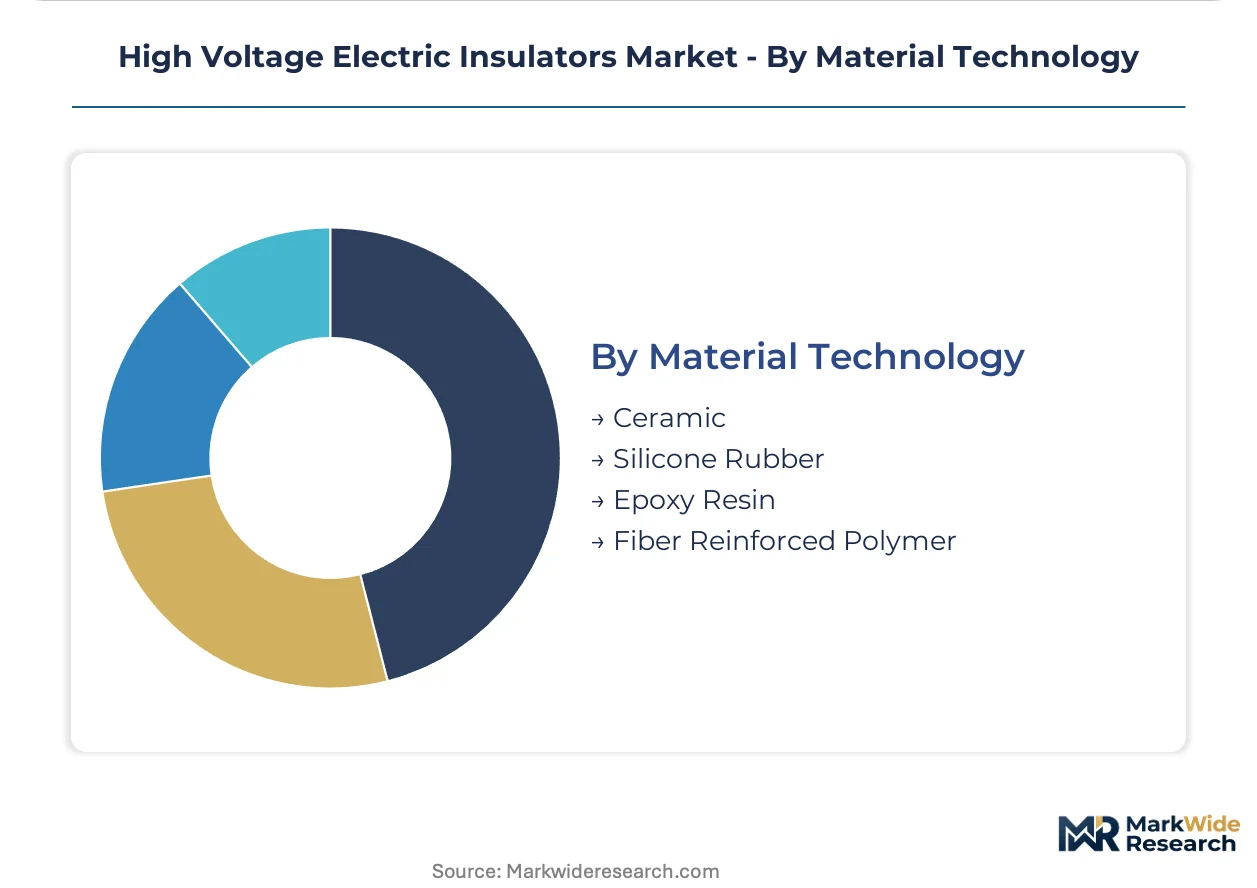
Material Technology:
Supply concentration in ceramic feedstocks versus petrochemical-linked polymer costs creates asymmetric margin volatility across this category.
- Silicone Rubber:Liquid silicone rubber and high-consistency rubber formulations enable tailored hydrophobicity profiles for specific climatic zones. In-house compounding capabilities at Siemens Energy and specialized Chinese manufacturers shorten qualification timelines.
- Ceramic:Alumina and steatite formulations from captive mines and tunnel-kiln networks sustain NGK Insulators' cost leadership in porcelain cores.
- Fiber Reinforced Polymer:E-glass and carbon fiber epoxy rods provide tensile strength for composite insulator mechanical loads.
- Epoxy Resin:Cycloaliphatic and bisphenol-A formulations target indoor switchgear and instrument transformer applications.
Ceramic holds the largest installed base, though Silicone Rubber is climbing the fastest as composite adoption accelerates in transmission corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys composite designs for offshore wind collector systems while India concentrates procurement around CEA-certified porcelain for substation upgrades. The United States balances aging grid replacement with renewable interconnection projects. Germany and Japan anchor composite material innovation and ultra-high voltage testing infrastructure respectively.
China
State Grid and Southern Power Grid drive demand through consolidated tenders covering 60-70% of annual composite insulator volume. GB/T 7253 revisions tighten contamination performance verification, extending qualification cycles by 12-18 months. Tianjin hosts captive testing laboratories securing first-mover advantage in tender pre-qualification rounds.
India
Green Energy Corridors and inter-regional HVDC links expand demand for 800 kV DC wall bushings and converter station hardware. Central Electricity Authority mandates type-testing adherence for 400 kV and above installations, creating 18-24 month certification backlogs. Bengaluru laboratory clusters serve CEA pre-qualification requirements for substation-focused suppliers.
United States
Aging transmission infrastructure and renewable interconnection projects drive replacement cycles across 220 kV and 400 kV corridors. FERC Order 1000 compliance frameworks shape regional transmission planning and procurement timelines. Texas and California grid operators specify composite designs for compact right-of-way corridors.
Germany
Offshore wind interconnection mandates in the North Sea and Baltic Sea drive 66 kV and 132 kV collector system specifications. EU Green Deal and F-Gas Regulation accelerate SF6-free switchgear transitions requiring redesigned bushing interfaces. Siemens Energy anchors composite compounding capabilities in Nuremberg manufacturing clusters.
Japan
Ultra-high voltage substation applications demand decades-validated porcelain reliability where empirical data dominates tender evaluations. METI technical standards govern dimensioning and testing protocols for 500 kV and above installations. Nagoya industrial corridors concentrate tunnel-kiln networks for alumina-based ceramic core production.
High Voltage Electric Insulators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in high voltage electric insulators. Ceramic specialists with captive alumina supply chains defend substation positions through accelerated type-testing investments. Composite manufacturers with in-house silicone rubber compounding capabilities capture transmission corridor volume. The dominant competitive moves are backward integration into raw material supply and geographic expansion through certified laboratory networks.
Among Japanese industrial conglomerates, NGK Insulators exemplifies the integrated ceramic archetype with tunnel-kiln networks sustaining cost leadership. Siemens Energy occupies a position representing the polymer-compounding vector through automated injection molding capabilities. Hitachi Energy sits within the diversified electrical equipment tier spanning transmission and distribution infrastructure.
| Leading Market Players |
|---|
| NGK Insulators |
| Siemens Energy |
| Hitachi Energy |
| Hubbell |
| Sediver |
| Aditya Birla Insulators |
| CYG Insulator |
| PFISTERER |
| LAPP Insulators |
| Others |
Pricing and Supply Chain Analysis
IEC 60383 certification requirements gate both supplier qualification and price differentiation in high voltage electric insulators, compressing procurement timelines for certified manufacturers while extending premium positioning windows for those with captive testing infrastructure. Buyers face bifurcated sourcing economics where CEA-mandated type-testing backlogs in India and GB/T 7253 revisions in China simultaneously constrain supply elasticity and sustain margin tiers across porcelain and composite formulations.
Pricing Analysis
Long-term framework agreements dominate procurement, with China's State Grid and Southern Power Grid consolidating 60-70% of annual composite insulator volume under multi-year contracts that compress spot market liquidity. Price differentiation rests on certification grade—CEA-qualified suppliers for 400 kV+ installations command substantial premiums over merchant-market distributors—and vertical integration into silicone rubber compounding or alumina processing. Cost compression in standard-grade porcelain intensifies as Chinese tunnel-kiln networks expand output, while premium composite tiers face margin pressure from petrochemical feedstock volatility. Renewable developers exhibit highest price sensitivity due to accelerated delivery timelines, whereas utility procurement officers prioritize lifecycle cost over unit price.
Supply Chain Analysis
Inbound logistics costs fluctuate with container availability on Asia-Europe trade lanes, particularly for German and Japanese manufacturers sourcing fiber-reinforced polymer rods from Chinese specialty chemical producers. Supply concentrates in China, India, and Japan—capturing ceramic processing, compounding capabilities, and ultra-high voltage testing infrastructure respectively. Raw material dependencies encompass premium-grade calcined alumina for porcelain cores, liquid silicone rubber for housing formulations, and E-glass epoxy rods for composite mechanical loads. Single-source vulnerability concentrates in Chinese alumina export quotas and Guyanese mining jurisdictions. Distribution runs through direct utility tender channels and certified manufacturer networks, displacing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite insulator technology is disrupting material specifications across transmission corridors, with IEC 60383 contamination class upgrades and SF6-free switchgear mandates creating simultaneous inflection points for procurement patterns and supplier positioning.
For Market Incumbents: Shield substation market share by accelerating type-testing investments in captive Bengaluru and Tianjin laboratories to exploit India's 18-24 month CEA certification backlogs. Consolidate backward integration into alumina mining or silicone rubber compounding to defend margin structures against petrochemical cost volatility and Chinese export quota uncertainty.
For New Entrants and Emerging Players: Anchor in India's Green Energy Corridor buildout and China's offshore wind collector system specifications, where 66 kV and 132 kV composite demand outpaces certified supplier capacity. Target modular bushing interfaces for SF6-free vacuum interrupter designs as the most penetrable specification window, leveraging partnerships with European switchgear OEMs to bypass entrenched utility tender panels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite compounding and automated injection molding capabilities, favoring scaled specialists over diversified industrial conglomerates. Long-term viability centers on manufacturers with integrated material science and captive testing infrastructure. Acquisition targets should demonstrate CEA or GB/T 7253 pre-qualification status plus regional laboratory footprints. The signal to watch is consolidation velocity in China's State Grid tender frameworks, where multi-year agreements now capture 60-70% of volume and foreclose late entrant access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Supply | NGK Insulators leverages captive Guyanese and Chinese mining to sustain porcelain cost leadership against polymer volatility. |
| CEA Certification Laboratory Expansion | Bengaluru testing clusters reduce India's 18-24 month qualification backlog, securing first-mover advantage in 400 kV+ tenders. |
| Silicone Rubber Compounding Capacity | Siemens Energy's Nuremberg facilities enable tailored hydrophobicity profiles that shorten IEC 60383 qualification timelines. |
| SF6-Free Bushing Interface Development | Modular composite assemblies capture specification windows from EU F-Gas Regulation and vacuum interrupter transitions. |
| Embedded Sensor Integration | Fiber optic leakage current monitoring shifts revenue toward predictive maintenance contracts with State Grid and Southern Power Grid. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement officers, composite manufacturing engineers, CEA certification specialists, and transmission project developers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with grid operators in China, India, Germany, and the United States, alongside technical consultations with material scientists at silicone rubber compounding facilities and alumina processing plants. Secondary sources included IEC 60383 and IEEE C29.11 standard documentation, FERC Order 1000 compliance filings, EU F-Gas Regulation implementation guidance, and customs trade data tracking alumina and polymer feedstock flows. Bottom-up demand modeling triangulated against top-down infrastructure investment forecasts to reconcile segmentation outputs.
Variance decomposition across material technology, voltage class, and application type anchored the analytical framework, with composite versus porcelain substitution rates modeled separately for transmission corridors and substation installations. CAGRs derived from unit volume projections weighted by regional grid investment cycles and renewable interconnection mandates. Industry-specific forecast inputs incorporated CEA type-testing queue dynamics, GB/T 7253 revision implementation timelines, and offshore wind collector system specifications from China's coastal provinces.
Underlying assumptions cover sustained utility capital expenditure trajectories, stable alumina export quota regimes, and gradual SF6-free switchgear transition pace, with deviation risk concentrated in petrochemical price volatility and certification backlog compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Global EMC Filtration Market