
 Europe Malt Ingredient Market | 2026-2036
Europe Malt Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Malt Ingredient Market Foresight
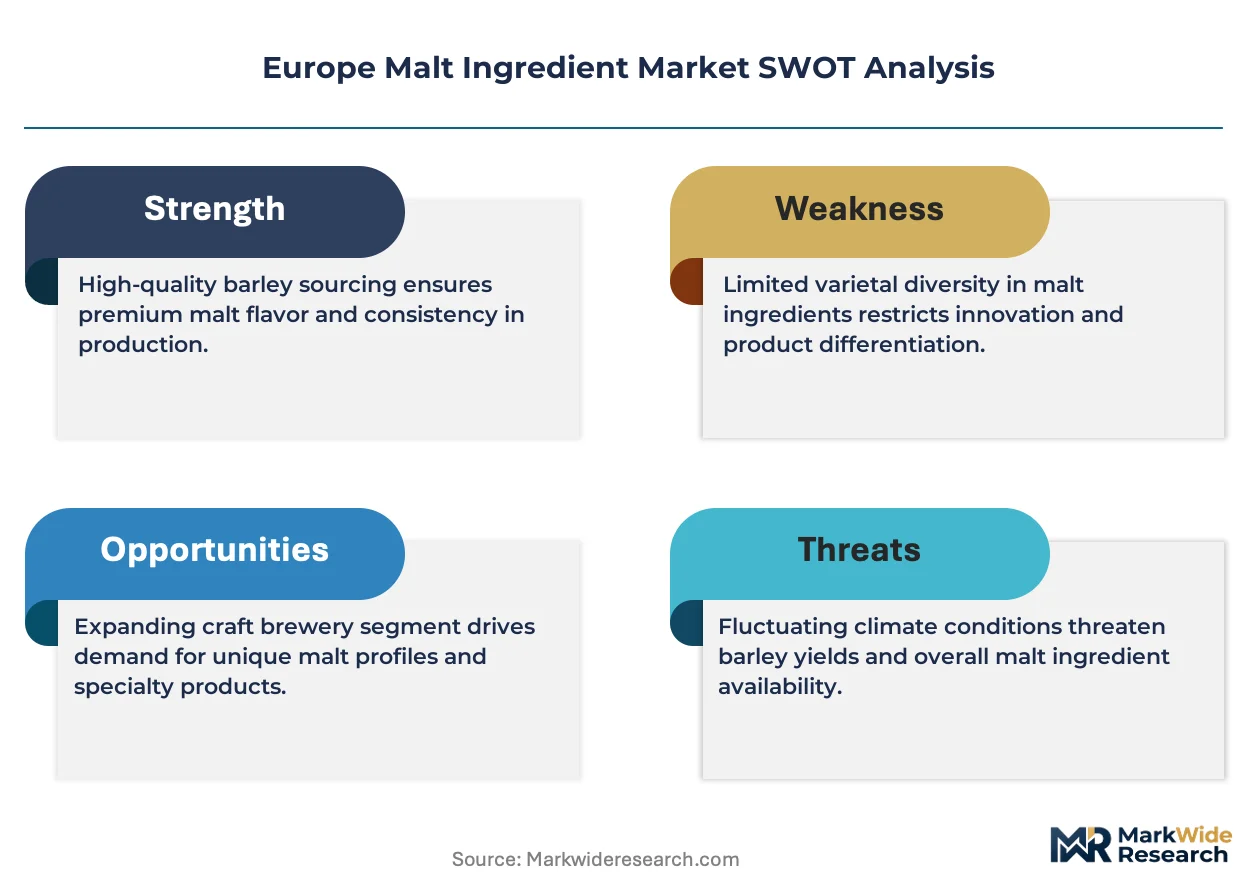
Craft distillers is collapsing the historical dominance of mass-market breweries as the fastest-growing buyer archetype across European malt procurement. Muntons plc anchors its position through deep vertical integration from barley breeding through malted finished goods. Simpsons Malt Limited differentiates via heritage roasting profiles targeting premium whisky producers in Scotland and Ireland. Malteries Soufflet competes on continental scale, leveraging French agronomic networks to secure consistent base grain supply.
Europe malt ingredients comprise germinated cereal grains—primarily barley—kilned to develop enzymatic diastatic power, color, and flavor precursors measured in degrees Lintner or EBC units, serving as the fermentable carbohydrate backbone for beer, spirits, and baked goods. Barley malt dominates volume flows due to established varietal breeding programs and brewhouse enzyme compatibility, while wheat malt captures premium positioning in Belgian-style and German wheat beer traditions. Powdered malt extracts concentrate margin pools through extended shelf stability and reduced logistics burden for industrial food processors.
EMA and EFSA frameworks govern enzyme activity claims and food-contact safety for malt-derived ingredients, while the EU Green Deal's carbon accounting rules reshape supplier qualification criteria across the value chain. REACH compliance and F-Gas Regulation standards affect kiln energy choices and refrigerant use in malt storage facilities. Stakeholders must monitor how the EU AI Act's impending traceability mandates intersect with batch-level provenance requirements already demanded by German purity law adherents and French AOC-aligned distillers.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing supplier qualification timelines across European malt procurement, forcing kilning operations to document carbon intensity per batch and accelerating backward integration into barley breeding programs.
Growth Catalysts
- Specialty Distilling Demand:Craft distillers in Scotland and Ireland are expanding roasted malt purchases for premium whisky production, creating new margin pools beyond traditional brewing contracts.
- REACH Compliance Infrastructure:Existing chemical safety documentation systems are enabling faster enzyme activity certifications for malt extract exporters targeting food processors.
- Heritage Brewing Clusters:Bavaria and Bohemia sustain premium consumption through Reinheitsgebot adherence and Czech Protected Geographical Indication frameworks.
Market Restraints
- Barley Supply Concentration:French and Danish agronomic networks control over sixty percent of malting-grade spring barley varietal development, creating germplasm access bottlenecks for smaller maltsters.
- Kiln Energy Cost Volatility:Natural gas price swings in Germany and Poland directly compress roasting margin structures, particularly for specialty caramel and chocolate malt profiles requiring extended heat cycles.
- Gluten-Free Substitution:Sorghum and rice-based brewing adjuncts are capturing share in mass-market lager segments where enzyme exogenous dosing is permitted.
Strategic Opportunities
- Polish Processing Expansion:Underdeveloped specialty malt capacity in Greater Poland Voivodeship offers greenfield sites with proximity to Baltic port logistics and EU structural fund eligibility.
- CSRD-Aligned Carbon Labeling:The Corporate Sustainability Reporting Directive is creating first-mover advantage for maltsters offering batch-level Scope 3 disclosures to brewery sustainability officers.
- Extract-Plus-Enzyme Bundles:Convergence of powdered malt extracts with tailored diastatic enzyme formulations is opening industrial bakery and plant-based dairy applications.
Industry Challenges
- Malting Technologist Scarcity:European brewing science programs are graduating fewer kiln operators and germination floor managers than replacement demand requires.
- F-Gas Refrigerant Retrofit:Existing malt storage facilities face compressed timelines to replace hydrofluorocarbon cooling systems under EU phase-down schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Malt Ingredient Market |
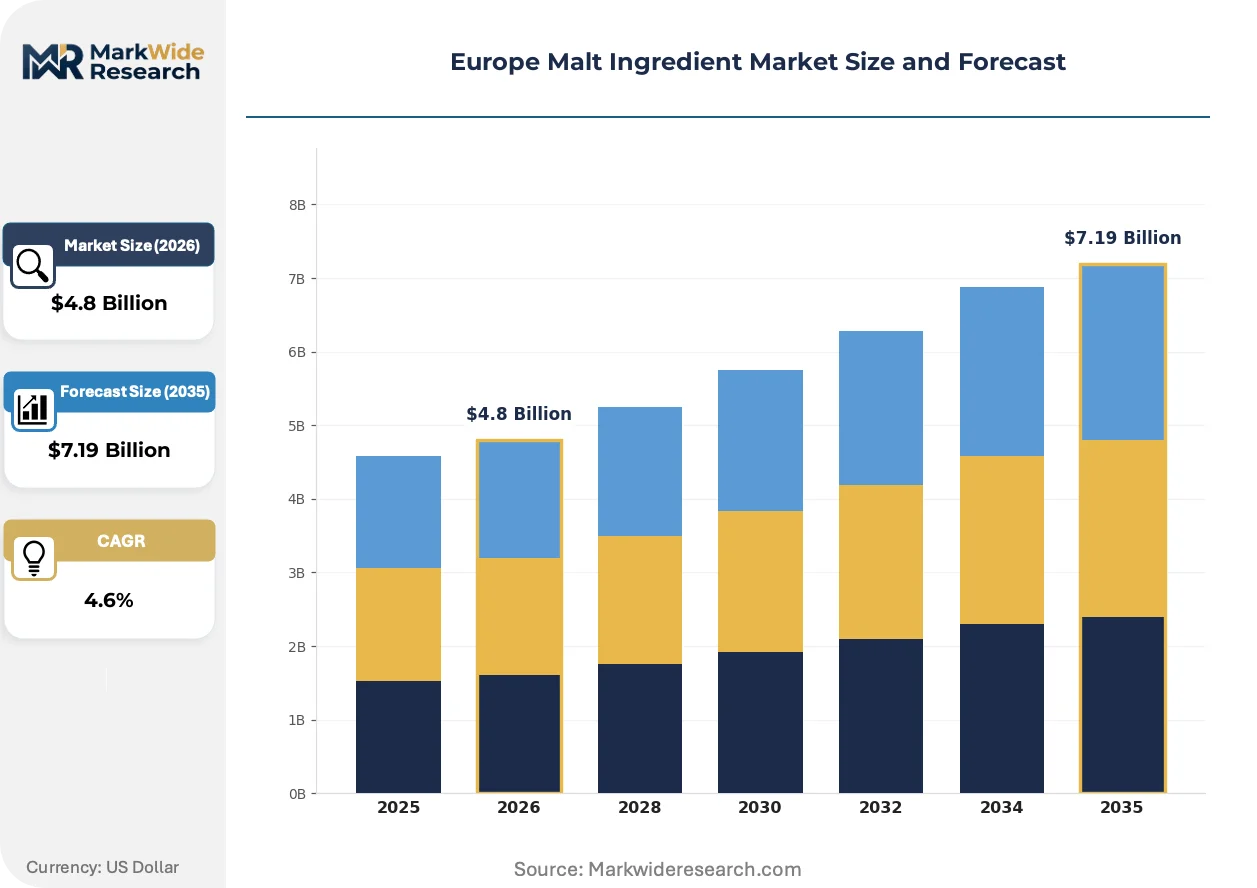
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barley Malt, Wheat Malt, Rye Malt, Oats Malt Application: Brewing, Distilling, Baking, Confectionery End User: Beverage Manufacturers, Food Processors, Breweries, Craft Distillers Form: Flaked, Powdered, Liquid, Whole Grain |
| Companies Covered | Cargill Incorporated, Muntons plc, Malteries Soufflet, Simpsons Malt Limited, Viking Malt, Boortmalt, IREKS GmbH, Briess Malt & Ingredients Co., Malteurop, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Malt Ingredient Market Shifts & Advancements
Automation and sustainability mandates are reshaping how European maltsters configure kilning operations, with digital process control and carbon accounting now inseparable from competitive positioning.
Precision kilning control systems using real-time moisture sensors and adaptive airflow algorithms are fragmenting the traditional craft-versus-industrial divide in roasting capabilities. Mid-size maltsters in Belgium and the Netherlands are deploying these systems to replicate heritage flavor profiles at scale, compressing the premium that artisan floor-malting operations previously commanded.
The EU AI Act's traceability requirements are intersecting with German purity law batch documentation standards, forcing maltsters to restructure data architectures before enforcement deadlines. Kilning operations must now maintain immutable provenance records linking barley field coordinates to final Lovibond color specifications, with French AOC-aligned distillers and Bavarian monastery breweries already demanding this granularity in supplier audits.
Direct contracting between distillers and heritage barley cooperatives is displacing spot-market grain purchasing in Scotland and Ireland. Whisky producers are securing multi-year supply agreements with specific Scottish Borders and Irish tillage farms, bypassing traditional merchant intermediaries and capturing terroir marketing claims that command shelf price premiums in export markets.
Europe Malt Ingredient Market Segmentation
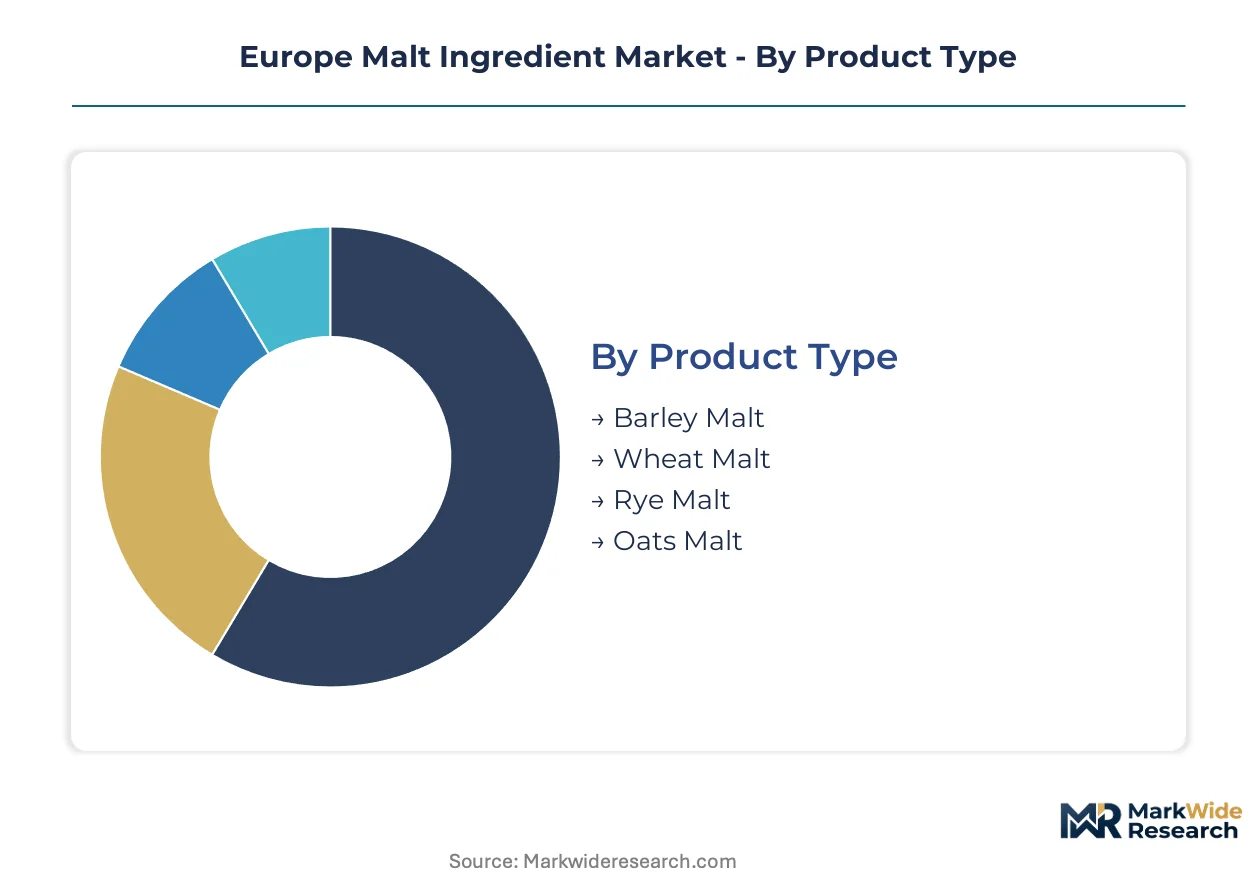
Malt ingredient procurement flows through distinct channel configurations depending on grain type and processing form. Understanding these segment boundaries clarifies where margin pools concentrate and which supplier capabilities determine contract awards.
Product Type:
Channel mix varies sharply by cereal base, with barley commanding dedicated malting infrastructure while wheat and alternative grains share modified brewhouse equipment.
- Barley Malt:Germinated and kilned two-row or six-row barley delivering standardized diastatic power measured in degrees Lintner. Demand concentrates in Bavarian monastery breweries and Bohemian Protected Geographical Indication zones where Reinheitsgebot compliance mandates enzymatic self-sufficiency. Kiln energy costs in Germany and Poland compress roasting margins for specialty caramel profiles.
- Wheat Malt:Lower-modified germination preserving protein structures essential for Belgian witbier and German Weissbier foam stability. Expansion concentrates among craft distillers in Scotland and Ireland seeking roasted wheat variants for premium whisky mash bills. French agronomic networks supply consistent spring wheat varietals through backward integration contracts.
- Rye Malt:Spicy phenolic flavor precursor for traditional Roggenbier and Scandinavian farmhouse ales. Polish and Danish maltsters capture rye volumes through Baltic port logistics advantages.
- Oats Malt:Beta-glucan-rich body enhancer for New England-style IPAs and oatmeal stouts. UK specialty maltsters supply oats to London and Manchester craft brewing clusters.
Barley Malt dominates installed base. Wheat Malt is where expansion concentrates.
Application:
Cost tier stratification separates commodity base malt flows from premium roasted specialties commanding three-to-five-fold price multiples.
- Brewing:Standard and specialty malts supplying enzymatic conversion and color specification for lager, ale, and hybrid beer styles. Volume concentrates in industrial-scale Pilsner production across Germany and the Czech Republic.
- Distilling:High-extract pale malts and roasted specialties for whisky, gin, and craft spirit mash bills. Scottish and Irish distillers drive roasted malt demand through direct farm contracting for terroir marketing claims.
- Baking:Diastatic and non-diastatic malt extracts for crust color, fermentation vigor, and shelf-life extension in artisan and industrial bread production.
- Confectionery:Malted milk powders and syrup infusions for chocolate coatings and traditional sweet formulations.
Brewing captures volume concentration. Distilling generates steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with beverage manufacturers demanding batch-level carbon accounting that food processors rarely require.
- Beverage Manufacturers:Integrated brewing and distilling groups with centralized procurement functions. These buyers enforce EU Green Deal Farm to Fork traceability mandates through supplier scorecards.
- Food Processors:Industrial bakeries and confectionery groups purchasing standardized malt extracts through distributor networks with limited provenance documentation.
- Breweries:Independent brewing operations spanning mass-market lager producers to regional ale specialists. Bavarian and Bohemian heritage breweries sustain premium malt consumption through Reinheitsgebot adherence.
- Craft Distillers:Small-batch whisky and spirit producers in Scotland, Ireland, and emerging Polish clusters. These buyers displace spot-market grain purchasing with multi-year heritage barley cooperative contracts.
Beverage Manufacturers dominate procurement volume. Craft Distillers are gaining share fastest.
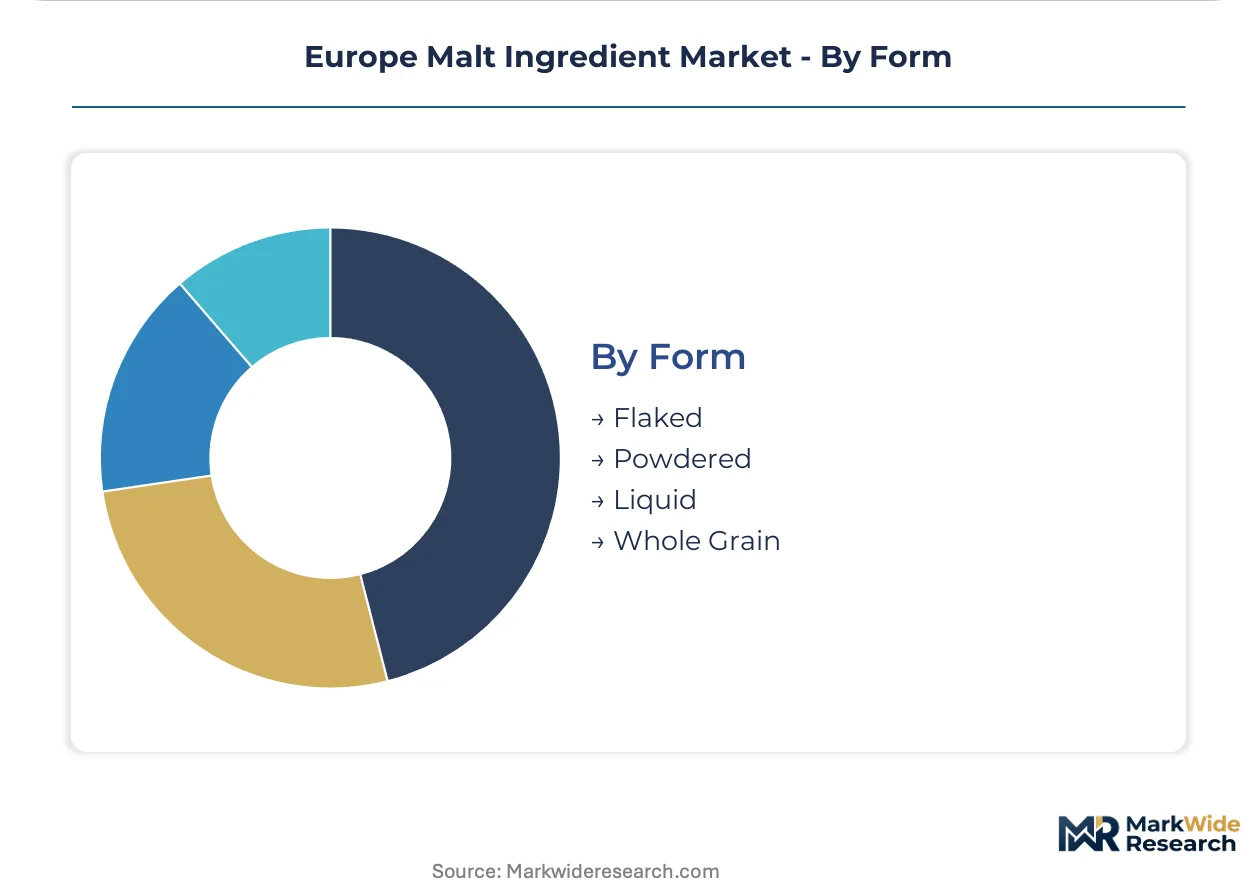
Form:
Supply concentration in kilning and extract processing infrastructure shapes regional availability of each physical format.
- Flaked:Pre-gelatinized unmalted or malted cereal flakes for direct mashing without separate cereal cookers. UK and Belgian maltsters lead flaked wheat and oat supply to craft brewing clusters.
- Powdered:Spray-dried malt extracts with extended shelf stability and reduced logistics burden for industrial food processors. Muntons plc anchors capacity through captive drying operations.
- Liquid:Concentrated malt syrups for beverage and bakery applications requiring precise fermentable sugar dosing. Netherlands-based processors serve Central European industrial bakeries.
- Whole Grain:Intact malted kernels for traditional floor-malted heritage brewing and distilling applications. Scottish Borders and Irish tillage farms supply whole grain through direct distiller contracts.
Whole Grain dominates heritage installed base. Powdered is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malting-grade barley breeding programs cluster in France and Denmark, concentrating germplasm access for continental maltsters. German and Polish kiln operations face acute energy cost pressures from natural gas price volatility. Scottish and Irish distillers are pioneering direct farm contracting models that bypass traditional grain merchants.
Germany
Bavarian monastery breweries sustain premium malt consumption through Reinheitsgebot adherence, requiring enzymatic self-sufficiency in base malts. The EU Green Deal's Farm to Fork Strategy is forcing kilning operations in Munich and Bamberg to document carbon intensity per batch. Cologne and Düsseldorf brewing clusters are retrofitting facilities under F-Gas Regulation phase-down schedules for hydrofluorocarbon cooling systems.
United Kingdom
Scottish whisky distillers are displacing spot-market grain purchasing with multi-year heritage barley cooperative contracts in the Scottish Borders. EMA and EFSA frameworks govern enzyme activity claims for malt extract exports targeting food processors. London and Manchester craft brewing clusters drive demand for flaked wheat and oat specialties from UK specialty maltsters.
France
French agronomic networks supply consistent spring wheat varietals through backward integration contracts with Malteries Soufflet. The EU AI Act's impending traceability mandates are intersecting with French AOC-aligned distiller requirements for batch-level provenance documentation. Alsace and Nord-Pas-de-Calais malting facilities leverage continental scale to secure base grain supply across European beverage manufacturers.
Poland
Greater Poland Voivodeship offers greenfield specialty malt capacity with proximity to Baltic port logistics and EU structural fund eligibility. REACH compliance infrastructure enables faster enzyme activity certifications for malt extract exporters. Polish and Danish maltsters capture rye volumes through Baltic port logistics advantages for Scandinavian farmhouse ale producers.
Ireland
Irish tillage farms are securing direct multi-year supply agreements with whisky producers seeking terroir marketing claims for export premiums. The Corporate Sustainability Reporting Directive is creating first-mover advantage for maltsters offering batch-level Scope 3 disclosures to distillery sustainability officers. Cork and Dublin distilling clusters are expanding roasted malt purchases for premium spirit mash bills.
Europe Malt Ingredient Market Competitive Landscape
Concentration sits with vertically integrated agronomy-to-malt processors and heritage roasting specialists serving premium whisky producers. Three structural tiers have emerged: continental-scale operators with captive barley breeding programs, mid-size regional maltsters deploying precision kilning automation, and specialty floor-malting artisans. Competitive moves center on backward integration into varietal development and CSRD-aligned carbon accounting infrastructure for brewery supplier scorecards.
Within the vertically integrated tier, Muntons plc anchors capacity through captive drying operations for powdered malt extracts. Malteries Soufflet exemplifies continental-scale positioning through French agronomic network control. Simpsons Malt Limited occupies the heritage roasting specialist position targeting premium whisky producers in Scotland and Ireland.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Muntons plc |
| Malteries Soufflet |
| Simpsons Malt Limited |
| Viking Malt |
| Boortmalt |
| IREKS GmbH |
| Briess Malt & Ingredients Co. |
| Malteurop |
| Others |
Supply & Pricing Matrix
Specialty roasted malt substitution for commodity base malt is compressing pricing premiums in Bavaria while extending supply lead times from Scottish Borders heritage farms. This input swap simultaneously concentrates procurement power among craft distillers and fragments legacy brewery supplier relationships across German and Czech malting clusters.
Pricing Analysis
Volume-discount tiering structures separate heritage floor-malted whole grain from industrial-scale powdered extracts. Three-tier pricing stratification across premium, standard, and economy levels reflects diastatic power certification, Reinheitsgebot compliance grade, and batch carbon intensity disclosure. Pricing pressure stems from natural gas cost volatility in German and Polish kiln operations. Mass-market lager producers exhibit highest price sensitivity; Scottish whisky distillers accept premium multiples for terroir-documented provenance.
Supply Chain Analysis
Inventory lead times for specialty caramel and chocolate profiles have extended due to extended heat cycle requirements and energy rationing contingencies. Geographic supply concentrates in France, Denmark, and Germany through malting-grade barley breeding program control. Raw material dependencies rest on spring barley varietals, natural gas for kilning, and diastatic enzyme formulations. Single-source vulnerability sits with French and Danish germplasm networks controlling varietal development. Distribution runs through direct contracting between distillers and heritage barley cooperatives displacing traditional grain merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft distiller consolidation in Scotland and Ireland is shifting buyer power toward small-batch producers capable of multi-year supply commitments, fragmenting the historical dominance of mass-market brewery procurement.
For Market Incumbents: Secure backward integration into barley breeding programs to bypass French and Danish germplasm bottlenecks. Anchor carbon accounting infrastructure to meet CSRD-aligned batch disclosure demands from beverage manufacturer supplier scorecards. Defensive positioning requires F-Gas Regulation compliance retrofit timelines and precision kilning automation deployment. For New Entrants and Emerging Players: Differentiate on CSRD-compliant Scope 3 traceability as Polish specialty malt capacity expands with EU structural fund eligibility. White-space concentration sits in Greater Poland Voivodeship greenfield sites and extract-plus-enzyme bundles for industrial bakery applications. Go-to-market leverage rests on Baltic port logistics proximity and direct distiller contracting models. For Investors and Strategic Acquirers: The market sits at a sustainability-mandate acceleration phase that favors vertically integrated agronomy-to-malt processors with captive breeding programs. Long-term viability over the coming decade hinges on carbon accounting infrastructure and heritage roasting capability. Acquisition target archetype: mid-size regional maltsters deploying precision kilning automation. Signal to watch: EU AI Act traceability enforcement deadlines intersecting with German purity law documentation standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Breeding | Muntons plc and Malteries Soufflet secure germplasm access independent of French and Danish networks. |
| CSRD-Aligned Carbon Labeling Infrastructure | Batch-level Scope 3 disclosures create first-mover advantage with brewery sustainability officers under EU Green Deal mandates. |
| Precision Kilning Automation Deployment | Belgian and Dutch mid-size maltsters replicate heritage flavor profiles at scale, compressing artisan floor-malting premiums. |
| Direct Farm Contracting Models | Scottish and Irish distillers bypass traditional grain merchants, capturing terroir marketing claims for export shelf price positioning. |
| F-Gas Refrigerant Retrofit Compliance | German and Czech storage facilities replace hydrofluorocarbon cooling systems under EU phase-down schedules. |
Research Methodology
A standing panel of malting technologists, brewery procurement directors, distiller supply chain managers, and kiln operations supervisors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from EMA enzyme activity filings, EU Green Deal Farm to Fork Strategy documentation, REACH compliance registries, and customs trade data for malting-grade barley flows. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Consistency checks validated projections against external benchmarks including malt extract export certifications, F-Gas Regulation facility retrofit disclosures, and CSRD implementation timelines. The analytical framework modeled product type, application, end user, and form dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories and price evolution assumptions, incorporating kiln energy cost volatility, specialty distilling demand curves, and heritage brewing cluster consumption patterns.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement schedules or natural gas price stabilization would require recalibration. Forecasts reflect documented assumptions regarding carbon accounting infrastructure deployment and craft distiller procurement consolidation. Specific risks that could revise projections include accelerated EU AI Act traceability mandates, germplasm network disruption, or gluten-free substitution acceleration in mass-market segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Vegetable Oils Market
Ingredients
South America Vegetable Oil Market
Ingredients
Agar Market
Ingredients
Egg Albumin Protein Market
Ingredients
USA Yeast Extracts Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Asia-Pacific Bakery Ingredients Market
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Cocoa Market
Ingredients
Wheat Gluten Market
Ingredients
Chewing Gum Base Market
Ingredients
Baking Ingredients Market
Ingredients
Pea Starch Market
Ingredients
Pine Needle Oil Market
Ingredients
Clean Label Flour Market