
 Medium-Chain Triglycerides Market | 2026-2036
Medium-Chain Triglycerides Market Size, Share, and Industry Trends Forecast 2026-2036
Medium-Chain Triglycerides Market Intelligence
Direct-to-consumer e-commerce channels is reconfiguring how medium-chain triglycerides reach end buyers, bypassing traditional ingredient distributors. BASF SE leverages its global oleochemicals network to sustain supply security across multiple continents. Croda International Plc anchors its position through lipid technology leadership in pharmaceutical-grade MCTs. Koninklijke DSM N.V. competes by integrating nutritional science expertise with precision fermentation capabilities.
Medium-chain triglycerides are fatty acids composed of 6–12 carbon chains, typically derived from coconut or palm kernel oil through fractionation and esterification processes; they metabolize rapidly into ketone bodies, making them valuable for energy-dense clinical and sports applications. The liquid product type dominates bulk ingredient procurement due to lower processing costs and broader formulation compatibility. Nutraceutical formulations within the dietary supplements end-user category are expanding fastest as consumers seek ketogenic and cognitive performance benefits. Pharmaceutical applications occupy higher-margin positions where USP-grade certification and GMP compliance create entry barriers.
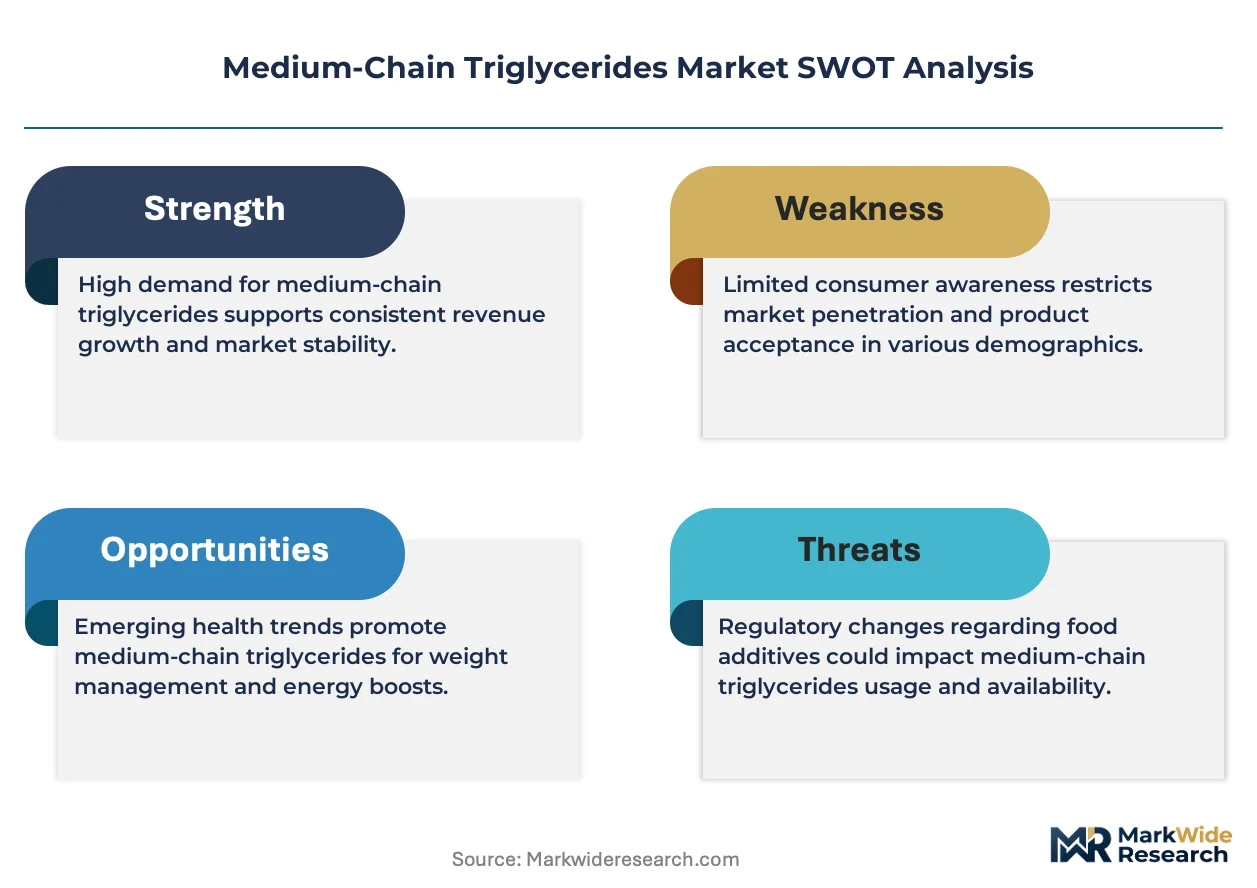
The FDA oversees structure-function claim substantiation for MCT dietary supplements, while the EPA regulates environmental impacts of palm-derived feedstock sourcing; EFSA in Europe enforces novel food authorization pathways that delay new MCT product introductions. These frameworks compel manufacturers to maintain dual regulatory dossiers and traceable supply chains. Stakeholders must monitor evolving ketogenic health claim jurisprudence and sustainable sourcing mandates to anticipate which product-positioning strategies will retain market access.
Market Dynamics
The FDA's intensifying scrutiny of structure-function claims for ketogenic supplements is forcing manufacturers to rebuild substantiation dossiers, reshaping how MCT products are positioned and distributed across dietary supplement channels.
Growth Catalysts
- Ketogenic diet proliferation:Clinical nutrition providers and sports nutrition brands are expanding MCT procurement for energy-dense formulations targeting metabolic therapy and athletic performance.
- REACH-compliant fractionation advances:European oleochemical refiners are scaling pharmaceutical-grade MCT output to serve EMA-authorized drug delivery applications.
- Palm kernel supply diversification:Southeast Asian feedstock processors are building redundant sourcing networks to reduce concentration risk in Malaysian and Indonesian production clusters.
Market Restraints
- Crude coconut oil volatility:Weather-driven harvest fluctuations in the Philippines and Sri Lanka compress margins for fractionation-dependent producers.
- EFSA novel food authorization delays:European entrants face 18-24 month assessment timelines for innovative MCT delivery formats, freezing product pipeline velocity.
- Long-chain triglyceride substitution:Cost-sensitive food manufacturers in emerging markets revert to conventional vegetable oils when MCT premiums exceed formulation budgets.
Strategic Opportunities
- Pediatric epilepsy protocols:Neurology departments in Germany and the Netherlands are integrating MCT-based ketogenic therapies into standard-of-care guidelines for drug-resistant seizure management.
- Precision fermentation integration:Biotech platforms combining microbial lipid synthesis with downstream esterification promise C8-C10 chain specificity without agricultural feedstock exposure.
- Direct-to-consumer subscription models:Functional beverage brands are bypassing ingredient distributors through owned e-commerce channels, capturing margin and consumption data.
Industry Challenges
- USP-grade certification timelines:Pharmaceutical customers demand 12-18 month validation cycles for GMP-compliant MCT excipients, straining working capital.
- Lipid technology talent scarcity:Fractionation process engineers and regulatory toxicologists command premium compensation, constraining R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium-Chain Triglycerides Market |
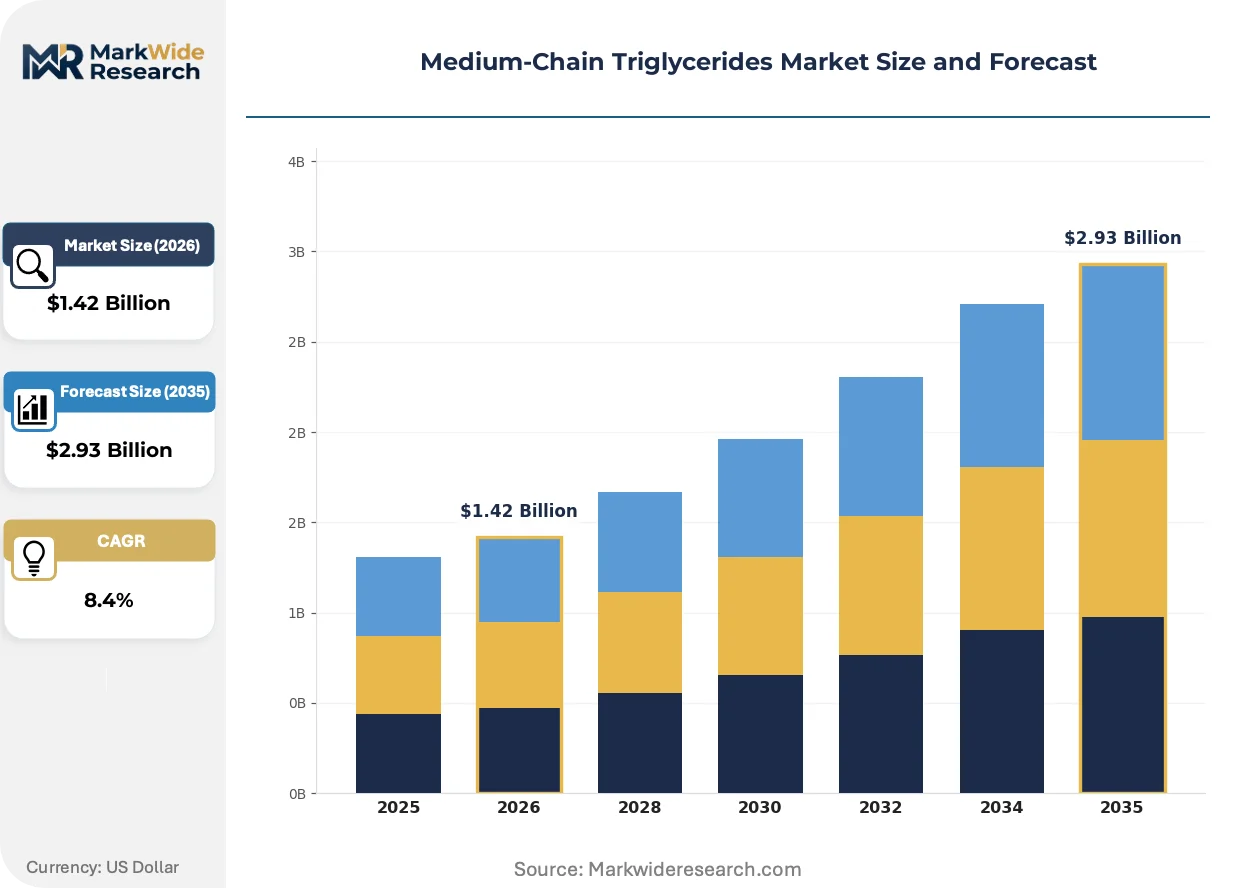
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Emulsion Application: Nutrition, Pharmaceuticals, Cosmetics, Animal Feed End User: Food & Beverage Industry, Dietary Supplements, Personal Care, Clinical Nutrition Formulation: Bulk Ingredients, Functional Foods, Ready-to-Drink, Nutraceuticals |
| Companies Covered | BASF SE, Croda International Plc, Koninklijke DSM N.V., Wilmar International Limited, Stepan Company, Lonza Group Ltd., Musim Mas Holdings, IOI Oleo GmbH, P&G Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium-Chain Triglycerides Market Strategic Shifts & Innovations
Formulation science and claim substantiation requirements are converging to redefine competitive advantage, with technology migration and regulatory adaptation separating viable participants from marginal operators.
Enzymatic interesterification is migrating from batch processing to continuous flow systems, enabling real-time carbon chain tailoring. Pharmaceutical contract manufacturers in Switzerland and Singapore are adopting these platforms to reduce solvent use and improve C8-C10 selectivity. The shift is compressing capital recovery timelines while raising barriers for legacy chemical esterification assets.
EFSA's evolving position on ketone body health claims is compelling European brands to narrow promotional language or pursue drug-device pathways. Sports nutrition marketers are retreating from cognitive performance assertions toward energy metabolism framing. The regulatory recalibration is diverting R&D investment from claim innovation toward delivery technology.
Hospital procurement departments are consolidating MCT sourcing through group purchasing organizations, displacing decentralized pharmacy buying. Acute care networks in Texas and Florida are mandating single-supplier contracts for clinical nutrition lipids. The concentration is squeezing regional distributors and favoring manufacturers with USP certification and national logistics infrastructure.
Medium-Chain Triglycerides Market Segmentation
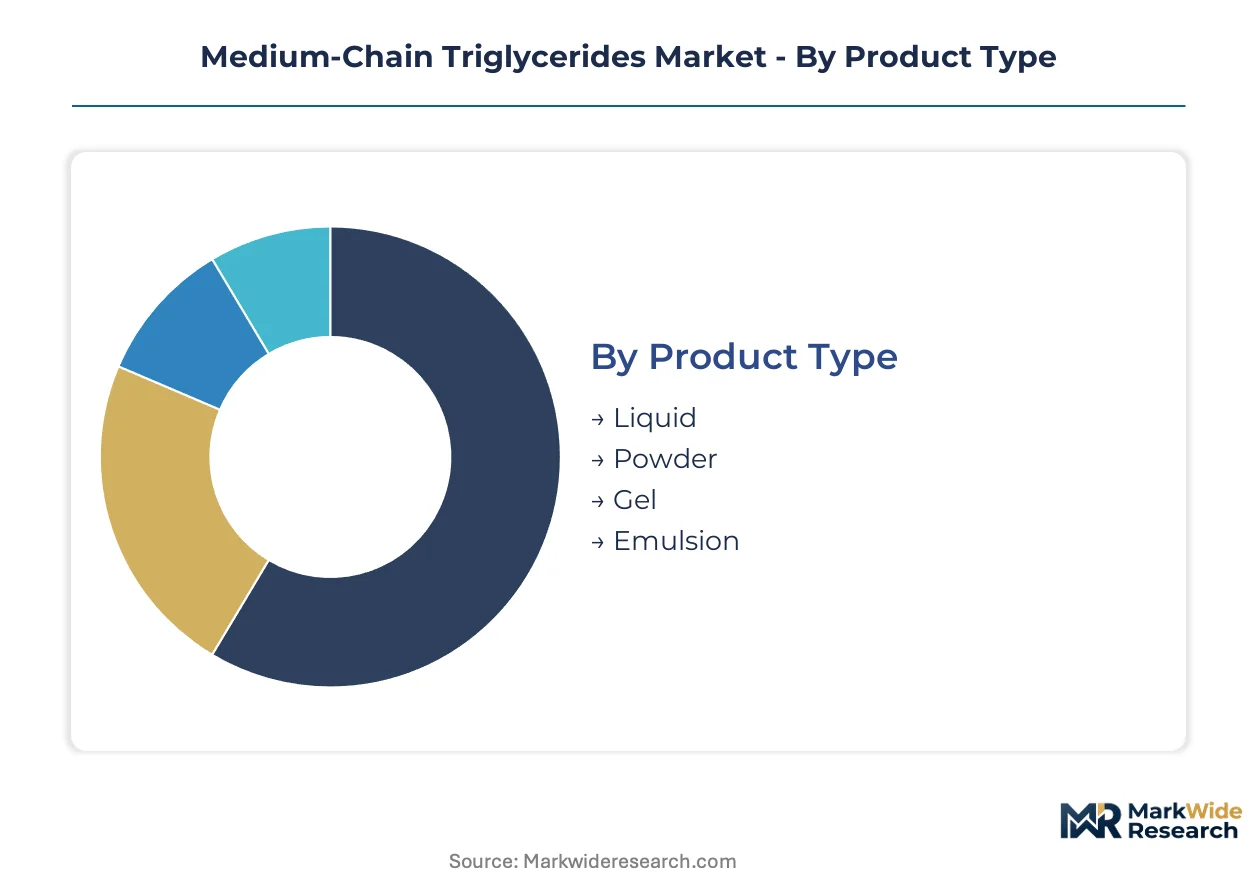
MCT segmentation reveals how formulation flexibility and regulatory pathways split commercial opportunity across divergent margin structures. Product format and end-use certification requirements determine which manufacturers can access pharmaceutical versus commodity pricing tiers.
Product Type:
The use-case spectrum spans from high-volume food manufacturing to precision-dosed clinical applications, with physical state dictating processing compatibility and stability profiles.
- Liquid:Dominates bulk procurement due to lower fractionation costs and seamless integration into beverage and oil-based formulations. Demand concentrates among United States ketogenic diet consumers and sports nutrition brands seeking rapid ketone body conversion for metabolic therapy protocols.
- Powder:Spray-dried or microencapsulated formats enable shelf-stable incorporation into dry mixes and capsule supplements. European dietary supplement manufacturers favor powder for EFSA-compliant novel food applications where precise dosing and flowability reduce formulation variability.
- Gel:Semi-solid matrices serve pediatric epilepsy protocols and dysphagia-friendly clinical nutrition where swallowing safety matters.
- Emulsion:Water-dispersible systems support parenteral nutrition and cosmetic formulations requiring homogenous lipid distribution.
The dominant share belongs to Liquid, while Powder is closing the gap fastest.
Application:
Margin concentration follows certification intensity, with pharmaceutical-grade production commanding price multiples over commodity nutrition uses.
- Nutrition:Energy-dense formulations for ketogenic diets and athletic performance drive volume procurement from coconut and palm kernel feedstocks. Sports nutrition brands in Germany and the Netherlands accelerate ready-to-drink adoption for metabolic therapy segments.
- Pharmaceuticals:USP-grade MCTs serve as drug delivery vehicles and excipients in parenteral emulsions, with GMP compliance creating supply scarcity. Swiss and Singaporean contract manufacturers adopt continuous flow enzymatic interesterification to improve C8-C10 chain specificity for EMA-authorized applications.
- Cosmetics:Lightweight emollients and carrier oils for active ingredients penetrate premium skincare formulations.
- Animal Feed:Energy supplementation for livestock and aquaculture operates at thinner margins sensitive to crude coconut oil volatility.
Pharmaceuticals capture the highest margin per kilogram, though Nutrition generates the largest absolute volume.
End User:
Procurement patterns diverge between centralized hospital purchasing and fragmented direct-to-consumer channels, reshaping distribution economics.
- Food & Beverage Industry:Functional beverage manufacturers integrate MCTs for ketogenic positioning, with Texas and Florida acute care networks consolidating sourcing through group purchasing organizations.
- Dietary Supplements:Direct-to-consumer e-commerce channels bypass traditional ingredient distributors, enabling subscription models that capture consumption data and margin.
- Personal Care:Cosmetic formulators prioritize oxidative stability and skin-feel characteristics over ketogenic functionality.
- Clinical Nutrition:Hospital procurement departments mandate USP certification and national logistics infrastructure, squeezing regional distributors.
Dietary Supplements is expanding most quickly through channel disintermediation, while Clinical Nutrition maintains the stickiest supplier relationships.
Formulation:
Processing depth determines value capture, with finished goods manufacturers retaining margin that fractionation-only suppliers forfeit.
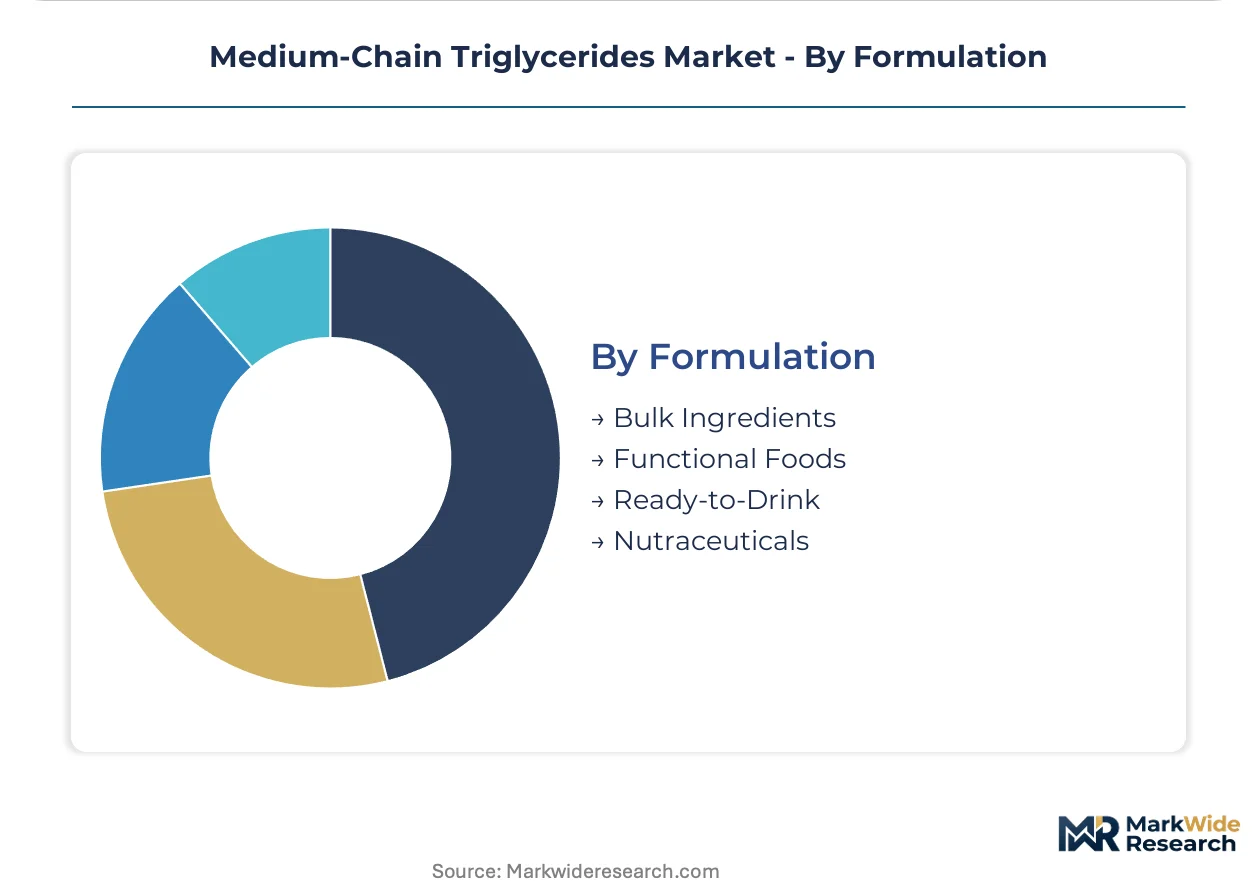
- Bulk Ingredients:Unformulated MCT oils supply downstream processors, with Malaysian and Indonesian feedstock processors building redundant sourcing networks to reduce concentration risk.
- Functional Foods:MCT-infused bars, spreads, and baked goods target ketogenic consumers seeking convenience formats beyond oils.
- Ready-to-Drink:Pre-mixed beverages command shelf space in sports nutrition and metabolic therapy segments, with FDA structure-function claim scrutiny forcing substantiation dossier rebuilds.
- Nutraceuticals:Softgel capsules and soft chews combine MCTs with complementary actives for cognitive and energy positioning, retreating from cognitive performance assertions toward energy metabolism framing under EFSA pressure.
Bulk Ingredients holds the volume base, yet Ready-to-Drink exhibits the steepest expansion trajectory as formulation science migrates to finished goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States runs 15-20% above German pharmaceutical-grade benchmarks, while Malaysian feedstock processors absorb volatility that compresses margins for European fractionators dependent on imported coconut and palm kernel oils.
United States
Ketogenic diet consumers and sports nutrition brands in Texas and Florida drive procurement concentration through group purchasing organizations. FDA structure-function claim scrutiny forces manufacturers to rebuild substantiation dossiers for dietary supplement channels. Houston and Miami acute care networks mandate single-supplier contracts for clinical nutrition lipids.
Germany
Neurology departments in Berlin and Munich integrate MCT-based ketogenic therapies into standard-of-care guidelines for drug-resistant pediatric epilepsy. EFSA novel food authorization delays freeze 18-24 month assessment timelines for innovative delivery formats. The Rhine-Ruhr industrial corridor hosts pharmaceutical contract manufacturers scaling EMA-authorized drug delivery applications.
Malaysia
Feedstock processors build redundant sourcing networks across Sabah and Sarawak to reduce concentration risk in Indonesian production clusters. The country's national palm oil regulator enforces sustainable sourcing mandates that trace supply chains to plantation level. Port Klang fractionation facilities supply bulk liquid MCTs to United States and European nutraceutical formulators.
Switzerland
Swissmedic certification requirements attract pharmaceutical-grade MCT production for parenteral nutrition and drug delivery vehicles. Continuous flow enzymatic interesterification platforms in Basel and Geneva improve C8-C10 chain selectivity. The country's precision fermentation ecosystem partners with lipid technology providers to develop microbial lipid synthesis pathways.
Singapore
Contract manufacturers serve as Asia-Pacific distribution hubs for USP-grade MCT excipients targeting hospital procurement departments. The city-state's national pharmaceutical regulator aligns GMP compliance frameworks with FDA and EMA standards. Jurong Island oleochemical refiners adopt enzymatic processing to reduce solvent use in pharmaceutical applications.
Medium-Chain Triglycerides Market Key Industry Players
Oleochemical majors and pharmaceutical-grade specialists split the market between volume-driven feedstock security and certification-intensive premium positioning. The vendor base concentrates around integrated palm oil processors and European lipid technology providers with USP-grade capabilities. Three archetypes dominate: integrated feedstock-to-fractionation operators, pharmaceutical-grade certification holders, and precision fermentation entrants. Capacity expansion in Southeast Asian fractionation assets and strategic partnerships between biotech platforms and downstream formulators represent the dominant competitive moves.
Among European-based chemical conglomerates, BASF SE and Croda International Plc occupy positions that exemplify the integrated and pharmaceutical-grade archetypes respectively. BASF SE leverages global oleochemicals networks to sustain supply security across multiple continents. Croda International Plc anchors its position through lipid technology leadership in pharmaceutical-grade MCTs. Koninklijke DSM N.V. represents the nutritional science integration archetype, combining precision fermentation capabilities with downstream formulation expertise.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Koninklijke DSM N.V. |
| Wilmar International Limited |
| Stepan Company |
| Lonza Group Ltd. |
| Musim Mas Holdings |
| IOI Oleo GmbH |
| P&G Chemicals |
| Others |
Cost & Logistics Intelligence
Malaysian and Indonesian palm kernel oil concentration anchors margin distribution across the MCT value chain, with upstream feedstock processors capturing working capital advantages that downstream fractionators forfeit during crude coconut oil volatility spikes. Pricing power pools with pharmaceutical-grade certification holders serving USP-compliant clinical nutrition contracts, while commodity liquid MCT suppliers compete on volume scale and logistics reach.
Pricing Analysis
The customization-premium spread between standard bulk liquid MCTs and pharmaceutical-grade excipients runs widest in clinical nutrition channels. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified GMP production from food-grade fractionation and animal feed applications. Cost compression in standard-grade liquid MCTs is intensifying because sports nutrition brands consolidate procurement through direct-to-consumer subscription models. Food and beverage manufacturers exhibit highest price sensitivity, while hospital procurement departments in Texas and Florida acute care networks accept premium positioning for validated supply security.
Supply Chain Analysis
Extended payment terms from Southeast Asian feedstock processors to European fractionators are compressing working capital cycles across the value chain. Supply concentrates in Malaysia, Indonesia, and the Philippines, with coconut and palm kernel oil feedstocks drawing from plantation networks subject to weather-driven harvest fluctuations. Single-source vulnerability runs through Port Klang fractionation corridors serving United States nutraceutical formulators. Distribution runs through integrated oleochemical majors with captive plantation supply and global logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by EFSA novel food authorization delays that froze European product pipeline velocity. The recovery trajectory hinges on ketogenic diet proliferation and pharmaceutical-grade capacity expansion.
For Market Incumbents: Insulate margin position by deepening captive supply of Malaysian and Indonesian palm kernel feedstocks through backward integration into plantation assets. BASF SE and Croda International Plc demonstrate how lipid technology leadership in pharmaceutical-grade MCTs creates switching costs that defend against precision fermentation entrants. Prioritize USP-grade certification investment to retain hospital procurement contracts.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer dietary supplement channels where FDA structure-function claim scrutiny has displaced incumbent positioning. Pediatric epilepsy protocols in Germany and the Netherlands offer the most penetrable clinical entry point. Pursue precision fermentation partnerships to bypass agricultural feedstock exposure and accelerate EMA-authorized drug delivery applications.
For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-grade certification holders with USP-compliant GMP infrastructure and national logistics reach. The five-to-ten year viability window favors manufacturers integrating enzymatic interesterification platforms for C8-C10 chain specificity. Watch for inflection when EFSA ketone body health claim jurisprudence stabilizes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive palm kernel supply insulates Malaysian processors from Indonesian production cluster disruptions. |
| Pharmaceutical-Grade Certification Investment | USP-grade GMP compliance secures hospital procurement contracts in Texas and Florida acute care networks. |
| Precision Fermentation Partnership | Microbial lipid synthesis platforms promise C8-C10 specificity without coconut oil harvest volatility exposure. |
| Direct-to-Consumer Channel Launch | Owned e-commerce subscriptions capture margin and consumption data from ketogenic diet consumers. |
| Continuous Flow Enzymatic Processing | Real-time carbon chain tailoring reduces solvent use for Swissmedic-certified parenteral nutrition applications. |
Research Approach
A standing panel of oleochemical plant managers, pharmaceutical procurement leads at hospital group purchasing organizations, sports nutrition brand formulators, and regulatory affairs directors provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA structure-function claim filings, EFSA novel food authorization registers, Malaysian Palm Oil Board sustainability traceability databases, and SEC 10-K disclosures from integrated feedstock processors. Bottom-up volume triangulation against top-down value estimates anchored segmentation-level outputs.
Scenario-bracketing around ketogenic diet adoption curves and pharmaceutical-grade capacity buildouts framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, application grade tier, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and feedstock cost pass-through assumptions. Industry-specific inputs incorporated EMA authorization timelines and crude coconut oil harvest variance bands.
Sensitivities concentrate around EFSA novel food jurisprudence evolution and sustainable sourcing mandate enforcement intensity. Forecasts reflect documented assumptions on ketogenic therapy protocol adoption and fractionation technology migration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
US Nutraceuticals Market