
 Nuclear Bomb Market | 2026-2036
Nuclear Bomb Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Bomb Market Insights
Multi-source component sourcing for plutonium pits and tritium reservoirs is broadening across the US nuclear weapons complex. Lockheed Martin Corporation dominates strategic systems integration for air-delivered weapons, while Northrop Grumman Corporation sustains ICBM modernization through the Sentinel program. RTX Corporation competes in nuclear-capable cruise missile propulsion and guidance architectures.
A nuclear bomb is a weapon deriving destructive energy from nuclear fission, fusion, or combined thermonuclear reactions, typically employing plutonium-239 or highly enriched uranium-235 cores with deuterium-tritium boosting to achieve yields from sub-kiloton to multi-megaton ranges. Its primary purpose is strategic deterrence through assured second-strike capability under mutual assured destruction doctrines. Thermonuclear warheads occupy the highest value tier given their complexity and limited production base, while submarine-launched delivery systems represent the fastest-growing segment as nations prioritize survivable second-strike platforms. Sea-based deployment platforms command premium margins due to integration complexity with ballistic missile submarine fleets.
The US National Nuclear Security Administration enforces design, safety, and security standards across the nuclear weapons enterprise, while the Department of Energy's Stockpile Stewardship Program shapes sustained demand for non-test validation technologies. The International Atomic Energy Agency's safeguards protocols and the Treaty on the Non-Proliferation of Nuclear Weapons constrain market access to authorized nuclear-weapon states, limiting supplier participation to government-directed industrial bases. Stakeholders must monitor shifts in US congressional appropriations for pit production capacity at Los Alamos and Savannah River, as these infrastructure investments determine long-term supply constraints for plutonium cores.
Market Dynamics
The US Department of Energy's Stockpile Stewardship Program mandates perpetual warhead refurbishment without underground testing, forcing reliance on supercomputing simulation and subcritical experiments to certify weapon reliability.
Growth Catalysts
- Submarine-Based Deterrence Modernization:The US Navy's Columbia-class ballistic missile submarine program drives demand for compatible warhead variants. Sea-launched platforms offer survivable second-strike capability that air and land systems cannot match.
- Plutonium Pit Production Expansion:The National Nuclear Security Administration's infrastructure investments at Los Alamos and Savannah River Sites aim to restore domestic pit manufacturing capacity after decades of single-source dependency.
- Tritium Reservoir Replacement Cycles:The Department of Energy's Tritium Modernization Program requires continuous refresh of decaying gas reservoirs across the deployed stockpile, sustaining specialized component demand.
Market Restraints
- Highly Enriched Uranium Feedstock Constraints:Downblending of weapons-grade uranium for civilian reactor fuel has depleted strategic reserves, complicating warhead life extension programs that require fresh fissile cores.
- Single-Point Production Concentration:The entire US plutonium pit fabrication base currently operates at Los Alamos National Laboratory, creating catastrophic supply vulnerability from seismic, security, or operational disruption.
- Comprehensive Test Ban Treaty Prohibition:The 1996 CTBT framework prevents full-yield nuclear testing, forcing billion-dollar investments in alternative certification infrastructure that raises program costs and extends development timelines.
Strategic Opportunities
- Warhead Interoperability Architectures:The W93 warhead program under development seeks common components across multiple delivery platforms, reducing unique part counts and enabling scalable production.
- Advanced Manufacturing Adoption:Additive manufacturing of specialized high-explosive lenses and precision-machined uranium components offers path to compressed production cycles and reduced hazardous waste generation.
- Allied Deterrence Burden-Sharing:NATO's nuclear sharing arrangements with Belgium, Germany, Italy, the Netherlands, and Turkey sustain demand for B61 gravity bomb modernization and shared basing infrastructure.
Industry Challenges
- Specialized Workforce Attrition:The weapons complex confronts accelerating retirement of nuclear engineers and plutonium metallurgists trained during Cold War-era testing programs, with insufficient pipeline replacement.
- Legacy System Integration Complexity:New warhead designs must interface with 1970s-era Minuteman III and 1980s-era Trident II delivery systems during extended modernization transitions, imposing severe interface constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Bomb Market |
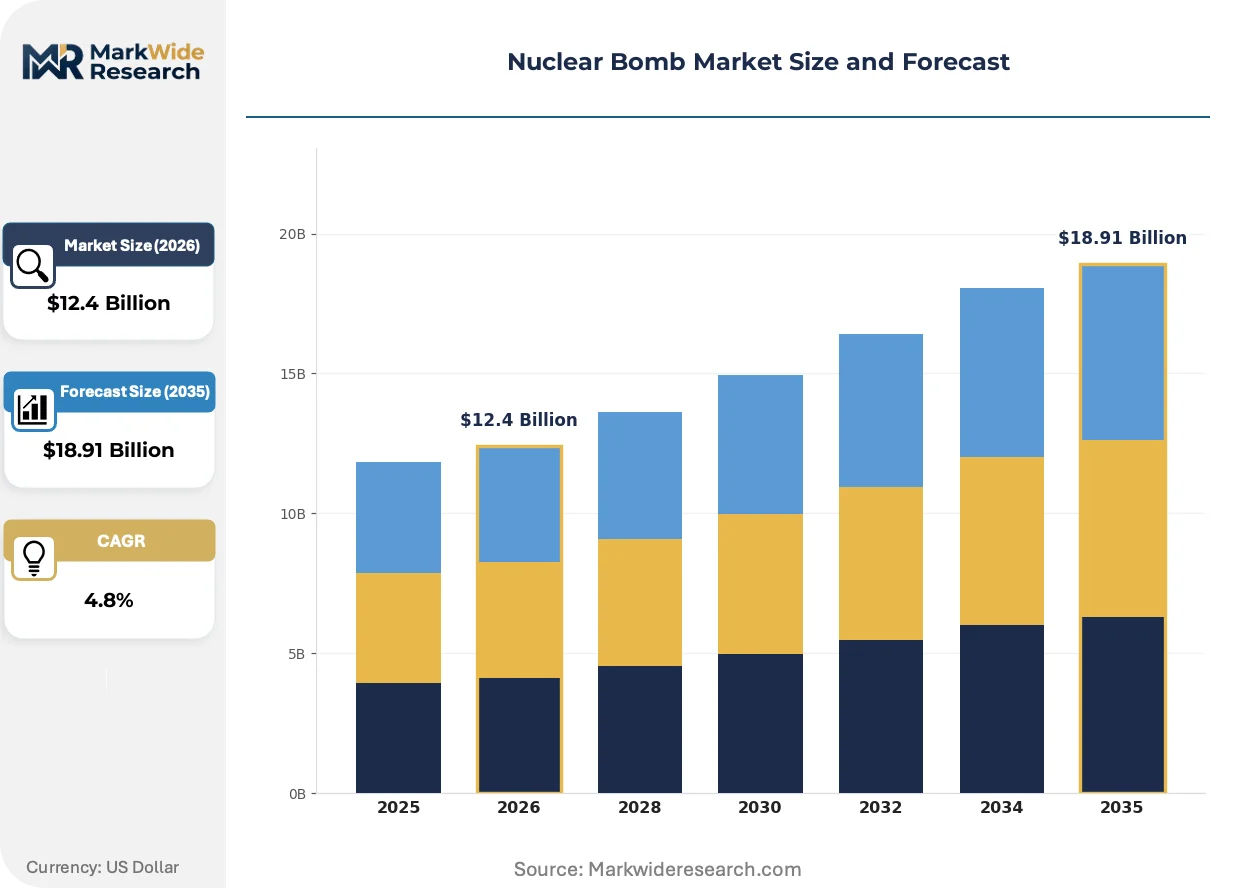
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warhead Type: Thermonuclear, Fission, Neutron, Enhanced Radiation, Boosted Fission Delivery System: Intercontinental Ballistic Missile, Submarine-Launched Missile, Strategic Bomber, Cruise Missile, Artillery Shell Yield Range: Sub-Kiloton, Low Kiloton, Medium Kiloton, High Kiloton, Megaton Deployment Platform: Land-Based, Sea-Based, Air-Based, Mobile Launcher, Underground Silo |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, BAE Systems, Boeing, MBDA, Airbus, Thales, Rafael Advanced Defense Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Bomb Market Trends and Innovations
Computational weapon physics is displacing empirical testing as the primary certification pathway, while modular warhead architectures promise production flexibility previously impossible under bespoke Cold War designs.
Supercomputing-based three-dimensional weapon simulation is overtaking hydrodynamic testing as the dominant certification methodology. The Lawrence Livermore and Los Alamos laboratories now deploy exascale systems to model thermonuclear burn physics. This capability compresses design iteration cycles and enables exploration of yield-to-weight optimizations impossible under test-limited regimes.
The US National Nuclear Security Administration's Enhanced Surveillance Program mandates continuous environmental monitoring of aged stockpile components. This policy forces replacement of organic materials—polymers, foams, adhesives—that degrade unpredictably over decades. Weapons laboratories respond with accelerated aging protocols and synthetic material substitutions validated through non-nuclear experiments.
Consolidated prime contracting is displacing fragmented subcontractor networks across the weapons complex. The Department of Energy has shifted toward fewer, larger indefinite-delivery contracts covering integrated design, manufacturing, and sustainment. This pattern concentrates risk with Bechtel National and Consolidated Nuclear Security at Pantex and Y-12 facilities, reducing interface management overhead but amplifying single-source dependency.
Nuclear Bomb Market Segmentation
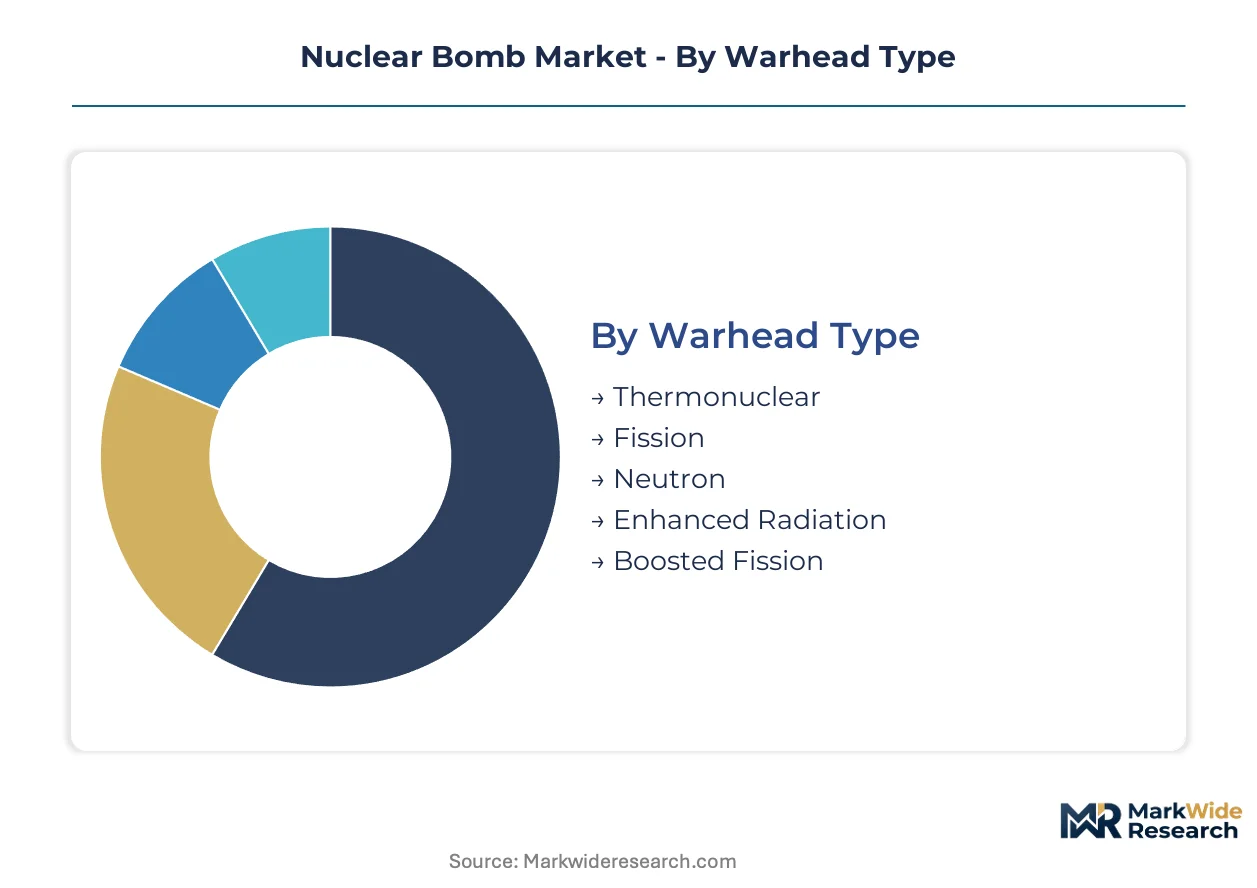
Segmentation in the nuclear bomb market reflects distinct operational requirements across deterrence missions. Each dimension—warhead physics, delivery kinematics, yield calibration, and basing mode—creates irreversible procurement commitments that shape decades-long modernization cycles.
Warhead Type:
Cost tiers separate strategic arsenals from tactical options, with thermonuclear designs commanding multiples of fission-only budgets due to materials and precision demands.
- Thermonuclear:Two-stage radiation implosion weapons using fission primary to ignite lithium deuteride secondary, achieving yields exceeding one megaton. The US W88 and W76 warheads for Trident II missiles concentrate demand at Los Alamos and Pantex facilities, driven by Navy Columbia-class submarine procurement.
- Fission:Single-stage plutonium or uranium devices with yields below 500 kilotons. These occupy legacy bomber and tactical roles; the B61 gravity bomb life extension program sustains production at Sandia National Laboratories.
- Neutron:Enhanced radiation weapons designed to maximize prompt neutron flux over blast effects. Minimal current procurement due to strategic obsolescence and warhead retirement schedules.
- Enhanced Radiation:Specialized variants for area denial with reduced fallout profiles. No active production lines; stockpile stewardship focuses on aging component surveillance.
- Boosted Fission:Deuterium-tritium gas injection amplifies fission efficiency without full thermonuclear staging. The W93 program evaluates boosted architectures for future ICBM and SLBM compatibility.
Thermonuclear warheads lead volumes today; boosted fission designs are gaining share fastest as modular architectures displace bespoke Cold War configurations.
Delivery System:
Application urgency varies by survivability calculus—sea-based platforms resist first-strike elimination while land systems prioritize prompt response.
- Intercontinental Ballistic Missile:Ground-based strategic deterrence with 5,500-plus kilometer range and 30-minute flight time. Northrop Grumman's Sentinel program replaces Minuteman III, sustaining demand at Hill Air Force Base and FE Warren installations.
- Submarine-Launched Missile:Trident II D5LE and successor systems deploy from Ohio-class and Columbia-class submarines. The Navy's strategic systems programs command premium integration budgets at Lockheed Martin's Sunnyvale facility.
- Strategic Bomber:B-2 Spirit and B-52H aircraft delivering gravity bombs and cruise missiles. B-21 Raider development shifts procurement toward penetrating bomber roles with compatible warhead interfaces.
- Cruise Missile:Air-launched AGM-86B and sea-launched Tomahawk variants with nuclear capability. RTX Corporation sustains propulsion and guidance architectures at Tucson and Camden facilities.
- Artillery Shell:Tactical 155mm and 203mm nuclear projectiles for battlefield use. Complete retirement from US inventory; NATO sharing arrangements retain gravity bomb alternatives exclusively.
Submarine-launched missiles lead volumes today; cruise missiles are climbing the fastest as dual-capable platforms expand mission flexibility.
Yield Range:
Customer type determines yield selection—strategic commanders require megaton-class assurance while theater commanders prioritize kiloton-scale discrimination.
- Sub-Kiloton:Specialized devices below one kiloton yield for ultra-precise targeting or enhanced radiation missions. Minimal stockpile presence; physics package miniaturization challenges limit deployment.
- Low Kiloton:One to ten kiloton yields for tactical aircraft and cruise missile delivery. The B61-12 life extension program incorporates selectable yield options down to 0.3 kilotons for graduated response scenarios.
- Medium Kiloton:Ten to 100 kiloton range balancing blast effects with collateral damage constraints. W76-1 warheads for Trident II occupy this tier with 100 kiloton nominal yield.
- High Kiloton:100 to 500 kiloton yields for hardened target defeat and area destruction. W88 warheads achieve 475 kilotons through advanced spherical secondary designs.
- Megaton:Exceeding one megaton for maximum deterrence signaling and counterforce missions. Legacy B83 gravity bombs represent sole active megaton-class US weapon pending retirement decisions.
Medium kiloton yields lead volumes today; low kiloton selectable-yield architectures are expanding most quickly as precision targeting reduces yield requirements.
Deployment Platform:
Supply concentration varies dramatically—sea platforms integrate with submarine industrial base while land systems leverage existing missile fields.
- Land-Based:Fixed silo and mobile launcher configurations across Wyoming, Montana, and North Dakota. FE Warren, Malmstrom, and Minot Air Force Base complexes sustain Minuteman III operations through Sentinel transition.
- Sea-Based:Ballistic missile submarine patrols from Kings Bay, Georgia and Bangor, Washington. The Columbia-class construction program at Electric Boat and Newport News Shipbuilding drives warhead integration demand.
- Air-Based:Bomber alert forces at Whiteman, Barksdale, and Minot bases with global reach. Nuclear-certified aircraft require specialized weapon storage and handling at secure aircraft shelters.
- Mobile Launcher:Road- and rail-mobile systems for survivable dispersal. No current US deployment; Russian RS-24 Yars and Chinese DF-41 systems inform adversary capability assessments.
- Underground Silo:Hardened concrete and steel emplacements resisting 2,000-plus psi overpressure. Existing Minuteman fields require sustained maintenance as Sentinel construction proceeds through the 2030s.
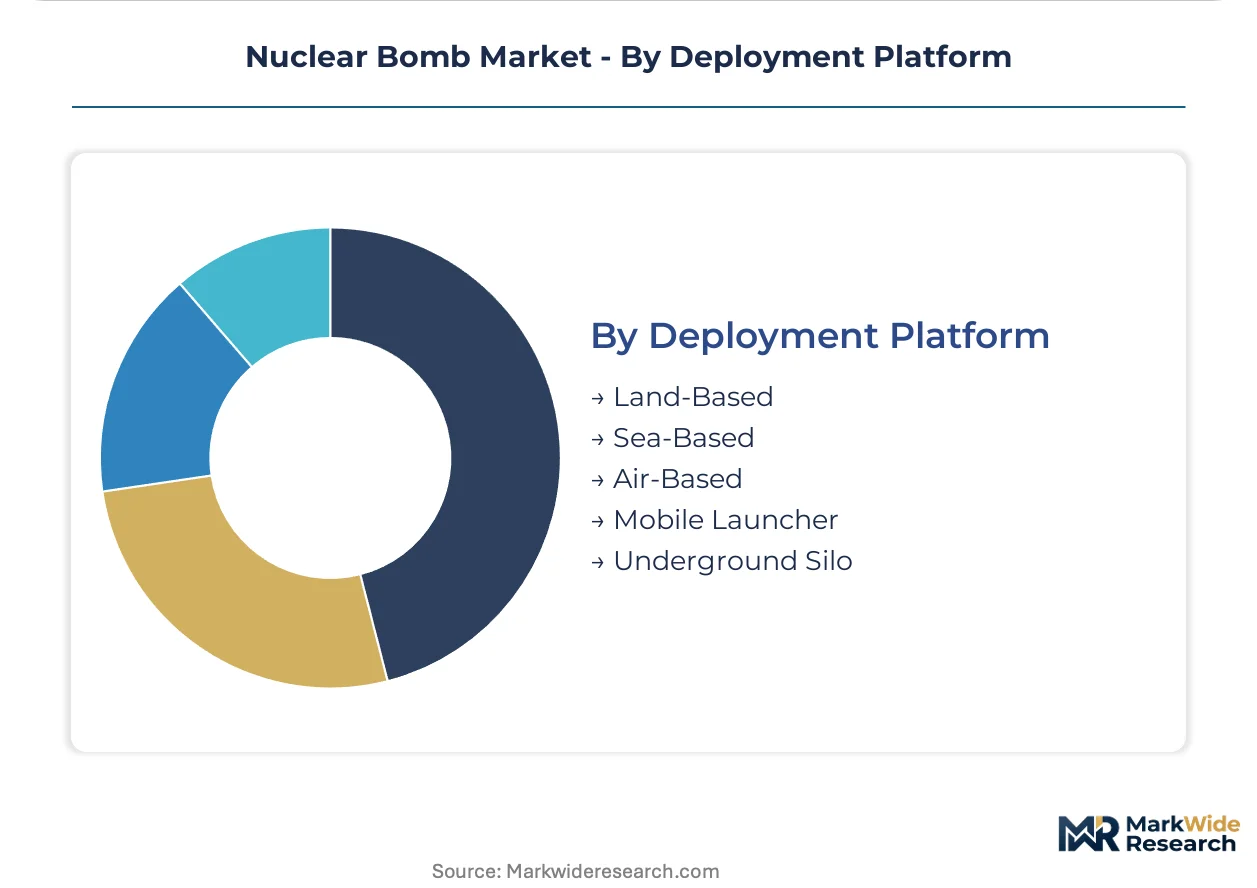
Sea-based platforms lead volumes today; land-based Sentinel infrastructure is gaining share fastest as modernization shifts procurement toward next-generation silo and launch control systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pantex Plant in Amarillo anchors the global nuclear weapons industrial base. Government-directed procurement concentrates warhead assembly and disassembly at this Texas facility. The National Nuclear Security Administration governs all site operations through federal contracting mechanisms.
United States
Stockpile Stewardship Program mandates drive pit production expansion at Los Alamos and Savannah River Sites. The Department of Energy oversees tritium reservoir replacement cycles through the Tritium Modernization Program. Pantex in Texas and Y-12 in Tennessee handle warhead assembly and uranium component fabrication respectively.
United Kingdom
Trident warhead refurbishment sustains demand at the Atomic Weapons Establishment in Aldermaston. The Ministry of Defence's nuclear enterprise program governs capability retention without live testing. Berkshire's AWE complex maintains plutonium handling and high-explosive manufacturing expertise.
France
Air-Sol Moyenne Portée-Amélioré modernization drives warhead life extension at Direction des Applications Militaires facilities. The Commissariat à l'énergie atomique et aux énergies alternatives regulates all nuclear weapons activities. Île-de-France's DAM laboratories at Bruyères-le-Châtel conduct simulation-based certification.
Russia
Avangard hypersonic glide vehicle deployment necessitates specialized warhead packaging at Sarov and Snezhinsk facilities. Rosatom's nuclear weapons complex operates under presidential decree through closed administrative territorial formations. Nizhny Novgorod Oblast's Sarov nuclear center remains the primary design hub.
China
DF-41 and JL-3 modernization programs expand plutonium pit manufacturing at Plant 821 and Plant 814. The China Academy of Engineering Physics governs weapons research under State Administration of Science, Technology and Industry for National Defense. Sichuan's Mianyang region concentrates simulation and testing infrastructure.
Nuclear Bomb Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent deterrence technologies outside warhead fabrication. The vendor base consolidates around prime systems integrators holding indefinite-delivery federal contracts. Two archetypes dominate: vertically integrated defense conglomerates managing multi-decade modernization programs, and specialized national laboratories executing design physics. Competitive positioning hinges on capturing Sentinel ICBM and Columbia-class submarine integration contracts, while secondary players seek tritium handling and surveillance technology niches.
Among US-based defense conglomerates, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the prime contractor archetype, with RTX Corporation occupying a position in propulsion and guidance subsystems. These entities anchor the competitive structure through consolidated federal contracting vehicles rather than market contestability.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| BAE Systems |
| Boeing |
| MBDA |
| Airbus |
| Thales |
| Rafael Advanced Defense Systems |
| Others |
Pricing and Supply Chain Analysis
Additive manufacturing adoption across high-explosive lens production and precision uranium component machining is compressing fabrication timelines while concentrating supplier relationships around Pantex and Y-12 facilities with certified advanced manufacturing capabilities.
Pricing Analysis
Input-cost pass-through from plutonium pit scarcity and tritium reservoir decay cycles dominates contract economics. The National Nuclear Security Administration employs cost-plus contracting with performance incentives, where price differentiation hinges on warhead complexity tier and delivery system integration certification level. Pricing pressure intensifies as single-source pit production at Los Alamos constrains volume scalability. Prime contractors face least price sensitivity on thermonuclear warhead programs; component suppliers encounter acute margin compression on organic material replacement contracts.
Supply Chain Analysis
Freight logistics for weapons-grade special nuclear materials operate under armed escort protocols that constrain routing flexibility and inflate transport costs. The supply chain draws from the United States, United Kingdom, and France for finished warhead assembly, with plutonium pits, tritium reservoirs, and high-explosive lenses as critical component dependencies. Single-source vulnerability at Los Alamos National Laboratory for pit fabrication creates catastrophic disruption risk. Distribution runs through National Nuclear Security Administration-administered federal contracting vehicles to Department of Defense delivery system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
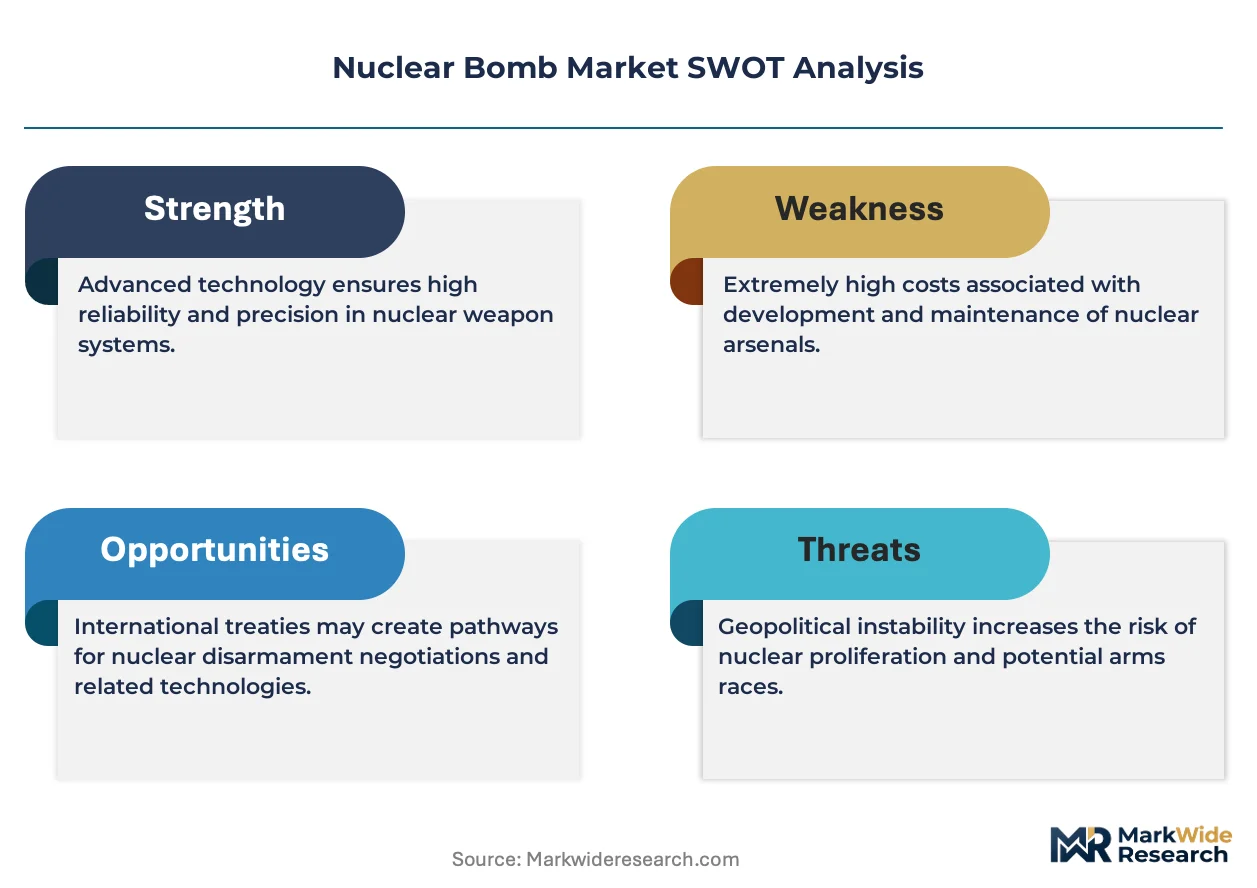
This market represents a late-cycle quality story as submarine-launched ballistic missile modernization and W93 warhead development shift procurement toward premium survivability specifications with extended service-life requirements.
For Market Incumbents: Anticipate workforce attrition threats by accelerating knowledge capture from retiring plutonium metallurgists and nuclear engineers through structured mentorship programs. Consolidate backward integration into tritium production at Savannah River Site to secure gas reservoir supply chains. Capture Sentinel ICBM integration contracts before Columbia-class submarine demand peaks absorb available engineering capacity.
For New Entrants and Emerging Players: Enter via surveillance technology and non-nuclear certification equipment niches where security clearance barriers are lowest. Target environmental monitoring systems for Enhanced Surveillance Program compliance at Pantex and Y-12. Pursue additive manufacturing partnerships with established primes to bypass direct warhead design authorization requirements.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component suppliers with dormant security clearances awaiting reactivation. Long-term viability centers on firms positioned for tritium handling and advanced manufacturing infrastructure across the weapons complex. Watch congressional appropriations for Savannah River pit production capacity as the inflection signal for supply constraint easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pit Production Capacity Expansion | Savannah River Site diversification reduces catastrophic single-source dependency at Los Alamos. |
| Warhead Interoperability Architecture | W93 common-component design enables scalable production across ICBM and SLBM platforms. |
| Advanced Manufacturing Certification | Additive manufacturing qualification at Pantex compresses high-explosive lens production cycles. |
| Tritium Supply Chain Integration | Vertical control over gas reservoir production secures decay-cycle replacement demand. |
| Computational Physics Infrastructure | Exascale simulation capability at Lawrence Livermore displaces empirical testing certification pathways. |
Research Methodology
Coverage spans the United States, United Kingdom, France, Russia, and China, with primary inputs from each market's weapons complex stakeholders. The analysis combines primary interviews with National Nuclear Security Administration program officers, prime contractor engineering directors, and plutonium metallurgy specialists with secondary validation through Department of Energy budget justifications, congressional appropriations records, and Stockpile Stewardship Program technical reports. Bottom-up procurement volume analysis triangulates against top-down defense budget allocation assessments.
Rate-of-change decomposition separates volume drivers from price escalation factors across the projection horizon. The analytical framework models segmentation by warhead physics type, delivery system kinematics, yield calibration tier, and deployment platform basing mode. CAGRs derive from infrastructure investment timelines tied to Columbia-class submarine and Sentinel ICBM procurement schedules. Forecast inputs incorporate pit production capacity constraints and tritium decay replacement cycles without assuming live testing resumption.
The model holds under continued Comprehensive Test Ban Treaty adherence and sustained congressional funding for Stockpile Stewardship; deviation in either trigger would shift certification cost curves and development timelines. Stakeholders should weight assumptions against their own operating context and clearance access levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Shotgun Shell Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Recoilless Rifle Market