
 Egypt Food Preservatives Market | 2026-2036
Egypt Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Preservatives Market Foresight
Domestic blending capacity in Egypt's chemical corridor is hardening as local formulators expand output for bakery and dairy clients. Cargill Egypt leverages its Red Sea logistics hub to import bulk antioxidant intermediates for redistribution to Upper Egypt processors. Kerry Group sustains technical service teams in Alexandria and Cairo that customize antimicrobial blends for meatpacking clients. BASF SE anchors the high-end synthetic segment through its Egyptian distributor network, supplying sorbate and benzoate salts to multinational food manufacturers.
Food preservatives comprise chemical substances added to food matrices to inhibit microbial spoilage, oxidative rancidity, and enzymatic degradation, typically dosed at concentrations between 0.01% and 0.3% by weight depending on water activity and pH of the substrate. Their primary commercial purpose is to extend distribution reach and reduce post-harvest losses in climates with ambient temperatures exceeding product stability thresholds. Antimicrobials dominate volume consumption in Egypt due to pervasive ambient-temperature distribution chains that lack continuous cold-chain integrity for processed meats and dairy. Natural preservatives are gaining fastest traction among food manufacturers reformulating for clean-label positioning in premium retail channels, though synthetic preservatives still capture the deepest margin pools in institutional foodservice procurement where cost sensitivity overrides label claims.
Egypt's food additive standards fall under the Egyptian Organization for Standardization and Quality (EOS) and the National Food Safety Authority (NFSA), which mandate registration, labeling, and maximum usage levels for permitted preservatives in specified food categories. Compliance with these frameworks shapes product access by requiring local efficacy testing and reformulation for heat-stable applications where Gulf-imported benchmarks may not satisfy domestic thermal processing parameters. EOS alignment with Codex Alimentarius guidelines creates dual compliance obligations for exporters serving both Egyptian retail and re-export markets through Suez Canal trade corridors. Stakeholders must monitor pending NFSA revisions to natural preservative positive lists, as expanded botanical extract approvals would redirect R&D spending toward plant-derived antimicrobial systems.
Market Dynamics
Egypt's preservative procurement is pivoting around NFSA's tightened maximum-residue protocols, which force reformulation cycles across dairy and meat processors operating in ambient-temperature distribution corridors.
Growth Catalysts
- Packaged Dairy Expansion:Heat-stressed supply chains in Upper Egypt drive antioxidant and antimicrobial dosing to prevent spoilage in unrefrigerated transit. Processors scale blended preservative procurement to match output growth.
- EOS Codex Alignment:Egyptian Organization for Standardization harmonization with Codex Alimentarius enables dual-compliant exports through Suez Canal corridors, opening re-export channels for preservative-treated foods.
- Clean-Label Reformulation:Natural antimicrobial systems from rosemary and green tea extracts gain shelf space in premium Cairo retail, pulling R&D spend toward botanical-derived preservation.
Market Restraints
- Synthetic Input Concentration:Sorbate and benzoate salt supply concentrates through a narrow importer base, exposing processors to Red Sea shipping volatility and currency-driven cost spikes.
- Clean-Label Cost Premium:Natural preservative systems command 3-4x synthetic equivalent pricing, constraining adoption in institutional foodservice where margin compression dominates procurement criteria.
- Thermal Stability Gaps:Gulf-imported preservative benchmarks often fail Egyptian UHT and retort processing parameters, requiring redundant local efficacy testing that extends registration timelines.
Strategic Opportunities
- Upper Egypt Distribution Penetration:Unrefrigerated rural retail networks in Minya and Assiut governorates remain underserved by preservative suppliers, creating first-mover positioning for antimicrobial blend formulators.
- NFSA Botanical List Expansion:Pending approvals for additional plant-derived antimicrobials would redirect technical service investment toward natural preservation system development.
- Red Sea Logistics Integration:Bulk intermediate import through Ain Sokhna port enables backward integration into local antioxidant blending, compressing lead times for Nile Delta manufacturers.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Technical staff capable of optimizing preservative synergy in high-water-activity dairy matrices remain concentrated in Alexandria and Cairo, constraining regional processor capability.
- Dual Registration Burden:Separate EOS and NFSA filing requirements for new preservative approvals extend commercialization timelines by 8-14 months versus single-regulator markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Preservatives Market |
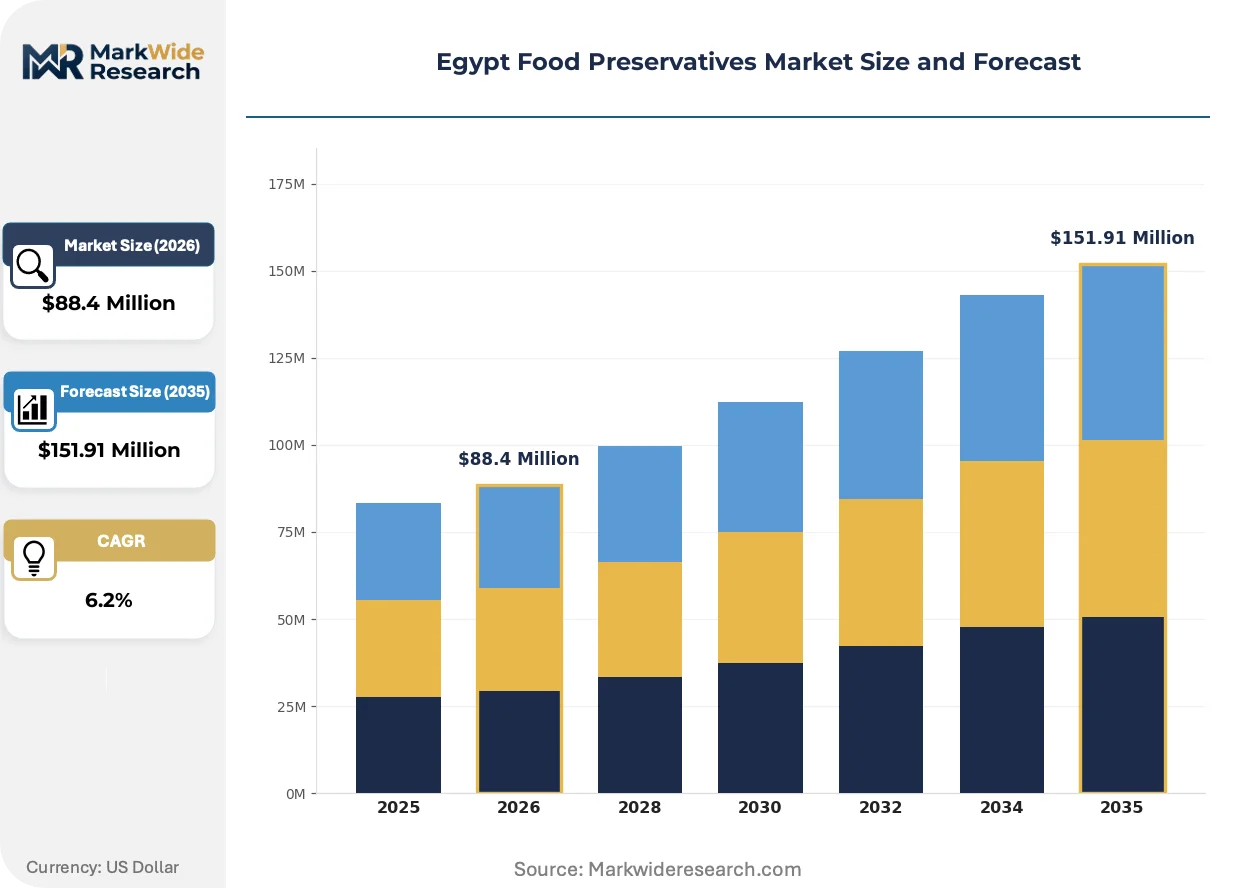
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $151.91 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antioxidants, Natural Preservatives, Synthetic Preservatives Application: Dairy Products, Bakery Goods, Meat Products, Beverages Form: Liquid, Powder, Granular, Spray End User: Food Manufacturers, Retailers, Foodservice Providers, Home Consumers |
| Companies Covered | Cargill Incorporated, DuPont de Nemours Inc, BASF SE, Kerry Group, Koninklijke DSM NV, KFG for International Trading, Cargill Egypt, Tate & Lyle, Kemin Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Preservatives Market Shifts & Advancements
Preservation technology in Egypt is bifurcating between synthetic cost optimization and natural system performance, with regulatory pressure and channel differentiation driving parallel innovation tracks.
Encapsulated essential oil delivery systems are decentralizing antimicrobial deployment across Egyptian bakery and dairy applications. These lipid-shell matrices protect volatile compounds from thermal degradation during UHT processing. Mid-size processors in 10th of Ramadan City adopt at accelerating pace to bridge clean-label positioning with ambient shelf stability. The technology is decentralizing formulation expertise from multinational technical centers to local blending facilities.
NFSA's pending revision to natural preservative positive lists is compressing synthetic dependency in premium retail channels. The framework expands approved botanical extracts for meat and dairy applications, creating compliance-driven demand for plant-derived alternatives. Multinational manufacturers operating in Greater Cairo's industrial corridor accelerate reformulation pipelines to preempt enforcement windows.
Direct procurement from Red Sea import terminals is displacing distributor-mediated chemical sourcing among large-volume dairy processors. Buyers in Sadat City and 6th of October industrial zones establish captive supply relationships with bulk intermediate importers. This pattern concentrates most visibly in mozzarella and processed cheese manufacturing, where antioxidant throughput demands justify logistics investment.
Egypt Food Preservatives Market Segmentation
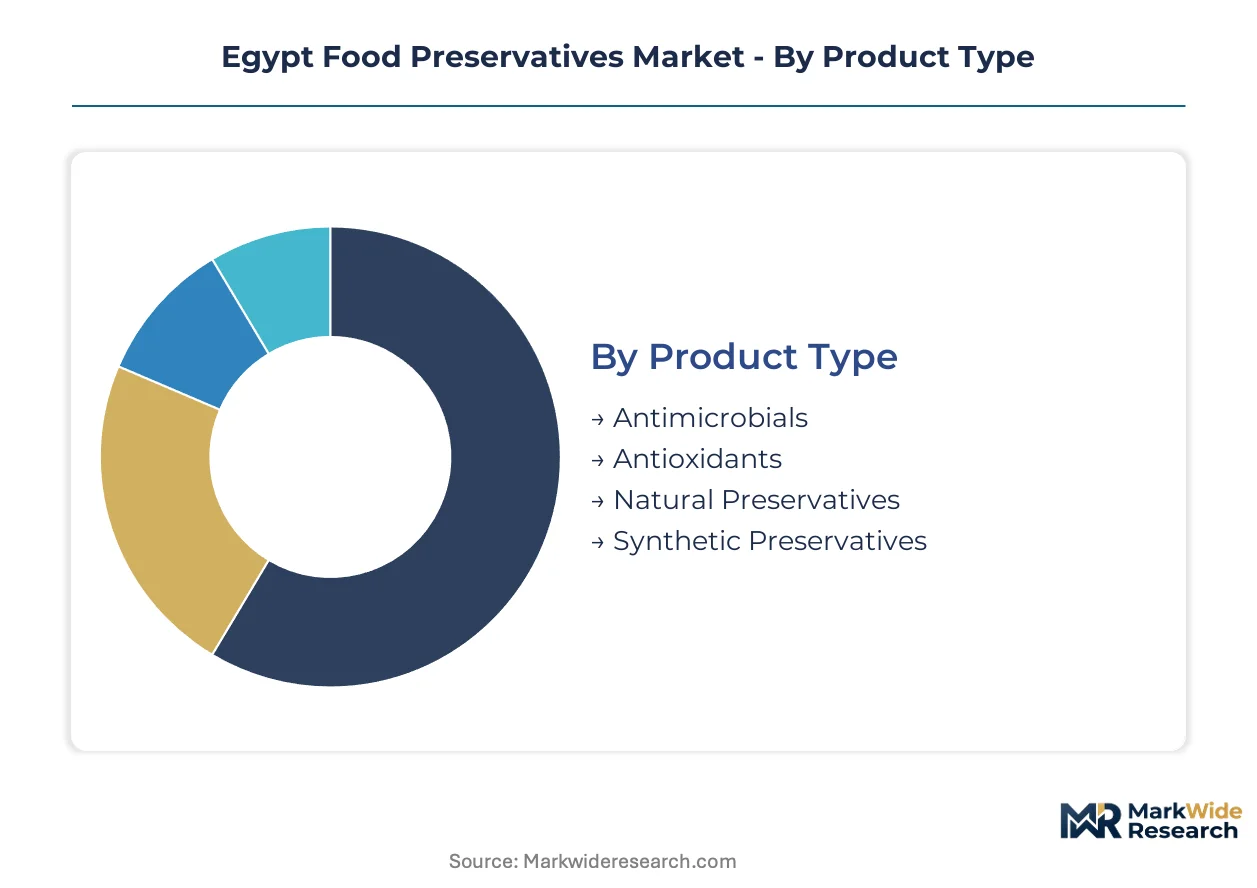
Preservative selection in Egypt's food industry hinges on thermal processing compatibility, distribution infrastructure, and regulatory compliance under NFSA protocols. Segmentation reveals how capital allocation and technical capability concentrate across distinct formulation categories and end-use channels.
Product Type:
Capital intensity varies sharply across preservation chemistry, with synthetic manufacturing requiring continuous reactor investment while natural extraction demands solvent recovery infrastructure.
- Antimicrobials:Sorbate and benzoate salts dominate volume consumption in ambient-temperature meat and dairy distribution. Greater Cairo processors scale bulk procurement to match unrefrigerated supply chain expansion into Upper Egypt governorates.
- Antioxidants:BHA, BHT, and tertiary butylhydroquinone formulations protect lipid oxidation in UHT dairy and frying oils. Sadat City mozzarella manufacturers drive concentrated demand through direct Red Sea terminal sourcing.
- Natural Preservatives:Rosemary extract and green tea polyphenol systems command premium positioning in clean-label retail channels.
- Synthetic Preservatives:Cost-optimized benzoic acid derivatives retain institutional foodservice dominance despite label-conscious reformulation pressure.
Antimicrobials absorb the bulk of installed capacity; natural preservatives are expanding most quickly.
Application:
Dairy processing commands the deepest technical service relationships due to complex water activity and pH optimization requirements.
- Dairy Products:Processed cheese and UHT milk formulations require heat-stable antimicrobial synergy. 6th of October industrial zone manufacturers invest in captive antioxidant blending to compress lead times.
- Bakery Goods:Propionate-based mold inhibitors face reformulation pressure as encapsulated essential oil systems gain technical validation in 10th of Ramadan City facilities.
- Meat Products:Ambient sausage and luncheon meat production drives nitrite and sorbate demand across Nile Delta slaughterhouse clusters.
- Beverages:Benzoate-acid combinations stabilize pH-sensitive soft drinks against yeast contamination in PET bottling lines.
Dairy applications anchor supplier technical investment; bakery goods are climbing the fastest as encapsulation technology decentralizes formulation expertise.
Form:
Powder handling infrastructure dominates capital deployment, though liquid dosing systems gain traction in continuous processing environments.
- Liquid:Pump-dispersed sorbate solutions integrate directly into automated dairy pasteurization loops. Alexandria-based formulators customize concentration ratios for specific pH matrices.
- Powder:Free-flowing benzoate and propionate salts suit dry-mix bakery premix operations. Bulk silo storage in Sadat City compression-molding facilities enables just-in-time antioxidant addition.
- Granular:Low-dust sorbic acid granules reduce respiratory exposure in meatpacking plant environments.
- Spray:Surface application systems for bakery mold inhibition remain niche due to uniform coverage challenges in high-humidity climates.
Powder forms retain the deepest installed base; liquid systems are gaining share fastest through continuous processing adoption.
End User:
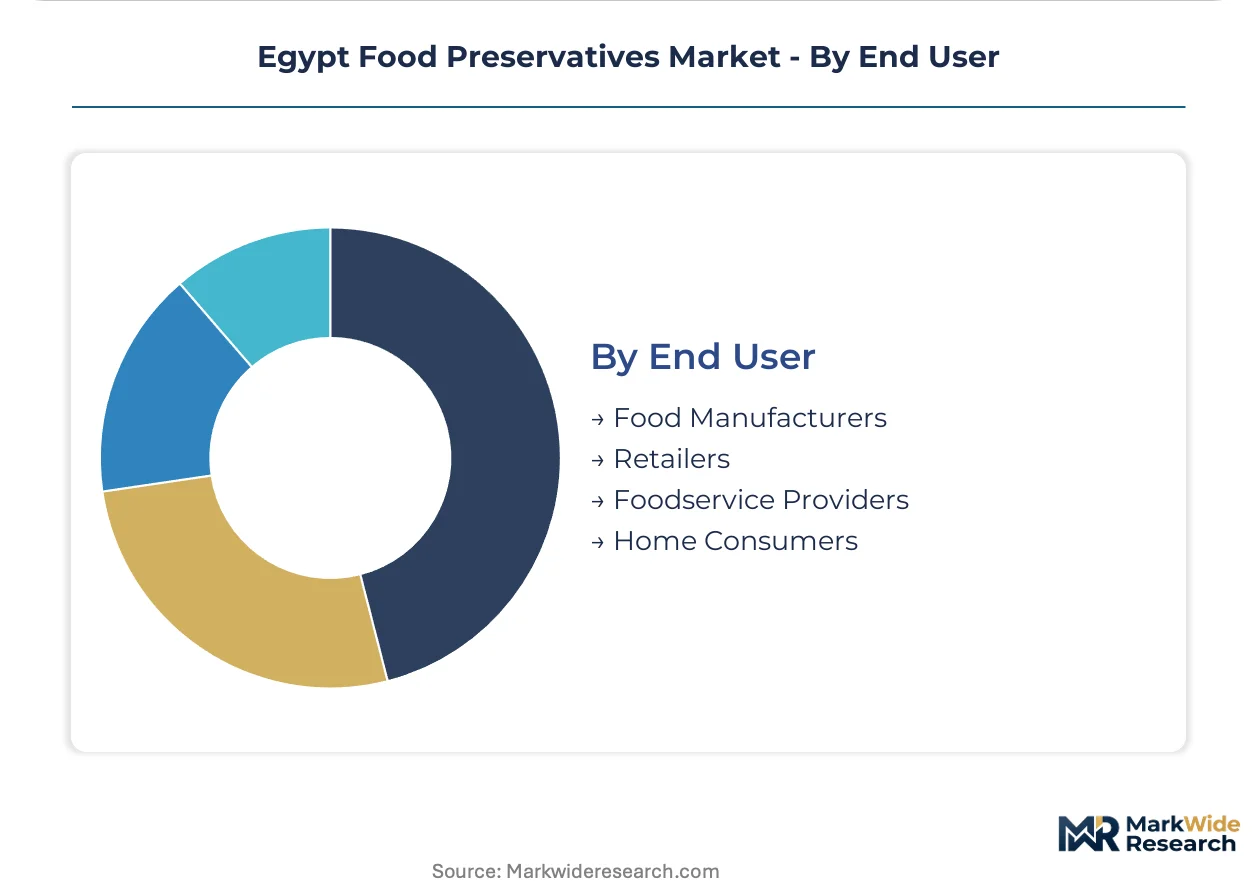
Food manufacturers concentrate procurement volume and technical specification authority, while downstream channels shape final formulation selection through label requirements.
- Food Manufacturers:Multinational dairy and meat processors in Greater Cairo's industrial corridor drive blended preservative specification. Kerry Group and Cargill Egypt maintain dedicated technical service teams for direct formulation support.
- Retailers:Hypermarket private-label buyers in Cairo and Alexandria impose clean-label mandates that cascade reformulation requirements to contract manufacturers.
- Foodservice Providers:Institutional catering procurement prioritizes cost stability over label positioning, sustaining synthetic preservative volume in bulk ingredient sourcing.
- Home Consumers:Direct retail purchase of pure preservative salts remains minimal, confined to artisanal food producers and small-scale bakery operations.
Food manufacturers command the steepest supplier investment; retailers are redirecting R&D spend fastest through compliance-driven specification changes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors along the Suez Canal anchor Egypt's preservative import infrastructure, with Red Sea terminals processing bulk antioxidant intermediates for redistribution to Nile Delta manufacturing clusters.
Greater Cairo
Industrial food corridors in 6th of October City and 10th of Ramadan City concentrate dairy and meat processing capacity. NFSA enforcement of tightened maximum-residue protocols drives reformulation demand among UHT milk manufacturers. Encapsulated essential oil systems gain technical validation in bakery applications as local blending facilities expand.
Alexandria
Mediterranean port access enables direct bulk chemical import for multinational formulators. Kerry Group maintains technical service teams customizing antimicrobial blends for meatpacking clients. The city's chemical logistics infrastructure supports just-in-time antioxidant delivery to Sadat City mozzarella processors.
Upper Egypt
Unrefrigerated distribution networks in Minya and Assiut governorates create concentrated demand for heat-stable antimicrobial systems. Ambient-temperature supply chains force elevated sorbate dosing in processed cheese transit. Rural retail penetration remains underserved by technical service providers.
Suez Canal Corridor
Ain Sokhna port terminals enable backward integration for large-volume dairy processors importing bulk intermediate antioxidants. Cargill Egypt leverages Red Sea logistics for redistribution to Upper Egypt manufacturing zones. The corridor supports dual-compliant export production aligned with Codex Alimentarius standards.
Nile Delta
Slaughterhouse clusters across Damietta and Kafr El Sheikh drive nitrite and propionate consumption in sausage and luncheon meat production. Domestic blending capacity hardens as local formulators expand output for bakery sector clients. Formulation chemistry expertise scarcity constrains regional processor technical capability.
Egypt Food Preservatives Market Competitive Landscape
Global majors compete with regional champions across technical service deployment and import logistics integration. The vendor base organizes around three tiers: multinational chemical conglomerates with Egyptian distributor networks, regional formulators with captive blending capacity, and local trading houses facilitating Red Sea bulk procurement. Consolidation pressures concentrate most visibly in synthetic preservative salts, where narrow importer bases expose processors to currency volatility. Competitive moves center on backward integration into local antioxidant blending and geographic expansion into underserved Upper Egypt distribution corridors.
Among multinational chemical conglomerates, BASF SE anchors high-end synthetic supply through its Egyptian distributor network, while Cargill Incorporated exemplifies integrated logistics players leveraging Red Sea terminal access. Kerry Group occupies a position within the technical service-intensive tier, maintaining dedicated formulation support teams for direct meatpacking and dairy processor engagement. These three archetypes represent distinct competitive vectors: manufacturing scale, supply chain control, and application expertise.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont de Nemours Inc |
| BASF SE |
| Kerry Group |
| Koninklijke DSM NV |
| KFG for International Trading |
| Cargill Egypt |
| Tate & Lyle |
| Kemin Industries |
| Others |
Supply & Pricing Matrix
Red Sea shipping tariffs on bulk antioxidant intermediates cascade through three distinct pricing tiers before reaching Nile Delta dairy processors, with technical service bundling separating multinational formulators from trading-house resellers. Unbundled procurement from Ain Sokhna terminals compresses landed costs for large-volume buyers in Sadat City, while smaller Upper Egypt processors absorb distributor markups on sorbate salts.
Pricing Analysis
Technical service bundling distinguishes pricing tiers in Egypt's preservative market, with Kerry Group and Cargill Egypt embedding formulation support into contracted rates while independent traders strip out advisory layers for price-sensitive institutional foodservice buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—NFSA-registered natural extracts command top positioning, EOS-compliant synthetics anchor mid-market, and unregistered imports serve informal channels. Cost compression in synthetic salts is intensifying because currency volatility elevates importer hedging costs. Institutional catering procurement teams exhibit highest price sensitivity, while multinational dairy manufacturers prioritize supply security over unit economics.
Supply Chain Analysis
Regional distribution centers in Alexandria and Ain Sokhna operate as hub-and-spoke nodes, consolidating bulk chemical imports for redistribution to 6th of October City and 10th of Ramadan City manufacturing clusters. Supply concentrates in Germany, China, and India for synthetic sorbate and benzoate precursors; natural extracts draw from Spanish rosemary cultivation and Chinese green tea processing. Raw material dependencies rest on petrochemical feedstocks, botanical solvent extraction capacity, and Red Sea container terminal throughput. Single-source vulnerability concentrates in the narrow importer base handling synthetic salt customs clearance. Distribution runs through captive logistics partnerships for large dairy processors and fragmented trading networks for regional meatpackers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's food preservative sector is accelerating into a vertical-integration race, with Red Sea terminal access and local blending capacity emerging as the decisive levers for margin control.
For Market Incumbents: Deepen backward integration into antioxidant blending at Ain Sokhna port to compress lead times for Upper Egypt dairy processors facing ambient-temperature distribution stress. Expand technical service teams in Minya and Assiut to preempt emerging competitors targeting underserved rural networks. The pending NFSA botanical list expansion threatens synthetic-dependent incumbents with reformulation displacement; captive natural extraction partnerships provide defensive optionality. For New Entrants and Emerging Players: Capture the technical service gap in Upper Egypt's meatpacking corridor, where formulation chemistry expertise scarcity constrains regional processor capability. The encapsulated essential oil segment offers lowest competitive density, with 10th of Ramadan City bakery facilities validating adoption curves. A go-to-market angle anchored in UHT thermal stability testing—addressing Gulf-imported benchmark failures—differentiates against established distributors. For Investors and Strategic Acquirers: NFSA's publication of expanded botanical positive lists is the leading indicator that natural preservation R&D spend will redirect toward compliance-driven demand. Long-term viability favors formulators with dual synthetic-natural capability across the projection horizon. Acquisition targets should display captive Red Sea logistics relationships or proprietary encapsulation technology. Monitor Cargill Egypt's blending capacity announcements as signal of sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Blending | Captive supply of antioxidants from Ain Sokhna terminals compresses lead times for Sadat City mozzarella processors. |
| NFSA Botanical List Pre-Registration | Early filing for rosemary and green tea extract approvals secures first-mover positioning in clean-label retail channels. |
| Upper Egypt Technical Service Expansion | Dedicated formulation teams in Assiut address expertise scarcity constraining regional meatpacking plant capability. |
| Encapsulation Technology Licensing | Lipid-shell essential oil systems bridge clean-label positioning with UHT thermal stability requirements. |
| Red Sea Logistics Partnership | Direct terminal relationships insulate against currency-driven cost spikes in sorbate salt procurement. |
Research Methodology
Trade customs databases, NFSA regulatory filings, and EOS standardization records formed the secondary backbone, cross-referenced with primary interviews conducted among preservative formulators, dairy procurement directors, and Red Sea logistics operators. Bottom-up volume estimates from individual manufacturing facilities in Greater Cairo's industrial corridor were triangulated against top-down import value analysis across the analysis window.
Historical trendline analysis of preservative import volumes and dairy processing capacity expansion informed the projection framework, with segmentation modeling across product type, application, and end-user channels. CAGRs were derived through regression analysis of import growth patterns and manufacturing output correlations. Key forecast inputs included NFSA enforcement timeline assumptions and Red Sea shipping cost volatility indices.
The model holds under stable EOS-NFSA regulatory alignment; deviation in botanical approval timelines or currency peg adjustments would shift natural versus synthetic adoption curves. Forecasts reflect base-case assumptions regarding Upper Egypt distribution infrastructure investment and encapsulated technology validation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Gardenia Food Color Market