
 France Feed Additives Market | 2026-2036
France Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
France Feed Additives Market Foresight
Modular premix bundling is pivoting how French compound feed mills configure additive procurement, shifting from single-ingredient orders toward integrated nutritional packets. Cargill Incorporated leverages its vertical grain-handling infrastructure to anchor supply security across northwestern France. Adisseo specializes in methionine and enzyme formulations that dominate the ruminant nutrition segment. BASF SE competes through its synthetic vitamin A and E portfolios, sustaining formulation partnerships with major cooperatives.
France feed additives comprise functional ingredients—enzymes, probiotics, vitamins, amino acids, and minerals—blended into compound feeds or premixes to enhance nutrient bioavailability, digestive efficiency, and animal metabolic performance at dosage rates typically measured in grams per ton of finished feed. These inputs serve commercial livestock producers seeking to optimize feed conversion ratios while complying with residue-limit protocols. Enzymes and probiotics command expanding share as antibiotic alternatives gain regulatory traction, while amino acids retain mature volume positions in poultry and swine rations. The animal type dimension structures demand around poultry and swine, with ruminant applications growing fastest as methane-mitigation additives attract dairy sector investment.
ANSM oversees veterinary medicinal product licensing, including zootechnical feed additives, while the EU Green Deal and F-Gas Regulation constrain chemical manufacturing inputs and emissions profiles for domestic production facilities. REACH compliance shapes import access for non-EU suppliers, elevating documentation burdens on novel microbial strains. Stakeholders must monitor pending revisions to the EU Feed Additives Regulation that could reclassify certain probiotic categories and redirect R&D investment toward fermentation-derived alternatives.
Market Dynamics
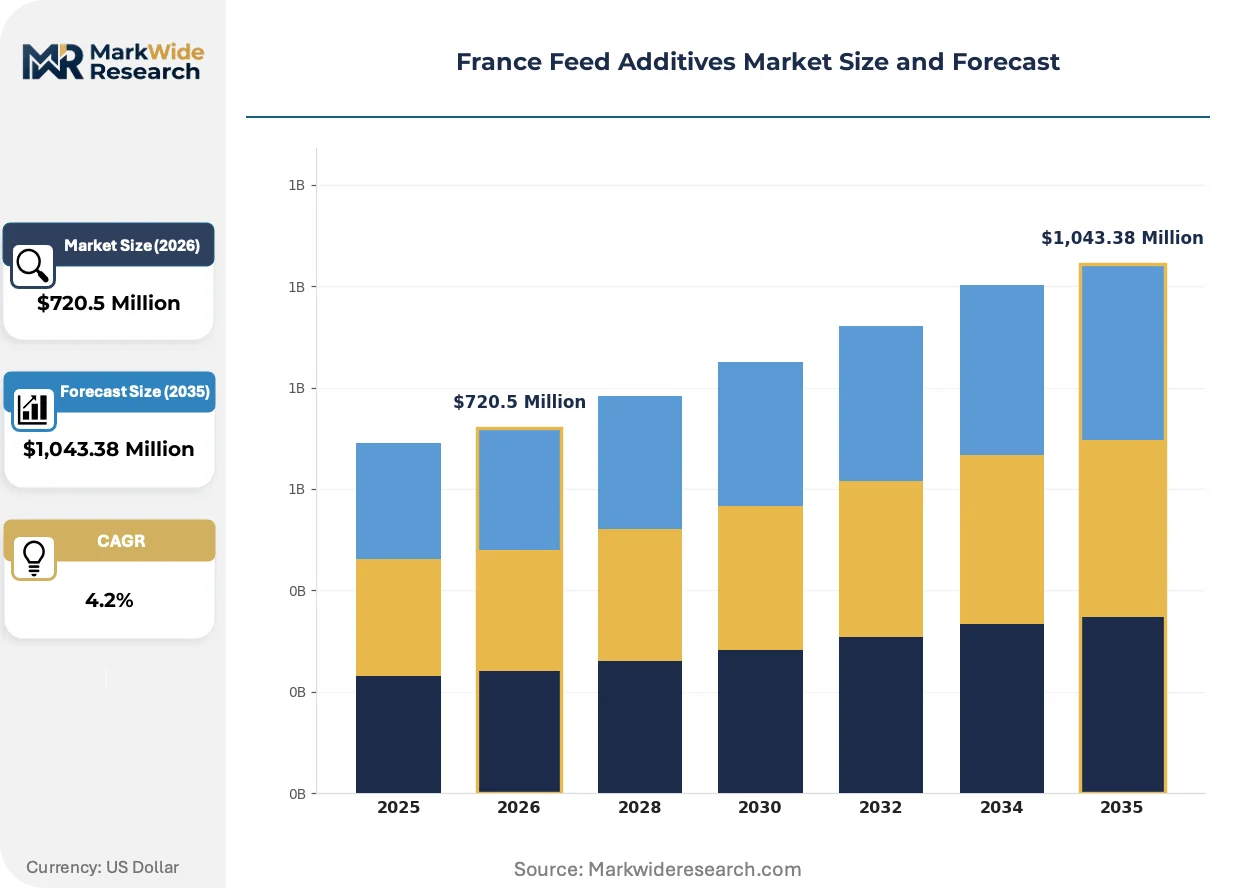
Modular premix bundling is compressing procurement cycles across French compound feed mills, forcing additive suppliers to reconfigure from single-ingredient sales toward integrated nutritional packets that reduce formulation complexity and inventory carrying costs.
Growth Catalysts
- EU Green Deal antibiotic restrictions:The Farm to Fork Strategy's tightening limits on antibiotic growth promoters and zinc oxide in piglet feeds accelerate demand for enzyme and probiotic alternatives in Brittany's dense pork production clusters.
- Precision-formulated premixes:Dairy cattle operations expand use of methane-mitigation additives as the sector invests in metabolic performance optimization to meet emission reduction targets.
- Brittany production concentration:Dense poultry and swine clusters in northwestern France drive bulk additive procurement volumes, creating scale economies for regional distribution infrastructure.
Market Restraints
- REACH documentation burdens:Compliance requirements for novel microbial strains elevate import barriers for non-EU suppliers, constraining strain diversity available to French formulators.
- F-Gas Regulation manufacturing constraints:Emissions profiles for domestic fermentation facilities face tightening chemical input restrictions, limiting production capacity expansion.
- Grain price volatility:Feed compounders face margin compression when cereal costs spike, reducing discretionary spending on premium additive tiers.
Strategic Opportunities
- Ruminant methane mitigation:Dairy sector investment in metabolic additives creates white space for fermentation-derived alternatives as probiotic categories face potential reclassification under pending EU Feed Additives Regulation revisions.
- Northwestern supply security:Vertical grain-handling infrastructure investments anchor captive additive distribution networks across Normandy and Brittany feed mill clusters.
- Cooperative formulation partnerships:Major agricultural cooperatives seek integrated vitamin and amino acid supply agreements that bundle technical services with ingredient procurement.
Industry Challenges
- Microbial strain certification timelines:ANSM veterinary medicinal product licensing procedures delay market entry for novel probiotic candidates, compressing effective patent windows.
- Fermentation capacity capex requirements:Domestic production of enzyme and amino acid intermediates demands bioreactor investments that mid-scale suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Feed Additives Market |
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,043.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Probiotics, Vitamins, Amino Acids, Minerals Animal Type: Poultry, Swine, Ruminants, Aquaculture, Pet Food Function: Growth Promotion, Immunity Enhancement, Feed Efficiency, Digestive Health, Reproductive Performance Distribution Channel: Veterinary Clinics, Specialized Feed Stores, Online Retailers, Agricultural Cooperatives, Direct Sales |
| Companies Covered | Cargill Incorporated, Alltech, Adisseo, BASF SE, Elanco, ADM, Evonik Industries AG, Novonesis Group, Nutreco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Feed Additives Market Shifts & Advancements
Active reformulation across French livestock nutrition is compressing additive development cycles, with suppliers racing to deliver integrated solutions ahead of regulatory deadlines while feed mills restructure procurement around bundled nutritional architectures.
Enzyme cocktails tailored for wheat-barley-based rations are modularizing how French poultry nutritionists configure grower diets. Large integrated operations in the Pays de la Loire region adopt these precision blends at accelerated pace. The technology is modularizing supplier relationships from transactional ingredient sales toward continuous formulation partnerships.
Pending EU Feed Additives Regulation revisions threaten to reclassify certain probiotic categories as veterinary medicinal products. This regulatory friction redirects R&D investment toward fermentation-derived alternatives and elevates documentation requirements for existing strain portfolios. Dairy and swine segments face the steepest compliance recalibration as ANSM licensing procedures extend evaluation timelines.
Feed mill procurement patterns are consolidating around multi-year premix supply agreements that bundle technical advisory services with volume commitments. Traditional spot-market ingredient purchasing contracts lose share to integrated nutritional service contracts. This behavioral shift concentrates most visibly across Brittany's cooperative-owned compound feed facilities.
France Feed Additives Market Segmentation
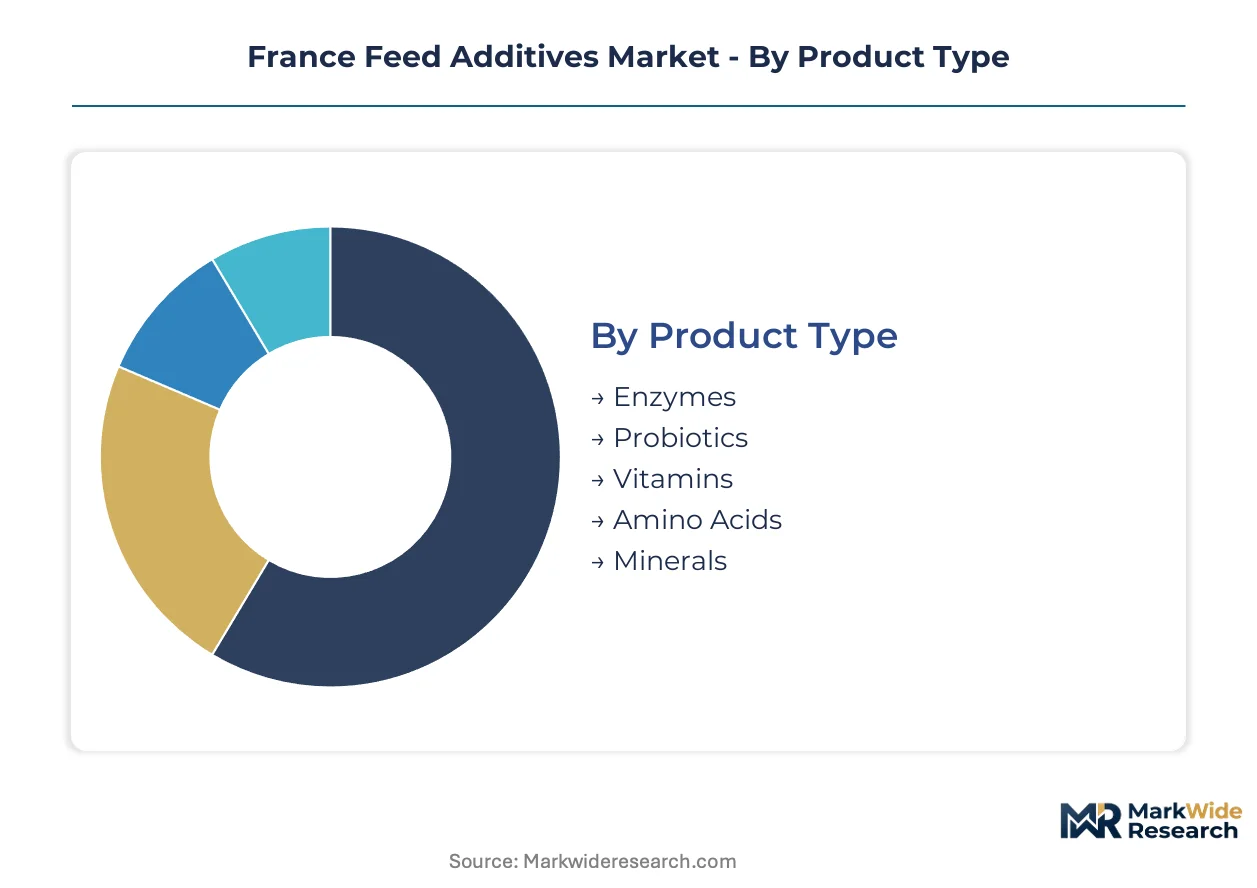
Feed additive procurement in France fragments across nutritional function, target species, and supply chain configuration. Each segmentation dimension reveals distinct margin structures and regulatory exposure profiles that shape supplier strategy.
Product Type:
Volume concentration sits with commodity amino acids and vitamins, while premium capture concentrates in enzyme and probiotic formulations.
- Enzymes:Protein- and carbohydrate-active formulations degrade anti-nutritional factors in wheat-barley-based poultry rations. Brittany's integrated pork operations deploy phytase and xylanase blends at scale to capture phosphorus release value. The EU Green Deal's antibiotic restrictions accelerate substitution demand across swine starter diets.
- Probiotics:Live microbial cultures including Bacillus and Lactobacillus strains colonize the gut microbiome to outcompete pathogenic bacteria. Pending EU Feed Additives Regulation revisions threaten reclassification of certain strains as veterinary medicinal products, compressing ANSM licensing timelines for novel candidates. Dairy methane-mitigation applications represent emerging deployment territory.
- Vitamins:Synthetic A, D, E, and K formulations maintain mature volume positions in premix specifications across all livestock categories.
- Amino Acids:Lysine, methionine, threonine, and tryptophan constitute baseline nutritional requirements in poultry and swine compound feeds.
- Minerals:Organic and inorganic trace element sources address deficiency risks in regional soil profiles.
Mature deployment sits with Amino Acids. Newer deployment is concentrated in Probiotics.
Animal Type:
Poultry and swine absorb the bulk of additive volume, while ruminant applications command premium pricing for metabolic performance solutions.
- Poultry:Broiler and layer operations in Pays de la Loire and Brittany drive standardized enzyme and amino acid consumption. Feed conversion optimization targets dominate procurement specifications.
- Swine:Post-weaning diets in northwestern France face zinc oxide phase-out mandates, redirecting formulation toward acidifier and probiotic alternatives. Sows and finishers maintain distinct additive protocols.
- Ruminants:Dairy cattle operations invest in methane-mitigation additives including 3-nitrooxypropanol and red seaweed derivatives to meet emission reduction commitments. Beef calf rearing applies lower-tier nutritional interventions.
- Aquaculture:Mediterranean and Atlantic fish farming deploys specialized gut health additives for sea bass and trout production systems.
- Pet Food:Premium companion animal nutrition incorporates probiotic and palatability-enhancing ingredients at low inclusion rates.
Volume leadership belongs to Poultry. Premium expansion concentrates in Ruminants.
Function:
Cost-tier differentiation separates baseline growth promotion from premium immunity and metabolic performance positioning.
- Growth Promotion:Traditional antibiotic growth promoters face tightening EU restrictions, displacing volume toward enzyme and acidifier alternatives. Legacy zinc oxide applications in piglet feeds confront usage limits.
- Immunity Enhancement:Beta-glucans, nucleotides, and targeted probiotics strengthen mucosal defense mechanisms. Stress transition periods—weaning, transport, heat events—drive concentrated demand spikes.
- Feed Efficiency:Enzyme cocktails and metabolic modifiers reduce feed conversion ratios in high-volume poultry and swine operations. Marginal cost savings determine adoption thresholds.
- Digestive Health:Acidifiers, prebiotics, and toxin binders stabilize gut microbiome composition. Mycotoxin risk management elevates binder inclusion in humid harvest years.
- Reproductive Performance:Vitamins, minerals, and specific fatty acids target breeding herd productivity in dairy and swine nucleus farms.
Feed Efficiency commands the largest installed base. Immunity Enhancement is climbing the fastest on antibiotic substitution demand.
Distribution Channel:
Supply concentration favors cooperative and direct channels, with digital and clinical routes capturing niche premium segments.
- Agricultural Cooperatives:Brittany and Normandy cooperative-owned feed mills consolidate additive procurement through multi-year premix supply agreements. Technical advisory bundling displaces spot-market transactions.
- Direct Sales:Large integrated livestock operations negotiate captive supply arrangements with Adisseo, BASF, and Cargill for amino acid and vitamin volumes.
- Specialized Feed Stores:Independent retailers serve smaller pork and poultry producers with bagged premix and concentrate offerings.
- Veterinary Clinics:Clinical nutrition products and therapeutic feed additives reach dairy and companion animal segments through practitioner recommendation.
- Online Retailers:Digital platforms capture hobby farmer and pet owner demand for specialty supplements and small-pack probiotics.
Procurement consolidation is reshaping Agricultural Cooperatives. Online Retailers remain peripheral to commercial livestock supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes more feed additives than it manufactures, creating import dependency for specialized enzyme and probiotic strains. Domestic production concentrates in fermentation-derived amino acids and synthetic vitamins. Regional clusters in Brittany and Pays de la Loire absorb the bulk of volume, while regulatory pressure from Brussels reshapes formulation requirements across all member states.
Brittany
Dense pork and poultry production clusters drive bulk additive procurement through cooperative-owned feed mills. The EU Green Deal's antibiotic growth promoter restrictions accelerate enzyme substitution in post-weaning piglet diets. Saint-Brieuc and Rennes anchor northwestern distribution infrastructure for premix suppliers.
Pays de la Loire
Integrated broiler operations deploy precision-formulated enzyme cocktails for wheat-barley-based grower rations. ANSM licensing procedures for novel microbial strains compress development timelines for regional formulators. Cholet and La Roche-sur-Yon concentrate technical advisory services bundled with multi-year supply agreements.
Normandy
Dairy cattle operations invest in methane-mitigation additives to meet emission reduction commitments under the Farm to Fork Strategy. Vertical grain-handling infrastructure anchors captive distribution networks across Caen and Rouen feed mill clusters. Precision premix bundling displaces spot-market transactions.
Auvergne-Rhône-Alpes
Specialized aquaculture feed production for Mediterranean fish farming creates niche demand for gut health additives. The F-Gas Regulation constrains fermentation facility emissions profiles, limiting domestic capacity expansion. Lyon-based formulators serve Rhône Valley trout and sea bass operations.
Hauts-de-France
Beef calf rearing and mixed farming apply lower-tier nutritional interventions compared to northwestern dairy and poultry intensity. REACH documentation burdens for novel microbial strains elevate import barriers, constraining strain diversity. Lille metropolitan area hosts distribution logistics for cross-border Benelux supply.
France Feed Additives Market Competitive Landscape
The competitive structure tilts toward diversified nutrition conglomerates with captive fermentation capacity and cooperative distribution lock-in. Three to five integrated players control amino acid and vitamin volume positions, while mid-scale specialists compete on probiotic strain differentiation and technical advisory bundling. Strategic archetypes include vertical grain-handlers extending into premix formulation, fermentation-based specialists anchoring ruminant nutrition, and synthetic vitamin producers sustaining cooperative partnerships. Capacity expansion and multi-year premix supply agreements represent the dominant competitive moves, displacing traditional spot-market ingredient sales.
Among the diversified nutrition conglomerates, Cargill Incorporated anchors supply security through northwestern grain-handling infrastructure. Adisseo occupies a position exemplifying fermentation-derived specialization in methionine and enzyme formulations. BASF SE represents synthetic vitamin portfolio breadth sustaining formulation partnerships with major cooperatives. These three players illustrate how competitive positioning fragments across upstream raw material control, biotechnological specialization, and chemical synthesis scale.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Alltech |
| Adisseo |
| BASF SE |
| Elanco |
| ADM |
| Evonik Industries AG |
| Novonesis Group |
| Nutreco |
| Others |
Supply & Pricing Matrix
Fermentation-derived amino acid intermediates trace from upstream bioreactor energy costs through contract-based long-term offtake structures to downstream cooperative procurement tiers. Grain price volatility feeds directly into feed compounder margin compression, forcing discretionary cuts to premium additive categories when cereal costs spike.
Pricing Analysis
Cost-down pressure on standard-tier enzyme formulations accelerates because REACH documentation burdens for novel microbial strains constrain strain diversity and intensify supplier competition. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived specialty probiotics from commodity synthetic vitamins and baseline mineral premixes. Price differentiation hinges on certification grade for ANSM veterinary licensing and volume scale through cooperative bundling agreements. Small independent pork producers in Brittany exhibit highest price sensitivity, while integrated dairy operations in Normandy absorb premium methane-mitigation additive costs.
Supply Chain Analysis
REACH certification gating for novel microbial strains elevates import barriers and concentrates viable supply among established EU fermentation facilities. France draws from domestic synthetic vitamin production, Dutch enzyme formulation expertise, and German amino acid intermediate supply. Raw material dependencies center on corn-derived fermentation substrates, phosphate rock for mineral premixes, and specialized bacterial culture stocks. Single-source vulnerability sits with fermentation capacity for methionine and lysine. Distribution runs through cooperative-owned feed mill clusters in Brittany and Normandy, anchored by vertical grain-handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France feed additives occupy a technology-transition phase where enzyme cocktails and probiotic alternatives displace legacy antibiotic growth promoters under EU Green Deal mandates. Precision-formulated premix architectures are replacing single-ingredient procurement across compound feed operations.
For Market Incumbents: Acquire captive fermentation capacity in northwestern France to secure supply continuity as F-Gas Regulation constraints tighten domestic production emissions profiles. Anchor multi-year premix supply agreements with Brittany cooperative feed mills to lock in volume commitments against emerging biotech entrants. Deepen backward integration into grain-handling infrastructure across Normandy distribution nodes.
For New Entrants and Emerging Players: EU Green Deal antibiotic restrictions in France open a window for novel methane-mitigation additive development targeting Normandy dairy cooperatives. White space concentrates in ruminant metabolic performance solutions where incumbent portfolios remain underdeveloped. Pursue ANSM licensing partnerships with established fermentation facilities to compress regulatory timelines. Target Pays de la Loire poultry integrators with wheat-barley-specific enzyme formulations.
For Investors and Strategic Acquirers: Pending EU Feed Additives Regulation revisions are the leading indicator that probiotic reclassification risk will concentrate value in fermentation-derived alternative platforms. Long-term viability favors suppliers with captive bioreactor capacity and cooperative distribution lock-in across the analysis window. Acquisition target archetype: mid-scale enzyme specialists with ANSM-approved strain portfolios and technical advisory bundling capabilities. Watch for ANSM licensing timeline extensions as signal of regulatory friction intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive bioreactor investment secures methionine supply continuity under F-Gas constraints. |
| Cooperative Premix Partnership | Multi-year technical service bundling displaces spot-market transactions in Brittany feed mills. |
| ANSM Regulatory Pathway Investment | Novel probiotic strain certification compresses development timelines against reclassification risk. |
| Backward Integration into Grain Handling | Vertical infrastructure control anchors distribution security across northwestern France. |
| Ruminant Methane-Mitigation R&D | Fermentation-derived 3-nitrooxypropanol alternatives capture dairy sector emission reduction investment. |
Research Methodology
Independent corroboration across primary interviews with compound feed mill procurement directors, ANSM regulatory affairs specialists, cooperative technical service managers, and fermentation facility operations heads underwrites the qualitative findings. Secondary validation draws from EU Feed Additives Regulation amendment drafts, ANSM veterinary medicinal product licensing databases, French customs trade data for amino acid imports, and SEC filings of listed nutrition conglomerates. Bottom-up volume modeling across Brittany, Pays de la Loire, and Normandy regional clusters triangulates against top-down macroeconomic feed consumption projections.
Comparable-period anchoring to historical premix procurement patterns and antibiotic substitution adoption curves structures the forecast framework across the projection horizon. Segmentation dimensions modeled include product type tier, animal species application, functional benefit positioning, and distribution channel configuration. CAGRs derive from regression analysis of additive inclusion rate trends against livestock production volume forecasts. Industry-specific inputs incorporate EU Green Deal implementation timelines and ANSM licensing procedure duration estimates.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived methane inhibitors would alter the outlook if breakthrough efficacy data accelerates dairy sector conversion. Forecasts reflect assumptions regarding regulatory implementation pacing and cooperative procurement consolidation trajectories. A model refresh is warranted upon material change in EU Feed Additives Regulation final text or ANSM licensing procedure restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market