
 Food Antimicrobial Additives Market | 2026-2036
Food Antimicrobial Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Food Antimicrobial Additives Market Foresight
Asset-light toll manufacturing and third-party bioprocessing partnerships are rewriting competitive entry economics in food antimicrobials. Chr. Hansen Holding A/S leverages its fermentation expertise to dominate live culture-derived bacteriocin supply. Kerry Group anchors its position through backward integration into dairy-derived antimicrobial peptide extraction. Corbion competes via specialized organic acid blends for meat preservation applications.
Food antimicrobial additives comprise biologically active or chemically synthesized substances incorporated at parts-per-million to percent-level concentrations to inhibit bacterial, fungal, or yeast proliferation in processed foods. Their primary commercial purpose centers on shelf-life extension and pathogen control without thermal degradation of nutritional or sensory properties. Organic acids maintain the largest volume share due to established cost structures and broad pH efficacy ranges, while bacteriocins represent the fastest-expanding category driven by label-friendly positioning and targeted anti-listerial activity. Natural extracts and essential oils concentrate margin pools where premium positioning commands formulation premiums in clean-label bakery and beverage segments.
The FDA governs antimicrobial food contact substances under the Food Contact Notification program, while EFSA evaluates safety of active substances under EU regulation 1333/2008 on food additives, and the FSSAI in India mandates BIS-compliant purity specifications for imported antimicrobial formulations. These frameworks shape demand by determining which chemistries gain market access and which require costly toxicological dossiers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and supply chain requalification requirements.
Market Dynamics
Clean-label mandates from major retailers are compressing synthetic preservative demand while bacteriocin fermentation capacity struggles to scale. This tension between formulation preference and bioprocessing constraints defines current competitive positioning.
Growth Catalysts
- EFSA Regulation 1333/2008 revisions:Tightened purity specifications for synthetic additives accelerate natural antimicrobial substitution in EU dairy applications.
- Meat processing automation:Continuous thermal processing lines require non-heat-labile antimicrobials, expanding organic acid blend demand.
- China's food safety investment wave:Provincial governments in Shandong and Henan deploy antimicrobial intervention systems across pork and poultry slaughter facilities.
Market Restraints
- Nisin supply concentration:Fermentation-based bacteriocin output clusters with Danish and Dutch bioprocessing specialists, creating single-source vulnerability.
- Clean-label cost premium:Natural extract formulations carry 40-60% raw material cost elevation versus synthetic benzoates and sorbates.
- pH efficacy windows:Organic acid antimicrobial activity collapses above pH 5.5, restricting application in neutral pH beverages and emulsified products.
Strategic Opportunities
- India FSSAI clean-label pathway:Regulatory clarity on natural antimicrobial definitions opens formulation services market for imported bacteriocin blends.
- Active packaging convergence:Integration of antimicrobial films with controlled-release edible coatings creates dual-function shelf-life extension systems.
- Plant-based protein segments:High-moisture extruded meat alternatives lack thermal pasteurization margins, demanding novel antifungal solutions.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with GMP bioprocessing experience command premium compensation in food versus pharma sectors.
- Toxicological dossier timelines:Novel antimicrobial submissions to FDA Food Contact Notification program face 18-24 month evaluation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Antimicrobial Additives Market |
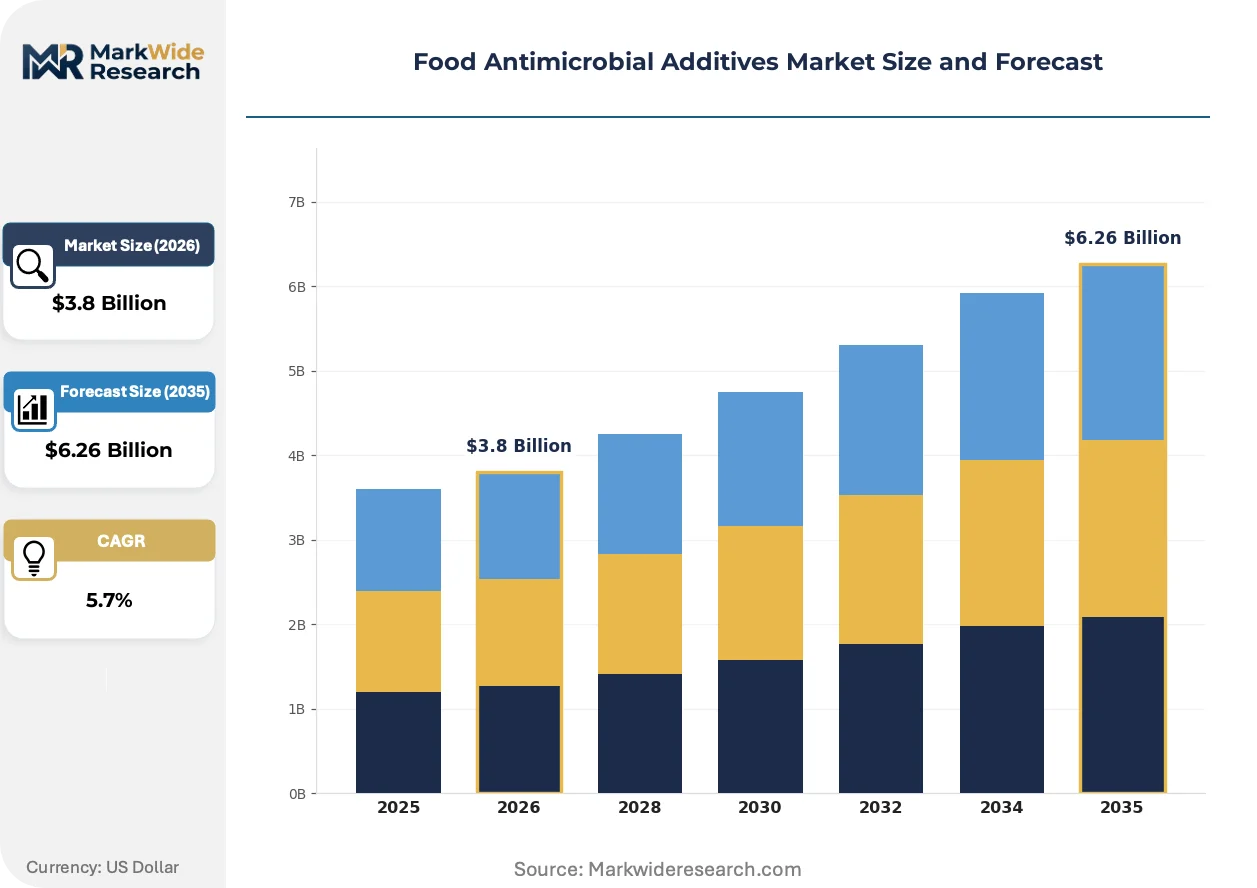
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Organic Acids, Enzymes, Bacteriocins, Essential Oils Application: Meat & Poultry, Dairy Products, Bakery Goods, Beverages, Seafood Form: Liquid, Powder, Granules, Emulsions, Capsules End User: Food Processing Companies, Beverage Manufacturers, Animal Feed Producers, Nutraceutical Firms |
| Companies Covered | Archer Daniels Midland Company, Kerry Group, Corbion, International Flavors & Fragrances, Cargill Corporation, BASF SE, Chr. Hansen Holding A/S, Tate & Lyle, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Antimicrobial Additives Market Shifts & Advancements
Biopreservation technologies are crossing from artisan dairy into industrial meat and bakery applications. This diffusion pattern reconfigures supplier relationships and technical service requirements across conventional additive categories.
Continuous fermentation systems with real-time metabolite monitoring are rendering obsolete batch-mode nisin production. Pork processors in the Midwest United States adopt these higher-potency concentrates for post-lethality surface treatments. The technology is rendering obsolete capital-intensive stainless steel bioreactor farms that dominated 1990s bacteriocin supply.
REACH authorization requirements for residual formaldehyde in food-contact materials tighten detection thresholds for certain organic acid salts. ECHA evaluations now demand migration studies for antimicrobial-incorporated casings and films. German sausage manufacturers accelerate shift toward fermentation-derived alternatives to maintain single-market compliance without dual formulation inventories.
Retail buyer consolidation into centralized technical procurement functions compresses supplier rosters and extends qualification timelines. Walmart and Carrefour now mandate antimicrobial additive disclosure at ingredient-sourcing stage, not finished-product certification. This pattern concentrates contract volume with integrated formulation houses capable of cross-category regulatory dossier management.
Food Antimicrobial Additives Market Segmentation
Antimicrobial additive selection hinges on pH compatibility, thermal stability, and clean-label positioning. Formulators balance regulatory clearance timelines against end-use processing conditions. Segment concentration patterns reveal where technical service investments yield highest returns.
Product Type:
Cycle times vary dramatically across chemistries. Organic acids turn inventory monthly through commodity meat channels. Bacteriocin fermentation batches stretch six to eight weeks from inoculation to release testing.
- Natural Extracts:Rosemary, green tea, and grape seed polyphenols deliver broad-spectrum antioxidant-antimicrobial synergy. Premium bakery and beverage applications in Germany absorb concentrated extracts despite 40% cost premiums over synthetic alternatives. Clean-label mandates from Rewe and Edeka accelerate substitution timelines.
- Organic Acids:Propionic, sorbic, and benzoic acid salts constitute the volume foundation. Lactic acid blends dominate U.S. pork and poultry surface interventions. Cost structures and established FDA GRAS status sustain penetration despite pH efficacy limitations above 5.5.
- Enzymes:Glucose oxidase and lysozyme preparations target niche dairy and egg applications.
- Bacteriocins:Nisin and pediocin fermentation concentrates command premium positioning.
- Essential Oils:Thymol, carvacrol, and eugenol formulations concentrate in organic-certified meat segments.
Organic acids dominate installed base. Bacteriocins are where expansion concentrates.
Application:
Margin structures diverge sharply by processing intensity and pathogen regulatory scrutiny. Thermal lethality exemptions in ready-to-eat categories drive antimicrobial dependence.
- Meat & Poultry:Post-lethality surface treatments against Listeria monocytogenes absorb the highest antimicrobial dosing rates per ton. USDA-FSIS compliance verification requirements lock in multi-hurdle formulations. Midwest U.S. processors adopt continuous organic acid spray systems with real-time concentration monitoring.
- Dairy Products:Cheese and yogurt applications favor live culture bacteriocins for label-friendly positioning. EFSA Regulation 1333/2008 purity revisions accelerate natural antimicrobial substitution in French and Italian premium cheese segments.
- Bakery Goods:Mold inhibition in extended-shelf-life bread drives propionate demand.
- Beverages:pH-neutral formulations limit organic acid utility.
- Seafood:Histamine control and gram-negative spoilage organisms require specialized blends.
Meat & Poultry commands formulation complexity. Dairy Products are gaining share fastest.
Form:
Dispersion requirements and processing equipment compatibility dictate form selection. Automated dosing systems favor pumpable liquids. Powder handling dominates batch-compounding environments.
- Liquid:Pumpable concentrates integrate with continuous processing lines. Automated metering systems in U.S. and Chinese meat plants reduce dosing variability. Post-lethality spray cabinets and chill tank interventions specify liquid delivery.
- Powder:Free-flowing salts suit dry-mix bakery and seasoning applications. Extended shelf stability simplifies inventory management for small and mid-sized processors.
- Granules:Dust-free handling properties serve high-volume feed and premix operations.
- Emulsions:Oil-in-water systems target fat-containing matrices.
- Capsules:Controlled-release formats concentrate in active packaging films.
Powder dominates installed base. Liquid is where expansion concentrates.
End User:
Procurement sophistication separates integrated multinationals from regional processors. Technical service demands scale with formulation complexity and regulatory filing obligations.
- Food Processing Companies:Integrated meat and dairy processors wield specification authority over additive suppliers. Walmart and Carrefour centralized procurement functions compress qualified supplier rosters. Cross-category regulatory dossier management capabilities determine contract awards.
- Beverage Manufacturers:pH-neutral formulation constraints limit antimicrobial options. Clean-label pressure from premium positioning drives natural extract evaluation despite efficacy challenges.
- Animal Feed Producers:Mycotoxin binders and gut health additives overlap with food antimicrobial supply chains.
- Nutraceutical Firms:Probiotic compatibility requirements restrict antimicrobial co-formulation.
Food Processing Companies dominate installed base. Beverage Manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated meat and dairy processors in the United States, Germany, and China command the largest antimicrobial additive procurement volumes. Retail buyer consolidation into centralized technical procurement functions compresses supplier rosters across all three markets. Provincial investment programs and regulatory tightening accelerate substitution timelines in each jurisdiction.
United States
Midwest pork and poultry processors deploy continuous organic acid spray systems with real-time concentration monitoring for post-lethality Listeria control. USDA-FSIS compliance verification requirements lock in multi-hurdle formulations across slaughter facilities. Chicago and Des Moines processing corridors absorb the highest antimicrobial dosing rates per ton in ready-to-eat meat categories.
Germany
EFSA Regulation 1333/2008 purity revisions accelerate natural antimicrobial substitution in premium cheese segments. ECHA evaluations now demand migration studies for antimicrobial-incorporated casings and films. Bavarian sausage manufacturers shift toward fermentation-derived alternatives to maintain single-market compliance without dual formulation inventories.
China
Provincial governments in Shandong and Henan deploy antimicrobial intervention systems across pork and poultry slaughter facilities. SAMR tightening of residue limits drives substitution toward label-friendly bacteriocin formulations. Yangtze River Delta food safety investment wave concentrates demand in Shanghai-Ningbo processing clusters.
India
FSSAI clean-label pathway regulatory clarity opens formulation services market for imported bacteriocin blends. BIS-compliant purity specifications for imported antimicrobial formulations reshape supply chain qualification requirements. Maharashtra and Gujarat dairy processors expand natural extract programs under retailer pressure from Reliance and BigBasket.
Food Antimicrobial Additives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement tiers. Integrated multinationals wield specification authority over additive suppliers through centralized technical procurement functions. Three archetypes dominate: fermentation-based bioprocessing specialists, backward-integrated dairy extract processors, and organic acid blend formulators. Capacity expansion in continuous fermentation systems and strategic partnerships for toll manufacturing represent the dominant competitive moves.
Within the fermentation-specialist tier, Chr. Hansen Holding A/S and Kerry Group occupy positions anchored by bioprocessing expertise and dairy-derived supply chains respectively. Corbion exemplifies the organic acid blend formulator archetype. These three entities represent the competitive anchors around which procurement consolidation patterns organize.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kerry Group |
| Corbion |
| International Flavors & Fragrances |
| Cargill Corporation |
| BASF SE |
| Chr. Hansen Holding A/S |
| Tate & Lyle |
| Ingredion |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors govern landed costs for fermentation-derived bacteriocins, concentrating margin pressure on suppliers distant from European dairy processing clusters while enabling price premiums for clean-label organic acid blends in German retail channels.
Pricing Analysis
Cost-plus contracts with lactose and dextrose feedstock indexation dominate bacteriocin supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates nisin concentrates from pediocin blends and commodity organic acid salts. Price differentiation rests on fermentation potency certification and EFSA compliance documentation. Cost compression in synthetic benzoate tiers is intensifying because of clean-label substitution, while dairy processors show least price sensitivity for live-culture bacteriocins.
Supply Chain Analysis
Toll manufacturing capacity clusters with Danish and Dutch fermentation specialists holding GMP-certified bioreactor networks. Raw material sourcing draws from Brazilian sugarcane dextrose, Ukrainian whey permeate, and Indian spice extract supply chains. Single-source vulnerability in nisin fermentation creates supply chain risk. Distribution runs through integrated formulation houses capable of cross-category regulatory dossier management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Walmart and Carrefour centralized technical procurement functions, fragmenting supplier rosters and extending qualification timelines for antimicrobial additive vendors.
For Market Incumbents: Insulate formulation margins by securing captive lactose supply through backward integration into dairy processing streams. Expand continuous fermentation capacity in Iowa and Shandong to offset Danish supply concentration. Lock in multi-year EFSA dossier management contracts with premium cheese processors before regulatory clarity hardens.
For New Entrants and Emerging Players: Establish a beachhead in India FSSAI clean-label pathway services before imported bacteriocin blend qualification requirements tighten. Target toll manufacturing partnerships with Midwest pork processors seeking post-lethality spray system integration. Lead with organic acid blend customization for automated dosing equipment compatibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fermentation assets and stranded organic acid production capacity. Long-term viability favors specialists with regulatory dossier depth across FDA, EFSA, and SAMR jurisdictions. Watch for SAMR residue limit tightening as inflection signal for natural antimicrobial substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Real-time metabolite monitoring renders batch-mode nisin production obsolete in Midwest pork processing. |
| Backward Integration into Dairy Streams | Kerry Group's captive whey permeate supply anchors cost position in bacteriocin peptide extraction. |
| EFSA Dossier Management Services | Cross-category regulatory expertise determines contract awards from Rewe and Edeka procurement functions. |
| Toll Manufacturing Partnerships | Asset-light bioprocessing entry rewrites competitive economics for fermentation-based antimicrobial supply. |
| Active Packaging Convergence | Antimicrobial film integration with edible coatings creates dual-function shelf-life extension in German sausage segments. |
Research Methodology
Desk research of FDA Food Contact Notification filings, EFSA scientific opinions, and SAMR residue limit announcements preceded structured interviews with dairy processing executives, meat plant technical directors, and retail category buyers. Secondary validation drew from USDA-FSIS compliance data, EU TRACES import records, and Chinese provincial food safety investment disclosures. Bottom-up volume modeling triangulated against top-down procurement spend analysis across the analysis window.
Assumptions held fixed include EFSA Regulation 1333/2008 purity specifications and USDA-FSIS Listeria control mandates; variables tested included fermentation yield improvements and clean-label substitution elasticities. Segmentation dimensions spanned product chemistry, application processing intensity, form factor compatibility, and end-user procurement sophistication. CAGRs derived from iterative convergence of supply-side capacity expansion and demand-side regulatory compliance requirements.
Stress conditions across nisin fermentation batch failure rates, lactose feedstock price volatility, and EFSA evaluation timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of SAMR residue limit announcements and Walmart supplier roster compressions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Global Flaked Shortenings Market