
 Global Food Anti Caking Agents Market | 2026-2036
Global Food Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Anti Caking Agents Market Foresight
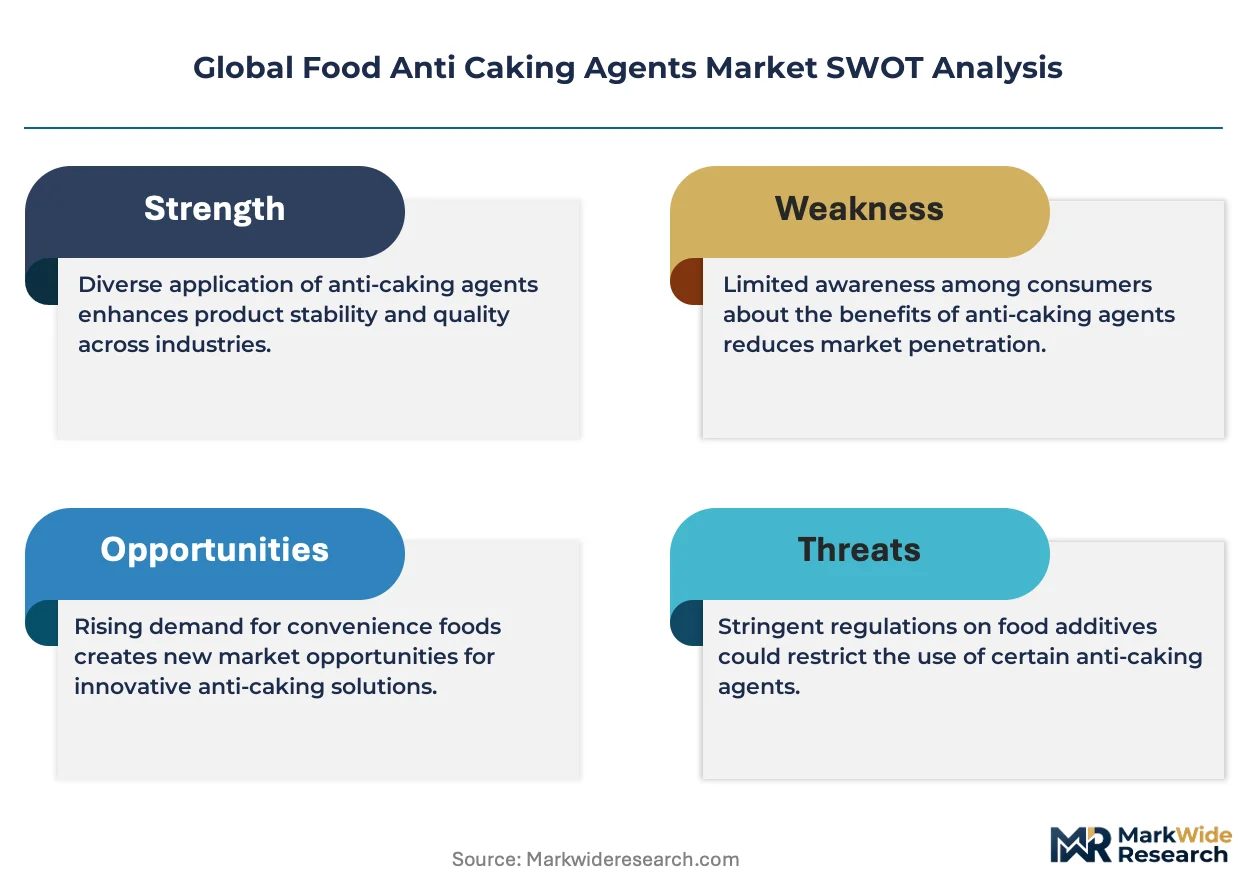
EU REACH is rebalancing the cost-of-entry calculus for anti-caking agent suppliers entering European markets. BASF SE leverages its integrated chemical manufacturing base to sustain compliance with evolving purity specifications. Kerry Group plc anchors its position through specialized formulation services that navigate regional additive approval pathways.
Food anti-caking agents are powdered or granular substances, typically composed of silicates, phosphates, or carbonates, that prevent particle agglomeration by absorbing moisture or coating surfaces to reduce interparticle friction. These materials maintain free-flow properties in hygroscopic food powders at inclusion rates generally below 2% by weight, ensuring consistent dosing and appearance in processed foods. Calcium silicate dominates product type supply due to its broad regulatory acceptance and cost efficiency in salt and baking powder applications. Silicon dioxide competes in premium segments where amorphous structure and ultra-fine particle size command higher specification premiums. Seasoning manufacturers represent the fastest-growing end user category as global spice blend consumption shifts toward pre-mixed, shelf-stable formats.
FDA, EFSA, and FSSAI collectively govern additive safety assessments, with each jurisdiction imposing distinct purity thresholds and labeling mandates that fragment product registration requirements. ISO standards for food-grade silicates provide a baseline for cross-border manufacturing consistency, though national deviations in heavy metal limits force recipe localization. Stakeholders must monitor divergence between EU Green Deal chemical hazard reclassifications and legacy FDA GRAS determinations to anticipate reformulation obligations.
Market Dynamics
Clean-label reformulations are compressing the acceptable ingredient palette for anti-caking agents, forcing manufacturers to retire legacy silicate variants and recertify replacements under divergent national purity regimes.
Growth Catalysts
- FSSAI-mandated additive standards:India's food safety regulator is accelerating domestic production of silicon dioxide and calcium silicate variants through mandatory compliance deadlines for imported seasoning blends.
- Pre-mixed spice consumption:Seasoning manufacturers in the United States are expanding procurement volumes as shelf-stable convenience formats displace bulk spice purchasing in retail and foodservice channels.
- EU Green Deal chemical hazard reclassifications:Tightening safety requirements are reshaping ingredient compliance costs, creating first-mover advantages for suppliers with integrated purity testing capabilities.
Market Restraints
- Input cost volatility in precipitated silicates:Sodium silicate feedstock prices fluctuate with energy costs, compressing margins for non-integrated manufacturers.
- Supply concentration in Chinese amorphous silica:A limited number of coastal producers control ultra-fine particle grade output, exposing buyers to single-source risk.
- Technical limitation in organic alternatives:Rice hull ash and cellulose derivatives lack the moisture absorption efficiency of synthetic silicates above 60% relative humidity.
Strategic Opportunities
- Underpenetrated geography:Nigerian seasoning processors face limited local anti-caking agent supply, creating openings for regional blending facilities with captive silicate production.
- Regulatory tailwind:Brazil's ANVISA is streamlining food additive approval timelines, reducing registration lag for novel phosphate-free formulations.
- Technology convergence:Encapsulation technologies combining modified starches with nano-silicates are enabling dual-function ingredients that simplify clean-label declarations.
Industry Challenges
- Certification timeline compression:Dual-track FDA GRAS self-determination and EFSA full scientific opinion processes now run in parallel, straining regulatory affairs staffing.
- Integration complexity with legacy dosing equipment:Ultra-fine particle size variants require pneumatic system recalibration, delaying production line conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Anti Caking Agents Market |
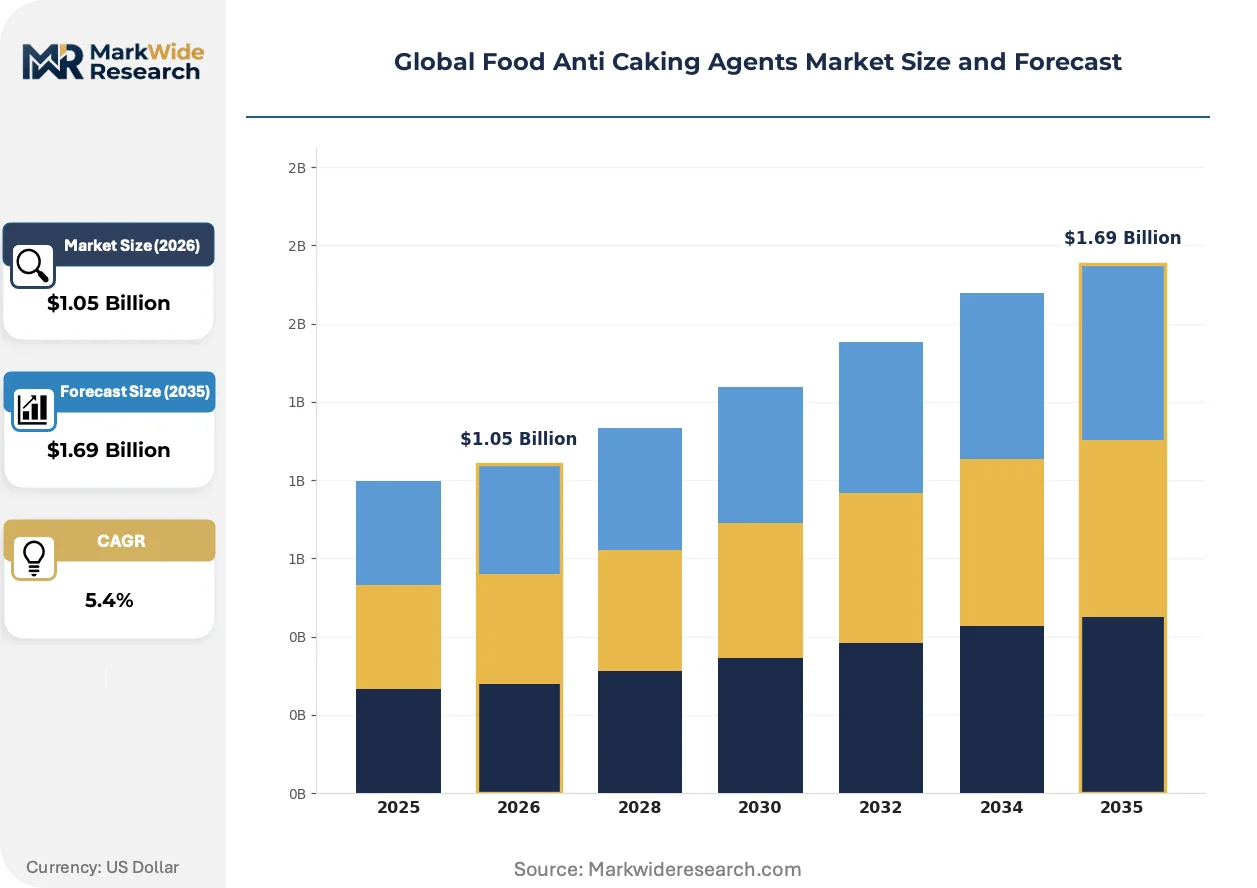
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Silicate, Magnesium Carbonate, Silicon Dioxide, Tricalcium Phosphate, Talc Application: Salt, Baking Powder, Spices, Sugar, Cheese Powder, Beverage Mix End User: Food Processing Units, Seasoning Manufacturers, Dairy Product Makers, Beverage Producers Packaging Type: Primary Packaging, Bulk Bags, Sachets, Drum Containers, Pouches |
| Companies Covered | Kerry Group plc, BASF SE, Cargill, Incorporated, Tate & Lyle PLC, Corbion N.V., Archer-Daniels-Midland Company, International Flavors & Fragrances Inc., Kemin Industries, Inc., Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Anti Caking Agents Market Shifts & Advancements
Anti-caking agent development is pivoting from commodity silicate supply toward engineered particle architectures that satisfy simultaneous demands for flow performance, label transparency, and regional regulatory alignment.
Modified rice starch blends are expanding into premium seasoning applications where clean-label positioning commands formulation priority. European organic spice processors are adopting these systems at accelerated rates despite 15-20% cost premiums over conventional silicates. The technology is expanding into salt replacement categories previously closed to synthetic additives, compressing the addressable market for traditional calcium silicate in health-positioned products.
REACH authorization requirements for synthetic amorphous silica are tightening occupational exposure documentation across EU manufacturing sites. Industrial consequence includes mandatory workplace monitoring investments that favor larger integrated producers over toll manufacturers. Seasoning exporters to Germany and France are consolidating supplier bases to reduce audit burden, privileging partners with certified in-house toxicology testing.
Buyer concentration among multinational seasoning houses is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Mid-sized regional blenders in India and Mexico are responding by forming purchasing cooperatives to retain volume leverage. This pattern is most visible in the United States, where three seasoning processors now account for the majority of silicon dioxide procurement in the retail channel.
Global Food Anti Caking Agents Market Segmentation
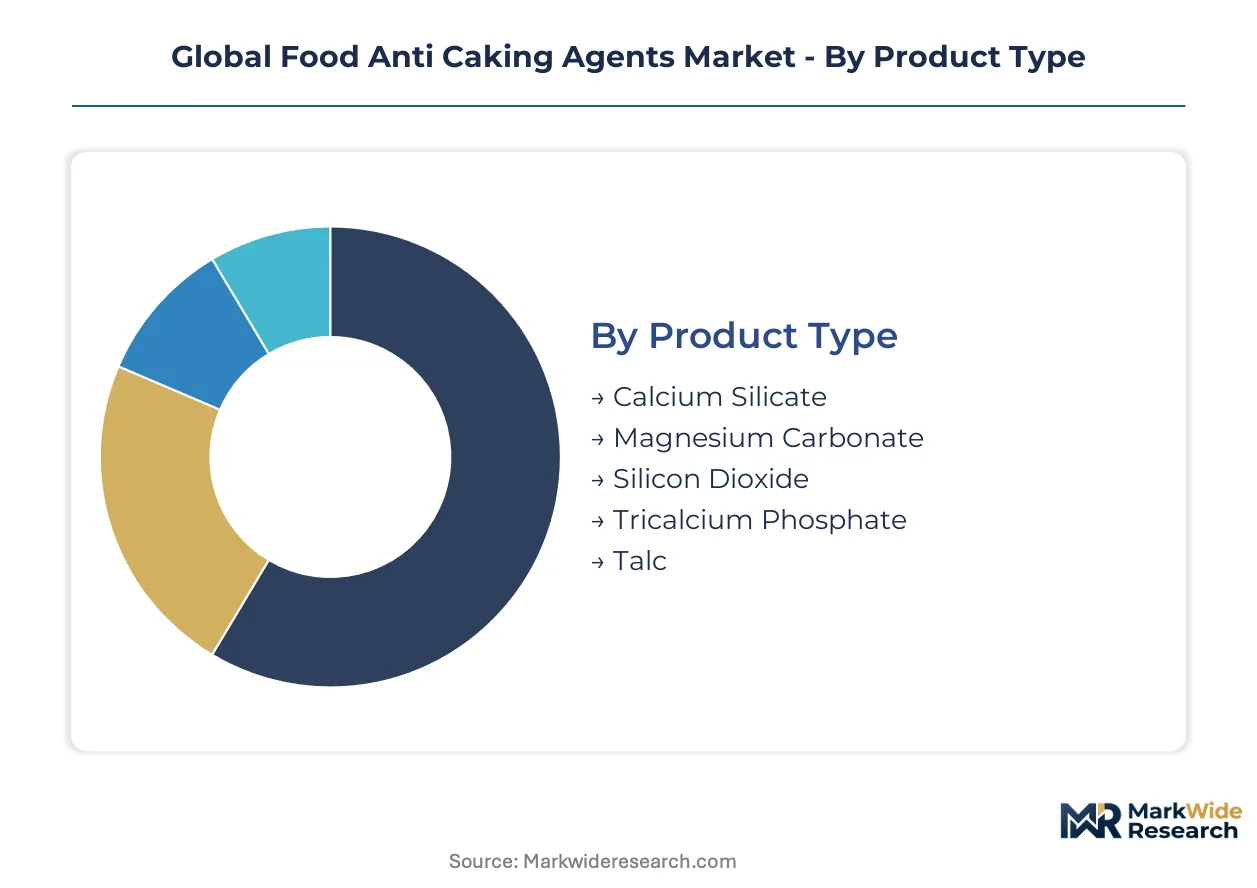
Anti-caking agent specifications fragment sharply across food categories, with moisture sensitivity and regulatory thresholds dictating material selection. Manufacturers configure product portfolios around these technical boundaries rather than pursuing universal formulations.
Product Type:
Standardization dominates commodity silicates while premium grades demand particle engineering precision.
- Calcium Silicate:Hydrated calcium silicate absorbs moisture through porous crystalline structure, maintaining flow in hygroscopic salt and leavening systems. Salt processors in India and baking powder manufacturers in the United States concentrate procurement here due to FSSAI and FDA GRAS alignment. Most installed capacity flows through Calcium Silicate. Expansion is steepest in Silicon Dioxide.
- Silicon Dioxide:Amorphous nano-structured silica delivers ultra-fine particle distribution for seasoning applications where transparency and minimal inclusion rates matter. European organic spice blenders and U.S. clean-label seasoning houses drive specification premiums above 40% over standard silicates.
- Magnesium Carbonate:Basic magnesium carbonate provides alkaline pH buffering alongside anti-caking function in cocoa and chocolate powder applications.
- Tricalcium Phosphate:Tribasic calcium phosphate offers dual functionality as calcium fortification source and flow agent in nutritional beverage powders.
- Talc:Purified magnesium silicate serves niche cheese powder and confectionery coating applications where lubricity requirements exceed moisture absorption needs.
Calcium silicate absorbs the majority of production volume. Silicon dioxide commands the steepest price escalation trajectory.
Application:
Volume concentration separates commodity salt from formulation-intensive seasoning blends.
- Salt:De-icing and food-grade salt manufacturers consume calcium silicate at inclusion rates of 0.5-2.0% to prevent caking in high-humidity storage. Indian salt refiners and U.S. bulk salt distributors anchor this segment's procurement scale.
- Spices:Ground chili, turmeric, and masala blends require sub-micron silica or modified starch systems to maintain color stability and flow. Seasoning manufacturers in the United States and ethnic food processors in Germany are displacing bulk spice purchases with pre-mixed formats.
- Baking Powder:Dual-action leavening systems incorporate calcium silicate to prevent premature acid-base reaction during storage.
- Sugar:Powdered and brown sugar applications use minimal inclusion rates given lower hygroscopicity versus salt.
- Cheese Powder:High-fat dairy powders demand specialized coating agents to prevent lipid oxidation alongside caking.
- Beverage Mix:Instant coffee, cocoa, and malted drink powders prioritize solubility compatibility over maximum flow performance.
Salt applications consume the largest absolute tonnage. Spice applications are expanding most quickly.
End User:
Direct manufacturing integration separates high-volume processors from outsourced seasoning specialists.
- Seasoning Manufacturers:Contract blenders and branded spice houses specify anti-caking agents based on customer clean-label requirements and retail channel positioning. Three U.S. seasoning processors now account for the majority of silicon dioxide procurement in North American retail.
- Food Processing Units:Cereal, soup, and sauce manufacturers source anti-caking agents as part of broader ingredient procurement systems with limited technical specification involvement.
- Dairy Product Makers:Cheese powder and infant formula producers face stringent purity documentation requirements for calcium and magnesium-based flow agents.
- Beverage Producers:Instant drink manufacturers prioritize solubility performance and clarity in finished beverage over maximum flow characteristics.
Food processing units represent the largest volume absorption. Seasoning manufacturers are gaining share fastest.
Packaging Type:
Supply chain position determines packaging complexity from production line to end-use dosing.
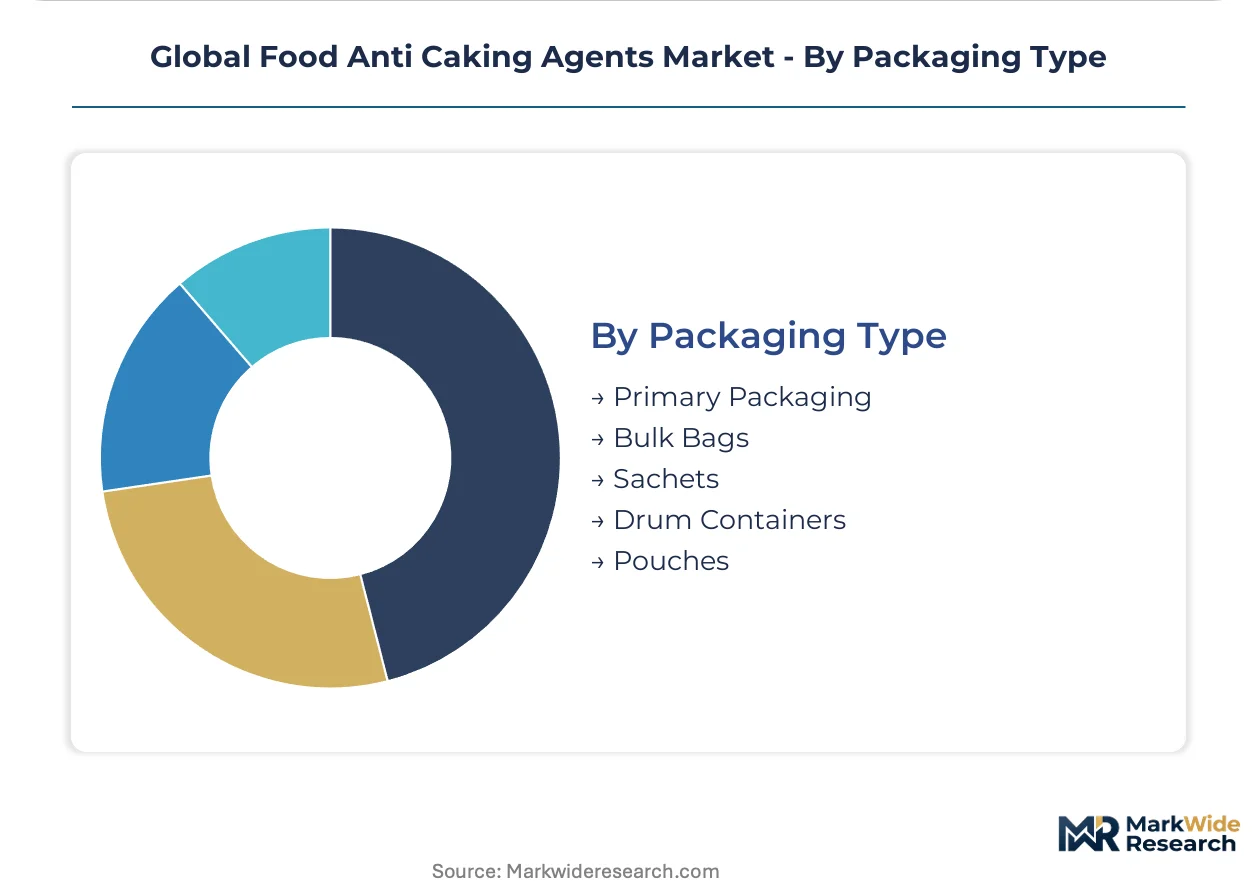
- Bulk Bags:One-ton flexible intermediate bulk containers serve salt refiners and large seasoning houses with pneumatic conveying systems and automated dosing.
- Drum Containers:Steel and fiber drums with nitrogen flushing protect hygroscopic silica grades for pharmaceutical-adjacent food applications.
- Primary Packaging:Direct-fill bottles and jars for retail salt and baking powder incorporate anti-caking agents during manufacturing rather than separate additive procurement.
- Sachets:Single-use foil pouches serve foodservice and airline catering segments with precise portion control.
- Pouches:Stand-up and flat pouches for mid-volume seasoning manufacturers bridge bulk and sachet formats.
Bulk bags carry the majority of material volume. Sachet formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemists and food technologists cluster around industrial salt basins and seasoning manufacturing corridors. Their concentration determines regional formulation capabilities and regulatory compliance infrastructure.
United States
Pre-mixed spice consumption and clean-label reformulations drive procurement expansion among seasoning manufacturers. FDA GRAS determinations govern silicon dioxide and calcium silicate approvals with distinct purity thresholds. Chicago and New Jersey host the largest seasoning processing clusters, where three processors now account for the majority of retail channel silicon dioxide procurement.
Germany
EU Green Deal chemical hazard reclassifications are reshaping compliance cost structures for anti-caking agent suppliers. ECHA REACH authorization requirements mandate occupational exposure documentation and workplace monitoring investments. The Rhine-Ruhr industrial corridor concentrates integrated chemical producers with certified in-house toxicology testing capabilities.
India
FSSAI-mandated food additive standards are accelerating domestic production of silicon dioxide and calcium silicate variants for seasoning blend compliance. Mandatory deadlines for imported spice mixtures force localization of anti-caking agent supply. Gujarat and Maharashtra salt refiners anchor calcium silicate consumption, while Bangalore seasoning processors drive silicon dioxide specification premiums.
Brazil
ANVISA streamlining of food additive approval timelines reduces registration lag for novel phosphate-free formulations. Seasoning processors in São Paulo and Minas Gerais seek regional blending facilities with captive silicate production. The absence of local ultra-fine particle grade manufacturing exposes buyers to import dependency.
China
Coastal producers control ultra-fine amorphous silica output for premium seasoning applications, creating single-source risk for international buyers. GB standards for food-grade silicates provide manufacturing baselines with deviations in heavy metal limits forcing recipe localization. Shandong and Jiangsu provinces concentrate precipitated silicate capacity tied to sodium silicate feedstock economics.
Global Food Anti Caking Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation-intensive and commodity supply tiers. The market structure consolidates around integrated chemical manufacturers with captive raw material positions and toll processors serving regional seasoning houses. Three archetypes dominate: multinational ingredient houses with regulatory affairs depth, regional silicate producers with cost-advantaged feedstock access, and specialized formulation service providers navigating clean-label transitions. Capacity expansion and portfolio diversification toward engineered particle architectures represent the dominant competitive moves.
Among diversified conglomerates, BASF SE exemplifies integrated chemical manufacturing with compliance infrastructure spanning multiple purity regimes. Kerry Group plc occupies a position as a formulation service specialist with regional additive approval expertise. Cargill, Incorporated anchors the agricultural-originated tier with backward integration into commodity salt and seasoning supply chains. These three represent distinct strategic postures: chemical synthesis depth, technical service intensity, and agricultural raw material control.
| Leading Market Players |
|---|
| Kerry Group plc |
| BASF SE |
| Cargill, Incorporated |
| Tate & Lyle PLC |
| Corbion N.V. |
| Archer-Daniels-Midland Company |
| International Flavors & Fragrances Inc. |
| Kemin Industries, Inc. |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Backward integration into sodium silicate feedstock anchors pricing power for precipitated silicate manufacturers serving salt and seasoning processors. Captive production of calcium silicate intermediates insulates integrated suppliers from energy-cost volatility that compresses margins at non-integrated toll processors.
Pricing Analysis
The bundled-unbundled service split separates commodity silicate supply from formulation-intensive technical support contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by particle size distribution and certification grade, with amorphous nano-silica commanding specification premiums above standard hydrated calcium silicate. Pricing pressure stems from buyer concentration among multinational seasoning houses that unbundle technical service from material contracts. Mid-sized regional blenders exhibit highest price sensitivity, while organic spice processors in Germany absorb 15-20% cost premiums for clean-label modified starch systems.
Supply Chain Analysis
Single-source vulnerability sits with Chinese coastal producers controlling ultra-fine amorphous silica output for premium seasoning applications. Raw material flows draw from sodium silicate feedstock tied to energy economics, calcium carbonate for calcium silicate synthesis, and rice hull ash for organic alternatives. Tariff exposure compounds import dependency for Brazilian seasoning processors lacking local ultra-fine particle manufacturing. Distribution runs through one-ton flexible intermediate bulk containers for salt refiners, steel drums with nitrogen flushing for hygroscopic silica grades, and direct-fill integration for retail salt packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as clean-label reformulations displace commodity silicate demand toward engineered particle architectures with dual-function performance.
For Market Incumbents: To counter unbundling pressure from concentrated seasoning buyers, deepen captive silicate production in Gujarat and Maharashtra to secure feedstock cost advantages. Invest in certified in-house toxicology testing to reduce audit burden for EU REACH compliance and retain supplier consolidation preferences from German and French seasoning exporters. For New Entrants and Emerging Players: Launch via regional blending facilities with captive silicate production targeting Nigerian seasoning processors facing limited local anti-caking agent supply. Prioritize phosphate-free formulation registration under Brazil's ANVISA streamlined timelines. Position encapsulated nano-silicate systems as dual-function ingredients simplifying clean-label declarations for U.S. clean-label seasoning houses. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized regional silicate producers with FSSAI-certified manufacturing because mandatory compliance deadlines for imported seasoning blends are accelerating domestic production localization in India. Watch for divergence between EU Green Deal chemical hazard reclassifications and legacy FDA GRAS determinations as the inflection signal triggering reformulation-driven supplier switches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock production insulates margins from energy-cost volatility at Chinese and Indian manufacturing sites. |
| REACH Certification Investment | Certified in-house toxicology testing privileges suppliers during seasoning exporter consolidation in Germany and France. |
| Encapsulation Technology Development | Modified starch nano-silicate systems enable dual-function ingredients that compress clean-label declaration complexity. |
| Regional Blending Facility Expansion | Captive silicate production in Nigeria and Brazil reduces import dependency for seasoning processors. |
| Organic Alternative Formulation | Rice hull ash and cellulose derivatives capture premium positioning despite moisture absorption limitations above 60% humidity. |
Research Methodology
Multiple input streams — regulatory filing analysis, customs and trade flow databases, and manufacturing capacity surveys — were reconciled against primary interviews with plant managers at precipitated silicate facilities, procurement leads at seasoning houses, and technical R&D directors at food additive suppliers. Secondary validation drew from FSSAI additive standard notifications, ECHA REACH authorization documentation, FDA GRAS determination records, and ISO food-grade silicate specifications. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across product types and applications.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application moisture sensitivity, end-user integration depth, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating pre-mixed spice consumption trends, clean-label reformulation pace, and FSSAI-mandated localization deadlines. Industry-specific forecast inputs encompass sodium silicate feedstock cost trajectories and seasoning manufacturer buyer concentration indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergence between EU Green Deal reclassifications and FDA GRAS legacy determinations, input cost spikes in energy-intensive silicate production, and technical limitation breakthroughs in organic alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Food Grade Glycerin Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Spain Food Enzymes Market