
 Clean Label Food Ingredient Market | 2026-2036
Clean Label Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Food Ingredient Market Analytics
Stevia and monk fruit extracts are pivoting toward cost parity with synthetic high-intensity sweeteners across beverage applications. Cargill leverages its vertically controlled stevia supply chain to secure consistent glycoside purity for multinational bottlers. Kerry Group anchors European reformulation services through specialized taste-modulation laboratories in Ireland and the Netherlands.
Clean label food ingredients comprise minimally processed, recognizable components free from artificial chemicals, genetically modified organisms, and undeclared processing aids, typically meeting specifications such as fewer than five ingredients on product declarations. Their primary commercial purpose is to satisfy consumer demand for transparency while maintaining shelf stability, texture, and flavor parity with conventional formulations. Natural preservatives and clean-label emulsifiers command widening margin pools as bakery and dairy manufacturers face compressed reformulation timelines. Non-GMO and organic quality standards attract disproportionate investment from ingredient suppliers seeking differentiation in North American retail channels.
The FDA maintains evolving guidance on "natural" claims while the EU Green Deal drives harmonized sustainability disclosure across food supply chains, with EFSA evaluating novel clean-label preservation mechanisms for safety validation. These frameworks compel ingredient suppliers to document provenance and processing methods with greater granularity than conventional additive portfolios. Stakeholders must monitor how regulatory divergence between Washington and Brussels reshapes certification costs and market access conditions for cross-border ingredient trade.
Market Dynamics
Retail chain clean-label scoring systems in Germany are compressing reformulation timelines for multinational packaged food manufacturers, forcing ingredient suppliers to accelerate documentation of provenance and processing methods.
Growth Catalysts
- EU Green Deal sustainability disclosure mandates:Harmonized supply chain transparency requirements across member states are compelling food manufacturers to source traceable, minimally processed ingredients for compliance with evolving ESG reporting frameworks.
- Beverage industry sweetener transitions:High-volume bottlers are reformulating product lines to incorporate plant-derived high-intensity sweeteners as synthetic alternatives face mounting consumer scrutiny.
- German retail scoring density:Discounter and supermarket chains operating in Germany have implemented proprietary clean-label algorithms that determine shelf placement premiums, concentrating supplier investment toward certification readiness.
Market Restraints
- Stevia leaf supply concentration:Cultivation of high-rebaudioside stevia varieties remains concentrated in specific subtropical growing regions, exposing processors to climate volatility and crop quality inconsistency.
- Natural preservative efficacy gaps:Clean-label antimicrobial systems demonstrate shorter shelf-life performance versus synthetic benzoates and sorbates in ambient bakery applications.
- FDA natural claim uncertainty:Absence of formal rulemaking on "natural" terminology creates litigation exposure for manufacturers deploying plant-derived ingredients in US retail channels.
Strategic Opportunities
- India FSSAI clean-label guidelines:Pending domestic food safety standards for minimal processing create first-mover positioning for suppliers establishing local technical service infrastructure.
- Fermentation-derived emulsifier platforms:Precision fermentation processes for producing phospholipid alternatives are opening reformulation pathways in dairy and plant-based beverage categories.
- Direct-to-manufacturer digital procurement:Ingredient marketplaces are disintermediating traditional distributor networks, enabling smaller clean-label suppliers to access mid-sized regional food processors.
Industry Challenges
- Cross-functional reformulation expertise scarcity:Food manufacturers face recruitment gaps for scientists capable of integrating sensory science, regulatory compliance, and supply chain verification within compressed product development cycles.
- Multi-certification audit burden:Simultaneous pursuit of Non-GMO Project, USDA Organic, and retailer-specific clean-label credentials extends validation timelines and strains quality assurance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Food Ingredient Market |
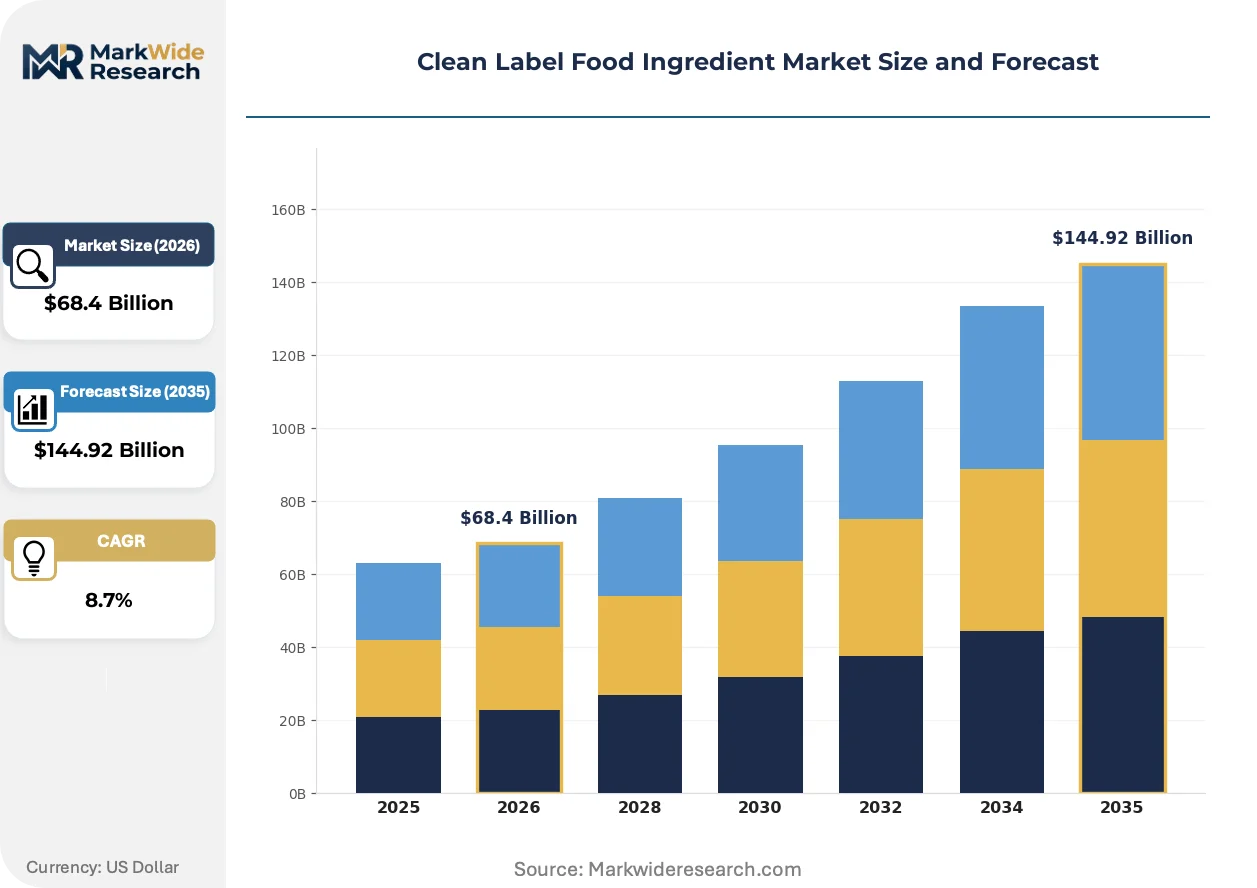
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Natural Preservatives, Flavoring Agents, Sweeteners, Emulsifiers Application: Beverages, Snacks, Bakery, Dairy Quality Standard: Organic, Non-GMO, Gluten-Free, Vegan End User: Food Manufacturers, Retailers, Foodservice Providers, Consumers |
| Companies Covered | Ingredion Incorporated, Corbion, Cargill, Tate & Lyle, Sensient Technologies Corporation, Archer Daniels Midland Company, Koninklijke DSM, International Flavors & Fragrances, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Food Ingredient Market Evolving Landscape
Bioprocessing advances and regulatory disclosure mandates are converging to reshape how ingredient suppliers document provenance, modify functional properties, and engage directly with reformulating manufacturers.
Precision fermentation for clean-label emulsifiers is absorbing capital allocation from chemical synthesis investments. Dairy alternative manufacturers in the Netherlands and plant-based beverage producers in California are adopting these microbial-derived lipids at pilot scale. The technology is absorbing margin pressure from volatile vegetable oil markets while delivering label declarations that satisfy EFSA scrutiny.
EFSA novel food evaluation pathways for plant-derived preservation systems are extending safety validation timelines for rosemary extract and cultured sugar applications. The industrial consequence is delayed market entry for European suppliers versus US competitors operating under GRAS self-determination frameworks. Bakery manufacturers in France and Italy are responding by accelerating partnerships with established US preservation ingredient suppliers.
Ingredient co-development contracts are displacing spot purchasing for strategic reformulation partnerships. Mid-sized European dairy processors are embedding supplier technical staff within product development teams to compress iteration cycles. This pattern is most visible in Ireland and Denmark, where export-oriented manufacturers face simultaneous retailer clean-label mandates and compressed launch windows.
Clean Label Food Ingredient Market Segmentation
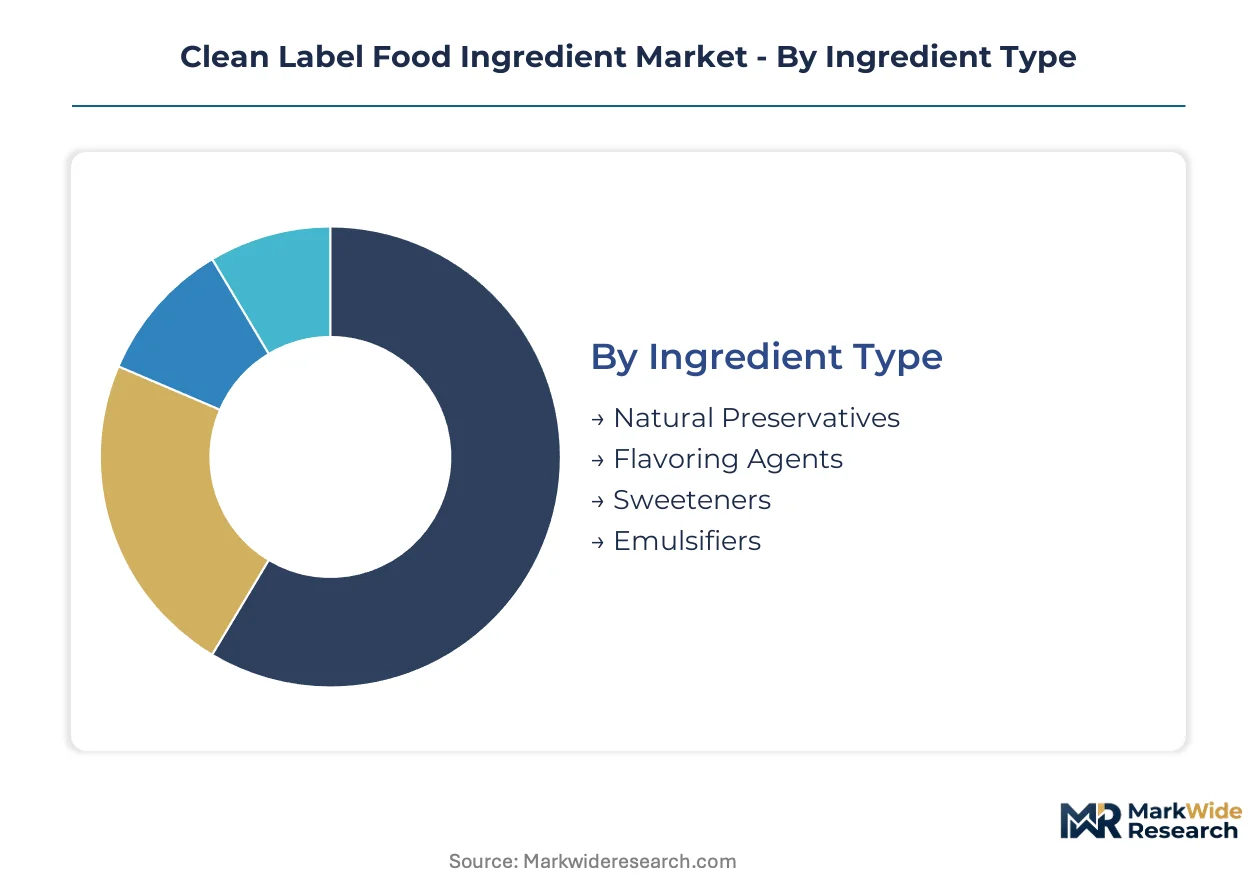
Clean label ingredient procurement diverges sharply by technical requirement and compliance burden. Manufacturers prioritize segments that compress reformulation timelines while satisfying retailer scoring algorithms and disclosure mandates.
Ingredient Type:
Functional performance and label declaration simplicity drive purchasing decisions across ingredient categories.
- Natural Preservatives:Rosemary extract, cultured sugar, and vinegar-based systems replace synthetic benzoates and sorbates. Beverage manufacturers in Germany and France absorb premium pricing to meet retailer clean-label shelf placement criteria.
- Sweeteners:Stevia glycosides and monk fruit extracts achieve cost parity with synthetic high-intensity alternatives in high-volume bottling operations. Cargill's vertically controlled cultivation secures consistent rebaudioside purity for multinational customers.
- Flavoring Agents:Botanical extracts and fermentation-derived natural flavors replace artificial counterparts in snack and bakery applications.
- Emulsifiers:Precision fermentation produces phospholipid alternatives for dairy and plant-based beverages. Dutch and California manufacturers pilot microbial-derived lipids to satisfy EFSA scrutiny.
Natural preservatives lead on scale; sweeteners lead on momentum.
Application:
Reformulation urgency varies by processing intensity and ambient shelf-life requirements.
- Beverages:High-volume bottlers face compressed timelines for sweetener transitions as synthetic alternatives encounter consumer scrutiny. Plant-derived high-intensity systems integrate at pilot scale in California and Netherlands operations.
- Bakery:Ambient shelf-life demands expose efficacy gaps in clean-label antimicrobial systems versus synthetic preservatives. French and Italian manufacturers accelerate partnerships with established US preservation suppliers.
- Dairy:Fermentation-derived emulsifiers enable texture parity in reformulated products. Irish and Danish export-oriented processors embed supplier technical staff to compress iteration cycles.
- Snacks:Flavor modulation requirements concentrate investment in taste-masking technologies for reduced-sodium and reduced-sugar formulations.
Beverages command the steepest expansion trajectory; bakery presents the most constrained reformulation pathway.
Quality Standard:
Certification density directly determines market access and pricing power in retail channels.
- Non-GMO:North American retail channels demand Project verification as a baseline qualification. Multi-certification audit burdens strain quality assurance departments pursuing simultaneous organic and retailer-specific credentials.
- Organic:USDA and EU organic standards attract disproportionate supplier investment for differentiation. Premium positioning justifies cost pass-through to reformulating manufacturers.
- Gluten-Free:Dedicated processing infrastructure requirements limit supplier participation to specialized operators.
- Vegan:Plant-based positioning aligns with fermentation-derived ingredient platforms and excludes animal-sourced processing aids.
Non-GMO leads on scale; organic leads on margin capture.
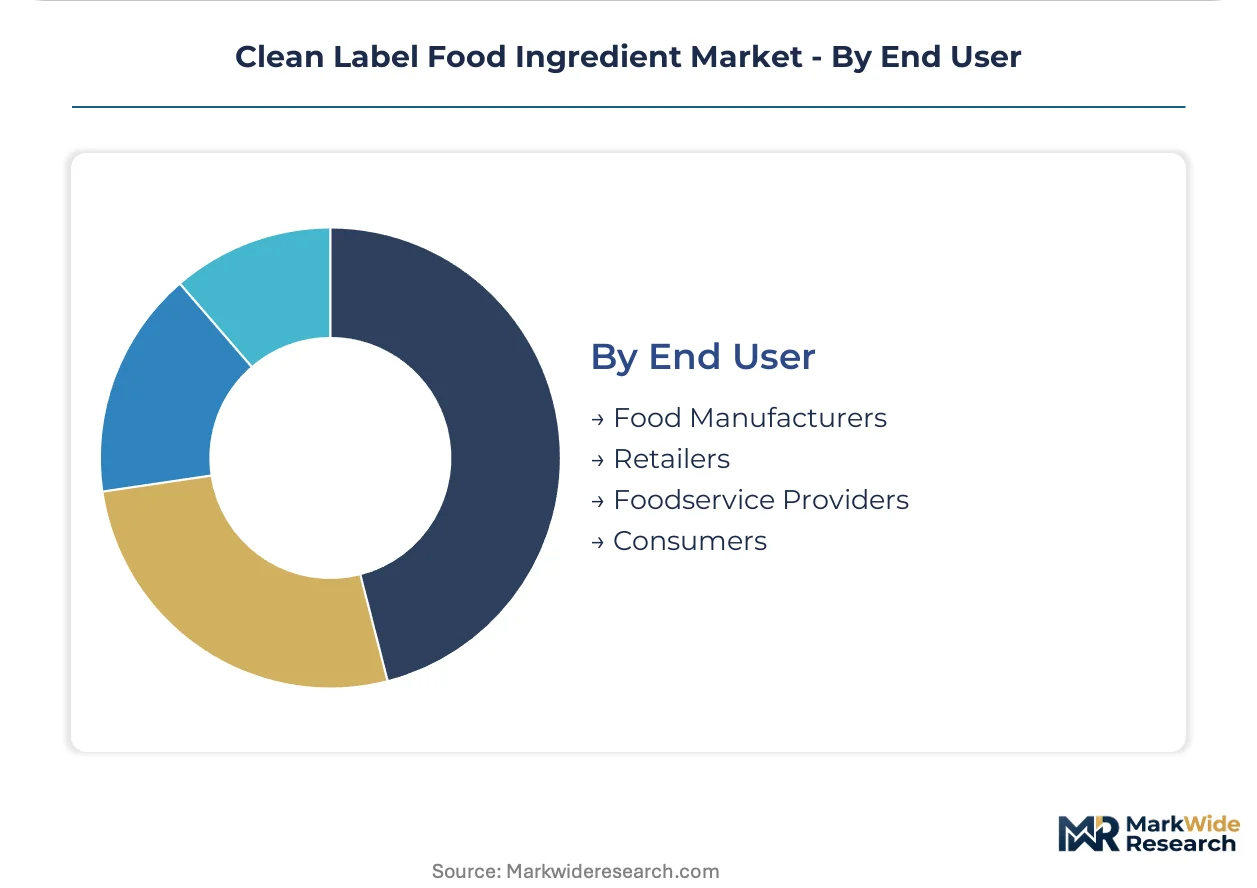
End User:
Procurement sophistication and technical service requirements segment the customer base.
- Food Manufacturers:Mid-sized European dairy processors adopt co-development contracts displacing spot purchasing. Embedded supplier technical staff compress product development cycles in Ireland and Denmark.
- Retailers:German discounter and supermarket chains deploy proprietary clean-label algorithms determining shelf placement premiums. Concentrated scoring density forces supplier investment toward certification readiness.
- Foodservice Providers:Menu transparency demands drive ingredient specification tightening in contract catering and quick-service operations.
- Consumers:Direct-to-manufacturer digital procurement platforms disintermediate traditional distributor networks for smaller regional processors.
Food manufacturers lead on volume; retailers lead on specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail scoring infrastructure anchors clean label procurement intensity across Europe, with discounter algorithms compressing supplier certification timelines and concentrating investment toward provenance documentation systems.
United States
Beverage manufacturers in California pilot plant-derived high-intensity sweeteners as FDA guidance on natural claims evolves without formal rulemaking. GRAS self-determination frameworks accelerate market entry for preservation ingredient suppliers versus European competitors. Midwest dairy processors embed technical staff from ingredient partners to compress reformulation cycles.
Germany
Discounter and supermarket chains deploy proprietary clean-label algorithms that determine shelf placement premiums, forcing multinational packaged food manufacturers to accelerate documentation timelines. EU Green Deal sustainability disclosure mandates compel traceable sourcing across member states. Bavarian bakery manufacturers absorb premium pricing for rosemary extract systems to meet retailer criteria.
Netherlands
Dairy alternative manufacturers adopt precision fermentation-derived emulsifiers at pilot scale to satisfy EFSA scrutiny on label declarations. Plant-based beverage producers integrate microbial-derived lipids amid volatile vegetable oil markets. Wageningen-area research clusters anchor taste-modulation laboratory partnerships with Irish and Danish export-oriented processors.
France
Ambient shelf-life demands expose efficacy gaps in clean-label antimicrobial systems versus synthetic preservatives in bakery applications. ANSM and EFSA evaluation pathways extend safety validation timelines for novel plant-derived preservation mechanisms. Lyon and Paris basin manufacturers accelerate partnerships with established US preservation suppliers to circumvent delays.
India
Pending FSSAI clean-label guidelines for minimal processing create first-mover positioning opportunities for suppliers establishing local technical service infrastructure. Domestic food safety standards are tightening disclosure requirements for processed foods. Maharashtra and Gujarat-based regional processors access ingredient marketplaces that disintermediate traditional distributor networks.
Clean Label Food Ingredient Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and technical service embedding. The supplier base stratifies between vertically integrated agricultural processors and specialized fermentation technology firms. Three archetypes dominate: scale-driven commodity suppliers with captive cultivation networks, precision biotechnology specialists with microbial platform IP, and integrated formulation service providers with embedded client laboratories. Capacity expansion in high-rebaudioside stevia varieties and strategic partnerships for co-development contracts represent the dominant competitive vectors.
Among North American agricultural processors, Cargill and Archer Daniels Midland occupy positions anchored by upstream control over subtropical cultivation regions. European specialists in fermentation-derived functional ingredients include Netherlands-based Corbion and Irish-headquartered Kerry Group, the latter exemplifying the integrated formulation service archetype through taste-modulation laboratory networks. These three companies represent distinct competitive vectors: captive supply systems, microbial platform technology, and embedded technical service partnerships.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Corbion |
| Cargill |
| Tate & Lyle |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| Koninklijke DSM |
| International Flavors & Fragrances |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between organic-Non-GMO Project dual-certified ingredients and single-standard alternatives manifests in both pricing premiums and supply chain complexity, as German retailer scoring algorithms force manufacturers to absorb multi-audit costs while subtropical stevia cultivation regions concentrate upstream bargaining power among vertically integrated processors.
Pricing Analysis
Input-cost pass-through from high-rebaudioside stevia leaf volatility shapes contract structures across beverage applications. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic-Non-GMO glycoside extracts from conventional natural preservatives and commodity-grade emulsifiers. Price differentiation intensifies as Kerry Group and Cargill embed technical service teams within client R&D facilities, bundling formulation support into long-term offtake agreements. Food manufacturers in compressed-reformulation timelines show lowest price sensitivity; mid-sized regional processors purchasing through digital marketplaces exhibit highest.
Supply Chain Analysis
Stevia leaf supply rests on subtropical cultivation zones in China, Paraguay, and Kenya, with high-rebaudioside variety propagation concentrated among Cargill's captive breeding programs and select agricultural cooperatives. Raw material dependencies include steviol glycoside extraction feedstock, precision fermentation nutrient media for microbial-derived emulsifiers, and rosemary extract oleoresin from Mediterranean harvests. Single-source vulnerability concentrates in high-purity rebaudioside M supply chains. Distribution runs through integrated formulation service providers embedding technical staff at dairy processors in Ireland and Denmark, supplemented by direct-procurement platforms for smaller regional manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate between EU Green Deal disclosure mandates driving premium certification demand and India's pending FSSAI guidelines creating first-mover positioning for suppliers establishing local technical infrastructure ahead of regulatory harmonization.
For Market Incumbents: Lock in captive stevia cultivation networks through backward integration into high-rebaudioside variety breeding programs in Paraguay and Kenya. Defend margin position by accelerating documentation systems for EU Green Deal provenance requirements before compliance deadlines compress. Certification investment represents the critical lever against emerging precision-fermentation specialists threatening emulsifier market share. For New Entrants and Emerging Players: The premium-economy price-point gap in natural preservatives creates white-space entry for vinegar-based and cultured sugar antimicrobial systems targeting French and Italian bakery manufacturers circumventing EFSA validation delays. Target India's pending FSSAI clean-label guidelines through local technical service infrastructure establishment. Direct-to-manufacturer digital procurement platforms offer the most penetrable go-to-market angle for mid-sized regional processors. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-certification audit burdens strain quality assurance departments at mid-tier suppliers lacking embedded client laboratory networks. Long-term viability favors integrated formulation service providers with taste-modulation capabilities and captive agricultural supply systems. Watch EFSA novel food evaluation pathway acceleration as the inflection signal for European preservation ingredient market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Cargill's captive supply secures glycoside purity consistency for multinational bottlers facing reformulation deadlines. |
| Precision Fermentation Capacity Expansion | Corbion's microbial lipid platforms satisfy EFSA scrutiny while absorbing vegetable oil price volatility for Dutch dairy alternatives. |
| Embedded Technical Service Partnerships | Kerry Group's taste-modulation laboratories compress iteration cycles for Irish and Danish export-oriented processors. |
| Multi-Certification Audit Infrastructure | Dual-certified organic-Non-GMO supply chains unlock German retailer shelf placement premiums under proprietary scoring algorithms. |
| Direct-to-Manufacturer Digital Procurement | Ingredient marketplaces disintermediate distributor networks, enabling smaller clean-label suppliers to access Maharashtra and Gujarat regional processors. |
Research Methodology
Direct dialogue with ingredient procurement directors, food manufacturer R&D heads, retailer category managers, and regulatory affairs specialists at EFSA and FDA combined with secondary validation from customs trade data, SEC 10-K filings of listed ingredient suppliers, EU Green Deal implementation documents, and FSSAI draft guideline releases. Bottom-up and top-down triangulation cross-referenced volume estimates from subtropical cultivation region export statistics against beverage industry reformulation announcements.
Bottom-up modeling anchored volume projections in segment-specific adoption curves across natural preservatives, sweeteners, emulsifiers, and flavoring agents, while top-down validation tested aggregate figures against macro-level food manufacturer R&D expenditure patterns. Segmentation dimensions included ingredient type, application category, quality standard tier, and end-user procurement sophistication. CAGRs derived from curve-fitting historical substitution rates of synthetic additives against clean-label alternatives, incorporating EFSA novel food approval timelines and FDA guidance evolution as industry-specific forecast inputs.
Caveats apply where EFSA safety validation acceleration, FDA formal rulemaking on natural claims, or climate volatility in subtropical stevia growing regions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market