
 Egg Wash Substitute Market | 2026-2036
Egg Wash Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Wash Substitute Market Foresight
Multi-source procurement of hydrocolloid and protein binders is decoupling from traditional egg supply chains in commercial baking. Corbion leverages microbial fermentation to sustain consistent lecithin alternatives for industrial-scale bread production. Puratos anchors European supply through specialized enzyme-stabilized wash systems. Dawn Foods competes across North American foodservice channels with ready-to-use liquid substitutes.
An egg wash substitute replicates the binding, browning, and sealing functions of whole-egg washes using plant-derived hydrocolloids, modified starches, or legume-based proteins such as aquafaba, typically formulated to 8-14% solids content for viscosity matching. Plant-based substitutes dominate volume as bakeries reformulate around allergen-free claims and vegan certification requirements. Aquafaba concentrates fastest growth among specialty segments, driven by premium pastry applications where foaming stability commands price premiums. Food service channels absorb disproportionate margin pools through bulk contracting and technical support bundling.
FDA allergen-labeling rules and EU REACH frameworks on processing aids shape formulation compliance costs across export-oriented suppliers. The USDA organic standard and EFSA novel food assessments create divergent approval pathways for emerging protein sources. Stakeholders must monitor regulatory convergence on precision-fermentation ingredients versus plant-extracted alternatives.
Market Dynamics
Commercial bakeries are decoupling from volatile egg supply chains through hydrocolloid and protein binder substitution, driven by allergen-labeling mandates and clean-label formulation pressures that reward ingredient transparency.
Growth Catalysts
- EU Green Deal targets:Germany's industrial baking sector accelerates plant-based ingredient substitution to meet carbon reduction benchmarks for food processing.
- Commercial bakery consolidation:Large-scale producers standardize on vegan-certified formulations to simplify multi-market distribution and reduce label complexity.
- FDA allergen-labeling rules:US export-oriented suppliers reformulate around egg-free claims to avoid mandatory disclosure requirements and cross-contamination protocols.
Market Restraints
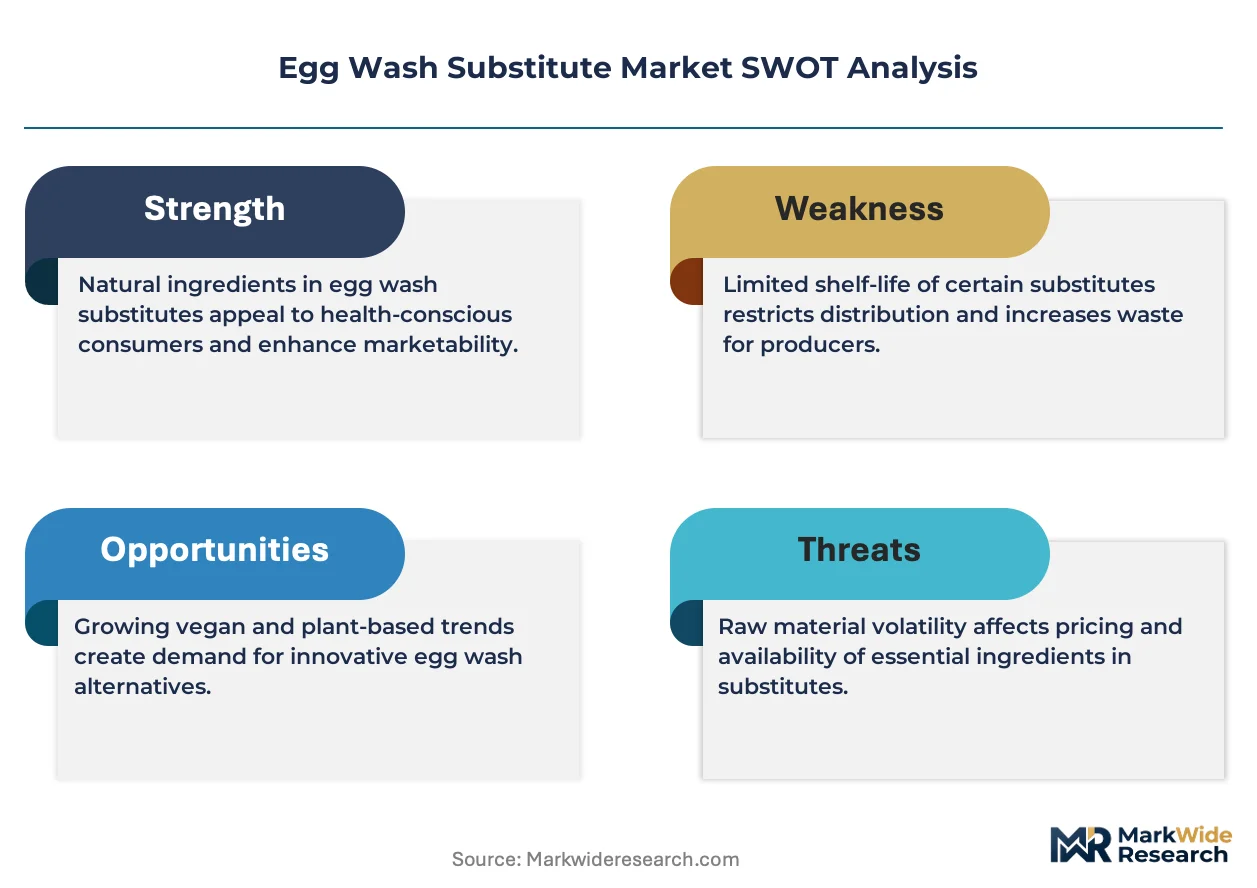
- Lecithin price volatility:Soy and sunflower lecithin feedstock costs fluctuate with commodity crop yields, compressing margins on microbial fermentation alternatives.
- EFSA novel food assessments:Emerging protein sources from precision fermentation face multi-year approval timelines that delay European market entry.
- Functional performance gaps:Plant-based substitutes struggle to replicate egg wash browning kinetics in high-temperature industrial ovens without enzyme supplementation.
Strategic Opportunities
- Premium pastry segment:Aquafaba concentrates command price premiums in artisan baking where foaming stability differentiates finished product quality.
- Foodservice bulk contracting:Technical support bundling with ready-to-use liquid substitutes captures disproportionate margin pools in institutional channels.
- USDA organic standard alignment:Certified organic egg wash substitutes access premium shelf placement in North American natural retail channels.
Industry Challenges
- Formulation chemist scarcity:Industrial baking R&D teams lack expertise in hydrocolloid rheology matching for viscosity-specific applications.
- Legacy equipment calibration:Spray application systems designed for whole-egg viscosity require retrofitting to handle 8-14% solids plant-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Wash Substitute Market |
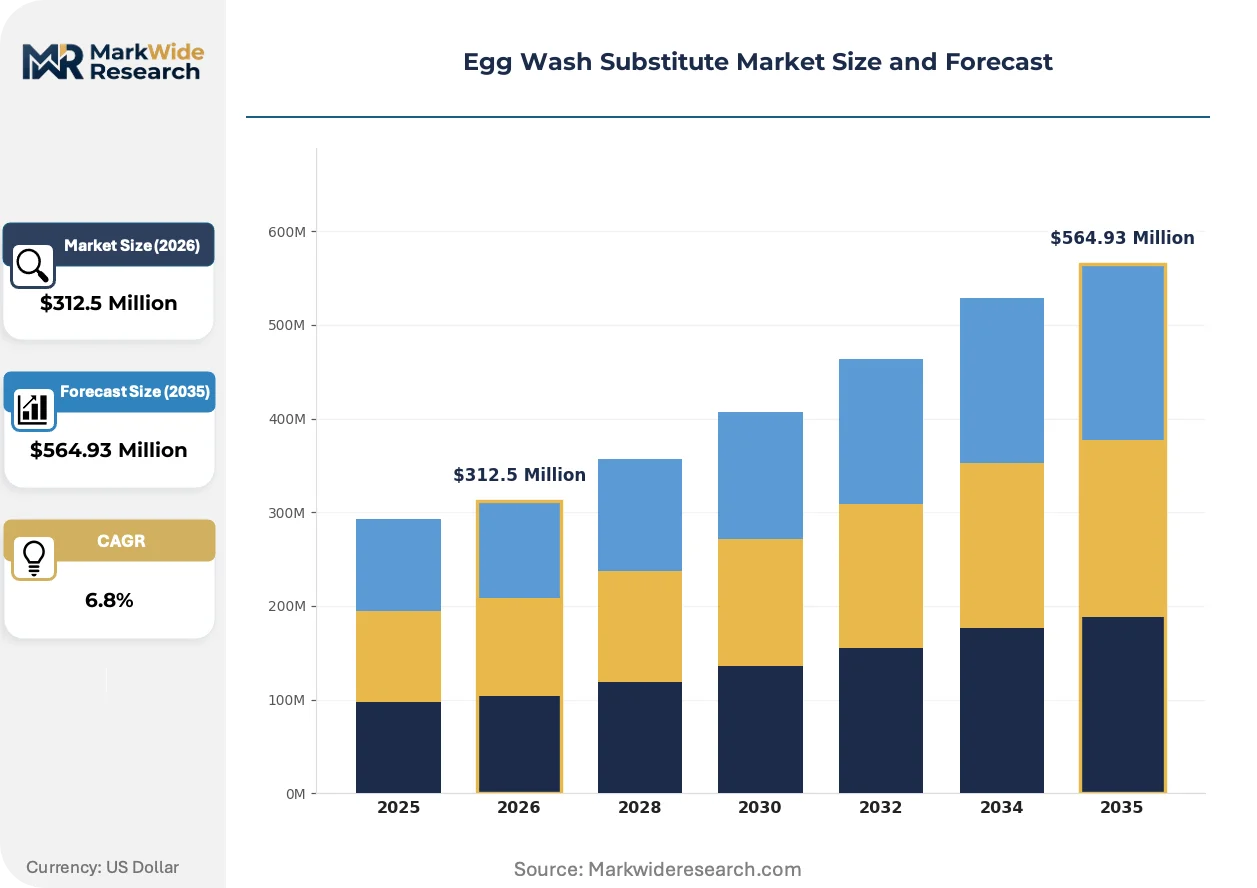
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based, Aquafaba, Almond Milk, Soy Milk Application: Baking, Pastries, Bread, Tarts Distribution Channel: Retail, Food Service, Online, Wholesale Customer Type: Bakers, Home Cooks, Restaurants, Catering |
| Companies Covered | Corbion, BOB's Red Mill, Ener-G Foods, JUST Inc., Puratos, Dawn Foods, Agropur Ingredients, Par-Way Tryson, Zero Egg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Wash Substitute Market Shifts & Advancements
Ingredient technology is pivoting from simple egg replacement toward functional replication systems that match specific performance parameters. This evolution is compressing the gap between plant-derived and animal-derived functionality.
Enzyme-stabilized wash systems are expanding into industrial-scale bread production across European commercial bakeries. Corbion deploys microbial fermentation-derived lecithin alternatives that sustain consistent emulsion stability at high throughput. This technology is expanding into North American markets as suppliers seek to reduce dependency on South American soy lecithin supply chains.
REACH frameworks on processing aids are tightening disclosure requirements for industrial baking ingredients sold into EU markets. ECHA classification debates around hydrocolloid derivatives are forcing reformulation of legacy starch-based substitutes. German and Dutch industrial bakeries are responding by accelerating novel protein source trials to preempt regulatory reclassification.
Buyer concentration among national bakery chains is compressing supplier negotiation cycles from annual to quarterly terms. Technical service bundling now determines contract awards more than unit pricing in North American foodservice channels. This pattern is most visible in California and Texas, where regional bakery consolidations have reduced viable supplier pools to three dominant distributors.
Egg Wash Substitute Market Segmentation
Ingredient functionality varies sharply across substitute categories, with viscosity specifications and browning kinetics determining suitability for industrial versus artisan applications. Procurement teams segment suppliers by solids content, protein binding efficiency, and clean-label certification status rather than price alone.
Product Type:
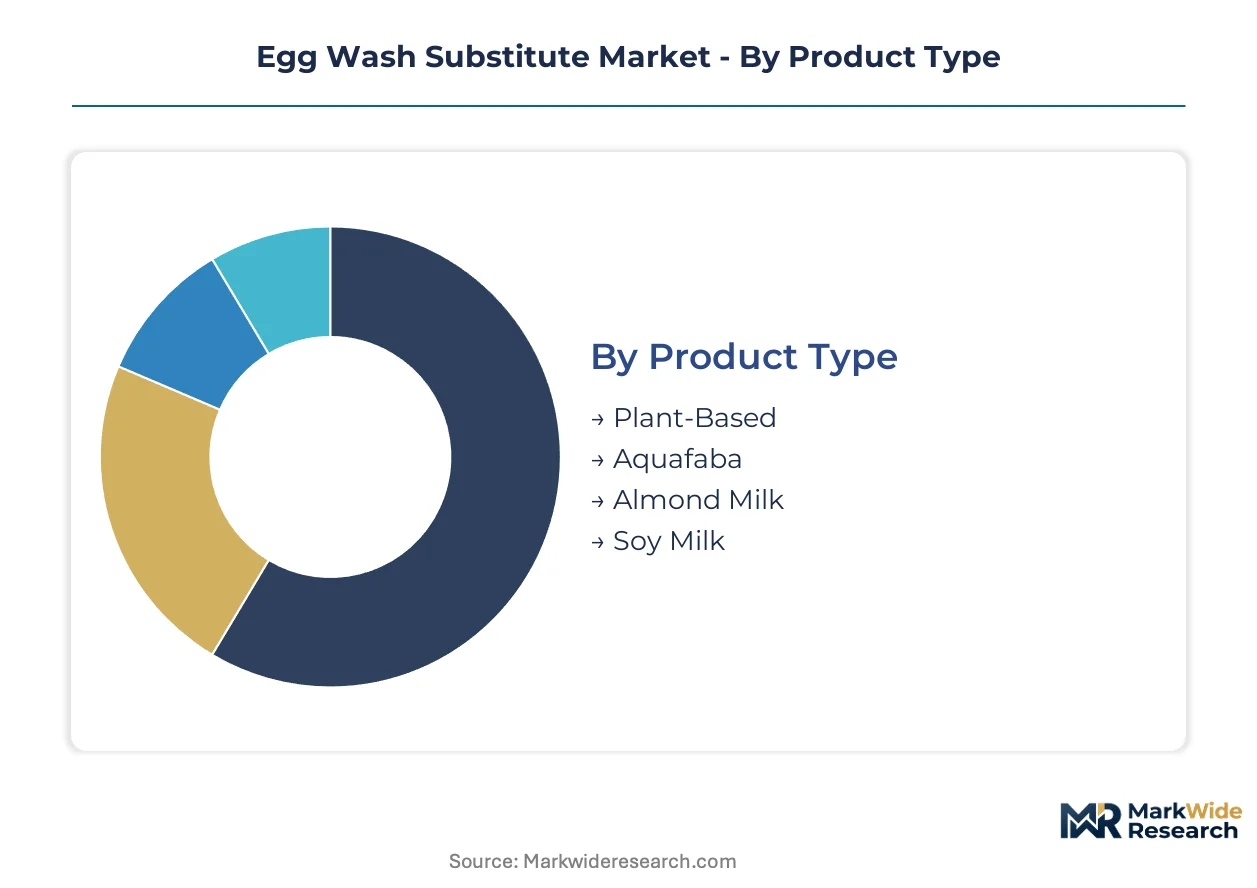
Formulation chemistry distinguishes performance tiers, with hydrocolloid systems and legume-derived proteins occupying separate specification bands for commercial baking.
- Plant-Based:Modified starches and hydrocolloid blends formulated to 8-14% solids content replicate egg wash viscosity for industrial spray application. Commercial bakeries in Germany standardize on these systems to meet EU Green Deal carbon benchmarks while maintaining throughput.
- Aquafaba:Chickpea brine concentrate delivers superior foaming stability through residual albumen proteins and saponins. Premium pastry kitchens in France and Belgium absorb supply at price premiums for macaron and meringue applications where structure retention is critical.
- Almond Milk:Nut-derived lipid emulsions provide subtle flavor profiles suited to sweet pastry finishing.
- Soy Milk:High-protein varieties offer cost-efficient browning through Maillard-active amino acids.
Plant-based formulations lead on scale across industrial channels; aquafaba climbs fastest among specialty segments commanding formulation premiums.
Application:
End-use thermal profiles dictate enzyme supplementation requirements and solids concentration targets.
- Baking:High-temperature industrial ovens demand enzyme-stabilized systems to accelerate browning kinetics without burning. North American commercial bakeries retrofit spray lines to handle lower-viscosity plant alternatives.
- Pastries:Laminated dough applications require precise moisture retention to prevent layer separation during proofing. Artisan producers in Italy and Spain specify aquafaba for croissant finishing where sheen uniformity differentiates retail presentation.
- Bread:Crust sealing and seed adhesion dominate functional requirements for sandwich loaf production.
- Tarts:Blind-bake compatibility and shrinkage resistance shape formulation selection for shell applications.
Bread applications absorb the largest volume flows; pastries generate the steepest expansion trajectory as premium positioning accelerates.
Distribution Channel:
Channel selection determines technical service bundling intensity and contract structuring flexibility.
- Retail:Packaged dry mixes and ready-to-use liquids target home bakers through supermarket baking aisles. Shelf placement depends on vegan certification and USDA organic seals in North American natural grocery channels.
- Food Service:Bulk liquid totes with quarterly technical support contracts dominate institutional procurement. Dawn Foods and Puratos compete through formulation assistance bundled with volume pricing.
- Online:Direct-to-consumer aquafaba concentrates bypass traditional distribution for specialty ingredient access.
- Wholesale:Distributor consolidation in California and Texas has compressed supplier pools to three dominant channels.
Food service channels lead on absolute margin capture; online distribution expands most quickly as specialty ingredient access democratizes.
Customer Type:
Scale and technical capability determine whether buyers self-formulate or rely on turnkey systems.
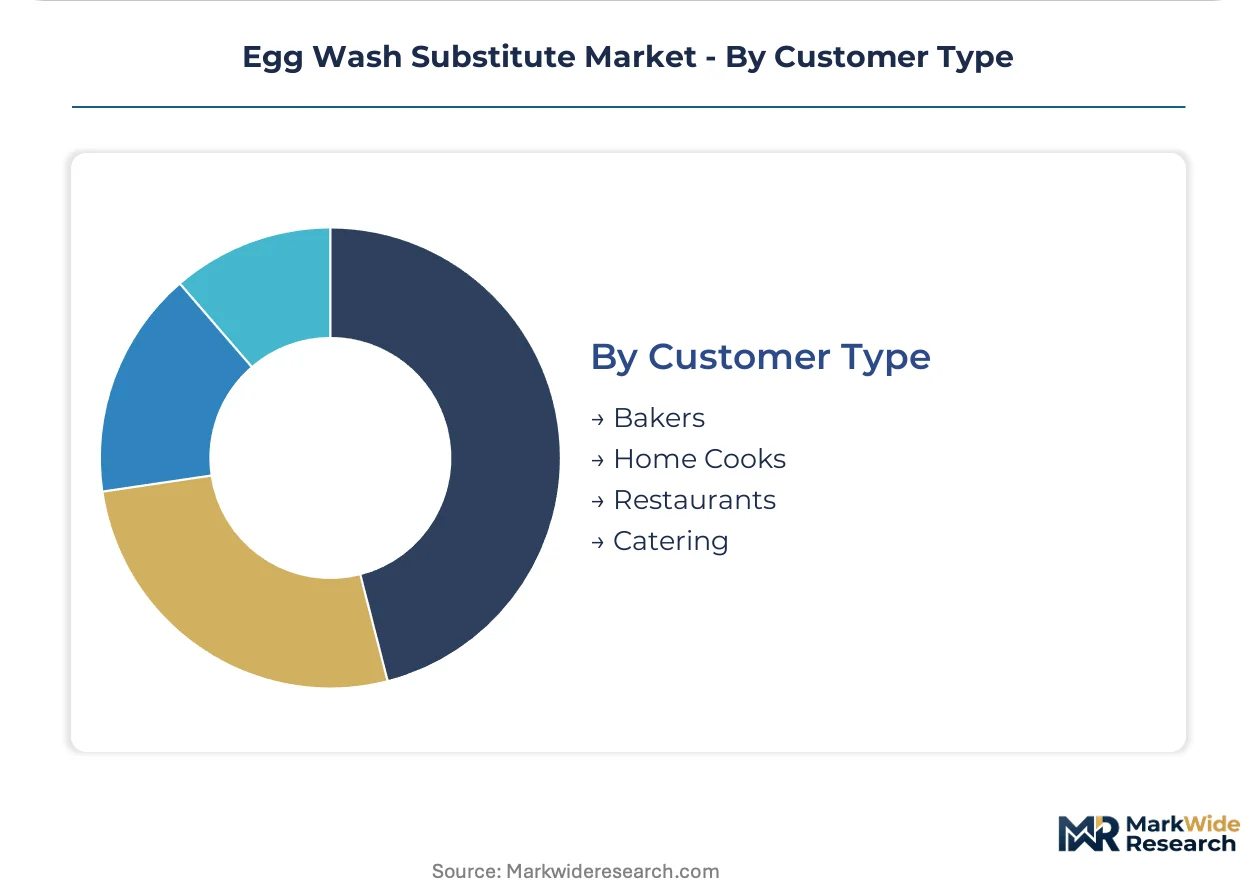
- Bakers:Industrial and artisan producers drive category volume through standardized vegan formulations that simplify multi-market distribution. Large-scale operations in Germany leverage consolidated procurement to enforce specification uniformity.
- Restaurants:Foodservice operators prioritize ready-to-use liquids to minimize kitchen labor and cross-contamination risk. Technical support availability outweighs unit pricing in contract awards.
- Home Cooks:Retail package sizes and recipe accessibility shape purchasing decisions.
- Catering:Event-scale volume requirements favor bulk sourcing with consistent performance guarantees.
Bakers command the deepest procurement volumes; restaurants represent the fastest-climbing customer segment as foodservice veganization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting egg wash substitute production toward jurisdictions with streamlined novel-food approval pathways and lower carbon-compliance costs, compressing manufacturing footprints in high-regulation zones.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia are accelerating plant-based formulation adoption to meet EU Green Deal carbon reduction benchmarks for food processing. EFSA novel food assessments for precision-fermentation proteins face multi-year timelines that favor established hydrocolloid suppliers over emerging entrants. Cologne-based ingredient distributors now bundle technical support with quarterly procurement contracts to lock in bakery chain loyalty.
United States
FDA allergen-labeling mandates are forcing export-oriented suppliers to eliminate egg-derived ingredients from standard formulations to avoid mandatory disclosure requirements and cross-contamination protocols. USDA organic certification unlocks premium shelf placement in natural grocery channels concentrated in California and Texas. Midwest commercial bakeries retrofit spray application systems to handle lower-viscosity plant-based alternatives at industrial throughput.
France
Premium pastry kitchens in Paris and Lyon absorb aquafaba concentrates at price premiums for macaron and meringue applications where foaming stability differentiates finished product quality. ANSM disclosure frameworks on processing aids tighten ingredient transparency requirements beyond EU baseline. Artisan producers in the Île-de-France region specify enzyme-stabilized systems for croissant finishing where sheen uniformity drives retail presentation value.
United Kingdom
Post-Brexit divergence from EU REACH frameworks creates dual compliance burdens for suppliers serving both British and continental markets. Commercial bakery consolidation in the Midlands and Greater Manchester reduces viable supplier pools to three dominant distributors. London-based foodservice operators prioritize ready-to-use liquid substitutes to minimize kitchen labor and cross-contamination risk in high-volume institutional channels.
Netherlands
ECHA classification debates around hydrocolloid derivatives are forcing reformulation of legacy starch-based substitutes in industrial baking applications. Randstad-region ingredient technology firms pivot toward microbial fermentation-derived lecithin alternatives to reduce dependency on South American soy lecithin supply chains. Dutch commercial bakeries standardize on vegan-certified formulations to simplify multi-market distribution across Benelux and German retail channels.
Egg Wash Substitute Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-fermentation and aquafaba concentrate niches to bypass incumbent scale advantages. The supplier base segments into three functional tiers: multinational ingredient houses with fermentation capabilities, regional bakery specialists with technical service bundling, and niche protein concentrate purveyors targeting premium pastry channels. Consolidation pressure concentrates contract awards among vendors offering quarterly technical support cycles rather than commodity pricing alone. Dominant competitive moves include strategic partnerships between hydrocolloid suppliers and equipment manufacturers for spray-system retrofitting, plus portfolio diversification into organic-certified product lines for North American natural retail placement.
Within the multinational fermentation tier, Corbion and Puratos exemplify archetypes of microbial-derived lecithin scale and enzyme-stabilized system specialization respectively. Dawn Foods occupies a position among North American foodservice channels where bulk liquid distribution and formulation assistance determine contract outcomes. These three entities anchor the competitive perimeter through divergent geographic and functional positioning rather than direct product overlap.
| Leading Market Players |
|---|
| Corbion |
| BOB's Red Mill |
| Ener-G Foods |
| JUST Inc. |
| Puratos |
| Dawn Foods |
| Agropur Ingredients |
| Par-Way Tryson |
| Zero Egg |
| Others |
Supply & Pricing Matrix
Microbial fermentation-derived lecithin alternatives are displacing commodity soy lecithin extraction methods, simultaneously compressing production costs for industrial-scale suppliers while concentrating manufacturing capabilities among fermentation-capable facilities in the Netherlands and Germany. This technology transition feeds directly into pricing power dynamics, as bakeries face divergent cost structures depending on their supplier's upstream process integration.
Pricing Analysis
Distributor margin layers absorb the steepest markup differentials in foodservice channels, where technical support bundling commands premium positioning over commodity spot pricing. Three-tier pricing structure across premium aquafaba concentrates, standard hydrocolloid blends, and economy modified starch formulations reflects certification grade and volume scale as primary differentiation drivers. Cost compression in economy tiers is intensifying because sunflower lecithin feedstock volatility transmits directly to microbial fermentation alternatives. National bakery chains exhibit lowest price sensitivity due to quarterly contract lock-ins, while independent artisan producers remain most exposed to spot market fluctuations.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia are pushing German industrial bakeries toward consolidated procurement relationships that reduce supplier management overhead. Supply concentrates in the Netherlands for enzyme-stabilized systems, in Germany for hydrocolloid blending, and in France for aquafaba concentrate finishing. Raw material dependencies center on South American soy lecithin, Ukrainian sunflower oil, and chickpea processing byproducts from Mediterranean pulse suppliers. Single-source vulnerability around precision-fermentation capacity creates bottleneck risk for emerging protein alternatives. Distribution runs through specialized ingredient distributors in Cologne and Rotterdam for European commercial bakeries, with direct bulk liquid totes serving North American foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where aquafaba concentrates and enzyme-stabilized systems command widening premiums as artisan and industrial bakeries converge on performance-validated substitutes over commodity alternatives.
For Market Incumbents: Anticipate margin compression from precision-fermentation entrants by locking multi-year supply agreements with German bakery chains before EFSA novel food approvals democratize access. Deepen backward integration into microbial fermentation capacity in Randstad-region facilities to secure lecithin alternative supply. Invest in USDA organic certification infrastructure to defend shelf placement in California and Texas natural retail channels against private-label encroachment.
For New Entrants and Emerging Players: Direct-to-consumer aquafaba concentrate platforms offer the most penetrable route for bypassing consolidated distributor pools in North American wholesale channels. Target premium pastry kitchens in Paris and Lyon with foaming-stability guarantees that command formulation premiums over standard hydrocolloid blends. Pursue technical co-development partnerships with Italian artisan producers seeking croissant-finishing alternatives to establish credibility before scaling into industrial channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional enzyme-stabilized system specialists with established European bakery relationships but limited North American penetration. Long-term viability hinges on regulatory convergence between FDA allergen-labeling frameworks and EU REACH processing aid classifications that determine addressable market breadth. Watch EFSA novel food approval timelines for precision-fermentation proteins as the critical inflection signal for competitive displacement risk in premium formulation tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive lecithin alternative production insulates Corbion and Puratos from South American soy supply volatility. |
| USDA Organic Certification Program | Organic seals unlock premium shelf placement in California natural grocery channels where Dawn Foods competes. |
| Technical Service Bundling Expansion | Quarterly formulation support contracts lock bakery chain loyalty in Germany's consolidated procurement environment. |
| Direct-to-Consumer Channel Launch | Online aquafaba concentrates bypass distributor consolidation in Texas and California wholesale markets. |
| Enzyme-Stabilized System R&D Partnership | Collaboration with equipment manufacturers retrofits spray lines for 8-14% solids plant-based viscosity ranges. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial bakery procurement directors, formulation chemists at ingredient houses, foodservice distribution channel managers, and regulatory affairs specialists at EFSA and FDA with secondary validation. Primary sources included plant managers at German industrial baking facilities, technical R&D directors at hydrocolloid suppliers, and category buyers at North American natural grocery chains. Secondary data drew from FDA allergen-labeling guidance documents, EFSA novel food assessment registers, EU Green Deal carbon benchmark disclosures, and customs records tracking lecithin alternative trade flows. Bottom-up volume estimates from bakery chain procurement data triangulated against top-down market sizing from ingredient supplier revenue disclosures.
Historical reference periods anchored the forecast window to pre-pandemic baseline throughput levels and post-2022 reformulation acceleration phases, ensuring continuity across regulatory transition points. The analytical framework modeled segmentation dimensions including ingredient functionality tier, application thermal profile, distribution channel structure, and customer scale archetype across the projection horizon. CAGRs derived from linear regression of quarterly procurement volumes adjusted for bakery consolidation events and regulatory approval timelines. Industry-specific forecast inputs incorporated EFSA novel food assessment pipeline status and USDA organic certification penetration rates in natural retail channels.
The model assumes a particular technology adoption path; alternative pathways for precision-fermentation protein commercialization would alter the outlook if EFSA accelerates approval timelines or FDA expands allergen-labeling enforcement scope. Forecasts reflect assumptions about sustained EU Green Deal carbon compliance pressure and continued bakery consolidation in Midwest and Texas markets. Material deviation in ECHA hydrocolloid reclassification decisions or sunflower lecithin commodity price spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Japan Food Additives Market