
 Global Metal Implants and Medical Alloys Market | 2026-2036
Global Metal Implants and Medical Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Implants and Medical Alloys Market Intelligence
The rising incidence of spinal disorders and cardiovascular diseases is restructuring the end-use landscape away from a sole focus on traditional orthopedics. Stryker Corporation leverages its extensive portfolio in trauma fixation and joint replacement to maintain a dominant market position. Zimmer Biomet Holdings Inc. specializes in musculoskeletal healthcare, focusing on innovative cobalt-chromium and titanium alloys. Meanwhile, Medtronic plc competes strongly in the cardiovascular and spinal implant segments, utilizing advanced metallic biomaterials.
Metal implants and medical alloys are specialized metallic materials, like titanium and cobalt-chromium, engineered for biocompatibility and structural integrity inside the body. They replace or support biological structures, demanding high corrosion resistance and specific fatigue strength. Titanium implants lead the market due to an excellent strength-to-weight ratio, while novel magnesium alloys are a high-growth niche. While orthopedic surgery is the largest application, dental restorations provide stable, high-margin demand for specialized alloy forms.
Market access is governed by stringent regulatory approvals from bodies such as the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). Compliance with standards like ISO 13485 and material-specific guidelines from China's National Medical Products Administration (NMPA) is mandatory for commercialization. Stakeholders must navigate the complex trade-offs between developing next-generation biodegradable alloys and managing the high costs of clinical validation and regulatory submission.
Market Dynamics
The convergence of additive manufacturing with personalized medicine is the central force shaping the metal implants market. This shift enables the production of patient-specific devices from materials like titanium, fundamentally altering surgical approaches and supply chain economics away from mass-produced, standardized components.
Growth Catalysts
- Additive Manufacturing:The adoption of 3D printing technologies allows for the creation of custom titanium implants with complex, porous structures that enhance osseointegration, particularly in orthopedic and craniomaxillofacial surgeries.
- Aging Demographics:Expanding elderly populations in countries like Germany and China are driving a higher incidence of degenerative joint diseases, directly increasing the volume of orthopedic procedures such as hip and knee replacements.
- Application Diversification:Demand for advanced metallic biomaterials is expanding beyond traditional orthopedics into high-growth cardiovascular and spinal implant segments, addressing conditions like spinal stenosis and cardiovascular disease.
Market Restraints
- High Validation Costs:The substantial expense and long timelines associated with clinical trials and regulatory submissions for novel alloys, such as biodegradable magnesium, create significant barriers to entry and innovation.
- Stringent Regulatory Hurdles:Navigating complex and lengthy approval pathways from bodies like the US FDA and the European Medicines Agency slows the commercialization of next-generation implants and materials.
- Material Biocompatibility Risks:Long-term concerns regarding ion leaching, corrosion, and the in-vivo degradation profile of certain metallic alloys can limit their application and necessitate costly post-market surveillance.
Strategic Opportunities
- Biodegradable Metals:Developing novel magnesium-based alloys that safely dissolve in the body presents a major opportunity, as these implants would eliminate the need for secondary removal surgeries, reducing healthcare costs.
- Smart Implants:The integration of micro-sensors into implants to monitor factors like strain, temperature, and infection offers a new frontier for post-operative care and data-driven patient management.
- Emerging Market Penetration:As healthcare infrastructure improves in certain Asian and Latin American nations, there is a significant opportunity to introduce established implant technologies to previously underserved patient populations.
Industry Challenges
- Divergent Global Standards:Manufacturers face significant operational complexity in ensuring that a single product line complies with the distinct material and testing requirements of the FDA, EMA, and China's NMPA.
- Raw Material Volatility:Securing a stable supply of high-purity medical-grade raw materials, including titanium and cobalt, is a persistent challenge, with supply chains susceptible to geopolitical and pricing instability.
- Specialized Talent Scarcity:A shortage of professionals with combined expertise in materials science, biomedical engineering, and additive manufacturing constrains research and development efforts and limits production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Implants and Medical Alloys Market |
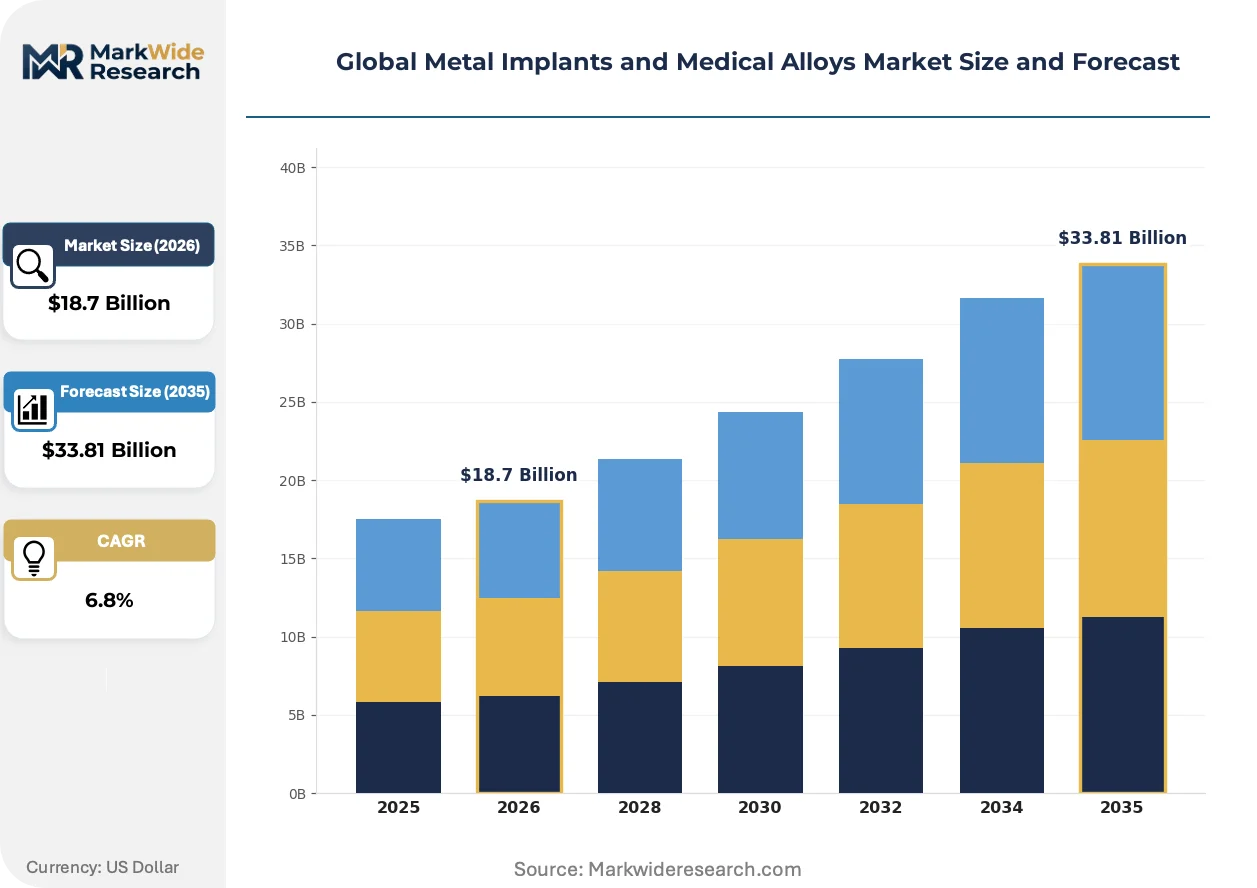
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Implants, Cobalt-Chromium Alloys, Stainless Steel, Tantalum, Zirconium Alloys, Magnesium Alloys Application: Orthopedic Surgery, Dental Restorations, Cardiovascular Devices, Spinal Implants, Maxillofacial Reconstruction, Trauma Fixation End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research Institutions, Rehabilitation Centers, Dental Laboratories Form: Bars, Sheets, Wire, Powder, Plates, Foils |
| Companies Covered | Carpenter Technology Corporation, Aperam S.A., Stryker Corporation, AMETEK Inc, Fort Wayne Metals Research Products LLC, Zimmer Biomet Holdings Inc., ATI Specialty Alloys and Components, Johnson Matthey, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Implants and Medical Alloys Market Strategic Shifts & Innovations
Personalization and biological integration are the primary forces driving innovation in medical alloy design and implant manufacturing. This evolution moves beyond simple structural replacement toward devices that actively participate in the healing process, guided by advanced material science and patient-specific data.
Additive manufacturing enables the creation of patient-specific titanium implants with porous architectures designed to mimic bone. Orthopedic and maxillofacial surgical specialties are adopting this for complex reconstructions and joint replacements. This technology is unifying the design and manufacturing phases, allowing for customized geometries that promote superior bone ingrowth and long-term implant fixation.
The European Union's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence, material traceability, and post-market surveillance. This policy forces manufacturers to generate more extensive data to prove the long-term safety and performance of their devices. Spinal and cardiovascular implant segments are particularly impacted, prompting reinvestment in clinical studies for both new and legacy products.
A notable shift in hospital procurement toward value-based criteria is altering purchasing decisions for high-volume implants. This model de-emphasizes initial unit cost in favor of devices with proven data on long-term durability and reduced revision rates. The trend disrupts traditional sales channels based on surgeon relationships alone and is most visible in the competitive joint replacement markets of the United States and Germany.
Global Metal Implants and Medical Alloys Market Segmentation
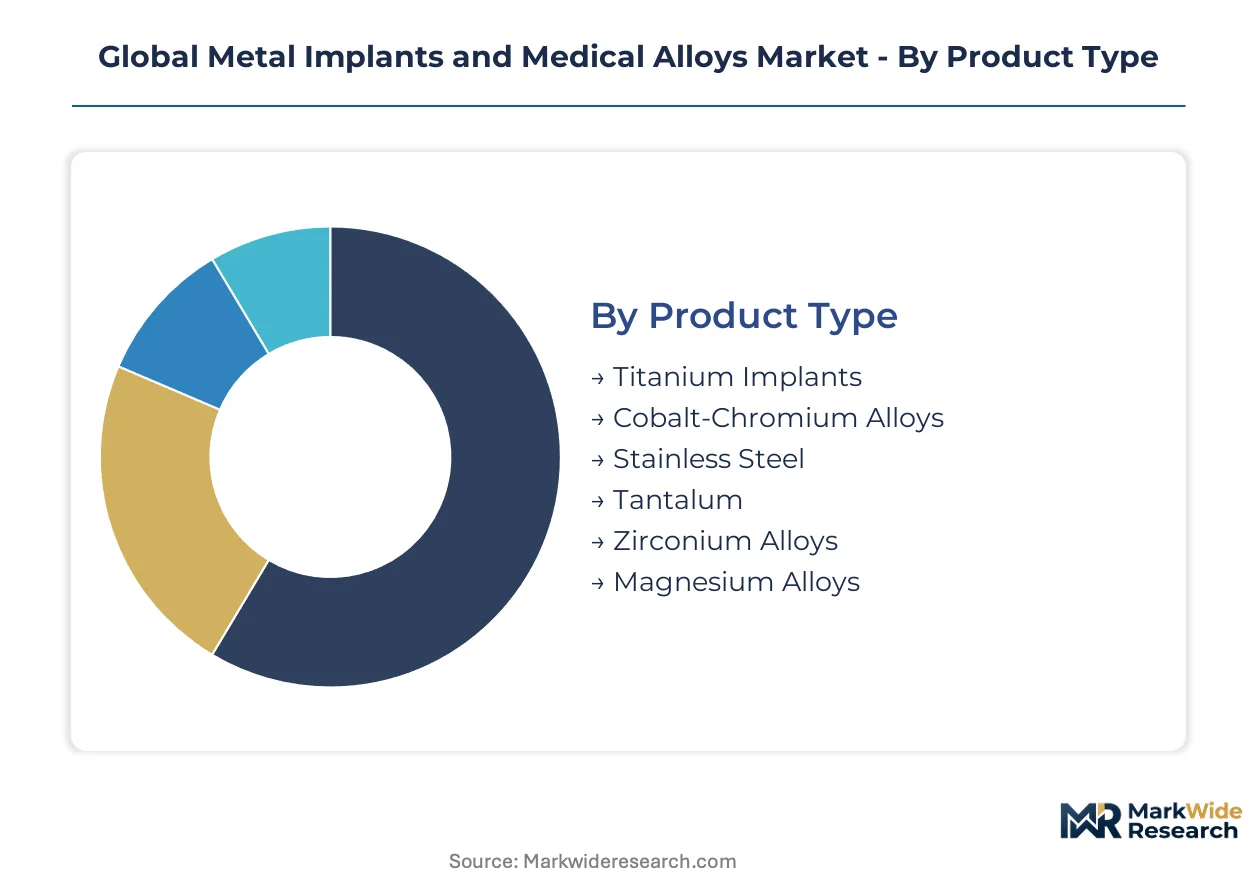
The segmentation of the global metal implants and medical alloys market reveals distinct material preferences, application priorities, and end-user demands. Understanding these segments is crucial for manufacturers to align product development with clinical needs and regulatory pathways. This granular view highlights areas of established use and emerging technological shifts.
Product Type:
Product types differentiate based on their material composition and inherent biocompatibility, influencing their suitability for standalone implants or integration into complex medical devices.
- Titanium Implants:These implants leverage titanium's exceptional strength-to-weight ratio and corrosion resistance, frequently used in orthopedic and dental applications. Demand concentrates in joint replacement surgeries across aging populations in Germany and China, driven by superior osseointegration properties.
- Cobalt-Chromium Alloys:Known for high wear resistance and mechanical strength, cobalt-chromium alloys find extensive use in joint prostheses, particularly for hip and knee components. The demand for these alloys remains stable in high-load bearing applications, despite concerns over ion release.
- Stainless Steel:This material offers cost-effectiveness and adequate mechanical properties for temporary fixation devices and certain surgical instruments.
- Tantalum:Tantalum's high biocompatibility and porous structure are beneficial for bone ingrowth, primarily in orthopedic and spinal fusion cages.
- Zirconium Alloys:These alloys provide enhanced biocompatibility and reduced allergic reactions compared to other metals, gaining traction in dental and joint replacement components.
- Magnesium Alloys:Emerging as biodegradable implants, magnesium alloys offer the advantage of dissolving safely in the body, eliminating the need for secondary removal surgeries.
Volume placements concentrate in Stainless Steel; the faster expansion belongs to Magnesium Alloys.
Application:
Applications categorize the market by the specific medical procedures and body systems where metal implants and alloys are utilized, reflecting diverse clinical requirements and patient demographics.
- Orthopedic Surgery:This segment encompasses joint replacements, trauma fixation, and spinal fusion, representing the largest application area for metal implants. Demand is substantial in countries with high incidences of degenerative joint diseases, such as the United States and Japan.
- Cardiovascular Devices:Metal alloys are critical for stents, heart valves, and pacemakers, requiring high fatigue strength and corrosion resistance. The segment's expansion is tied to the rising global prevalence of cardiovascular diseases and technological advancements in minimally invasive procedures.
- Dental Restorations:Metal alloys are used for crowns, bridges, and dental implants, providing durable and functional solutions for tooth replacement.
- Spinal Implants:This category includes rods, plates, and cages for spinal stabilization and fusion procedures, addressing conditions like scoliosis and degenerative disc disease.
- Maxillofacial Reconstruction:Implants for facial bone repair and reconstruction utilize specialized alloys, often benefiting from patient-specific additive manufacturing.
- Trauma Fixation:Devices such as plates, screws, and nails for repairing bone fractures fall into this application, providing temporary or permanent support.
High-volume utilization is evident in Orthopedic Surgery, while Cardiovascular Devices are gaining share quickly.
End User:
End-user segments highlight the primary healthcare facilities and institutions procuring and utilizing metal implants and medical alloys, demonstrating varied purchasing models and patient care settings.
- Hospitals:These institutions serve as the primary end-users due to their comprehensive surgical capabilities, emergency services, and high patient volumes for complex procedures. Hospitals in urban centers across Europe and Asia drive significant procurement.
- Specialty Clinics:Focused on specific medical areas like orthopedics or cardiology, these clinics perform a range of implant procedures, often offering specialized patient care. Their procurement patterns are influenced by referral networks and technological adoption.
- Ambulatory Surgery Centers:These centers offer cost-effective outpatient surgical procedures, including some joint and spinal interventions.
- Research Institutions:Universities and private research facilities use medical alloys for material science studies, biocompatibility testing, and new implant development.
- Rehabilitation Centers:While not direct implanters, these centers manage post-operative care and rehabilitation for patients with metal implants.
- Dental Laboratories:These facilities fabricate custom dental prosthetics and restorations using various medical alloys based on dentist specifications.
The largest volume of implants flows through Hospitals, with Ambulatory Surgery Centers demonstrating increasing throughput.
Form:
The form segment categorizes metal implants and medical alloys by their physical shape and processing state, which dictates their manufacturing application and suitability for different implant types.
- Powder:Metallic powders are critical feedstocks for additive manufacturing processes, enabling the creation of complex, patient-specific implants with porous structures. Demand for powder forms is particularly high in advanced manufacturing hubs like the United States and Germany.
- Plates:Plates are widely used in orthopedic and trauma fixation for stabilizing fractures and supporting bone structures, available in various sizes and designs. The consistent demand for plates underscores their foundational role in surgical interventions.
- Bars:Metal bars serve as raw material for machining into custom components or for the fabrication of rods and pins used in orthopedic surgery.
- Sheets:Thin metal sheets are utilized in reconstructive surgery, particularly for cranial and facial implants, due to their malleability and formability.
- Wire:Medical-grade wires are essential for cardiovascular stents, surgical sutures, and certain dental applications requiring flexibility and strength.
- Foils:Very thin metal foils find niche applications in specialized medical devices and some implantable sensors due to their minimal profile.
Production volumes are substantial for Plates, while Powder forms are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global metal implants market exhibits a clear divide between established production hubs and expanding consumption centers. Advanced economies often lead in material innovation and complex manufacturing processes. Developing regions, conversely, fuel demand through expanding patient populations and improving healthcare access.
United States
The United States experiences high incidence of orthopedic surgeries and advanced cardiovascular procedures. US FDA approval is critical for market access and commercialization of new implant technologies. Boston's medical technology hub drives innovation in biomaterials and patient-specific implant development.
Germany
Germany demonstrates strong demand for joint replacements, driven by its aging demographics. The European Medical Device Regulation (MDR) imposes strict clinical evidence requirements for all medical devices. Southern Germany's "Medical Valley" region fosters R&D in advanced implant manufacturing techniques.
China
China's expanding healthcare infrastructure fuels a rising prevalence of spinal disorders and orthopedic needs. China's National Medical Products Administration (NMPA) sets material-specific guidelines for local and imported products. The Yangtze River Delta region sees significant investment in additive manufacturing for customized implants.
Japan
Japan's rapidly aging population drives high adoption of advanced dental and orthopedic implants. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent quality and safety standards for medical devices. Tokyo and Osaka host numerous R&D centers for metallic biomaterials and implant design.
India
India experiences increasing healthcare expenditure and a growing number of orthopedic and cardiovascular patients. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing. Bengaluru emerges as a hub for medical device startups focusing on cost-effective implant solutions.
Global Metal Implants and Medical Alloys Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers focus on niche applications. The market demonstrates a tiered structure, with a few large players dominating core segments and numerous smaller firms innovating in specific material science areas. Strategic archetypes include diversified medical device conglomerates and material science specialists. Companies prioritize portfolio diversification and strategic partnerships to navigate regulatory complexities.
Within the diversified medical device conglomerate archetype, Stryker Corporation exemplifies a broad portfolio spanning trauma fixation and joint replacement applications. Zimmer Biomet Holdings Inc. represents a strong focus on musculoskeletal healthcare, leveraging innovative cobalt-chromium and titanium alloys for various procedures. Medtronic plc, a globally recognized entity, anchors a significant presence in cardiovascular and spinal implant segments, utilizing advanced metallic biomaterials. These organizations often leverage their established distribution networks and clinical relationships to maintain market leadership across various geographies. Their strategies frequently involve integrating advanced biomaterials into existing product lines through focused R&D efforts and targeted acquisitions.
| Leading Market Players |
|---|
| Carpenter Technology Corporation |
| Aperam S.A. |
| Stryker Corporation |
| AMETEK Inc |
| Fort Wayne Metals Research Products LLC |
| Zimmer Biomet Holdings Inc. |
| ATI Specialty Alloys and Components |
| Johnson Matthey |
| Medtronic plc |
| Others |
Cost & Logistics Intelligence
Raw material volatility for high-purity metals like titanium and cobalt significantly impacts manufacturing costs, which then influences the final pricing tiers for medical implants sold to hospitals and clinics.
Pricing Analysis
Cost-down pressure on implant manufacturers intensifies as value-based criteria alter hospital procurement decisions. The dominant pricing structure for high-volume implants shifts toward contract-based long-term offtake agreements. Price differentiation stems from certification level (e.g., ISO 13485 compliance), customization level for patient-specific devices, and bundled after-sales service. Hospitals, particularly in the United States and Germany, exhibit less price sensitivity for devices with proven long-term durability and reduced revision rates.
Supply Chain Analysis
Dual-sourcing requirements for critical components and raw materials are becoming standard practice, driven by geopolitical instability and material volatility. Geographic supply concentration for medical-grade metals centers on specialized processors in countries like Germany and the United States, drawing raw materials from diverse global sources. Raw material dependencies include titanium, cobalt, and emerging magnesium alloys. Commodity price volatility for these metals represents a significant structural risk. Distribution runs through established direct sales channels to hospitals and specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, primarily justified by the scarcity of specialized talent in materials science and additive manufacturing, which props up pricing for advanced implant development.
For Market Incumbents: Anchor market leadership by consistently investing in R&D for advanced biomaterials and additive manufacturing capabilities. Diversify product portfolios to mitigate risks from stringent regulatory hurdles like the EU MDR. Leverage established distribution networks and clinical relationships to reinforce market position against emerging specialized manufacturers. Invest in robust post-market surveillance to address long-term biocompatibility risks and satisfy evolving regulatory requirements.
For New Entrants and Emerging Players: China's NMPA setting material-specific guidelines opens a window for local and specialized foreign players to develop compliant, cost-effective implant solutions. Target the high-growth niche of biodegradable magnesium alloys, emphasizing their ability to eliminate secondary removal surgeries. Penetrate emerging markets in Asia and Latin America with established implant technologies. Focus on patient-specific implants enabled by additive manufacturing as a go-to-market strategy for complex orthopedic and maxillofacial cases.
For Investors and Strategic Acquirers: Successful clinical validation of novel biodegradable alloys is the leading indicator that signals transformative long-term market viability. The market offers sustained demand from aging populations and the rising incidence of chronic diseases. Target material science specialists and additive manufacturing technology firms for acquisition, particularly those with strong intellectual property in patient-specific device creation. Watch for regulatory harmonization efforts across major markets as a signal for broader commercialization opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Expedites market access for novel implant technologies in the United States. |
| Additive Manufacturing Scale-Up | Enhances production of patient-specific devices, improving surgical outcomes. |
| Strategic Material Science Partnerships | Fosters innovation in advanced metallic biomaterials and biodegradable alloys. |
| Emerging Market Geographic Expansion | Taps into underserved patient populations and expanding healthcare infrastructures. |
| R&D Investment in Smart Implants | Integrates micro-sensors for real-time monitoring, improving post-operative care. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews with industry stakeholders. This involved conversations with biomedical engineers, hospital procurement managers, regulatory affairs specialists, and orthopedic surgeons. Secondary data sources included US FDA filings, European Medicines Agency guidelines, China's NMPA standards, and academic literature. The analysis utilized both bottom-up and top-down triangulation to ensure data accuracy.
The data-stream reconciliation approach integrated market size estimations, historical growth trends, and future projections across the analysis window. Segmentation dimensions modeled included product type, application, end user, form, and regional regulatory compliance. Compound annual growth rates were derived from a comprehensive historical data analysis and forward-looking market dynamics. Key industry-specific forecast inputs included the global incidence of degenerative diseases and advancements in additive manufacturing technologies.
The model assumes a particular technology adoption path; alternative pathways for novel magnesium alloys would alter the outlook significantly. Forecasts reflect assumptions regarding regulatory stability and raw material supply chain resilience. Deviation in geopolitical stability impacting raw material sourcing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Automated CPR Devices Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Helium Free MRI Scanners Market
Medical Devices
Stent Delivery Systems Market