
 India Contract Manufacturing Organization (CMO) Market | 2026-2036
India Contract Manufacturing Organization (CMO) Market Size, Share, and Industry Trends Forecast 2026-2036
India Contract Manufacturing Organization (CMO) Market Insights
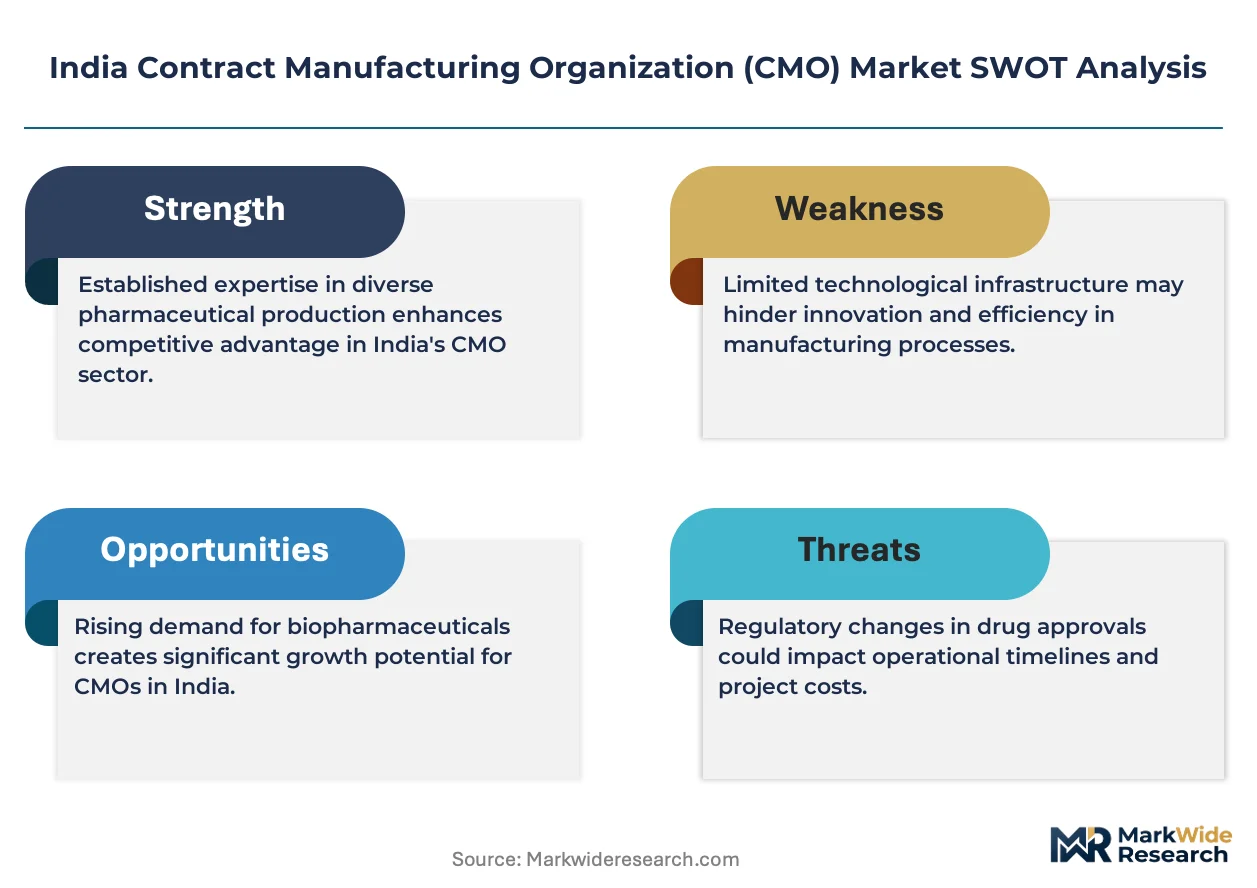
CDSCO's tightened Good Manufacturing Practice requirements is broadening compliance costs for new entrants while favoring established operators. Aurobindo Pharma Limited leverages integrated API-to-formulation capabilities across multiple dosage platforms. Divi's Laboratories Limited anchors high-purity active pharmaceutical ingredient output for global innovators. Akums Drugs and Pharmaceuticals sustains one of India's largest contract manufacturing footprints across therapeutic categories.
India Contract Manufacturing Organization refers to third-party entities that execute pharmaceutical production—from synthesis of active pharmaceutical ingredients through finished dose formulation, packaging, and labeling—under client-owned licenses and quality systems, typically operating facilities with dedicated containment suites, cleanroom classifications, and validated analytical laboratories to assure batch consistency and regulatory audit readiness. Active Pharmaceutical Ingredients commands the deepest margin pools due to technical complexity and import substitution tailwinds, while Biologics represents the fastest-expanding product category as innovators seek mammalian cell culture capacity that remains scarce domestically. Continuous Manufacturing technology adoption remains nascent but carries disproportionate strategic weight for clients pursuing FDA-aligned quality benchmarks.
BIS certification standards for pharmaceutical equipment and CDSCO's periodic facility inspections shape capital deployment decisions and client qualification timelines. The PLI scheme administered by the Department of Pharmaceuticals directly subsidizes domestic API production, redirecting contract manufacturing flows toward backward-integrated models. Stakeholders must monitor how CDSCO's alignment with ICH Q12 lifecycle management guidelines reshapes technology transfer obligations and long-term supply agreements.
Market Dynamics
CDSCO's tightened Good Manufacturing Practice requirements are broadening compliance costs for new entrants while favoring established operators with validated containment suites and audit-ready quality systems.
Growth Catalysts
- PLI scheme subsidies:The Department of Pharmaceuticals' production-linked incentive scheme directly subsidizes domestic API production, redirecting contract manufacturing flows toward backward-integrated models.
- Gujarat-Telangana cluster concentration:Dedicated pharmaceutical infrastructure zones in these states support large-scale formulation output with shared utilities and regulatory fast-tracking.
- Biologics capacity scarcity:Mammalian cell culture manufacturing remains scarce domestically, creating pull-through demand for CMOs investing in single-use bioreactor platforms.
Market Restraints
- Imported equipment dependency:BIS certification standards for pharmaceutical equipment create procurement friction, with 60-70% of high-purity processing hardware sourced from European and US suppliers.
- API input cost volatility:Key starting materials and intermediates face price swings tied to Chinese supply fluctuations and freight rate instability.
- Regulatory friction from CDSCO inspections:Periodic facility inspections extend client qualification timelines and delay commercial batch releases for new market entrants.
Strategic Opportunities
- Continuous Manufacturing adoption:FDA-aligned quality benchmarks from continuous processing technology create differentiation for CMOs investing in real-time release testing capabilities.
- Biologics CDMO expansion:Vaccine and biosimilar innovators seek domestic mammalian cell culture capacity that remains underdeveloped relative to small-molecule infrastructure.
- ICH Q12 alignment:CDSCO's adoption of lifecycle management guidelines reshapes technology transfer obligations, favoring CMOs with established post-approval change management protocols.
Industry Challenges
- Analytical method transfer complexity:Client-specific validated assays require 6-12 month transfer timelines, compressing effective capacity utilization at multi-client facilities.
- Containment suite capex intensity:Potent compound handling requires dedicated isolator technology and specialized HVAC systems, demanding 40-50% higher capital deployment per production line.
- Quality auditor talent scarcity:Experienced professionals capable of managing simultaneous US FDA, EMA, and CDSCO inspections command premium compensation and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Contract Manufacturing Organization (CMO) Market |
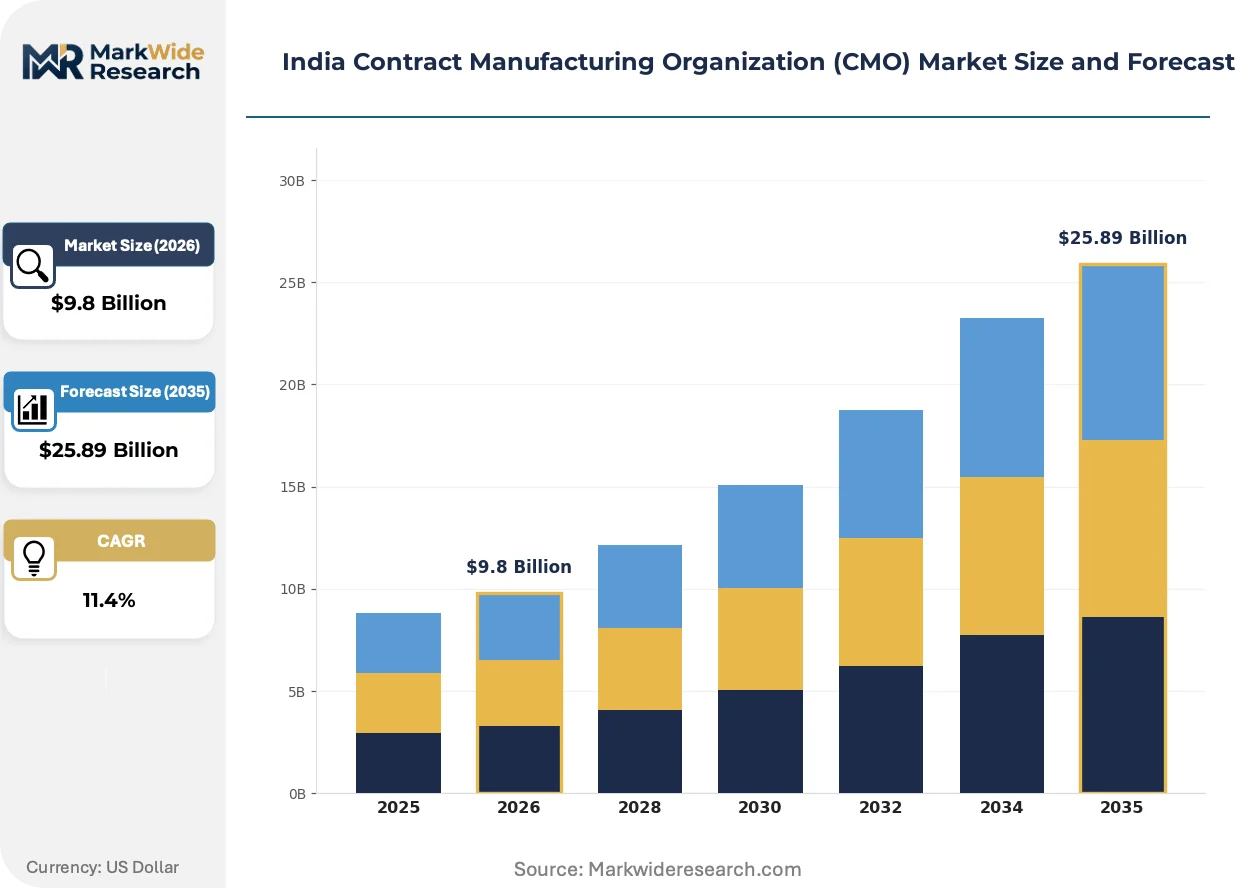
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
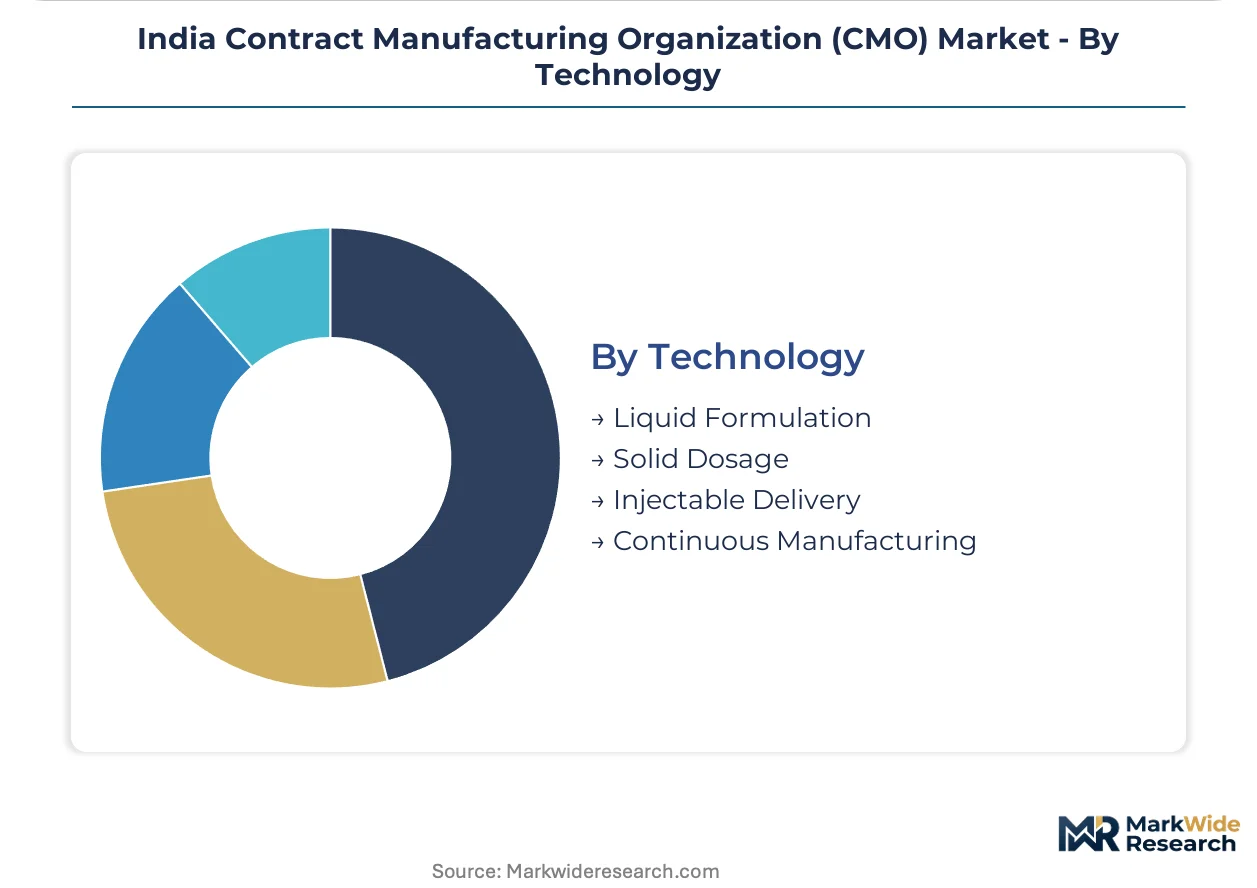
| Segmentation | Service Type: Active Pharmaceutical Ingredients, Formulations, Packaging, Labeling End User: Pharmaceutical Companies, Biotechnology Firms, Medical Device Manufacturers, Nutraceutical Providers Product Type: Generic Drugs, Biologics, Small Molecules, Specialty Pharmaceuticals Technology: Liquid Formulation, Solid Dosage, Injectable Delivery, Continuous Manufacturing |
| Companies Covered | Aurobindo Pharma Limited, Akums Drugs and Pharmaceuticals, Divi's Laboratories Limited, Protech Telelinks, Gracure Pharmaceutical, Dr. Reddy's Laboratories Limited, Zydus Lifesciences Limited, Lifevision India, Sun Pharmaceutical Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Contract Manufacturing Organization (CMO) Market Trends and Innovations
Process intensification and regulatory harmonization are compressing batch cycle times while elevating quality benchmarks across Indian pharmaceutical manufacturing.
Continuous Manufacturing technology is electrifying competitive positioning among mid-scale CMOs seeking FDA-aligned quality benchmarks. Domestic innovators and multinational subsidiaries are piloting continuous direct compression and hot-melt extrusion systems at accelerated timelines. This technology is compressing batch release timelines from weeks to days while reducing in-process material waste.
CDSCO's alignment with ICH Q12 lifecycle management guidelines is reshaping technology transfer obligations and long-term supply agreement structures. The regulator's framework now requires documented post-approval change management protocols, forcing CMOs to invest in enhanced quality systems. High-purity API manufacturers face the steepest compliance ramps, with documentation burdens extending qualification timelines.
Buyer consolidation among generic pharmaceutical innovators is concentrating procurement decisions with fewer sourcing managers managing larger contract portfolios. Large Indian formulation companies are unbundling API and finished dose manufacturing, awarding separate contracts to specialized CMOs rather than integrated suppliers. This pattern is most visible in Gujarat, where clustered infrastructure supports rapid vendor switching and competitive rebidding cycles.
India Contract Manufacturing Organization (CMO) Market Segmentation
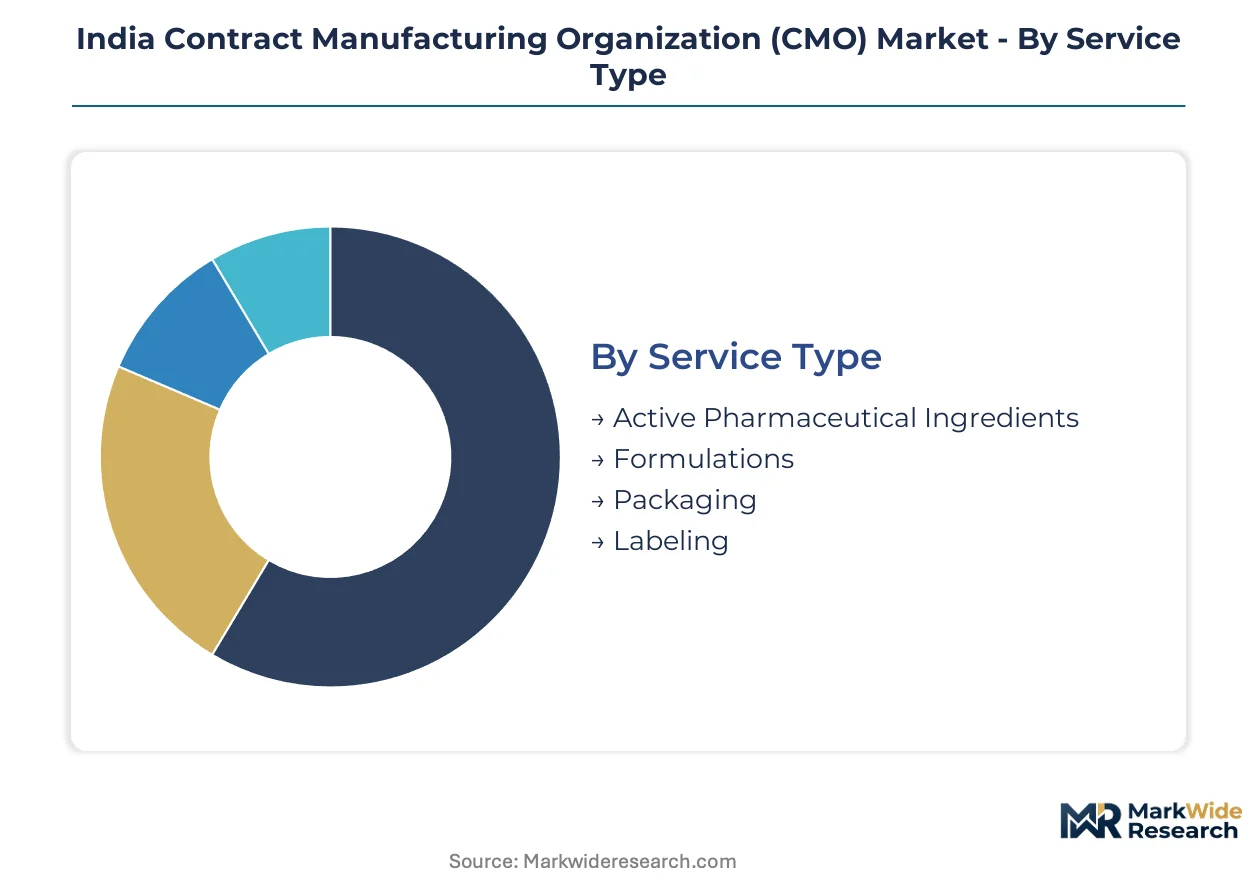
CMO procurement decisions in India diverge sharply across service depth, with API manufacturing commanding premium pricing due to technical complexity while packaging and labeling operate on volume-driven cost curves. End-user requirements further fragment the market, as biotechnology firms demand mammalian cell culture capabilities that generic pharmaceutical clients rarely specify.
Service Type:
Customization intensity varies dramatically across this spectrum, from highly tailored API synthesis requiring client-specific process validation to commoditized labeling operations with minimal technical differentiation.
- Active Pharmaceutical Ingredients:High-purity synthesis and intermediate production with containment requirements for potent compounds. Demand concentrates among Gujarat-based formulation giants seeking backward integration under PLI scheme incentives, though CDSCO's tightened GMP compliance extends qualification timelines for new entrants.
- Formulations:Finished dose manufacturing spanning tablets, capsules, and oral liquids with validated analytical methods. Telangana's clustered infrastructure supports large-scale output for domestic innovators and multinational subsidiaries, with dedicated cleanroom classifications driving site selection decisions.
- Packaging:Blister packing, bottling, and serialization for commercial distribution. Standardized equipment platforms limit differentiation, with BIS certification requirements for imported machinery creating procurement friction.
- Labeling:Primary and secondary labeling with regulatory artwork compliance. Lowest technical barrier among service types, with automation investments compressing per-unit costs at high-volume facilities.
Leading the category by volume: Formulations. Growing fastest: Active Pharmaceutical Ingredients.
End User:
Procurement scale and technical sophistication separate these buyer groups, with biotechnology firms paying 40-60% premiums for mammalian cell culture capacity that remains scarce domestically.
- Pharmaceutical Companies:Generic innovators and branded formulation specialists outsourcing production to manage capital intensity. Gujarat-Telangana cluster concentration supports rapid vendor switching and competitive rebidding cycles for multi-year supply agreements.
- Biotechnology Firms:Vaccine and biosimilar developers requiring single-use bioreactor platforms and aseptic fill-finish capabilities. Scarcity of domestic mammalian cell culture infrastructure creates supply bottlenecks for CDMOs with validated containment suites.
- Medical Device Manufacturers:Sterile device assembly and combination product manufacturing with ISO 13485 quality systems. Niche demand relative to pharmaceutical volumes, with specialized HVAC requirements elevating facility costs.
- Nutraceutical Providers:Dietary supplement and functional food production with FSSAI compliance obligations. Lower regulatory stringency than pharmaceutical clients, attracting CMOs seeking capacity diversification.
Dominating procurement volumes: Pharmaceutical Companies. Expanding most quickly: Biotechnology Firms.
Product Type:
Margin profiles and regulatory pathways distinguish these categories, with specialty pharmaceuticals requiring dedicated isolator technology while generic drugs compete on batch scale and cost efficiency.
- Generic Drugs:Off-patent small-molecule formulations with established bioequivalence pathways. Volume concentration in Gujarat supports economies of scale, though buyer consolidation among Indian generic giants intensifies pricing pressure.
- Biologics:Mammalian cell-derived proteins and biosimilars demanding specialized fermentation and purification infrastructure. Fastest-climbing segment as innovators seek domestic alternatives to imported capacity, with CDSCO's ICH Q12 alignment reshaping technology transfer obligations.
- Small Molecules:Synthetic organic compounds across therapeutic categories with validated synthetic routes. Mature demand base with established CMO relationships, limiting new entrant penetration.
- Specialty Pharmaceuticals:Potent compounds and controlled substances requiring dedicated containment suites and specialized waste handling. Isolator technology investments demand 40-50% higher capital deployment per production line, restricting supplier base.
Highest volume segment: Generic Drugs. Steepest expansion trajectory: Biologics.
Technology:
Process maturity and capital intensity separate these manufacturing approaches, with continuous manufacturing carrying disproportionate strategic weight despite limited installed base.
- Liquid Formulation:Solutions, suspensions, and emulsions with validated mixing and homogenization protocols. Standard demand from pediatric and geriatric dosage requirements, with established equipment platforms limiting differentiation.
- Solid Dosage:Tablet compression and capsule filling with direct compression or granulation pathways. Dominant technology by unit volume, with process analytical technology adoption accelerating batch release timelines.
- Injectable Delivery:Parenteral formulations requiring aseptic processing and terminal sterilization capabilities. CDSCO inspection intensity elevates compliance costs, favoring established operators with audit-ready quality systems.
- Continuous Manufacturing:Real-time processing with integrated direct compression or hot-melt extrusion systems. Nascent adoption compressing batch release from weeks to days, creating FDA-aligned differentiation for mid-scale CMOs investing early.
Widest installed base: Solid Dosage. Gaining share fastest: Continuous Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical Special Economic Zones in Gujarat and Telangana concentrate India's contract manufacturing capacity, with dedicated infrastructure zones offering shared utilities and regulatory fast-tracking for formulation and API production.
Gujarat
Ahmedabad and Vadodara host the densest cluster of formulation facilities serving domestic generic innovators. CDSCO's tightened GMP requirements favor established operators with validated containment suites. The state's Dedicated Pharmaceutical Infrastructure Zones support large-scale tablet and capsule output with centralized waste handling and environmental clearances.
Telangana
Hyderabad's Genome Valley and surrounding industrial corridors anchor biologics and vaccine manufacturing investments. The Department of Pharmaceuticals' PLI scheme redirects API production flows toward backward-integrated models in this corridor. Mammalian cell culture capacity remains underdeveloped relative to small-molecule infrastructure, creating supply bottlenecks for CDMOs with single-use bioreactor platforms.
Maharashtra
Mumbai-Pune industrial belt concentrates injectable and sterile formulation capacity for export markets. BIS certification standards for imported pharmaceutical equipment create procurement friction for facility upgrades. The region's analytical testing laboratories and logistics connectivity support rapid technology transfer for multinational subsidiaries.
Karnataka
Bengaluru's biotechnology corridor attracts vaccine innovators seeking domestic manufacturing alternatives to imported capacity. CDSCO's alignment with ICH Q12 lifecycle management guidelines reshapes post-approval change management protocols for local CMOs. The state's IT infrastructure supports process analytical technology adoption for real-time release testing capabilities.
Andhra Pradesh
Visakhapatnam's pharma city development targets API intermediate production under PLI scheme subsidies. FSSAI compliance obligations for nutraceutical manufacturing attract CMOs seeking capacity diversification. The region's port connectivity reduces freight cost exposure for export-oriented formulation output.
India Contract Manufacturing Organization (CMO) Market Competitive Landscape
Gujarat-based producers anchor one tier with integrated API-to-formulation capabilities; Telangana specialists hold differentiated positions in biologics and high-purity synthesis. The market structure tilts toward established operators with audit-ready quality systems and multi-regulatory inspection histories. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, standalone API specialists with containment expertise, and diversified CDMOs spanning multiple dosage platforms. Capacity expansion and technology licensing represent the dominant competitive moves, with continuous manufacturing adoption creating FDA-aligned differentiation for mid-scale entrants.
Among integrated pharmaceutical conglomerates, Aurobindo Pharma Limited and Dr. Reddy's Laboratories Limited exemplify the API-to-formulation archetype with validated multi-dosage capabilities. Divi's Laboratories Limited occupies a distinct position as a high-purity API specialist serving global innovators. Akums Drugs and Pharmaceuticals represents the diversified CDMO model with broad therapeutic category coverage. These three anchors illustrate how scale, specialization, and service breadth segment competitive positioning across India's contract manufacturing base.
| Leading Market Players |
|---|
| Aurobindo Pharma Limited |
| Akums Drugs and Pharmaceuticals |
| Divi's Laboratories Limited |
| Protech Telelinks |
| Gracure Pharmaceutical |
| Dr. Reddy's Laboratories Limited |
| Zydus Lifesciences Limited |
| Lifevision India |
| Sun Pharmaceutical Industries Limited |
| Others |
Pricing and Supply Chain Analysis
Continuous Manufacturing technology adoption is compressing batch economics while redrawing competitive tiers, as CMOs with FDA-aligned real-time release capabilities capture premium positioning against conventional batch operators facing cost pressure from extended CDSCO qualification timelines.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent spot orders commanding substantial premiums from scheduled contract volumes securing preferential rates. Three-tier pricing structure across premium, standard, and economy levels reflects containment suite certification grade and volume commitment scale, with CDSCO audit-ready facilities capturing the premium tier. Cost compression in standard formulations is intensifying because buyer consolidation among Indian generic giants concentrates procurement leverage with fewer sourcing managers. Biotechnology firms show least price sensitivity due to mammalian cell culture scarcity, while generic pharmaceutical companies drive aggressive rebidding cycles.
Supply Chain Analysis
Freight rate instability and port congestion at Mundra and Visakhapatnam elevate landed costs for imported high-purity processing equipment, with 60-70% of containment hardware sourced from Germany, Switzerland, and the United States. API input supply draws from China, India, and select European intermediates hubs, with key starting materials facing volatility tied to Chinese environmental enforcement cycles. Single-source vulnerability concentrates in advanced isolator technology and single-use bioreactor platforms. Distribution runs through direct long-term supply agreements with multinational subsidiaries and domestic formulation giants, bypassing spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic mammalian cell culture capacity scarcity props pricing power for qualified CDMOs, creating a supply-constrained market structure where validated containment assets command sustained premium positioning.
For Market Incumbents: Cement multi-regulatory inspection readiness as the primary defensive moat against emerging entrants with greenfield continuous manufacturing investments. Prioritize capacity addition in Telangana's Genome Valley corridor to capture biologics demand pull-through. Deepen backward integration into API intermediates under PLI scheme subsidies to defend margin position against unbundling trends. For New Entrants and Emerging Players: Vaccine innovators seeking domestic alternatives to imported mammalian cell culture capacity represent the most penetrable buyer archetype for specialized CDMO positioning. Target Andhra Pradesh's Visakhapatnam pharma city development for API intermediate production under subsidized cost structures. Pursue technology licensing partnerships with European equipment suppliers to accelerate BIS certification timelines and bypass procurement friction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated pharmaceutical conglomerates seeking to unbundle manufacturing capabilities. Long-term viability hinges on CDSCO's ICH Q12 alignment trajectory and the pace of continuous manufacturing adoption across the installed base. Monitor CDSCO facility inspection backlog clearance rates as the critical inflection indicator for qualification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Adoption | Real-time release testing capabilities differentiate mid-scale CMOs seeking FDA-aligned quality benchmarks from conventional batch operators. |
| Biologics CDMO Capacity Expansion | Single-use bioreactor platform investments address mammalian cell culture scarcity that constrains vaccine and biosimilar domestic production. |
| PLI Scheme-Anchored Backward Integration | API intermediate production subsidies redirect contract manufacturing flows toward captive supply models in Gujarat and Telangana clusters. |
| Multi-Regulatory Quality System Investment | Simultaneous US FDA, EMA, and CDSCO audit readiness commands premium positioning as compliance costs broaden for new market entrants. |
| Technology Transfer Protocol Enhancement | ICH Q12-aligned post-approval change management capabilities reshape long-term supply agreement structures for global innovator clients. |
Research Methodology
Independent corroboration across CDSCO regulatory filings, PLI scheme disbursement records, and pharmaceutical equipment import manifests underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and containment technology suppliers combined with secondary validation from FDA Form 483 observations, EMA inspection reports, and BIS certification databases. Bottom-up facility capacity assessments and top-down market size triangulation anchored the quantitative framework.
Rate-of-change decomposition across the analysis window isolated volume growth from pricing dynamics and mix shift effects. Segmentation dimensions modeled include service type depth, end-user technical sophistication, product type regulatory pathway, and technology platform maturity. CAGRs derived from facility expansion announcements, technology licensing disclosures, and client contract duration patterns. Forecast inputs incorporated CDSCO inspection throughput assumptions and PLI scheme renewal probability.
Revisions become necessary when CDSCO aligns additional ICH guidelines beyond Q12, when PLI scheme subsidy rates materially adjust, or when continuous manufacturing technology adoption accelerates beyond pilot-scale deployment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Closed Funnel Ampoules Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Automated Drug Kiosk Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market