
 Global Medical Packaging Market | 2026-2036
Global Medical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Packaging Market Foresight
ISO 11607 compliance for sterile barrier systems is rotating the competitive landscape toward manufacturers with validated cleanroom operations and established regulatory dossiers. Amcor Plc leverages its multi-continent film extrusion network to serve pharmaceutical clients with consistent sterility assurance. Berry Global Inc. sustains pouch and closure leadership through deep polymer science capabilities and healthcare-dedicated production lines.
Medical packaging encompasses materials and engineered containers designed to maintain sterility, protect against contamination, and ensure traceability of healthcare products through distribution and clinical use; typical constructions employ multi-layer coextruded films, medical-grade papers, or borosilicate glass with defined barrier properties against moisture, oxygen, and microbial ingress. Blister packs dominate solid-dose pharmaceutical dispensing due to compliance with unit-dose tracking requirements, while biopolymers represent the fastest-expanding material class as European healthcare procurement shifts toward carbon-accountable supply chains. Pouches capture growing share in sterilization wrap and kit applications where flexibility and breathability balance cost against performance.
FDA enforces strict biocompatibility and extractables testing through 21 CFR Part 211, while the EU MDR imposes Unique Device Identification and post-market surveillance obligations that cascade into packaging serialization mandates. ISO 11607 and ASTM F2097 provide the technical backbone for sterile barrier validation, with notified bodies in Germany and the Netherlands conducting the bulk of European conformity assessments. Stakeholders must monitor evolving EUDAMED integration timelines and FDA guidance on human factors in packaging design to anticipate compliance-driven sourcing shifts.
Market Dynamics
EU MDR compliance deadlines and FDA sterile barrier validation requirements are compressing supplier qualification timelines, forcing pharmaceutical manufacturers to consolidate sourcing around packaging partners with pre-validated cleanroom infrastructure and established regulatory dossiers.
Growth Catalysts
- Biologics expansion:Cell and gene therapy manufacturing in Germany, the United States, and China is multiplying demand for cold-chain-compatible barrier systems with validated thermal protection.
- EU MDR serialization mandates:Unique Device Identification requirements are compelling packaging line upgrades across European contract manufacturers, expanding the addressable market for integrated label-printing solutions.
- Sustainability procurement shifts:Carbon-accountable supply chain policies in European healthcare systems are accelerating adoption of bio-based films and recyclable multi-layer structures.
Market Restraints
- Medical-grade polymer supply concentration:Specialty resin production clusters in the US Gulf Coast and northwestern Europe create geographic vulnerability to weather disruptions and energy price spikes.
- Cleanroom capex intensity:ISO 14644 Class 7-8 facility construction requires capital deployment that excludes smaller regional converters from sterile barrier qualification.
- Glass substitution threat:Borosilicate vials face displacement from advanced cyclic olefin polymers in mRNA vaccine containment, constraining traditional glass packaging volume growth.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO alignment with ICH Q1A stability guidelines creates opening for pre-qualified barrier suppliers serving API-to-formulation integrators.
- Home healthcare infusion kits:Self-administered biologic therapies require patient-centric pouch designs with intuitive tear initiation and dose verification features.
- Digital watermark integration:Convergence of printed electronics with flexible films enables unit-level authentication without secondary label application.
Industry Challenges
- Extractables testing capacity:ISO 10993-18 analytical chemistry expertise scarcity extends validation timelines for novel coextruded structures.
- Legacy ERP integration:Serialization data exchange between packaging execution systems and pharmaceutical manufacturing execution platforms creates implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Packaging Market |
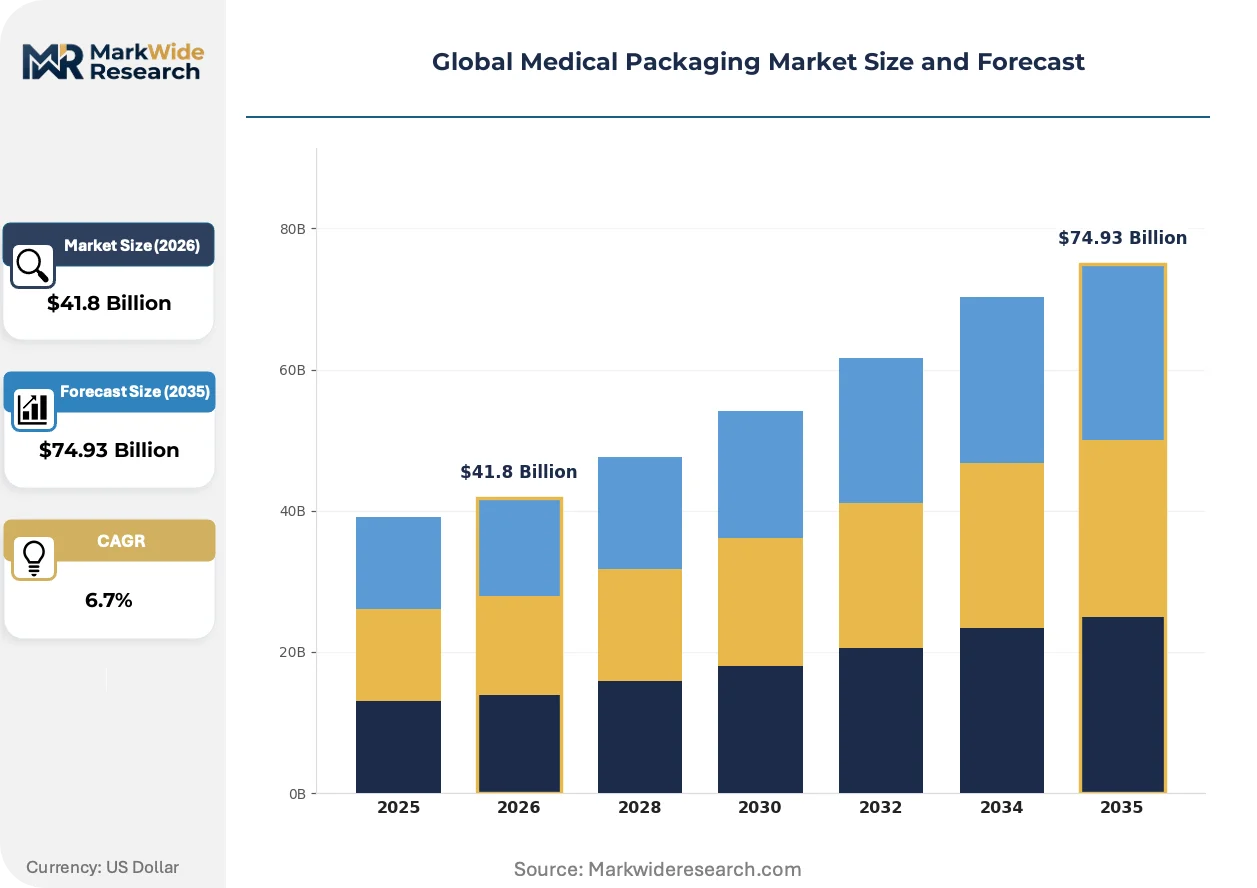
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $74.93 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Aluminum, Paperboard, Foil, Biopolymers Packaging Format: Blister Packs, Bottles, Pouches, Vials, Ampoules, Trays Application: Pharmaceuticals, Diagnostics, Surgical Instruments, Injectable Drugs, Dental Products, Veterinary Supplies End User: Hospitals, Clinics, Laboratories, Pharmacies, Research Institutes, Home Healthcare |
| Companies Covered | Amcor Plc, Berry Global Inc., DuPont de Nemours Inc., 3M Company, WestRock Company, Gerresheimer AG, Schott AG, AptarGroup, Inc., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Packaging Market Shifts & Advancements
Active and intelligent packaging technologies are migrating from pharmaceutical logistics into primary sterile barriers, embedding sensors and indicators directly into pouch and tray constructions rather than applying them as secondary components.
Multi-layer coextruded films with embedded oxygen scavengers and humidity indicators are fragmenting the traditional separation between primary packaging and supply chain monitoring. Large molecule biologics manufacturers in Switzerland and Massachusetts are specifying these integrated structures for high-value parenteral products. The technology is compressing qualification timelines by combining barrier and monitoring validation into single dossier submissions.
REACH restriction proposals on per- and polyfluoroalkyl substances are compelling European converters to reformulate fluoropolymer-based heat-seal layers before 2027 enforcement windows. Medical device manufacturers with EU MDR certificates expiring in 2026-2027 are accelerating alternative material validation to avoid supply interruption. German notified bodies are experiencing backlog surge for revised technical documentation supporting PFAS-free barrier claims.
Hospital supply chain consolidation is compressing vendor management bandwidth, driving preference for packaging suppliers offering consolidated sterile barrier, labeling, and kitting services. Integrated delivery networks in Texas and California are reducing qualified supplier lists from dozens to single-digit portfolios. This concentration rewards converters with redundant cleanroom capacity across multiple geographic nodes.
Global Medical Packaging Market Segmentation
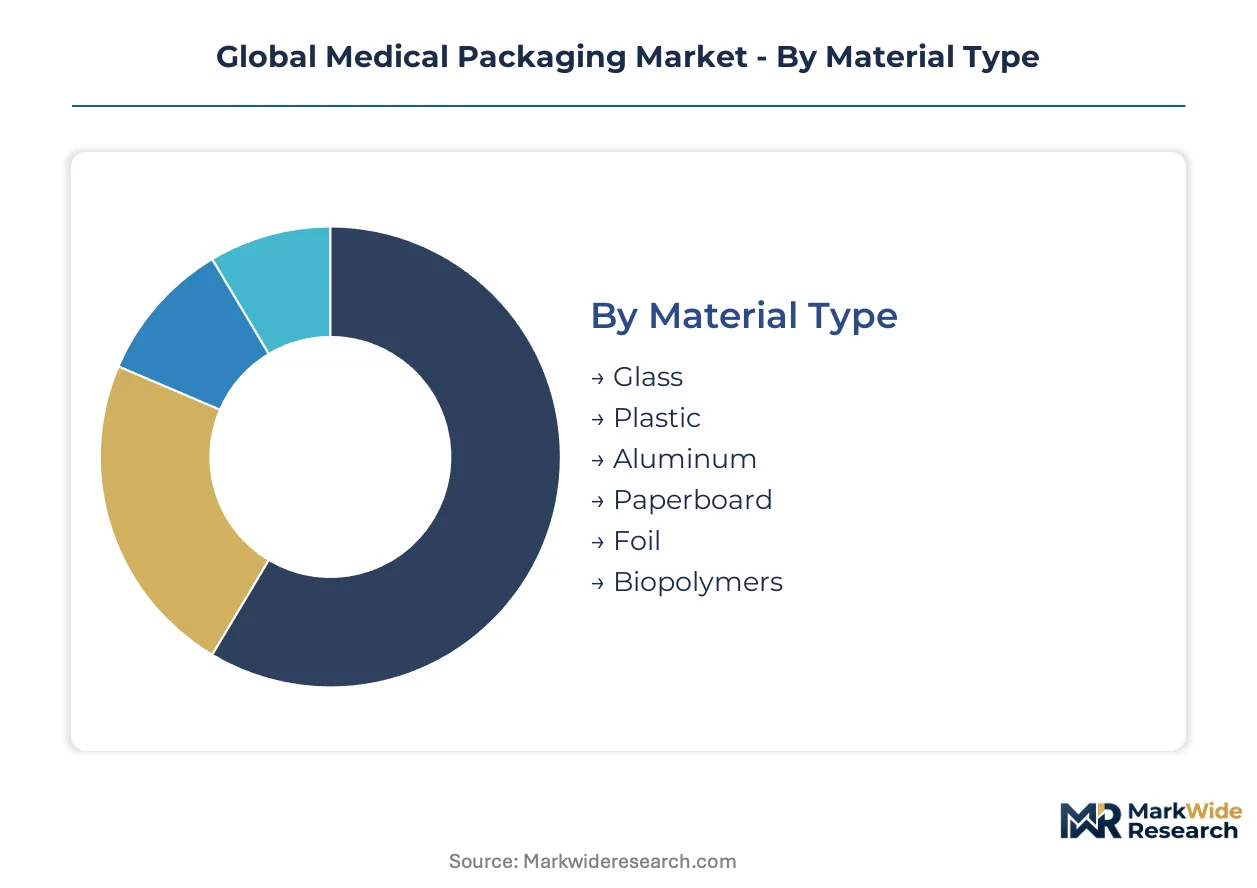
Medical packaging segmentation reveals how material science, format engineering, and end-use requirements intersect to determine procurement priorities. Each dimension carries distinct regulatory burdens and channel economics that reshape supplier selection criteria across pharmaceutical and device manufacturing.
Material Type:
Channel flow varies sharply by material chemistry — glass and aluminum dominate institutional procurement through direct manufacturer contracts, while plastics and biopolymers route increasingly through consolidated healthcare distributors responding to carbon-accountability mandates.
- Glass:Borosilicate and soda-lime compositions deliver inert containment for parenteral biologics with validated extractables profiles. Demand concentrates in Swiss and Massachusetts biologics clusters where mRNA and cell therapy manufacturers specify Type I borosilicate for protein stability assurance.
- Plastic:Cyclic olefin polymers and multilayer coextruded films enable flexible sterile barriers with tunable oxygen and moisture transmission rates. German and Chinese converters are expanding cyclic olefin copolymer capacity to serve cold-chain vaccine distribution networks.
- Aluminum:Cold-form foil laminates provide absolute moisture barrier for hygroscopic solid-dose formulations in tropical distribution.
- Paperboard:Medical-grade kraft and sulfate papers serve sterilization wrap and secondary carton applications where breathability meets printability.
- Foil:Aluminum-polymer laminates form peelable lidstock for thermoformed trays in surgical kit presentation.
- Biopolymers:Polylactic acid and bio-based polyethylene are gaining procurement traction in European hospital systems with Scope 3 emission reduction targets.
By volume, plastic leads. By growth pace, biopolymers are climbing the fastest.
Packaging Format:
Format selection tracks administration setting — hospital-centric formats prioritize sterility assurance and rapid opening, while home healthcare formats emphasize patient handling and dose verification.
- Blister Packs:Thermoformed PVC or aluminum cavities with lidding foil enable unit-dose accountability for oral solid medications. North American and European contract manufacturers are retrofitting lines with integrated vision inspection to meet EU MDR serialization mandates.
- Bottles:High-density polyethylene and polypropylene containers with child-resistant closures dominate outpatient prescription dispensing.
- Pouches:Tyvek and film combinations balance microbial barrier with gas permeability for ethylene oxide sterilization of surgical instruments.
- Vials:Borosilicate and polymer vials contain injectable and lyophilized biologics with elastomeric closure integrity.
- Ampoules:Glass ampoules provide single-use sterile containment for emergency and anesthetic applications.
- Trays:Thermoformed PETG and HIPS structures organize multi-component surgical kits with instrument fixation features.
Blister packs command the largest production volume. Pouches are expanding most quickly through sterilization service outsourcing.
Application:
Application segmentation aligns with regulatory pathway intensity — pharmaceutical and injectable applications carry FDA 21 CFR Part 211 and EU GMP Annex 1 compliance burdens that elevate barrier validation requirements above diagnostic or veterinary segments.
- Pharmaceuticals:Solid oral, topical, and respiratory dosage forms require moisture and light protection with child-resistant features where mandated. German and Indian formulation exporters are driving demand for stability-validated primary containers aligned with ICH Q1A guidelines.
- Diagnostics:Test kits and reagent containment prioritize shelf-life extension through desiccant integration and foil barrier layers.
- Surgical Instruments:Sterile barrier systems for reusable and single-use instruments must withstand sterilization cycles and maintain integrity through distribution.
- Injectable Drugs:Parenteral containers face the most stringent particulate and endotoxin specifications, with glass and advanced polymer vials competing for biologics containment.
- Dental Products:Sterile and non-sterile packaging for instruments and materials balances clinical presentation with cost constraints.
- Veterinary Supplies:Animal health packaging applies pharmaceutical-grade barriers with modified child-resistance and labeling requirements.
Pharmaceuticals generate the highest revenue concentration. Injectable drugs are gaining share fastest through biologics volume expansion.
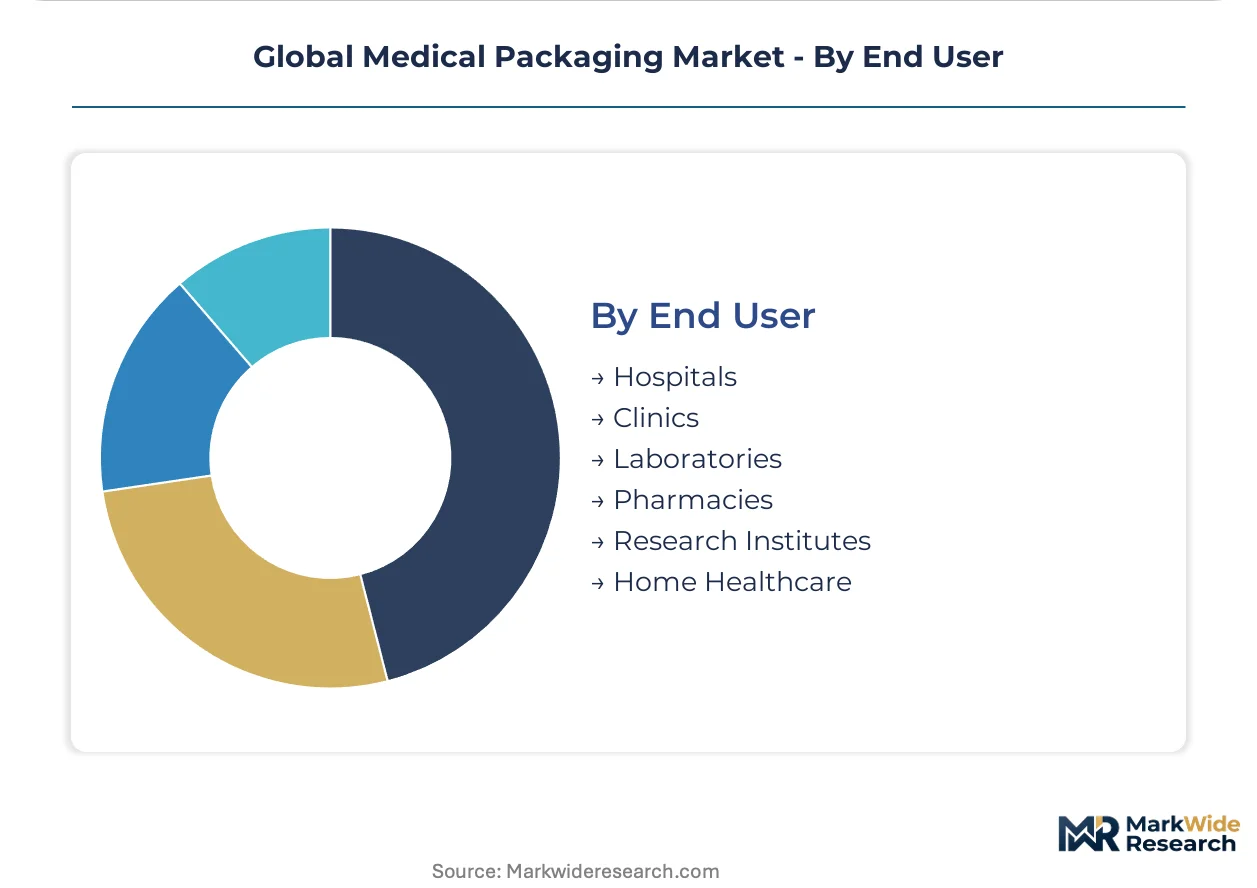
End User:
End-user channel structure determines packaging specification authority — hospitals and integrated delivery networks consolidate purchasing power, while home healthcare decentralizes decision-making toward patient-centric design requirements.
- Hospitals:Acute care facilities specify sterile barrier systems for surgical supplies and unit-dose pharmaceuticals with supply chain traceability. Texas and California integrated delivery networks are reducing qualified packaging suppliers to single-digit portfolios.
- Clinics:Outpatient settings prioritize cost-efficient primary containers with adequate shelf-life protection for moderate-volume dispensing.
- Laboratories:Diagnostic and research facilities require contamination-resistant containment for reagents and specimens with temperature stability.
- Pharmacies:Retail and specialty pharmacies drive demand for adherence packaging and child-resistant compliance.
- Research Institutes:Preclinical and clinical trial materials require protocol-specific labeling and chain-of-custody documentation.
- Home Healthcare:Self-administered therapy packaging demands intuitive opening, dose verification, and disposal features for patient safety.
Hospitals represent the largest addressable spend. Home healthcare is expanding most quickly through biologic self-injection therapy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's biologics distribution dominance, while China's high-speed rail pharmaceutical corridors connect manufacturing clusters to domestic hospitals and export terminals.
United States
FDA sterile barrier validation requirements and biologics manufacturing expansion in Massachusetts and North Carolina are compressing supplier qualification timelines. The 21 CFR Part 211 enforcement framework elevates packaging partners with pre-validated cleanroom dossiers. Greater Boston's cell therapy cluster specifies cold-chain-compatible barrier systems with embedded thermal protection.
Germany
EU MDR serialization mandates and notified body concentration in Berlin and Munich are accelerating packaging line upgrades across contract manufacturers. REACH restriction proposals on per- and polyfluoroalkyl substances compel converters to reformulate heat-seal layers before enforcement windows. The Rhine-Main biopharma corridor anchors sterile barrier demand for parenteral biologics export.
China
NMPA alignment with ICH stability guidelines and domestic biologics capacity expansion in Shanghai and Suzhou are multiplying demand for validated primary containers. The country's dual carbon goals pressure converters toward bio-based film adoption. Yangtze River Delta vaccine manufacturers specify cyclic olefin polymer capacity for mRNA containment.
Switzerland
Swissmedic's stringent extractables testing requirements and Basel's biologics manufacturing density create premium demand for Type I borosilicate vials. The country's pharmaceutical export orientation necessitates multi-language serialization compliance. Romandy region converters specialize in high-value parenteral packaging for global clinical trial distribution.
India
CDSCO harmonization with ICH Q1A guidelines and API-to-formulation integration in Hyderabad and Ahmedabad create openings for pre-qualified barrier suppliers. The country's pharmaceutical export growth drives stability-validated primary container demand. Maharashtra's formulation clusters specify moisture-barrier systems for tropical distribution networks.
Global Medical Packaging Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier depth and cleanroom network reach. The market structures around three tiers: diversified materials conglomerates with healthcare-dedicated divisions, pure-play medical packaging converters with notified body relationships, and regional specialists serving single geography export markets. Consolidation pressure intensifies as pharmaceutical manufacturers reduce qualified supplier lists. Dominant competitive moves include M&A for cleanroom capacity acquisition and strategic partnerships for integrated kitting services.
Within the diversified conglomerate tier, Amcor Plc and Berry Global Inc. exemplify scale-driven positioning through multi-continent film extrusion networks. DuPont de Nemours Inc. occupies a materials science anchor role. Among European specialists, Gerresheimer AG and Schott AG represent glass containment expertise. These named entities illustrate how regulatory dossier depth and geographic redundancy determine sourcing consolidation outcomes.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| DuPont de Nemours Inc. |
| 3M Company |
| WestRock Company |
| Gerresheimer AG |
| Schott AG |
| AptarGroup, Inc. |
| Sonoco Products Company |
| Others |
Supply & Pricing Matrix
Cleanroom capacity utilization above 85 percent in Germany and the United States simultaneously compresses marginal cost curves and elevates price floors for sterile barrier qualification. Pharmaceutical manufacturers facing EU MDR deadlines absorb premium pricing for pre-validated supply, while converters with redundant ISO 14644 Class 7-8 facilities capture disproportionate margin expansion.
Pricing Analysis
Volume-discount tiering structures separate global pharmaceutical manufacturers from mid-tier contract manufacturers and regional generic producers. Certification grade—specifically FDA 21 CFR Part 211 dossier completeness and EU MDR notified body alignment—drives price differentiation above resin cost or format complexity. Pricing pressure stems from REACH restriction timelines compelling PFAS-free reformulation investment. Regional generic producers exhibit highest price sensitivity, while cell therapy manufacturers in Massachusetts and Basel demonstrate inelastic demand for validated cold-chain barriers.
Supply Chain Analysis
Germany, the United States, and China anchor specialty resin production and sterile barrier conversion capacity for biologics containment. Medical-grade cyclic olefin polymer and multilayer coextruded film production draws from petrochemical feedstocks concentrated on the US Gulf Coast and in northwestern Europe. Single-source vulnerability to energy price spikes and weather disruptions at these production nodes elevates supply risk. Distribution runs through consolidated healthcare distributors and direct manufacturer contracts to hospital integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR serialization mandates and REACH restriction deadlines constitute simultaneous regulatory inflections accelerating competitive consolidation. The market rewards capability depth over geographic breadth.
For Market Incumbents: Consolidate cleanroom capacity acquisitions in the Rhine-Main and Greater Boston corridors to defend against PFAS-free material substitution threats. Deepen backward integration into medical-grade polymer resin supply through captive production or long-term offtake with US Gulf Coast and northwestern European petrochemical complexes. Prioritize ISO 10993-18 extractables testing laboratory certification to compress validation timelines for novel barrier structures.
For New Entrants and Emerging Players: Patient-centric design capabilities for home healthcare infusion kits represent an under-served service layer where incumbents optimize for hospital throughput rather than intuitive handling. Target Indian pharmaceutical export packaging where CDSCO-ICH Q1A alignment creates qualification gaps for pre-validated barrier suppliers. Pursue strategic partnerships with European contract manufacturers facing EU MDR line upgrade deadlines as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play medical packaging converters with established notified body relationships over diversified materials conglomerates. Five-to-ten year viability rests on regulatory dossier depth rather than scale economies alone. Acquisition targets should demonstrate redundant cleanroom capacity across multiple geographic nodes. The signal to watch is EUDAMED integration timeline acceleration compressing supplier qualification windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 Class 7-8 facilities in Germany and Massachusetts capture biologics manufacturer consolidation. |
| PFAS-Free Material Reformulation | REACH restriction compliance before 2027 enforcement avoids supply interruption for EU MDR certificate holders. |
| Extractables Testing Laboratory Certification | ISO 10993-18 analytical chemistry capability shortens validation timelines for novel coextruded structures. |
| Integrated Kitting Service Partnership | Consolidated sterile barrier, labeling, and kitting offerings match hospital vendor reduction mandates in Texas and California. |
| Cold-Chain Barrier Validation | Embedded thermal protection specifications align with cell and gene therapy distribution requirements from Basel and Boston clusters. |
Research Methodology
A standing panel of pharmaceutical packaging engineers, regulatory affairs specialists, hospital procurement directors, and sterile barrier quality managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EU MDR technical documentation requirements, ISO 11607 and ASTM F2097 standards, EUDAMED implementation timelines, and REACH restriction proposal filings. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from pharmaceutical manufacturing capacity expansion announcements and healthcare distributor procurement data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated material type, packaging format, application, and end-user channel dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from trend extrapolation of pharmaceutical production growth, biologics capacity expansion, and sterile barrier qualification velocity. Industry-specific forecast inputs included notified body backlog data and cleanroom construction permit filings.
Material uncertainties—regulatory timeline delays, energy price volatility at resin production nodes, and PFAS substitution technical failures—sit outside the modeled envelope. Forecasts reflect assumptions about EUDAMED integration pace and REACH enforcement adherence. Recalibration cycles align with material shifts in EU MDR certificate expiry schedules and biologics manufacturing capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
Syringe Trays Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
Asia-Pacific Medical Devices Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
Medical Diagnostic Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Middle East and Africa Parenteral Packaging Market
Medical Devices Packaging
Sterile Wraps Market