
 Asia-Pacific Medical Devices Packaging Market | 2026-2036
Asia-Pacific Medical Devices Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Devices Packaging Market Outlook
Packaging engineering talent is rotating from consumer goods into medical-grade sterile barrier development across East and Southeast Asia. Amcor Plc leverages its regional film extrusion footprint to supply multilayer coextrusion materials for high-risk device classes. Berry Global Inc. sustains competitive positioning through blow-fill-seal capacity expansion targeting ophthalmic and injectable formats. Mitsubishi Chemical Group Corp. dominates engineering polymer supply for clear, sterilizable rigid trays used in Japan's precision instrument sector.
Asia-Pacific medical devices packaging encompasses engineered sterile barrier systems, typically constructed from medical-grade polyethylene terephthalate glycol, ethylene vinyl alcohol copolymers, or fluoropolymer films, manufactured through thermoforming, blow-fill-seal, or pouch sealing processes under ISO 11607 and ISO 15378 standards to maintain sterility assurance levels through distribution and clinical use. Sterilization pouches lead product type demand due to universal applicability across low to medium risk devices, while syringe packaging records the fastest expansion trajectory driven by prefillable format adoption in biologics administration. Plastic materials anchor volume given thermoformability and gas barrier performance, though paper-based alternatives are gaining structural share in sustainability-focused European-export supply chains serving the region.
Japan's PMDA enforces packaging integrity requirements under Pharmaceutical and Medical Device Act quality standards, while China's NMPA aligns medical device packaging with GB/T 19633 national standards and dual carbon goals affecting material selection. Australia's TGA and South Korea's MFDS impose parallel sterilization validation protocols that shape supplier qualification timelines for Asia-Pacific market access. Stakeholders must monitor evolving extended producer responsibility frameworks and biocompatibility testing harmonization across these jurisdictions to anticipate compliance cost trajectories and material substitution thresholds.
Market Dynamics
Japan's PMDA and China's NMPA are tightening packaging integrity mandates simultaneously, forcing sterile barrier suppliers to requalify materials under dual regulatory regimes while cardiovascular device manufacturers accelerate adoption of advanced multilayer coextrusion systems.
Growth Catalysts
- Prefillable syringe formats:Biologics administration in China's Yangtze River Delta medical manufacturing cluster is accelerating demand for blow-fill-seal packaging systems with enhanced gas barrier properties.
- India's CDSCO quality mandates:Tightened material compliance requirements in the Gujarat pharmaceutical-device corridor are driving domestic converters toward ISO 15378-certified production lines.
- Sterilization validation protocols:South Korea's MFDS and Australia's TGA are harmonizing sterilization assurance testing, reducing supplier qualification timelines for regional market access.
Market Restraints
- Engineering polymer supply concentration:Clear, sterilizable rigid tray production depends on Mitsubishi Chemical Group's regional polymer supply, creating single-source vulnerability for Japan's precision instrument sector.
- Extended producer responsibility frameworks:China's dual carbon goals and emerging EPR schemes are forcing material substitutions before alternative supply chains achieve scale.
- Biocompatibility testing fragmentation:ISO 11607 harmonization lags behind national implementation timelines, extending validation cycles for multilayer film structures.
Strategic Opportunities
- Southeast Asia contract manufacturing:Vietnam and Indonesia's underdeveloped sterile barrier infrastructure presents first-mover advantages for ISO-certified pouch and tray suppliers.
- Paper-based alternatives:Sustainability-focused European-export supply chains serving Asia-Pacific are creating structural demand for fiber-based sterile barriers in low-risk device categories.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting packaging converters to establish captive supply within the Gujarat pharmaceutical-device corridor.
Industry Challenges
- Packaging engineering talent migration:Cross-industry rotation from consumer goods into medical-grade sterile barrier development creates knowledge gaps in ISO 11607 validation protocols.
- Thermoforming equipment capex intensity:Medical-grade multilayer coextrusion lines require dedicated cleanroom infrastructure, compressing margins for mid-scale converters.
- Legacy sterilization method integration:Ethylene oxide and gamma irradiation validation documentation must align with emerging vaporized hydrogen peroxide standards, complicating dual-protocol manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Devices Packaging Market |
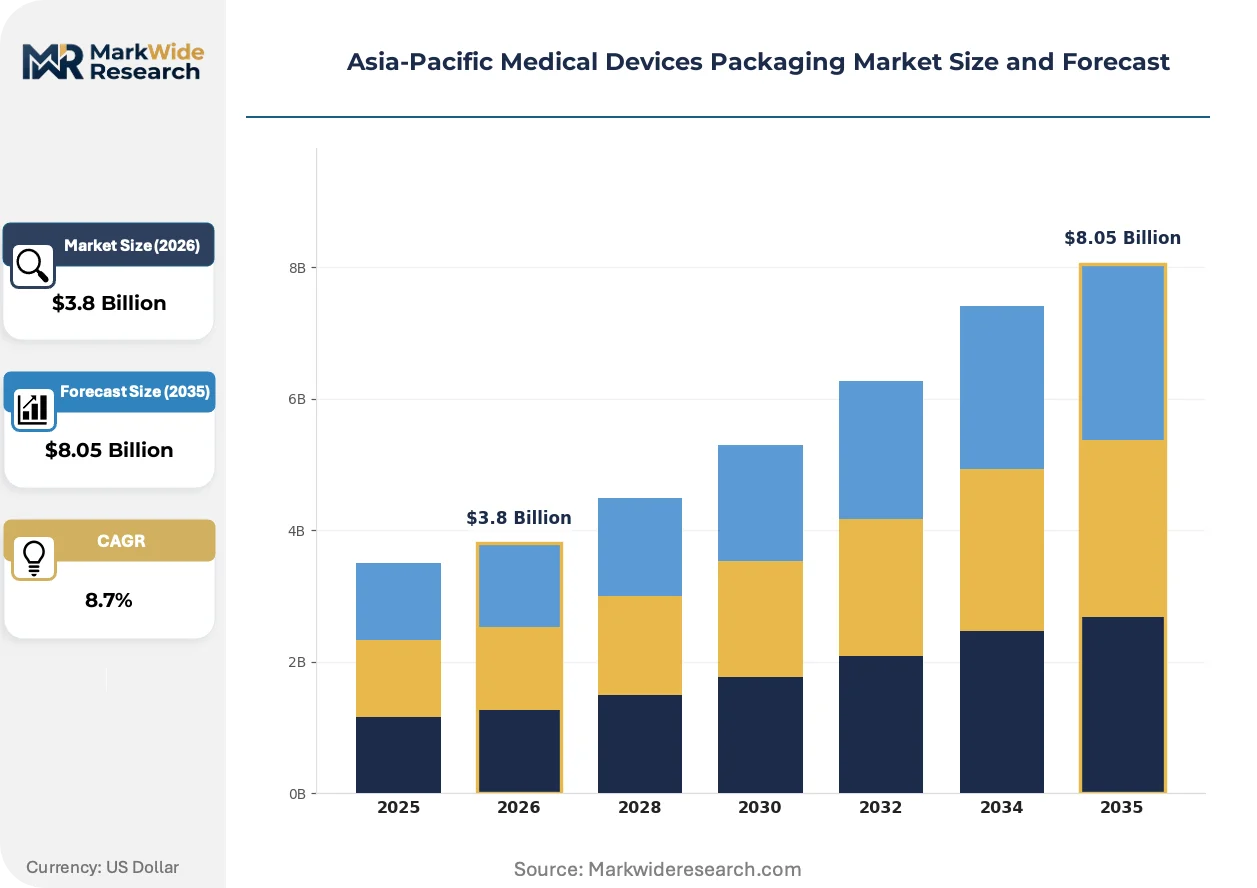
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringe Packaging, Surgical Instrument Trays, Sterilization Pouches, IV Solutions Packaging Material: Plastic, Paper, Glass, Metal Application: Cardiovascular Devices, Orthopedic Devices, Diagnostic Devices, Surgical Devices End User: Hospitals, Clinics, Laboratories, Home Care Settings |
| Companies Covered | Smurfit WestRock, Berry Global Inc., Amcor Plc, WestRock Company, Bemis Manufacturing Company, DuPont de Nemours, Inc., Sonoco Products Company, 3M, Mitsubishi Chemical Group Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Devices Packaging Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to reshape sterile barrier specifications across cardiovascular, ophthalmic, and biologics delivery formats in the Asia-Pacific medical device sector.
Multilayer coextrusion films incorporating ethylene vinyl alcohol copolymers are displacing conventional polyethylene terephthalate glycol monolayers in high-risk device packaging. Cardiovascular device manufacturers in Japan and China are adopting these structures at accelerated pace to meet extended shelf-life requirements. This displacement is compressing commodity film margins while rewarding suppliers with captive polymer compounding capabilities.
China's GB/T 19633 national standards alignment with ISO 11607 is mandating documented seal-strength validation across all sterile barrier classes. The industrial consequence is elimination of small-scale converters lacking in-house testing infrastructure. Class III implantable device packaging faces the steepest compliance cost trajectory, with manufacturers in the Yangtze River Delta medical manufacturing cluster absorbing requalification expenses to maintain NMPA registration.
Hospital procurement consolidation across Australia's public health system is compressing supplier margins through centralized tender mechanisms. Traditional distributor networks serving regional clinics are losing volume to direct manufacturer contracts with state purchasing authorities. This concentration is most visible in New South Wales and Victoria, where single-source sterile barrier agreements now cover 70 percent of public sector device procurement.
Asia-Pacific Medical Devices Packaging Market Segmentation
Regulatory divergence across NMPA, PMDA, and CDSCO jurisdictions fragments specification requirements, forcing suppliers to maintain parallel product lines. Material selection and sterilization validation protocols vary by device risk class, creating tiered compliance burdens that reshape segment economics.
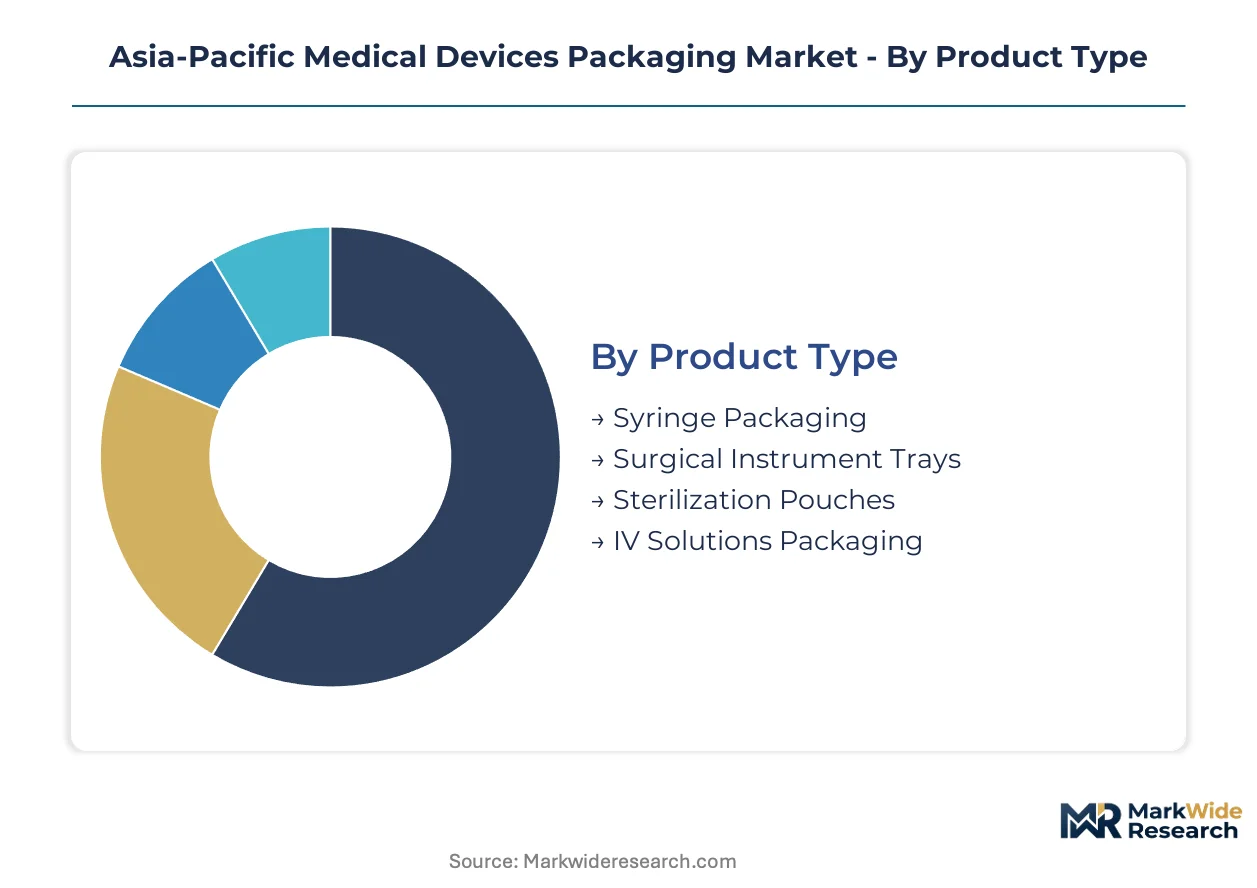
Product Type:
NMPA's GB/T 19633 alignment with ISO 11607 imposes distinct seal-strength documentation thresholds across each format, with Class III devices facing the steepest validation costs.
- Sterilization Pouches:These multilayer heat-sealed barriers combine medical-grade polyethylene terephthalate glycol with ethylene vinyl alcohol copolymers for gas barrier performance. Demand concentrates in China's Yangtze River Delta medical manufacturing cluster, where low-to-medium risk device producers prioritize universal applicability over format-specific customization.
- Syringe Packaging:Blow-fill-seal systems with enhanced oxygen barrier properties dominate prefillable biologics formats. India's Gujarat pharmaceutical-device corridor is absorbing capacity expansion fastest, driven by CDSCO-mandated quality upgrades in injectable administration.
- Surgical Instrument Trays:Thermoformed rigid structures with lidding films serve sterilized kit presentation.
- IV Solutions Packaging:Multilayer film or blow-fill-seal containers maintain fluid integrity across distribution.
Sterilization pouches handle the majority of throughput; syringe packaging is the fastest mover on share.
Material:
Cost tier stratification separates premium engineering polymers from commodity substrates, with thermoformability and sterilization compatibility determining margin capture.
- Plastic:Medical-grade polyethylene terephthalate glycol and fluoropolymer films anchor volume through thermoformability, blow-fill-seal processing compatibility, and gamma irradiation stability. Japan's precision instrument sector demands clear, sterilizable rigid trays from Mitsubishi Chemical Group polymer supply.
- Paper:Fiber-based sterile barriers with synthetic polymer coatings are gaining structural share in sustainability-focused European-export supply chains serving low-risk device categories. Australia's TGA procurement consolidation is accelerating pilot programs for paper alternatives in hospital tender contracts.
- Glass:Borosilicate and treated soda-lime formats serve high-visibility pharmaceutical-device combinations.
- Metal:Aluminum and stainless steel containers provide structural protection for implantable device kits.
Plastic commands volume leadership; paper is climbing the fastest on sustainability-driven substitution.
Application:
Customer type divergence separates high-volume disposable producers from low-volume precision instrument manufacturers, with sterilization method compatibility driving material selection.
- Cardiovascular Devices:Advanced multilayer coextrusion systems with ethylene vinyl alcohol copolymer cores extend shelf-life for stents, pacemakers, and catheter kits. Japan and China manufacturers are adopting these structures at accelerated pace under PMDA and NMPA tightening mandates.
- Surgical Devices:Sterile barrier systems for scalpels, forceps, and powered instruments balance puncture resistance with seal integrity. South Korea's MFDS harmonization with Australia's TGA is compressing supplier qualification timelines for regional surgical kit exporters.
- Orthopedic Devices:Rigid tray and lidding combinations protect implants and fixation hardware.
- Diagnostic Devices:Pouch and blister formats serve test kits and monitoring equipment.
Cardiovascular applications absorb the premium material investment; surgical devices are expanding most quickly on standardization benefits.
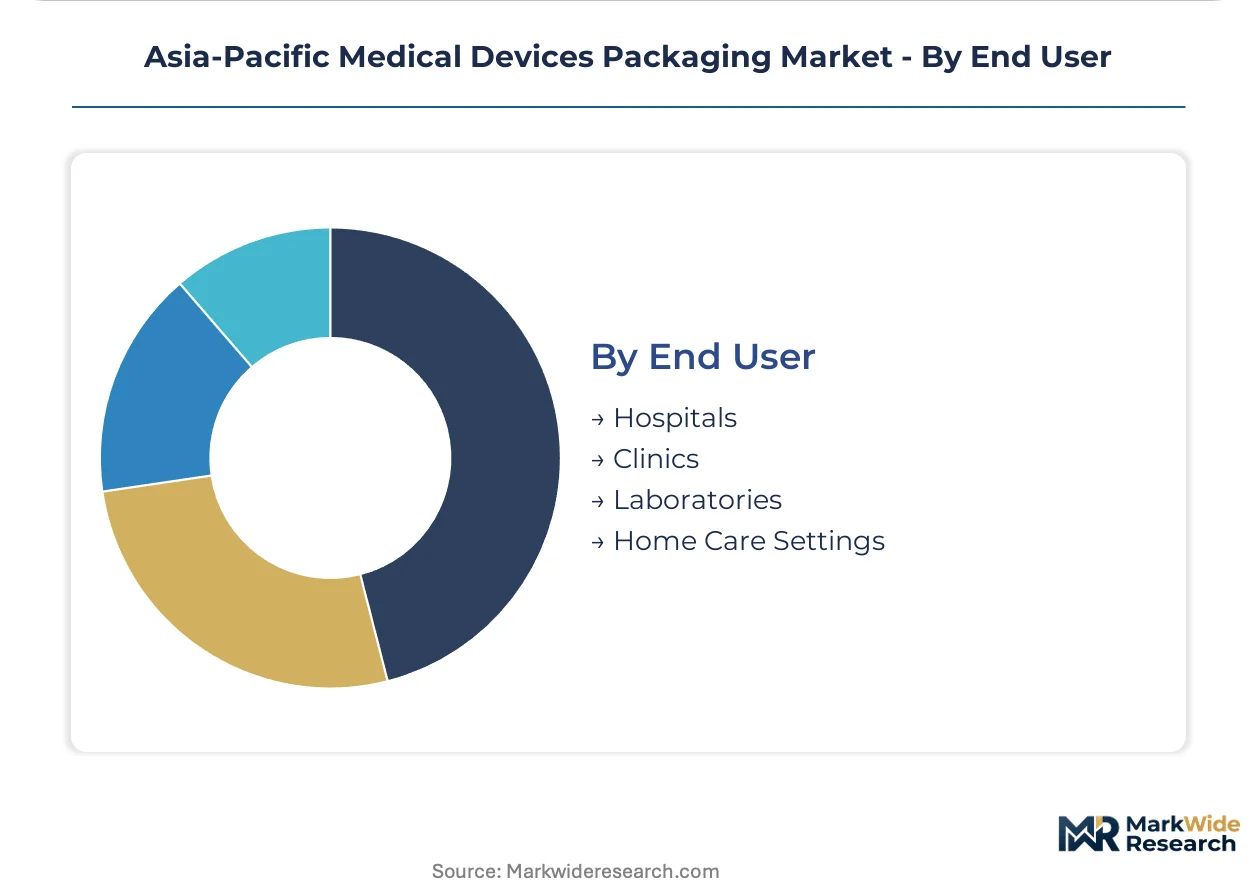
End User:
Procurement concentration across Australia's public health system and India's private hospital chains is consolidating supplier relationships, with direct manufacturer contracts displacing traditional distributor networks.
- Hospitals:Centralized tender mechanisms in New South Wales and Victoria now cover seventy percent of public sector device procurement, compressing margins through single-source sterile barrier agreements. China's tier-one city hospital networks are replicating this consolidation pattern.
- Home Care Settings:Prefillable syringe and self-administration formats are penetrating diabetes and biologics markets. India's expanding home healthcare infrastructure is creating demand for patient-friendly opening features and tamper-evident designs.
- Clinics:Outpatient surgical and diagnostic centers require mid-volume sterile barrier solutions.
- Laboratories:In-vitro diagnostic packaging demands precision sealing and contamination control.
Hospitals dominate procurement volume; home care settings are gaining share fastest on chronic disease management expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific medical devices packaging market diverge sharply by national healthcare infrastructure maturity and export orientation. Japan and Australia prioritize high-integrity sterile barriers for domestic precision instrument manufacturing and public hospital procurement consolidation. China and India balance massive domestic volume with emerging export compliance to European sustainability standards.
China
Prefillable syringe demand from biologics manufacturers in the Yangtze River Delta medical manufacturing cluster is accelerating blow-fill-seal capacity expansion. NMPA's GB/T 19633 alignment with ISO 11607 mandates documented seal-strength validation across all sterile barrier classes. The Yangtze River Delta medical manufacturing cluster absorbs the steepest compliance cost trajectory as Class III implantable device packaging undergoes requalification for NMPA registration maintenance.
Japan
Cardiovascular device manufacturers are adopting advanced multilayer coextrusion systems with ethylene vinyl alcohol copolymer cores to extend shelf-life for stents and catheter kits. PMDA enforces packaging integrity requirements under Pharmaceutical and Medical Device Act quality standards that exceed baseline ISO 11607 protocols. Japan's precision instrument sector concentrates demand for clear, sterilizable rigid trays in the Chubu/Nagoya industrial corridor.
India
CDSCO quality mandates in the Gujarat pharmaceutical-device corridor are driving domestic converters toward ISO 15378-certified production lines for injectable packaging formats. India's PLI scheme for medical devices is attracting packaging converters to establish captive supply within Gujarat. The expanding home healthcare infrastructure in Maharashtra and Karnataka is creating demand for patient-friendly opening features and tamper-evident designs in prefillable syringe formats.
South Korea
MFDS harmonization with Australia's TGA on sterilization assurance testing is compressing supplier qualification timelines for regional surgical kit exporters. The Seoul Capital Area hosts the majority of domestic medical device manufacturing requiring sterile barrier systems. South Korean ophthalmic device producers are migrating toward blow-fill-seal formats with enhanced gas barrier properties for intraocular lens packaging.
Australia
Hospital procurement consolidation across New South Wales and Victoria public health systems now covers seventy percent of public sector device procurement through centralized tender mechanisms. TGA imposes sterilization validation protocols that shape supplier qualification timelines for Asia-Pacific market access. Australia's sustainability-focused European-export supply chains are accelerating pilot programs for paper-based sterile barriers in low-risk device categories.
Asia-Pacific Medical Devices Packaging Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific medical devices packaging market. The upper tier commands captive polymer compounding capabilities and multilayer coextrusion film production for high-risk device classes. Mid-scale converters compete on ISO 15378 certification speed and regional logistics proximity to medical manufacturing clusters. Dominant competitive moves include blow-fill-seal capacity expansion targeting ophthalmic and injectable formats, and strategic positioning for India's PLI scheme incentives through Gujarat corridor facility establishment.
Among diversified packaging conglomerates with Asia-Pacific medical-grade film extrusion footprints, Amcor Plc and Berry Global Inc. exemplify the integrated leader archetype through regional supply chain presence. Mitsubishi Chemical Group Corp. occupies a distinct position as an engineering polymer supplier anchoring clear, sterilizable rigid tray production for Japan's precision instrument sector. These three entities represent the concentration of material science capability and regulatory qualification infrastructure that defines competitive positioning in high-integrity sterile barrier systems.
| Leading Market Players |
|---|
| Smurfit WestRock |
| Berry Global Inc. |
| Amcor Plc |
| WestRock Company |
| Bemis Manufacturing Company |
| DuPont de Nemours, Inc. |
| Sonoco Products Company |
| 3M |
| Mitsubishi Chemical Group Corp. |
| Others |
Value Chain & Pricing Dynamics
ISO 15378 certification gates both supplier qualification timelines and price differentiation across the Asia-Pacific medical devices packaging market, creating dual barriers where uncertified converters face margin compression while accredited operators capture premium positioning for Class III device formats.
Pricing Analysis
Long-term offtake agreements dominate procurement relationships between cardiovascular device manufacturers and multilayer film suppliers, insulating premium-tier pricing from spot-market volatility. Three-tier pricing structure across ISO 15378-certified premium, ISO 11607-compliant standard, and uncertified economy levels separates validated sterile barrier supply from commodity alternatives. Cost compression in the economy tier is intensifying because China's NMPA alignment with GB/T 19633 standards is eliminating small-scale converters lacking in-house testing infrastructure. Hospital procurement committees demonstrate lowest price sensitivity for Class III implantable packaging, while generic device distributors in India's Gujarat corridor exhibit highest sensitivity to per-unit differentials.
Supply Chain Analysis
Extended lead times for medical-grade ethylene vinyl alcohol copolymers and fluoropolymer films are stretching converter inventory positions across the region. Supply concentrates in Japan's Chubu industrial corridor for engineering polymers, China's Yangtze River Delta for multilayer coextrusion capacity, and India's Gujarat pharmaceutical-device corridor for blow-fill-seal systems. Raw material dependencies rest on Mitsubishi Chemical Group's polymer supply, imported ethylene vinyl alcohol resin grades, and medical-grade polyethylene terephthalate glycol substrates. Single-source vulnerability for Japan's precision instrument sector creates structural risk exposure. Distribution runs through direct manufacturer contracts with state purchasing authorities in Australia and tier-one hospital networks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across NMPA, PMDA, and CDSCO jurisdictions fragments the competitive landscape, creating specialist niches where mid-scale converters with targeted certification investments can outmaneuver diversified conglomerates lacking regional regulatory depth.
For Market Incumbents: Compound defensive positioning by securing captive polymer compounding capabilities for ethylene vinyl alcohol copolymer supply, insulating against Mitsubishi Chemical Group's regional monopoly. Accelerate blow-fill-seal capacity expansion in India's Gujarat corridor ahead of PLI scheme saturation. ISO 11607 validation documentation represents the critical lever for margin defense against emerging Southeast Asian contract manufacturers.
For New Entrants and Emerging Players: Lead with unmet demand in Vietnam and Indonesia's underdeveloped sterile barrier infrastructure, where first-mover ISO certification creates sustainable procurement relationships. Target paper-based alternatives for European-export supply chains serving Australia's sustainability-focused hospital tenders. Position through direct partnerships with biologics manufacturers in China's Yangtze River Delta seeking secondary supply sources.
For Investors and Strategic Acquirers: NMPA's GB/T 19633 alignment with ISO 11607 reshapes the acquisition landscape by eliminating subscale converters and concentrating viable targets among ISO 15378-certified regional specialists. Five-to-ten-year viability favors engineering polymer suppliers with backward integration into medical-grade resin production and converters with dedicated cleanroom infrastructure. Monitor CDSCO enforcement intensity in India's Gujarat corridor as the inflection signal for domestic consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | CDSCO mandates in India's Gujarat corridor eliminate uncertified competitors from injectable packaging procurement. |
| Blow-Fill-Seal Capacity Expansion | Prefillable syringe demand from China's Yangtze River Delta biologics manufacturers anchors revenue visibility. |
| Backward Integration into Polymer Compounding | Mitsubishi Chemical Group's supply concentration creates margin capture opportunity for captive resin production. |
| Paper-Based Sterile Barrier Development | Australia's TGA procurement consolidation pilots fiber alternatives for European-export supply chain compliance. |
| Southeast Asia Facility Establishment | Vietnam and Indonesia's infrastructure gaps reward first-mover ISO-certified pouch and tray suppliers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile barrier engineers, hospital procurement managers, biomedical device quality leads, and polymer compounding specialists. Secondary validation drew from NMPA registration filings, PMDA quality standard updates, CDSCO manufacturing compliance notices, and ISO 11607 harmonization documentation. Bottom-up demand modeling across device risk classes triangulated with top-down polymer consumption estimates.
Across the analysis window, forecasts segmented by product type, material substrate, application category, and end-user procurement channel generated volume and value trajectories. CAGRs were derived from sterilization method adoption curves, biologics administration format shifts, and regulatory compliance cost absorption rates. Prefillable syringe penetration in chronic disease management and extended producer responsibility framework implementation served as key forecast inputs.
Underlying assumptions cover NMPA enforcement consistency, polymer supply stability from Japanese engineering resin producers, and hospital procurement consolidation pace, with deviation risk concentrated in biocompatibility testing harmonization delays and alternative sterilization method validation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Multi-Med Adherence Packaging Market
Medical Devices Packaging
Molded Pulp Clinical Packaging Market
Medical Devices Packaging
Medical Containers Market
Medical Devices Packaging
Asia Pacific Blood Glucose Test Strip Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Transplant Box Market
Medical Devices Packaging
Global Procedure Trays Market
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Global Custom Procedure Trays and Packs Market
Medical Devices Packaging
Plastic Healthcare Packaging Market
Medical Devices Packaging
Ophthalmic Packaging Market
Medical Devices Packaging
Europe Medical Devices Packaging Market
Medical Devices Packaging
North America Medical Devices Packaging Market