
 Global Cosmetic Contact Lens Market | 2026-2036
Global Cosmetic Contact Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Contact Lens Market Analysis
Subscription-based lens replacement programs are decoupling unit sales from traditional retail channels. Johnson & Johnson Vision Care leverages direct-to-consumer platforms to sustain recurring revenue. CooperVision anchors its position through specialized color portfolios. Bausch + Lomb differentiates via extended wear formulations.
Cosmetic contact lenses are vision-correcting or non-correcting ocular devices manufactured from hydrogel, silicone hydrogel, or tinted plastic materials, designed to alter iris appearance through pigmentation patterns or special effects while maintaining oxygen transmissibility measured in Dk/t values. Their primary commercial purpose spans fashion enhancement, theatrical performance, and aesthetic eye color modification without surgical intervention. Color lenses occupy the largest volume position while silicone hydrogel commands premium pricing due to superior oxygen permeability. Decorative lenses for theatrical use represent the fastest-expanding margin pool as entertainment production budgets rise.
FDA oversight in the United States classifies all cosmetic lenses as medical devices requiring prescription authorization, while Japan's PMDA enforces stringent biocompatibility testing under MHLW guidelines. South Korea's MFDS mandates GMP certification for domestic manufacturing facilities. Stakeholders must monitor evolving material safety standards and prescription enforcement mechanisms across key markets.
Market Dynamics
Silicone hydrogel material substitution is compressing legacy hydrogel margins while elevating clinical safety standards across prescription and non-prescription channels.
Growth Catalysts
- FDA Medical Device Classification:Prescription requirements for all cosmetic lenses in the United States channel demand through optometric gatekeepers, legitimizing professional fitting services and reducing counterfeit circulation.
- K-Beauty Export Engine:South Korean MFDS-certified manufacturers supply pigmented lens designs to Southeast Asian and Latin American markets through cross-border e-commerce platforms.
- Silicone Hydrogel Oxygen Permeability:Dk/t values exceeding 100 enable extended daily wear protocols that expand addressable use cases beyond occasional cosmetic application.
Market Restraints
- Input Cost Concentration:Silicone hydrogel monomer supply concentrates among Japanese and German specialty chemical producers, exposing lens manufacturers to feedstock volatility.
- Prescription Enforcement Friction:Online gray-market sellers circumvent FDA authorization requirements, undermining legitimate retail channels and creating liability exposure for uninformed consumers.
- Biocompatibility Testing Burden:PMDA and MFDS cytotoxicity protocols extend product registration timelines by 18-24 months for novel pigmentation chemistries.
Strategic Opportunities
- Underpenetrated Indian Middle Class:CDSCO medical device rules formalizing in 2026 will clarify import pathways for color lens portfolios targeting metropolitan cosmetic users.
- Subscription Replenishment Models:Direct-to-consumer platforms bypass optical retail markups while capturing recurring revenue through automated lens replacement scheduling.
- AR/Virtual Try-On Convergence:Smartphone-based iris visualization tools reduce purchase hesitation and return rates for online color lens selection.
Industry Challenges
- Specialized Fitting Skill Scarcity:Optometric training programs emphasize medical contact lens management over cosmetic fitting protocols, creating service bottlenecks in high-volume retail settings.
- ISO 18369-3 Compliance Complexity:International dimensional tolerance standards for cosmetic lenses require metrology investments that strain mid-tier manufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Contact Lens Market |
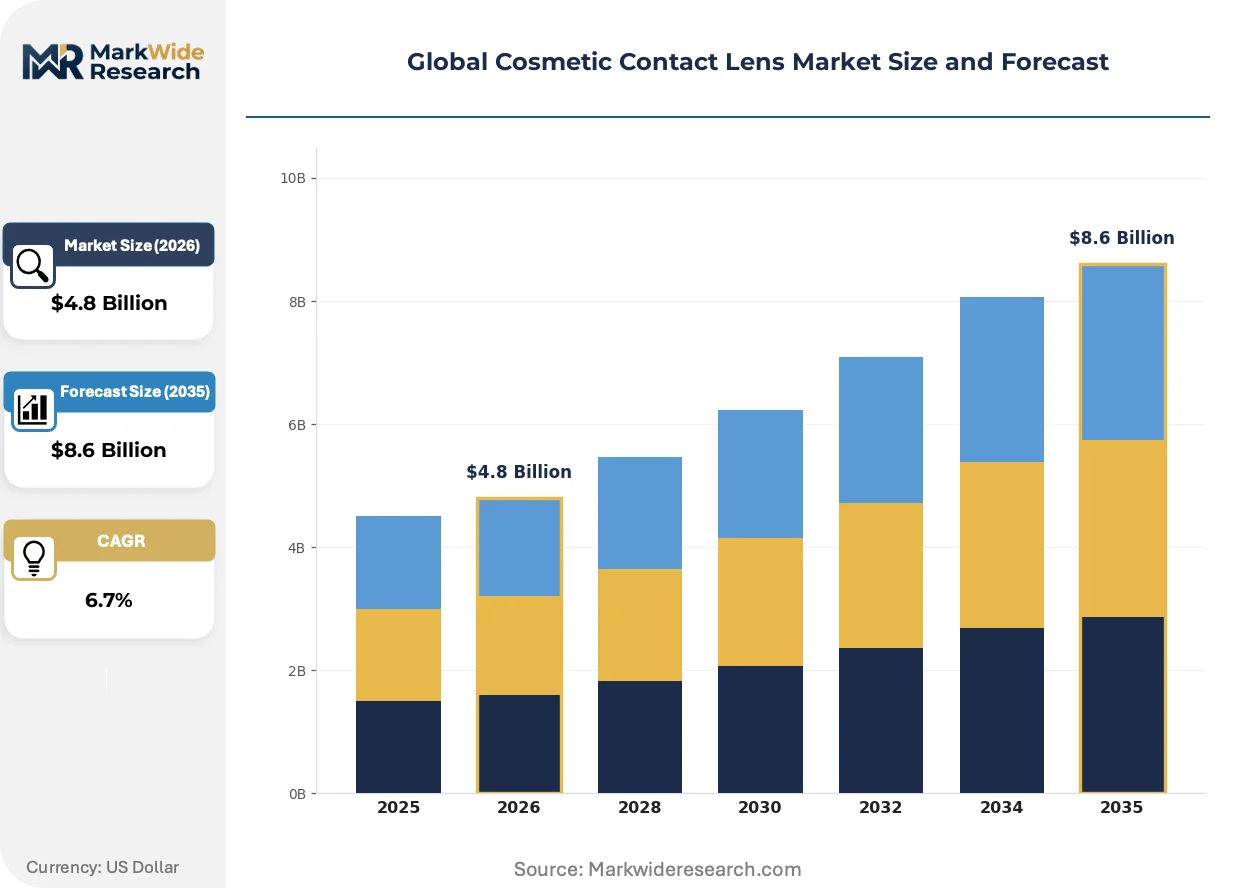
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Lenses, Decorative Lenses, Optical Lenses, Specialty Lenses Material: Hydrogel, Silicone Hydrogel, PMMA, Tinted Plastic Use Case: Fashion Statement, Eye Enhancement, Theatrical Use, Vision Correction Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | Bausch + Lomb, Hoya Corporation, Cooper Companies, Inc. (CooperVision), Menicon Co., Ltd., Seed Co., Ltd., Johnson & Johnson Vision Care, Carl Zeiss AG, EssilorLuxottica, Alcon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Contact Lens Market Emerging Trajectories
Digital content creation economies are normalizing cosmetic lens wear as everyday fashion accessory rather than special-occasion purchase, compressing replacement cycles and expanding SKU proliferation.
Silicone hydrogel formulations are integrating comfort polymers that reduce end-of-day dryness symptoms. Content creators and entertainment professionals adopt these materials for 12-16 hour filming schedules. The technology is integrating cosmetic and corrective functions into single SKUs, collapsing the historical segmentation between vision correction and aesthetic modification.
Japan's PMDA tightened biocompatibility surveillance for imported decorative lenses in 2024, mandating post-market adverse event reporting within 30 days. Domestic distributors now shoulder compliance liability previously borne by manufacturers. South Korean exporters are responding by establishing Tokyo-based regulatory affairs subsidiaries to manage direct PMDA correspondence.
Social commerce platforms are displacing optical retail for initial cosmetic lens discovery among 18-34 year old consumers. Influencer-curated collections drive impulse purchases that bypass professional fitting. This behavioral shift concentrates in Brazil and Indonesia, where smartphone penetration outpaces optometric infrastructure density.
Global Cosmetic Contact Lens Market Segmentation
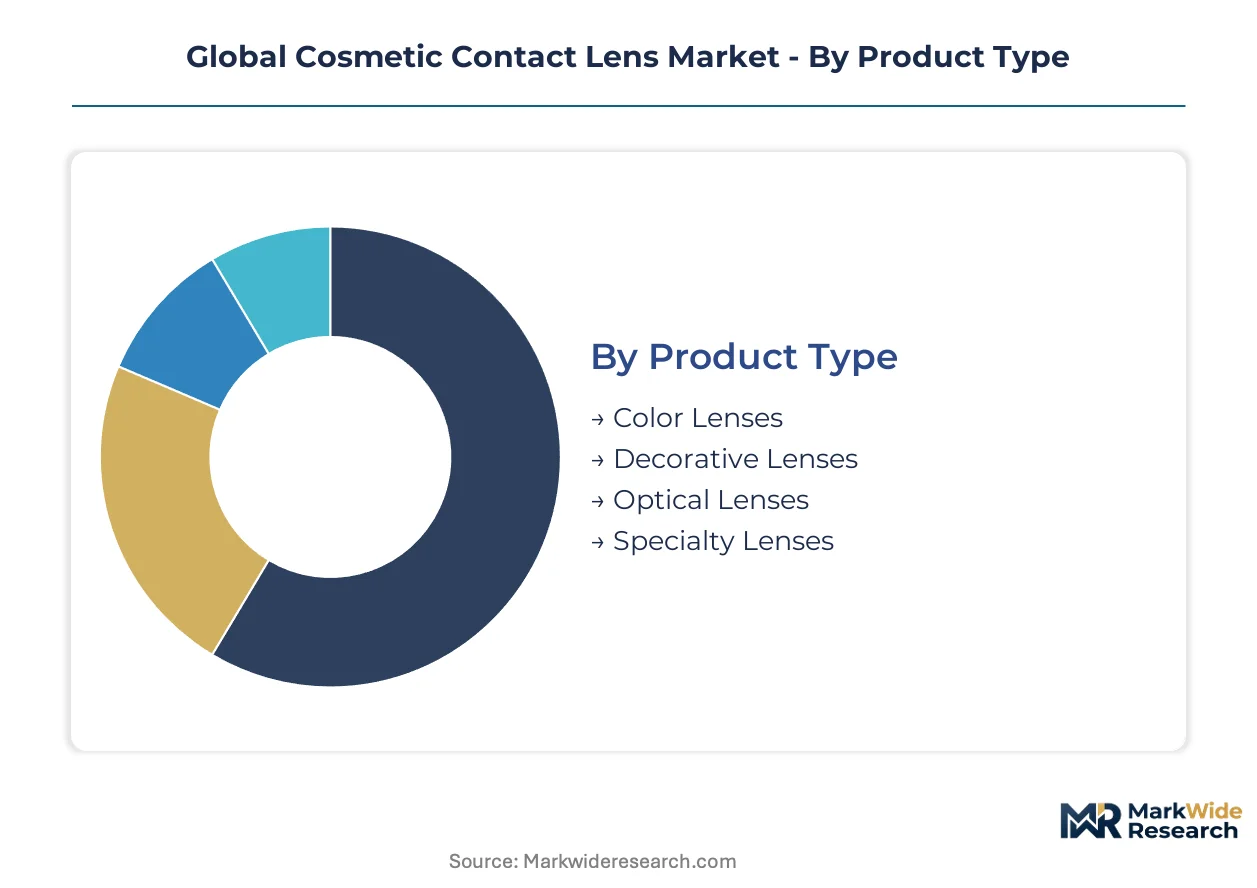
Cosmetic contact lens segmentation reveals divergent margin profiles across material technologies and use case intensity. Manufacturers optimize portfolio mix between high-volume color lens production and premium decorative formulations for entertainment professionals.
Product Type:
Volume concentration sits with everyday color modification while premium capture concentrates in specialized theatrical applications.
- Color Lenses:Hydrogel and silicone hydrogel substrates incorporate printed iris patterns or gradient tints to modify natural eye color. Demand clusters in Japan and South Korea where K-beauty influence normalizes daily cosmetic lens wear among working-age consumers seeking aesthetic enhancement.
- Decorative Lenses:Opaque pigmentation and special effects designs alter iris appearance for costume, cosplay, and film production use. Entertainment industry procurement in Los Angeles and Seoul drives adoption as production budgets allocate to character-specific ocular effects.
- Optical Lenses:Vision-correcting cosmetic devices combine prescription power with color or tint functionality.
- Specialty Lenses:Custom-manufactured designs for medical prosthetics or extreme theatrical effects.
Mature deployment sits with Color Lenses. Newer deployment is concentrated in Decorative Lenses.
Material:
Clinical safety standards are compressing legacy hydrogel positioning while elevating silicone hydrogel to premium tier dominance.
- Silicone Hydrogel:Advanced polymer matrix achieves Dk/t values exceeding 100 for superior oxygen transmissibility. Extended daily wear protocols in the United States and Japan expand addressable use cases beyond occasional cosmetic application into professional content creation schedules.
- Hydrogel:Water-absorbing polymer formulations dominate entry-level price tiers through established manufacturing scale. Cost-sensitive markets in Southeast Asia sustain volume despite inferior oxygen permeability limiting wear duration.
- PMMA:Rigid gas-permeable material for specialized cosmetic-prosthetic hybrid applications.
- Tinted Plastic:Lower-cost pigmented materials for novelty and single-use theatrical segments.
Supply concentration favors Silicone Hydrogel among Japanese and German specialty chemical producers. Price-sensitive procurement gravitates toward Hydrogel.
Use Case:
Application intensity separates occasional fashion experimentation from professional-grade daily deployment.
- Fashion Statement:Social media content creators and everyday consumers adopt cosmetic lenses as personal style accessories. Instagram and TikTok visibility in Brazil and Indonesia normalizes frequent lens replacement and multi-color wardrobe matching.
- Theatrical Use:Film, television, and live performance productions require specialized effects lenses for character transformation. Hollywood and Seoul studio procurement demands 12-16 hour comfort durability and custom color matching.
- Eye Enhancement:Subtle tinting to deepen or brighten natural iris appearance.
- Vision Correction:Prescription-powered cosmetic lenses serving dual functional-aesthetic purposes.
Replacement frequency peaks with Fashion Statement users. Per-unit margin capture concentrates in Theatrical Use.
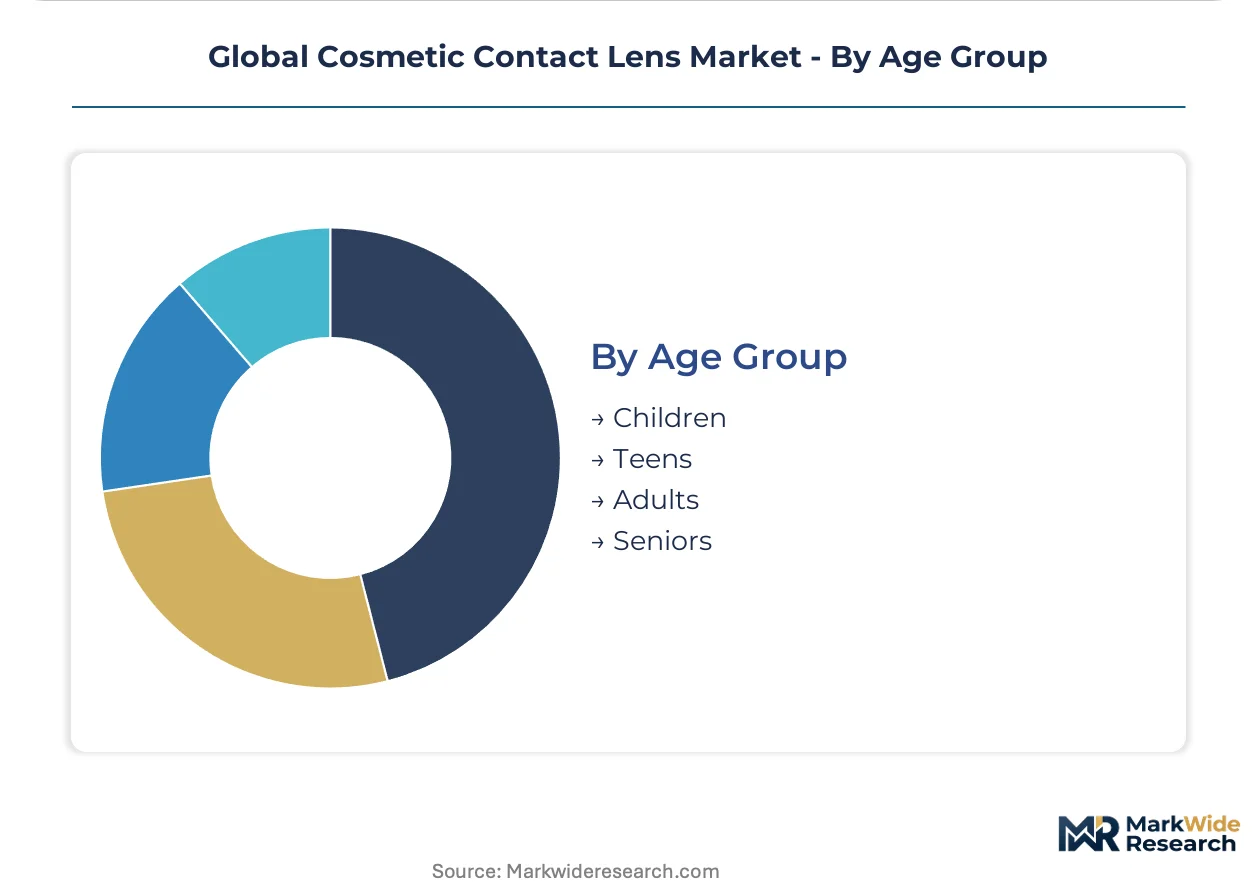
Age Group:
Purchase authority and ocular health considerations segment the addressable population across life stages.
- Adults:Independent purchasing decisions and established optometric relationships sustain the core revenue base. Working-age professionals in metropolitan United States and South Korean markets drive subscription replenishment program adoption.
- Teens:Social commerce discovery and influencer-curated collections accelerate trial rates among 13-19 year olds. Parental purchase authorization requirements in FDA-regulated channels create friction versus gray-market alternatives.
- Children:Medical-prosthetic applications for congenital conditions or trauma reconstruction.
- Seniors:Presbyopia-correcting cosmetic options for aging populations seeking aesthetic maintenance.
Commercial volume concentrates with Adults. Trial conversion expansion targets Teens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian manufacturing clusters while consumption spreads across mature economies with strong optometric infrastructure and emerging markets with social commerce penetration.
United States
FDA prescription requirements channel demand through optometric gatekeepers and sustain professional fitting services. The agency's medical device classification for all cosmetic lenses reduces counterfeit circulation but creates friction against online gray-market alternatives. Los Angeles anchors theatrical demand as film studios procure specialized effects lenses for character production.
Japan
K-beauty influence and daily cosmetic lens normalization drive working-age consumer adoption. PMDA tightened biocompatibility surveillance in 2024, mandating 30-day post-market adverse event reporting that shifts compliance liability to domestic distributors. Tokyo hosts regulatory affairs subsidiaries established by South Korean exporters managing direct PMDA correspondence.
South Korea
Cosplay culture and entertainment industry procurement normalize decorative lens wear across age cohorts. MFDS mandates GMP certification for domestic manufacturing facilities and enforces cytotoxicity protocols extending product registration timelines. Seoul studio clusters drive demand for 12-16 hour comfort durability in professional content creation schedules.
Brazil
Smartphone penetration outpaces optometric infrastructure density, concentrating initial discovery on social commerce platforms. Influencer-curated collections accelerate impulse purchases among 18-34 year old consumers. São Paulo and Rio de Janeiro metropolitan areas exhibit the highest trial conversion rates for fashion statement applications.
India
CDSCO medical device rules formalizing in 2026 will clarify import pathways for color lens portfolios. The underpenetrated middle class in metropolitan centers presents expansion opportunity as aesthetic enhancement demand rises. Mumbai and Delhi-NCR concentrate early adopter populations with established optometric relationships.
Global Cosmetic Contact Lens Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across material innovation and distribution channel control. The vendor base stratifies between integrated chemical-lens manufacturers and specialized brand marketers. Three archetypes dominate: silicone hydrogel substrate specialists, color pattern designers, and direct-to-consumer platform operators. Capacity expansion in oxygen-permeable materials and strategic partnerships with entertainment studios represent the dominant competitive moves.
Among diversified optical healthcare groups, Johnson & Johnson Vision Care and Bausch + Lomb exemplify the integrated archetype combining material science with professional channel access. CooperVision occupies a position within the specialized color portfolio tier. These three entities anchor the premium segment through distinct vectors: automated replenishment platforms, extended wear formulations, and theatrical effects specialization respectively.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Hoya Corporation |
| Cooper Companies, Inc. (CooperVision) |
| Menicon Co., Ltd. |
| Seed Co., Ltd. |
| Johnson & Johnson Vision Care |
| Carl Zeiss AG |
| EssilorLuxottica |
| Alcon |
| Others |
Supply Flow & Price Mechanics
Specialized polymer chemist concentrations in Osaka and Düsseldorf create labor-cost differentials that widen pricing-tier spreads between premium silicone hydrogel formulations and commodity hydrogel alternatives. Japanese and German specialty chemical clusters command compensation premiums that feed into material input costs, while Southeast Asian manufacturing bases compete on scale economics for entry-tier tinted plastic segments.
Pricing Analysis
Margin tightening in hydrogel tiers reflects silicone hydrogel substitution pressure as clinical safety standards elevate. Three-tier pricing structure across premium silicone hydrogel, standard color-corrective, and economy novelty segments separates oxygen permeability certification grades. Cost-down pressure on hydrogel portfolios accelerates because MFDS and PMDA biocompatibility testing burdens extend registration timelines. Teens and social commerce trialists exhibit highest price sensitivity; entertainment procurement departments show lowest sensitivity due to production budget allocation flexibility.
Supply Chain Analysis
Polymer synthesis specialist availability concentrates in Japan, Germany, and South Korea, constraining capacity expansion for oxygen-permeable formulations. Silicone hydrogel monomer production draws from Japanese and German feedstock specialists, while colorant patterning equipment sources from Swiss and Italian precision engineering clusters. Single-source vulnerability sits with specialty silicone monomer supply from Osaka-area chemical complexes. Distribution runs through optometric professional channels in FDA-regulated markets and social commerce platforms in infrastructure-constrained geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone hydrogel monomer supply constraints prop pricing power for substrate specialists, creating a supply-constrained market structure that favors incumbent material science capabilities over brand marketing alone.
For Market Incumbents: Hedge against gray-market circumvention by deepening direct-to-consumer platform investments that capture subscription replenishment revenue. Anchor position through captive supply arrangements with Japanese monomer producers. Defensive consolidation around MFDS-certified manufacturing assets in Seoul and Tokyo clusters protects against regulatory enforcement escalation. For New Entrants and Emerging Players: Launch via influencer-curated social commerce collections targeting Brazilian and Indonesian 18-34 year old discovery patterns. White-space concentration sits with theatrical effects specialization for Los Angeles and Seoul studio procurement. Penetrable entry points cluster in AR-enabled virtual try-on platforms that reduce professional fitting friction. For Investors and Strategic Acquirers: Re-rating potential sits with silicone hydrogel substrate specialists given oxygen permeability certification tiering. Long-term viability favors integrated material-lens manufacturers over pure-play brand marketers. Watch for PMDA adverse event reporting acceleration as inflection signal for regulatory enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Capacity Expansion | Captures premium pricing tier as Dk/t certification becomes baseline clinical expectation. |
| Direct-to-Consumer Platform Launch | Bypasses optical retail markups while locking recurring revenue through automated replenishment. |
| Regulatory Affairs Subsidiary Establishment | Tokyo-based PMDA correspondence management reduces distributor liability exposure. |
| AR Virtual Try-On Integration | Smartphone-based iris visualization cuts return rates for online color lens selection. |
| Entertainment Studio Partnership | Hollywood and Seoul production procurement anchors high-margin theatrical effects demand. |
Methodological Framework
Document review covered FDA 510(k) filings, MFDS GMP certification records, and PMDA adverse event databases, complemented by interviews with optometric chain procurement directors, silicone hydrogel polymer chemists, theatrical effects lens designers, and social commerce platform category managers. Secondary validation drew from trade customs data, ISO 18369-3 dimensional tolerance standards, and entertainment industry production budget disclosures. Bottom-up SKU-level volume builds were triangulated against top-down category spend estimates.
Cross-referencing historical silicone hydrogel adoption curves against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material technology tier, use case intensity, age cohort purchase authority, and regional regulatory cluster. CAGRs were derived from fitted adoption curves rather than extrapolated linear trends. Forecast inputs incorporated PMDA biocompatibility surveillance tightening and CDSCO rule formalization timelines.
Feedstock price volatility, prescription enforcement friction escalation, and social commerce regulatory intervention are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding monomer supply concentration and platform channel displacement velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
UK Surgical Devices Market
Medical Devices
India Clear Aligners Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Global Breast Implants Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Global External Fixators Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market