
 Healthcare Packaging Market | 2026-2036
Healthcare Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Packaging Market Intelligence
A shift from single-source to multi-source material procurement is decoupling packaging converters from legacy resin suppliers across North America and Western Europe. Amcor plc leverages its global film extrusion footprint to secure alternative polymer streams. Gerresheimer AG anchors its position through captive glass-tubing operations in Germany and India. Berry Global competes by extending blow-molded bottle capacity into pharmaceutical-grade cleanroom environments.
Healthcare packaging encompasses engineered primary and secondary enclosures designed to maintain sterility, stability, and traceability for pharmaceuticals, medical devices, and diagnostic products, typically manufactured via thermoforming, blow molding, or cold-forming processes with barrier properties measured in oxygen transmission rates and moisture vapor transmission rates. Blister packs dominate unit volume in oral solid-dose pharmaceuticals due to their unit-dose compliance advantages and child-resistance adaptability. Plastic materials lead value contribution across injectables and respiratory devices, while glass sustains premium positioning in biologics where extractables and leachables profiles must satisfy the most stringent pharmacopeial limits. Aluminum occupies a specialized niche in cold-form foil laminates for moisture-critical formulations.
FDA regulations govern material biocompatibility and drug master file submissions for primary packaging in the United States, while EU Directives enforce serialized traceability and Falsified Medicines Directive compliance across European supply chains. ISO standards and GMP frameworks establish baseline quality management systems that determine supplier qualification status for multinational pharmaceutical procurement teams. Stakeholders must monitor evolving EPR legislation in the European Union and state-level packaging waste laws in the United States to anticipate compliance-driven material substitutions.
Market Dynamics
Serialization mandates across pharmaceutical supply chains are forcing packaging converters to retool lines for track-and-trace integration, compressing lead times and elevating capital requirements for tier-two suppliers.
Growth Catalysts
- EU Falsified Medicines Directive:Mandatory 2D barcodes and anti-tamper devices on prescription packs are expanding demand for integrated authentication solutions across European distribution networks.
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibodies and cell therapies require validated thermal packaging systems that sustain sub-zero conditions through last-mile delivery.
- India's injectables sector:CDSCO serialization deadlines are accelerating barrier-grade polymer adoption among domestic sterile formulation manufacturers supplying regulated export markets.
Market Restraints
- Resin supply concentration:Medical-grade polypropylene and cyclic olefin copolymer production clusters in the US Gulf Coast and Northeast Asia, exposing converters to hurricane and trade-route disruptions.
- Aluminum foil dependency:Cold-form blister laminates rely on rolling mill capacity concentrated in China and Russia, creating input cost volatility for moisture-critical formulations.
- Extractables testing bottlenecks:US FDA drug master file reviews for novel polymer contact materials extend qualification timelines by 18-24 months, delaying commercialization.
Strategic Opportunities
- Germany's biologics hub:mRNA vaccine manufacturers in Marburg and Dresden are commissioning dedicated cleanroom packaging lines for parenteral fill-finish operations.
- Paper-based barrier substrates:Fiber-forming technologies combined with plasma-deposited silica coatings are emerging as recyclable alternatives to multi-layer plastic blisters.
- Homecare infusion devices:Self-administered biologics are driving demand for prefilled syringe and auto-injector formats with integrated needle safety systems.
Industry Challenges
- Serialization engineering talent:Packaging line integration with aggregation stations and warehouse management systems requires scarce automation specialists familiar with GS1 standards.
- Cleanroom capacity conversion:Food-grade blow-molding assets require $4-8 million per line for ISO 14644-1 Class 8 pharmaceutical certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Packaging Market |
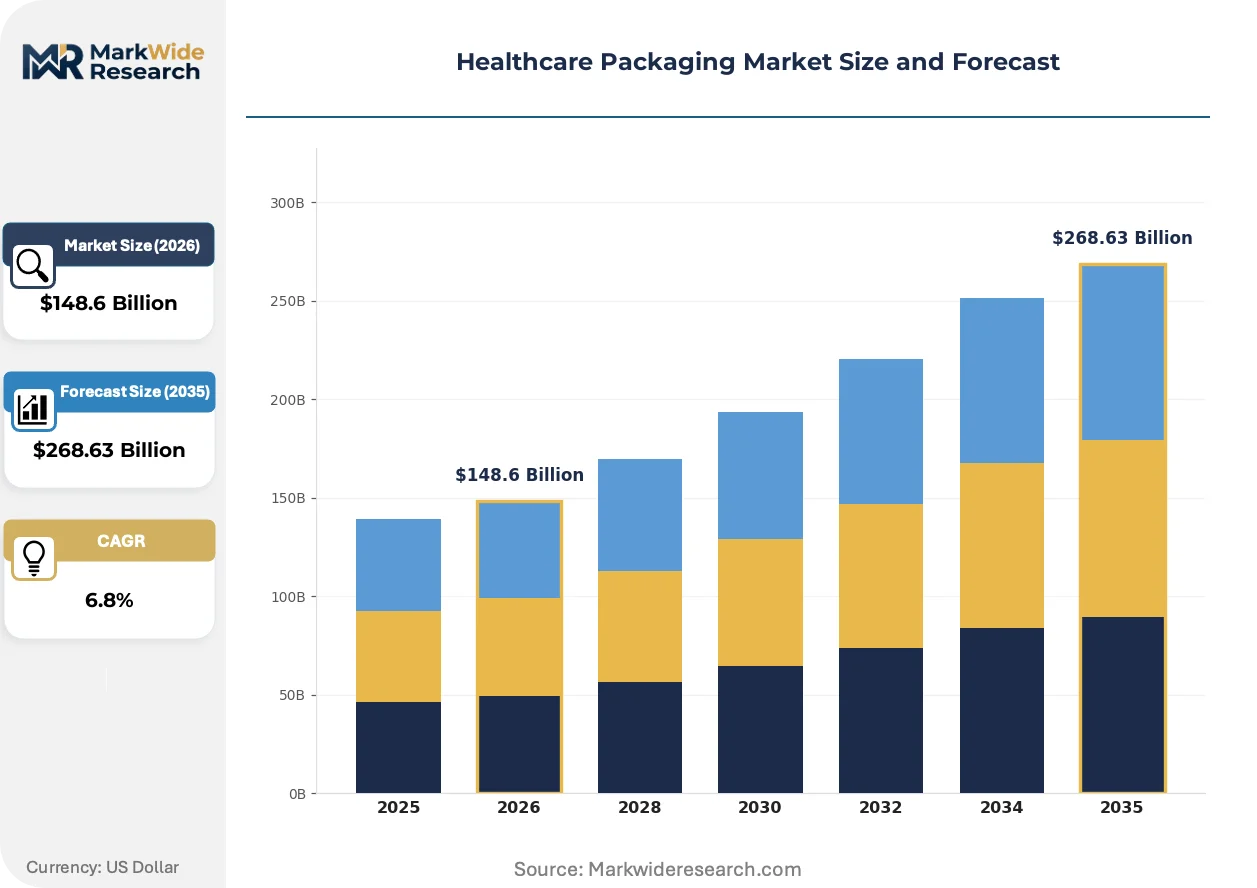
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Labels, Bottles, Sachets Material: Plastic, Glass, Paper, Aluminum Application: Pharmaceuticals, Medical Devices, Nutraceuticals, Diagnostics Regulatory Compliance: ISO Standards, FDA Regulations, EU Directives, GMP |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, Berry Global, West Pharmaceutical Services, AptarGroup Inc., WestRock Company, Becton Dickinson & Company, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging systems are migrating from pilot programs to commercial deployment, embedding sensors and connectivity directly into primary containers to monitor product integrity throughout distribution.
Printed electronics with near-field communication tags is electrifying unit-dose compliance tracking. Chronic disease management programs at US hospital systems are piloting NFC-enabled blister packs that timestamp patient access. The technology is electrifying adherence data capture for pay-for-performance reimbursement models.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barrier coatings from European pharmaceutical packaging by 2025. Converters are qualifying silicone oxide and aluminum oxide vapor-deposited alternatives for high-barrier applications. Blister packs for hygroscopic active pharmaceutical ingredients face the most acute material substitution pressure.
Direct contracting between pharmaceutical manufacturers and specialized packaging engineering firms is displacing traditional distributor-mediated procurement in North America. Large molecule drug sponsors are embedding packaging development teams within their device combination product groups. This pattern is most pronounced in Massachusetts and California, where biotech clusters maintain captive packaging innovation capabilities.
Healthcare Packaging Market Segmentation
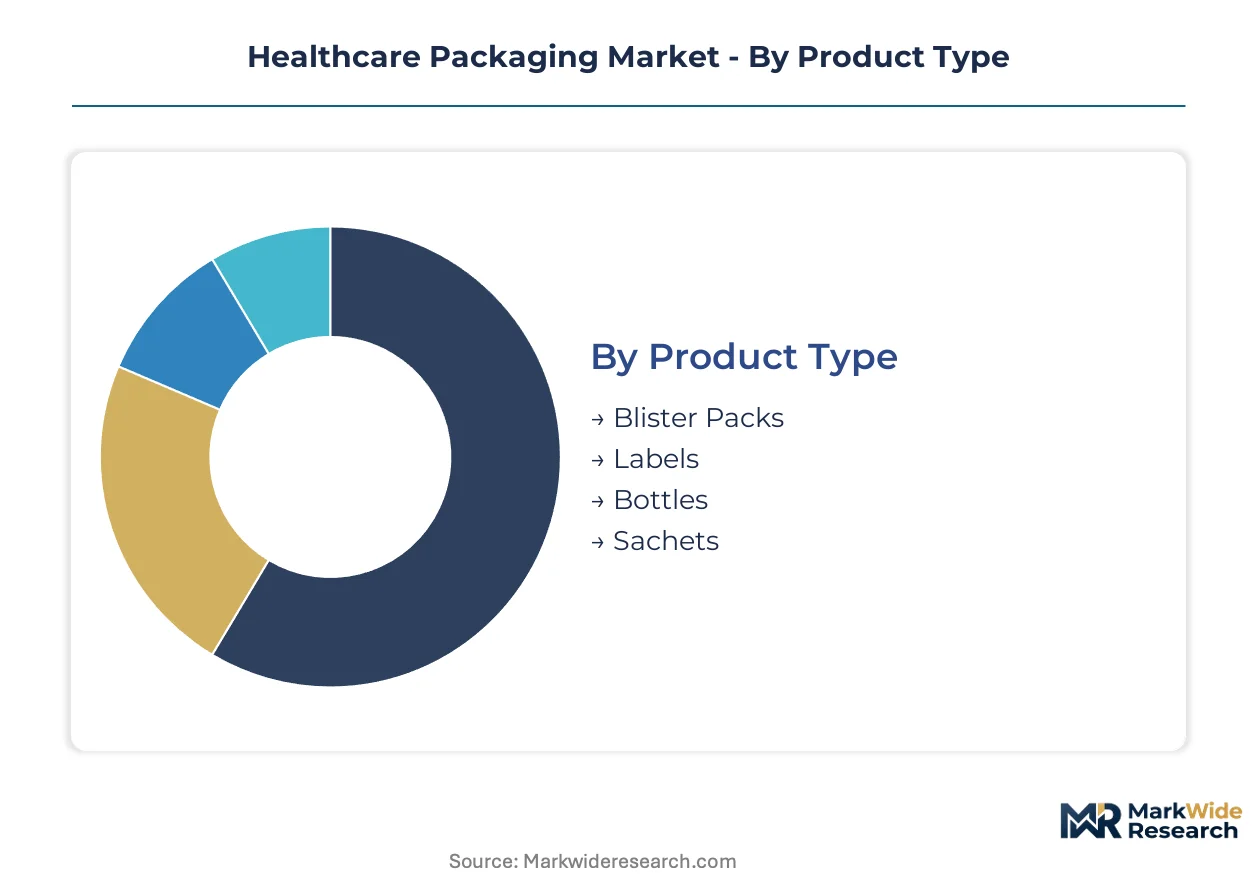
Healthcare packaging segmentation reveals divergent margin profiles across material classes and regulatory tiers. Product format selection directly determines sterilization compatibility, barrier performance, and serialization integration costs for pharmaceutical sponsors.
Product Type:
Volume concentrates in unit-dose formats, while premium margins accrue to specialized delivery systems requiring cleanroom fabrication.
- Blister Packs:Thermoformed or cold-formed cavities sealed with lidding foil dominate oral solid-dose pharmaceuticals. India's injectables sector and Germany's biologics hub drive demand for high-barrier cold-form variants with aluminum oxide coatings replacing fluoropolymer barriers under REACH deadlines.
- Labels:Pressure-sensitive and booklet formats integrate 2D barcodes and anti-tamper features for EU Falsified Medicines Directive compliance. Serialization mandates across European distribution networks elevate demand for thermal-transfer and digital print substrates.
- Bottles:Blow-molded HDPE and PET containers serve oral liquids and solid-dose bulk packaging.
- Sachets:Flexible strip packaging for unit-dose powders and granules.
Today's leader: Blister Packs. Tomorrow's challenger: Labels.
Material:
Cost tier stratification separates commodity resins from pharmacopeial-grade substrates commanding qualification premiums.
- Plastic:Medical-grade polypropylene and cyclic olefin copolymer lead injectables and respiratory devices. US Gulf Coast and Northeast Asian production clusters expose converters to hurricane and trade-route disruptions.
- Glass:Borosilicate and aluminosilicate tubing sustains premium positioning in biologics where extractables and leachables profiles must satisfy stringent pharmacopeial limits. Gerresheimer's captive operations in Germany and India anchor supply security.
- Paper:Fiber-forming technologies with plasma-deposited silica coatings emerge as recyclable alternatives to multi-layer plastic blisters.
- Aluminum:Cold-form foil laminates for moisture-critical formulations depend on rolling mill capacity concentrated in China and Russia.
Plastic holds volume dominance. Glass captures margin expansion.
Application:
Customer type fragmentation separates multinational pharmaceutical sponsors from regional generic manufacturers with divergent qualification requirements.
- Pharmaceuticals:Primary and secondary packaging for small molecules, biologics, and vaccines commands the largest value share. mRNA vaccine manufacturers in Marburg and Dresden commission dedicated cleanroom lines for parenteral fill-finish operations.
- Medical Devices:Sterile barrier systems for implants, surgical instruments, and diagnostic equipment.
- Nutraceuticals:Dietary supplements and functional foods with lower barrier requirements than prescription pharmaceuticals.
- Diagnostics:Specimen collection containers, reagent kits, and point-of-care test cassettes.
Pharmaceuticals anchor current revenue. Diagnostics offer steepest expansion trajectory.
Regulatory Compliance:
Geography determines which framework governs market access, with EU and US requirements setting the ceiling for supplier qualification.
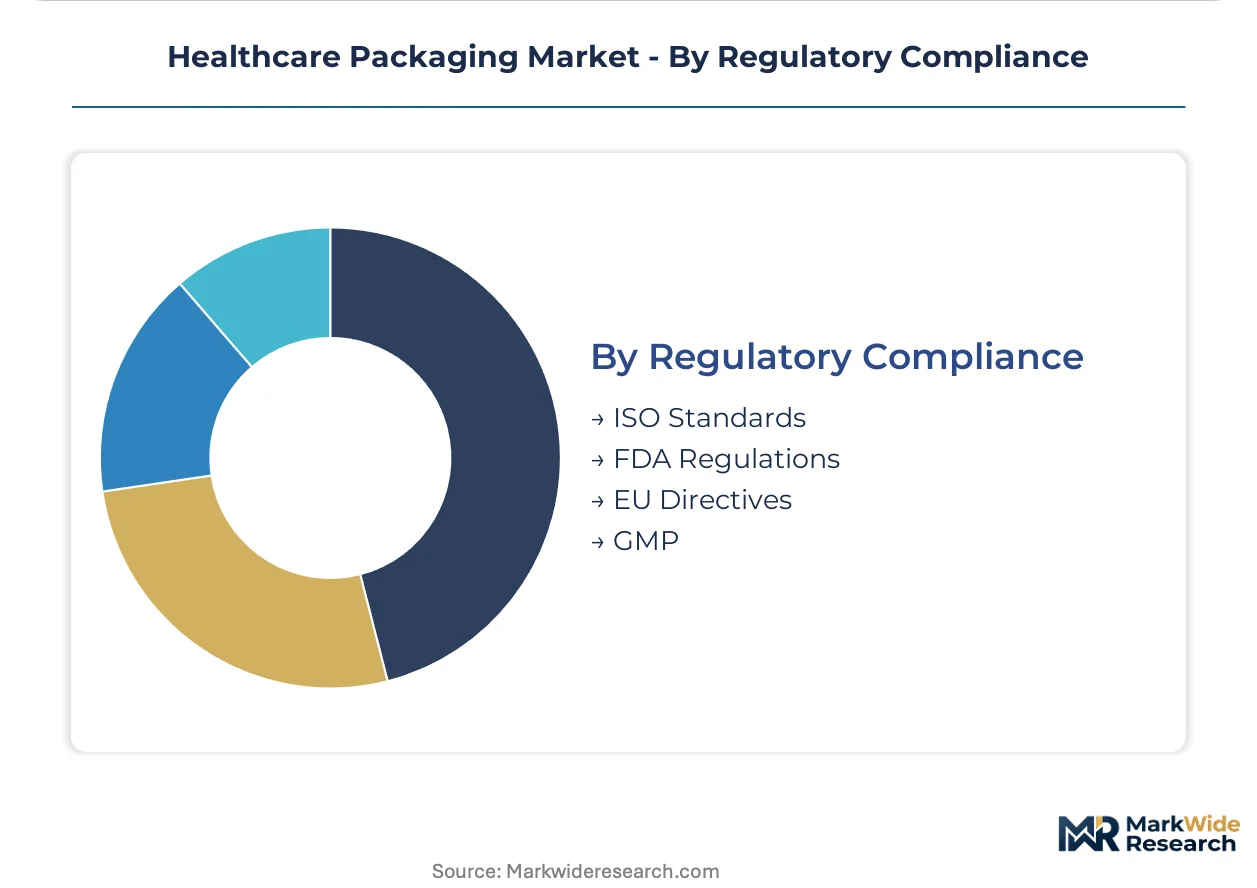
- ISO Standards:ISO 11607 for sterile barrier systems and ISO 15378 for pharmaceutical packaging materials establish baseline quality management systems. These determine supplier qualification status for multinational procurement teams.
- FDA Regulations:Drug master file submissions for primary packaging materials govern US market access. Novel polymer contact materials face 18-24 month qualification timelines.
- EU Directives:Falsified Medicines Directive serialization and Medical Device Regulation technical documentation requirements.
- GMP:Good Manufacturing Practice frameworks for pharmaceutical packaging operations.
ISO and FDA dominate qualification burden. EU Directives drive fastest-changing compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marburg and Dresden anchor pharmaceutical packaging demand through mRNA vaccine manufacturing clusters, while regulatory divergence across jurisdictions reshapes material qualification timelines and supplier selection criteria for healthcare packaging procurement teams.
United States
FDA drug master file reviews for novel polymer contact materials extend qualification timelines by 18-24 months, compressing commercialization windows for domestic sterile formulation manufacturers. Massachusetts and California biotech clusters maintain captive packaging innovation capabilities, embedding development teams within device combination product groups. The US Gulf Coast concentration of medical-grade polypropylene production exposes converters to hurricane-related supply disruptions.
Germany
Gerresheimer's captive glass-tubing operations in Germany anchor supply security for borosilicate primary containers serving biologics manufacturers. EU Falsified Medicines Directive serialization mandates expand demand for integrated authentication solutions across German distribution networks. Marburg and Dresden mRNA vaccine manufacturers commission dedicated cleanroom packaging lines for parenteral fill-finish operations.
India
CDSCO serialization deadlines accelerate barrier-grade polymer adoption among domestic sterile formulation manufacturers supplying regulated export markets. Maharashtra and Gujarat injectables producers upgrade polymer formats to meet track-and-trace integration requirements. Local converters retool lines for aggregation stations and warehouse management system compatibility.
China
Rolling mill capacity concentration for aluminum cold-form foil laminates creates input cost volatility for moisture-critical formulation packaging. NMPA regulations govern material biocompatibility submissions for primary packaging accessing domestic pharmaceutical markets. Yangtze River Delta converters face REACH-aligned substitution pressure for fluoropolymer barrier coatings in export-oriented production.
Switzerland
Swissmedic technical documentation requirements for pharmaceutical packaging materials establish premium qualification benchmarks for high-value biologics containers. Basel-area pharmaceutical sponsors direct-contract specialized packaging engineering firms, displacing traditional distributor-mediated procurement patterns. Alpine-region cleanroom certification standards exceed ISO 14644-1 Class 8 baselines for parenteral drug product containment.
Healthcare Packaging Market Key Industry Players
Global majors compete with regional champions across material qualification and cleanroom certification dimensions, producing a tiered structure where resin supply security and pharmacopeial-grade substrate access determine supplier viability. Consolidation concentrates among film extrusion and glass-tubing specialists, while fragmentation persists in blow-molded pharmaceutical-grade conversion. Three archetypes dominate: captive integrated manufacturers, specialized barrier substrate engineers, and scale-driven multi-material converters. Competitive moves center on backward integration into resin supply and geographic expansion of cleanroom assets.
Within the integrated manufacturing tier, Amcor plc and Gerresheimer AG exemplify divergent strategic positions. Amcor leverages global film extrusion footprint to secure alternative polymer streams across multiple sourcing jurisdictions. Gerresheimer anchors supply security through captive glass-tubing operations spanning German and Indian production clusters. Berry Global occupies a position among scale-driven converters extending blow-molded capacity into pharmaceutical-grade cleanroom environments.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| Berry Global |
| West Pharmaceutical Services |
| AptarGroup Inc. |
| WestRock Company |
| Becton Dickinson & Company |
| DuPont de Nemours Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up packaging specialists have consolidated North American film extrusion assets, tightening working capital discipline and compressing payment terms for resin distributors while passing through medical-grade polymer premiums to pharmaceutical sponsors.
Pricing Analysis
Input-cost pass-through from Gulf Coast polypropylene disruptions and Northeast Asian cyclic olefin copolymer freight spikes is accelerating contract renegotiations. Pricing stratifies across pharmacopeial-grade, ISO-certified, and commodity resin tiers, with cold-form aluminum foil laminates commanding premiums due to China and Russia rolling mill concentration. Cost compression in standard-grade blow-molded bottles is intensifying because food-grade converters are certifying pharmaceutical cleanroom lines. Regional generic manufacturers exhibit highest price sensitivity, while mRNA vaccine sponsors in Germany absorb premium pricing for borosilicate glass security.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions and trans-Pacific container rate spikes is forcing inventory positioning shifts among European distributors. Medical-grade polymer production clusters in the United States, South Korea, and Saudi Arabia draw from naphtha and propane feedstock pools exposed to energy price swings. Single-source vulnerability concentrates in Chinese aluminum cold-form foil and Indian borosilicate tubing for non-captive buyers. Distribution runs through pharmaceutical distributor networks in Europe, direct-contract channels in North America, and tender-based procurement in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthcare packaging market reads as a late-cycle quality story, with CDSCO and EU Falsified Medicines Directive serialization deadlines shifting procurement toward barrier-grade polymer and integrated authentication capabilities.
For Market Incumbents: Hedge resin supply exposure by securing alternative polymer streams across multiple sourcing jurisdictions, mirroring Amcor's multi-continent film extrusion footprint. Defend margin position through captive glass-tubing operations or backward integration into medical-grade polypropylene compounding. Serialization engineering talent scarcity threatens line integration timelines; acquire automation specialists familiar with GS1 aggregation standards. For New Entrants and Emerging Players: Mid-tier Indian injectables manufacturers represent an underserved buyer archetype seeking barrier-grade formats without multinational minimum order quantities. Paper-based barrier substrates with plasma-deposited silica coatings offer white-space positioning ahead of REACH fluoropolymer deadlines. Target German mRNA vaccine cleanroom packaging through specialized engineering partnerships rather than commodity conversion. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blow-molded bottle converters with food-grade assets requiring ISO 14644-1 Class 8 certification investment. Long-term viability hinges on qualification speed for novel polymer contact materials and serialization integration capabilities. Watch FDA drug master file review timelines as an inflection indicator for polymer innovation commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin Compounding | Captive polypropylene supply secures qualification continuity for CDSCO-mandated serialization upgrades. |
| Cold-Form Foil Laminates with REACH-Compliant Coatings | Silicon oxide vapor deposition replaces fluoropolymer barriers for hygroscopic API blister packs. |
| Cleanroom Certification of Food-Grade Blow-Molding Lines | ISO 14644-1 Class 8 conversion opens pharmaceutical oral liquid container markets. |
| Direct Contracting with Biotech Combination Product Groups | Embedded packaging development teams capture Massachusetts and California mRNA vaccine demand. |
| NFC-Enabled Blister Pack Commercial Deployment | Printed electronics integration timestamps patient access for US hospital pay-for-performance models. |
Research Approach
Direct dialogue with pharmaceutical packaging procurement managers, GPO contracts directors, regulatory affairs leads at CDSCO and FDA, and sterile formulation manufacturing heads grounded qualitative findings. Secondary validation drew from FDA drug master file submissions, EMA Falsified Medicines Directive implementation reports, ISO 15378 certification databases, and customs trade data for medical-grade polymer flows. Bottom-up line-item modeling and top-down market sizing triangulated volume and value estimates.
Segment-level outputs across material class, product format, application, and regulatory compliance tier were generated through the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating serialization mandate deadlines, cold-chain expansion trajectories, and REACH substitution timelines. Forecast inputs included CDSCO track-and-trace implementation schedules, EU GDP guideline revisions for temperature-sensitive biologics, and medical-grade resin capacity expansion announcements.
Inputs from FDA drug master file review databases and EU serialization aggregation system deployments were available through the study window; gaps in real-time polymer spot pricing and confidential pharmaceutical sponsor procurement contracts introduce uncertainty bands around near-term pricing dynamics. Forecasts reflect assumptions regarding regulatory deadline adherence and resin supply disruption frequency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices Packaging
Medical Devices Secondary Packaging Market
Medical Devices Packaging
Global First Aid Kit Packaging Market
Medical Devices Packaging
Sterile Wraps Market
Medical Devices Packaging
Bio-Medical Packaging Market
Medical Devices Packaging
US Home Care Packaging Market
Medical Devices Packaging
Asia-Pacific Parenteral Packaging Market
Medical Devices Packaging
Europe Parenteral Packaging Market
Medical Devices Packaging
Sterile and Antiviral Packaging Market
Medical Devices Packaging
Middle East and Africa Medical Devices Packaging Market
Medical Devices Packaging
Sterile Packaging Market
Medical Devices Packaging
Medical Processing Seals (MPS) Market
Medical Devices Packaging
Medical Implants Sterile Packaging Market
Medical Devices Packaging
Medical-Grade Foil Market
Medical Devices Packaging
North America Parenteral Packaging Market
Medical Devices Packaging
Global Medical Packaging Market
Medical Devices Packaging
Global Medical Devices Packaging Market