
 Meat and Poultry Processing Equipment Market | 2026-2036
Meat and Poultry Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Meat and Poultry Processing Equipment Market Analysis
Premium automated lines and commodity manual stations is decoupling across buyer tiers. Marel leads high-throughput smart system integration for large processing plants. GEA Group leverages thermal processing expertise to anchor European demand. Bettcher Industries specializes in precision cutting tools that dominate mid-scale butcher shop channels.
Meat and poultry processing equipment encompasses machinery for slaughtering, cutting, grinding, mixing, thermal treatment, and packaging of animal proteins, operating at temperatures from minus 40°C in blast freezing to 160°C in industrial ovens to ensure microbial safety and shelf-life extension. Smart systems with real-time yield monitoring and predictive maintenance protocols represent the fastest-expanding technology tier, while manual equipment retains stable replacement demand in emerging butcher shop segments. Vacuum sealers and brining tanks command concentrated margin pools where modified-atmosphere packaging and precision curing drive premium pricing.
USDA FSIS inspection mandates and FDA Food Safety Modernization Act traceability rules elevate capital requirements for US market entry, while EU MDR and CE marking frameworks shape equipment safety standards across European member states. Stakeholders must weigh compliance cost trajectories against automation payback periods when allocating capital across manual, semi-automatic, and smart system portfolios.
Market Dynamics
USDA FSIS inspection mandates and FDA Food Safety Modernization Act traceability rules are forcing processing plants to replace legacy manual stations with automated smart systems capable of real-time microbial monitoring and lot-level tracking.
Growth Catalysts
- USDA Hygiene Mandates:FSIS inspection protocols now require continuous temperature logging and automated washdown documentation, compelling mid-scale plants in the United States to upgrade to IoT-enabled equipment.
- Plant Protein Diversification:Contract manufacturers serving hybrid meat-analogue brands in Germany and Brazil are retrofitting grinding and blending lines for rapid protein-source switching.
- Cold Chain Expansion:Blast freezing demand from Brazilian beef exporters is accelerating deployment of minus 40°C tunnel freezers with integrated yield optimization sensors.
Market Restraints
- Stainless Steel Price Volatility:Grade 304 and 316 stainless steel input costs fluctuate with nickel and chromium spot markets, compressing margins for European thermal processing equipment fabricators.
- Specialized Component Concentration:Precision servo motors and hygienic bearings for high-speed cutting lines concentrate supply with German and Japanese industrial automation suppliers.
- CE Marking Complexity:EU MDR machinery safety assessments and notified body backlogs extend equipment certification timelines by four to eight months for non-European manufacturers.
Strategic Opportunities
- Indian Cold Chain Modernization:FSSAI enforcement of mandatory cold storage for poultry distribution is creating first-time equipment demand in Uttar Pradesh and Maharashtra processing clusters.
- Precision Curing Systems:Modified-atmosphere packaging integration with brining tank automation offers margin expansion in premium dry-cured meat segments across Iberian and Italian producer networks.
- 5G-Enabled Predictive Maintenance:Convergence of industrial IoT sensors with private 5G networks allows Brazilian and US plants to shift from scheduled to condition-based maintenance contracts.
Industry Challenges
- Mechatronics Talent Scarcity:Programming and maintaining servo-driven portioning equipment requires hybrid mechanical-electrical-software skills that outpace vocational training output in US Midwest processing corridors.
- Legacy System Integration:Retrofitting 1990s-era thermal processing ovens with modern data acquisition modules demands custom middleware development that stretches project timelines.
- Multi-Jurisdiction Certification Burden:Equipment destined for both US and EU markets must simultaneously satisfy USDA acceptance criteria and CE marking requirements, doubling documentation load.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat and Poultry Processing Equipment Market |
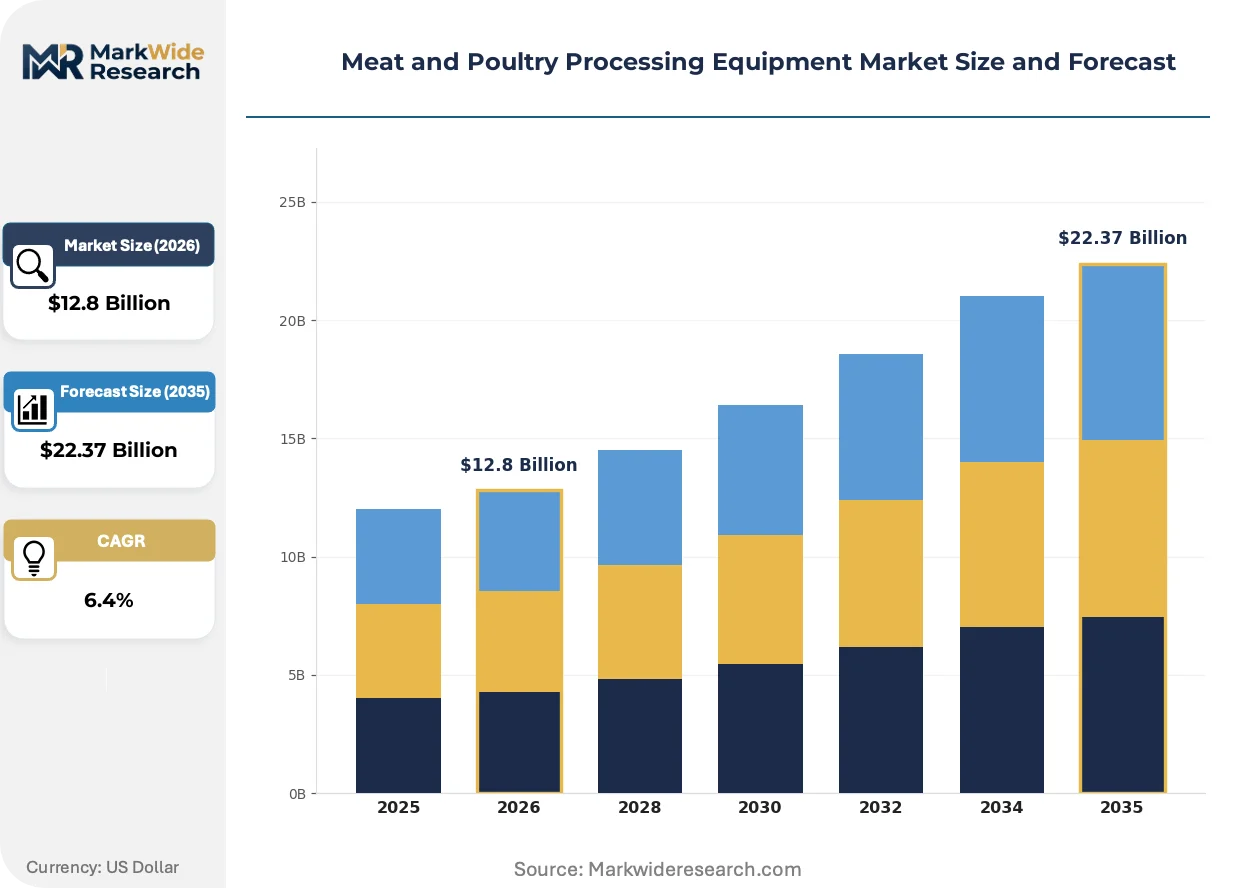
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Slicers, Sausage Stuffers, Brining Tanks, Vacuum Sealers Technology: Automatic, Semi-Automatic, Manual, Smart Systems End User: Processing Plants, Butcher Shops, Supermarkets, Restaurants Application: Processing, Packaging, Refrigeration, Cooking |
| Companies Covered | Baader, Bettcher Industries, GEA Group, Heat and Control, Duravant, Marel, The Middleby Corporation, Formax, John Bean Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat and Poultry Processing Equipment Market Emerging Trajectories
Smart automation is compressing the performance gap between artisan-scale precision and industrial throughput, while regulatory data mandates are embedding compliance functionality directly into equipment control architectures.
Machine vision-guided portioning systems with sub-millimetre accuracy are rewriting yield optimization protocols in high-volume poultry cutting operations. Large US and Brazilian integrators are deploying these systems at line speeds exceeding 200 birds per minute. The technology is rewriting traditional trade-offs between labour-intensive manual trimming and mass-production uniformity.
EU MDR machinery safety regulations and the FDA Food Safety Modernization Act's enhanced traceability requirements are mandating embedded data-logging capabilities in all new equipment installations. Manufacturers must now pre-integrate HACCP documentation software and automated washdown validation sensors. European thermal processing and US grinding equipment segments are responding with modular control platforms that simplify multi-jurisdiction compliance.
Service unbundling is fragmenting traditional equipment procurement patterns. Mid-scale butcher shops and specialty processors in Germany and the United States are shifting from capital purchase toward usage-based leasing with bundled maintenance. This restructuring is most visible in precision cutting tool and vacuum packaging equipment categories, where OEMs now retain asset ownership and charge per kilogram processed.
Meat and Poultry Processing Equipment Market Segmentation
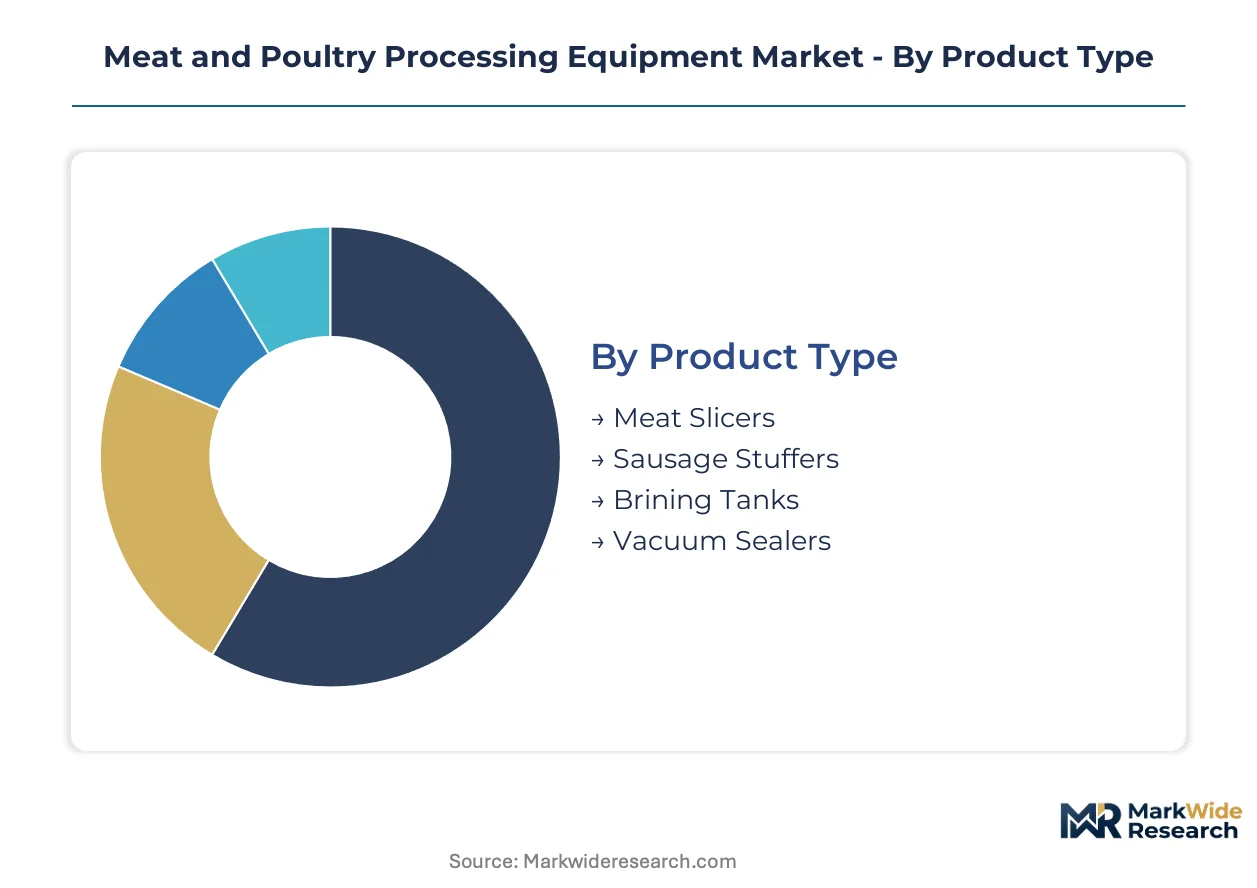
Equipment buyers in this market face starkly different procurement logics across automation tiers and facility scales. Segmentation reveals where capital concentrates versus where replacement cycles dominate purchasing behavior.
Product Type:
Standardized units serve high-volume commodity processing while customized configurations anchor premium cured-meat and specialty packaging workflows.
- Meat Slicers:Rotary blade systems with adjustable thickness controls dominate high-throughput deli and bacon operations. Processing plants in Germany and the United States are retrofitting slicer lines with integrated checkweighers to comply with FDA net-weight verification mandates.
- Sausage Stuffers:Piston-driven and vacuum-assisted stuffing technologies vary by casing type and emulsion viscosity. Butcher shops in Brazil's São Paulo state are driving demand for mid-capacity hydraulic stuffers as artisanal sausage production expands.
- Brining Tanks:Stainless steel vessels with precision saline circulation serve dry-cured meat producers across Iberian and Italian networks.
- Vacuum Sealers:Chamber and external suction configurations handle modified-atmosphere packaging for retail-ready portions.
Leading the category by volume: Meat Slicers. Growing fastest: Vacuum Sealers.
Technology:
Capital intensity and labor substitution potential create four distinct investment thresholds across the automation spectrum.
- Automatic:Fully integrated lines with programmable logic controllers manage continuous-flow slaughtering through packaging sequences. Brazilian beef exporters in Mato Grosso are deploying automatic tunnel freezers with yield optimization sensors to meet cold chain expansion requirements.
- Semi-Automatic:Operator-supervised stations balance throughput with flexibility for mixed-species processing. Mid-scale plants in the US Midwest favor semi-automatic grinding and blending equipment to accommodate shifting USDA FSIS inspection protocols without full line replacement.
- Manual:Hand-operated saws, knives, and stuffer units retain stable demand in emerging butcher shop segments and specialty processing.
- Smart Systems:IoT-enabled equipment with predictive maintenance protocols and real-time microbial monitoring represents the technology tier expanding most quickly.
Automatic equipment commands the largest installed base. Smart Systems are gaining share fastest as regulatory data mandates harden.
End User:
Facility scale and regulatory exposure determine whether buyers prioritize throughput maximization or compliance-driven equipment refresh cycles.
- Processing Plants:Large integrated operations with USDA or equivalent national inspection status require continuous-duty equipment with automated washdown validation. Plants across the United States are replacing legacy thermal processing ovens with data-logging-capable units to satisfy FDA Food Safety Modernization Act traceability rules.
- Butcher Shops:Small-batch operations favor precision cutting tools and manual or semi-automatic stations with rapid changeover capability. German craft butcher networks are shifting toward usage-based leasing models for vacuum packaging equipment.
- Supermarkets:In-store processing departments demand compact, sanitary equipment for case-ready meat preparation.
- Restaurants:Commercial kitchen operations prioritize portion control and food safety compliance in compact footprints.
Processing Plants absorb the majority of capital expenditure. Butcher Shops are expanding fastest as service unbundling spreads.
Application:
Temperature extremes and regulatory touchpoints fragment equipment requirements across the protein transformation chain.
- Processing:Slaughtering, cutting, grinding, and mixing operations span ambient to chilled environments with strict USDA FSIS or EU hygiene mandates. High-speed portioning systems with machine vision guidance are penetrating US and Brazilian poultry cutting operations.
- Packaging:Modified-atmosphere and vacuum technologies extend shelf life for retail distribution. Precision curing system integration with brining tank automation is creating margin expansion in premium dry-cured segments.
- Refrigeration:Blast freezing and cold storage equipment operates at minus 40°C for export-grade beef preservation.
- Cooking:Thermal processing ovens and smokehouses deliver microbial safety through controlled heat application.
Processing commands the deepest equipment footprint. Packaging is climbing the fastest as traceability requirements embed into control architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors processing equipment demand across Brazil's protein belt. USDA-inspected plants in the United States and EU MDR-certified facilities in Germany concentrate capital deployment for smart system upgrades.
United States
Midwestern beef and poultry clusters drive automated line retrofits for FSIS compliance. FDA Food Safety Modernization Act traceability rules mandate embedded data-logging in new thermal processing installations. Nebraska and Iowa processing corridors are replacing legacy manual stations with IoT-enabled yield monitoring systems.
Germany
Bavarian meat processors and Rhineland packaging integrators anchor European demand for precision curing equipment. EU MDR machinery safety assessments and CE marking frameworks govern equipment certification timelines. Stuttgart-area automation suppliers are concentrating servo motor production for high-speed cutting lines serving Iberian cured-meat networks.
Brazil
Mato Grosso beef exporters and São Paulo poultry integrators deploy tunnel freezers with minus 40°C blast capacity for export-grade preservation. ANVISA sanitary regulations align with USDA equivalence protocols for North American market access. Campinas technology clusters are developing 5G-enabled predictive maintenance platforms for processing plant networks.
India
Uttar Pradesh and Maharashtra poultry processing clusters generate first-time equipment demand from cold chain modernization. FSSAI enforcement of mandatory cold storage distribution rules elevates capital requirements for market entry. Pune fabrication workshops are scaling stainless steel vessel production for brining and thermal treatment applications.
China
Shandong Peninsula pork processors and Yangtze River Delta poultry integrators balance domestic volume with export-grade equipment specifications. GB standards and SAMR food safety frameworks shape local equipment procurement decisions. Qingdao port logistics clusters are expanding blast freezing capacity for Australian and Japanese protein trade routes.
Meat and Poultry Processing Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation sophistication and regulatory compliance depth. The vendor base stratifies between integrated system architects, precision tool specialists, and regional fabrication houses serving replacement cycles. Three archetypes dominate: multinational turnkey providers, mid-cap precision equipment specialists, and stainless steel fabricators with hygienic design expertise. Competitive moves concentrate on strategic partnerships for IoT platform integration and geographic expansion into FSSAI-regulated Indian markets.
Within the integrated system tier, Marel and GEA Group occupy positions defined by high-throughput smart system deployment and thermal processing expertise respectively. Bettcher Industries exemplifies the precision-tool specialist archetype, anchoring mid-scale butcher shop channels with cutting equipment that balances artisan-scale accuracy against industrial durability. These three entities represent distinct competitive vectors: automation platform depth, thermal engineering heritage, and precision mechanics specialization.
| Leading Market Players |
|---|
| Baader |
| Bettcher Industries |
| GEA Group |
| Heat and Control |
| Duravant |
| Marel |
| The Middleby Corporation |
| Formax |
| John Bean Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Mechatronics engineers concentrated in Stuttgart and Osaka feed labor-cost differentials into three-tier pricing spreads across manual, semi-automatic, and smart system tiers. Stainless steel fabricators in Pune and Qingdao compete on wage arbitrage while German automation houses command premium positioning through servo motor integration density.
Pricing Analysis
Yield-guarantee contracts anchor value-based pricing for IoT-enabled equipment with real-time microbial monitoring and predictive maintenance protocols. Pricing stratifies across premium smart systems, standard automatic lines, and economy manual stations, with CE marking tier and USDA FSIS data-logging certification as primary differentiation drivers. Cost compression in economy tiers is intensifying because Indian and Chinese fabricators are scaling stainless steel vessel production. Mid-scale butcher shops exhibit highest price sensitivity, while large processing plants with USDA inspection status prioritize compliance-grade equipment regardless of premium positioning.
Supply Chain Analysis
Workforce availability for hygienic welding and precision servo calibration concentrates in Germany, Japan, and select Indian fabrication clusters. Supply draws from nickel and chromium spot markets for Grade 304 and 316 stainless steel, precision servo motors from German and Japanese industrial automation suppliers, and hygienic bearings for high-speed cutting lines. Single-source vulnerability in precision motion control components exposes European thermal processing equipment fabricators to extended lead times. Distribution runs through OEM direct sales for large processing plants, regional distributor networks for mid-scale butcher shops, and usage-based leasing platforms for specialty processors in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where mechatronics talent scarcity in US Midwest processing corridors props pricing for smart system integration contracts.
For Market Incumbents: Extend predictive maintenance service contracts to capture recurring revenue from Brazilian beef exporters deploying tunnel freezers with yield optimization sensors. Consolidate position by acquiring stainless steel fabricators in Pune with FSSAI-compliant hygienic design expertise, countering emerging competition from Indian cold chain modernization entrants. For New Entrants and Emerging Players: Launch via usage-based leasing models targeting German craft butcher networks shifting from capital purchase toward per-kilogram processed contracts. Penetrate the precision curing systems segment across Iberian and Italian producer networks where modified-atmosphere packaging integration with brining tank automation commands margin expansion unavailable in commodity processing equipment. For Investors and Strategic Acquirers: Re-rating potential sits with precision-tool specialists given embedded data-logging capabilities mandated by FDA Food Safety Modernization Act traceability rules. Long-term viability favors mid-cap equipment fabricators with CE marking and USDA acceptance criteria documentation capacity. Monitor ANVISA-FSIS regulatory alignment negotiations as inflection signal for Brazilian export-grade equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart System Platform Integration | GEA Group and Marel anchor European demand through IoT-enabled thermal processing and yield monitoring deployment. |
| Precision Curing System Development | Bettcher Industries captures premium dry-cured meat segments across Iberian networks with brining tank automation. |
| Regional Fabrication Expansion | Pune workshops scale FSSAI-compliant stainless steel vessel production for Uttar Pradesh poultry clusters. |
| 5G-Enabled Predictive Maintenance | Campinas technology clusters develop condition-based service contracts for Brazilian Mato Grosso beef exporters. |
| Multi-Jurisdiction Certification Investment | Equipment vendors simultaneously satisfy USDA acceptance criteria and CE marking to access US-EU dual markets. |
Methodological Framework
Trade publications, equipment procurement databases, and regulatory filing repositories formed the secondary backbone for this analysis. Primary interviews with plant engineers at USDA-inspected facilities, aftermarket service heads at precision cutting tool specialists, OEM procurement teams at Brazilian beef exporters, and maintenance directors at German packaging integrators combined with customs records and SEC 10-K equipment expenditure disclosures. Bottom-up unit shipment estimates and top-down capital expenditure triangulation validated segmentation outputs across automation tiers.
Historical trendline analysis of equipment replacement cycles and regulatory compliance-driven refresh patterns informed the projection framework. Segmentation dimensions modeled include product type, automation technology tier, facility scale, and application temperature extreme across the analysis window. CAGRs derived from installed base evolution and capital intensity ratios incorporated cold chain expansion trajectories in Brazil and India, FSIS protocol tightening in the United States, and EU MDR machinery safety assessment timelines.
Stainless steel price volatility, notified body certification backlogs, and mechatronics training pipeline gaps are the dominant revision risks to forecast assumptions. Material deviation in input cost trajectories, regulatory enforcement intensity, or vocational education output warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Seed Processing Equipment Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market