
 Animal Feed Processing Equipment Market | 2026-2036
Animal Feed Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Processing Equipment Market Analysis
Market Context
The capital-intensity divergence between integrated engineering groups and regional fabrication shops is unwinding competitive stability across the sector. Bühler Holding AG leverages its Swiss-based R&D campus to sustain premium positioning in thermal processing lines for aquafeed. Jiangsu Muyang Group Co., Ltd. anchors volume supply across Asia through vertically integrated steel-forging and assembly plants. Andritz AG competes on pelletizing technology leadership, extending its Austrian engineering base into South American livestock markets.
Technical Definition and Structural Segments
Animal feed processing equipment encompasses mechanical and thermal systems designed to reduce particle size, homogenize ingredient blends, and form durable pellets with specified durability indices exceeding ninety-five percent for aquatic species. Extruders operate at barrel temperatures between one hundred twenty and one hundred eighty degrees Celsius to gelatinize starches and deactivate anti-nutritional factors in oilseed meals. Mills dominate installed base value due to universal grinding demand across all feed categories, while extruders capture the fastest growth trajectory as salmon and shrimp producers substitute fishmeal with processed plant proteins. Mixers hold mature margin pools in developed markets where batch uniformity regulations enforce replacement cycles.
Regulatory Frame and Outlook
The EU F-Gas Regulation and REACH chemical standards constrain refrigerant and lubricant choices in thermal processing equipment sold across Europe. FDA feed safety rules under the Food Safety Modernization Act mandate hazard analysis plans for equipment contacting medicated premixes in the United States. China's SAMR enforces GB standards on heavy-metal migration from alloy contact surfaces in feed mills. Stakeholders must monitor how divergent carbon-accounting rules for Scope three emissions reshape equipment procurement criteria across integrated protein supply chains.
Market Dynamics
Automated feed milling capacity expansion across commercial livestock operations is compressing replacement cycles for grinding and thermal processing lines. This capital deployment wave reflects processor efforts to meet export-grade protein standards while absorbing digital batch-tracking mandates from farm-to-fork traceability frameworks.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Tightened feed-to-food traceability rules in Europe are pushing processors toward digital batch-tracking systems and automated quality control infrastructure.
- Aquaculture protein substitution:Salmon and shrimp producers are accelerating extruder deployments to process plant-based proteins as fishmeal alternatives, driving thermal processing equipment demand.
- Captive feed manufacturing consolidation:Integrated pork producers in China's Yangtze River Delta are centralizing feed production into owned facilities, expanding installed base for mills and mixers.
Market Restraints
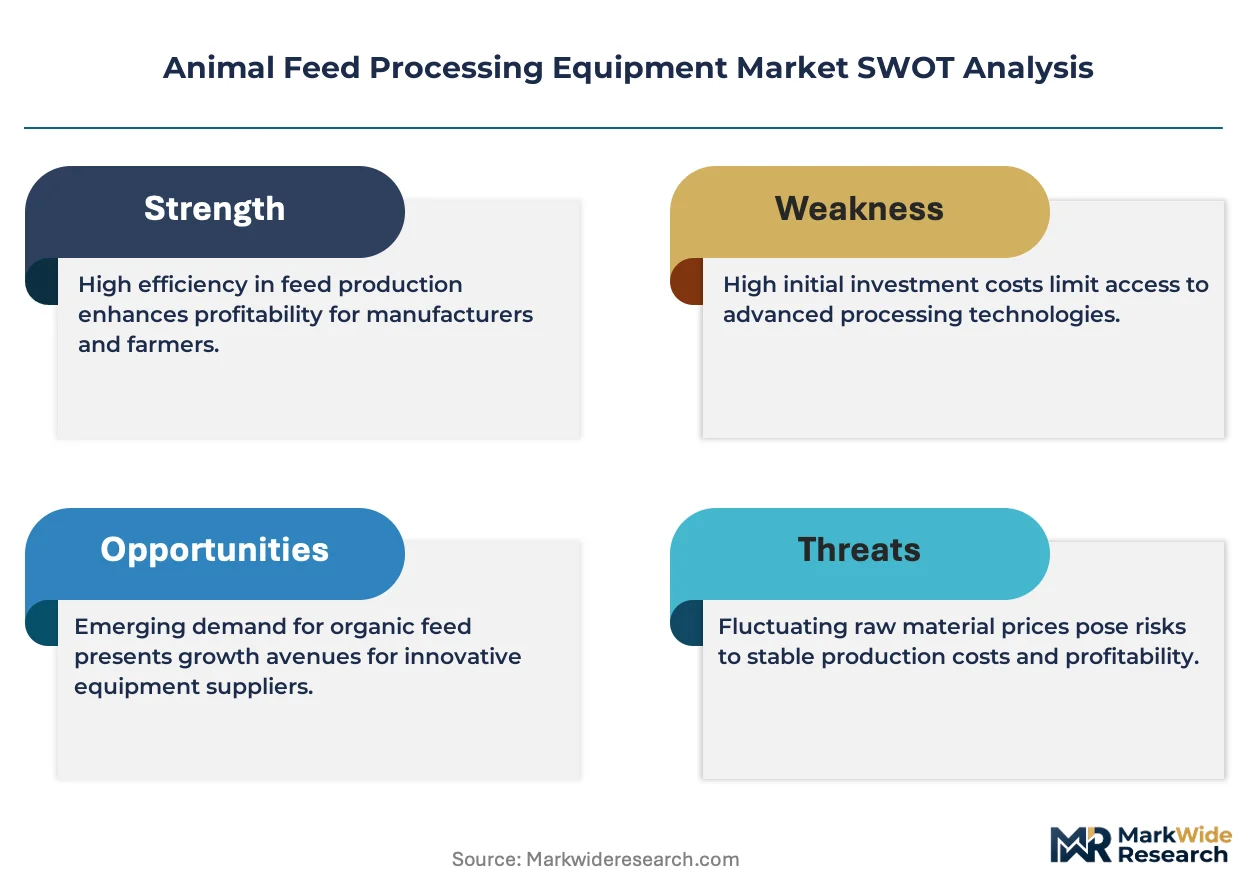
- Alloy input cost volatility:Stainless steel and specialty alloy price swings constrain margin stability for equipment fabricators producing contact-surface components.
- European regulatory friction:The EU F-Gas Regulation and REACH chemical standards restrict refrigerant and lubricant choices in thermal processing lines sold across member states.
- Technical limitation in small-batch flexibility:Large-scale extruders and pellet mills face configuration constraints when processors require rapid formulation changeovers for niche species feeds.
Strategic Opportunities
- Brazilian automated livestock expansion:Commercial cattle and poultry operations are scaling feed milling capacity to meet export certification requirements, creating equipment deployment openings.
- Dual carbon goals in China:National decarbonization targets are incentivizing energy-efficient thermal processing retrofits and waste-heat recovery system installations.
- Sensor-software convergence:Integration of inline near-infrared spectroscopy with batch control software enables real-time formulation adjustment, creating premium upgrade paths.
Industry Challenges
- Control systems integration complexity:Legacy pneumatic batch controllers require extensive retrofit engineering to interface with digital traceability platforms demanded by EU and US buyers.
- Thermal process engineering talent scarcity:Specialized expertise in extruder die design and starch gelatinization kinetics remains concentrated among retiring cohorts at original equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Processing Equipment Market |
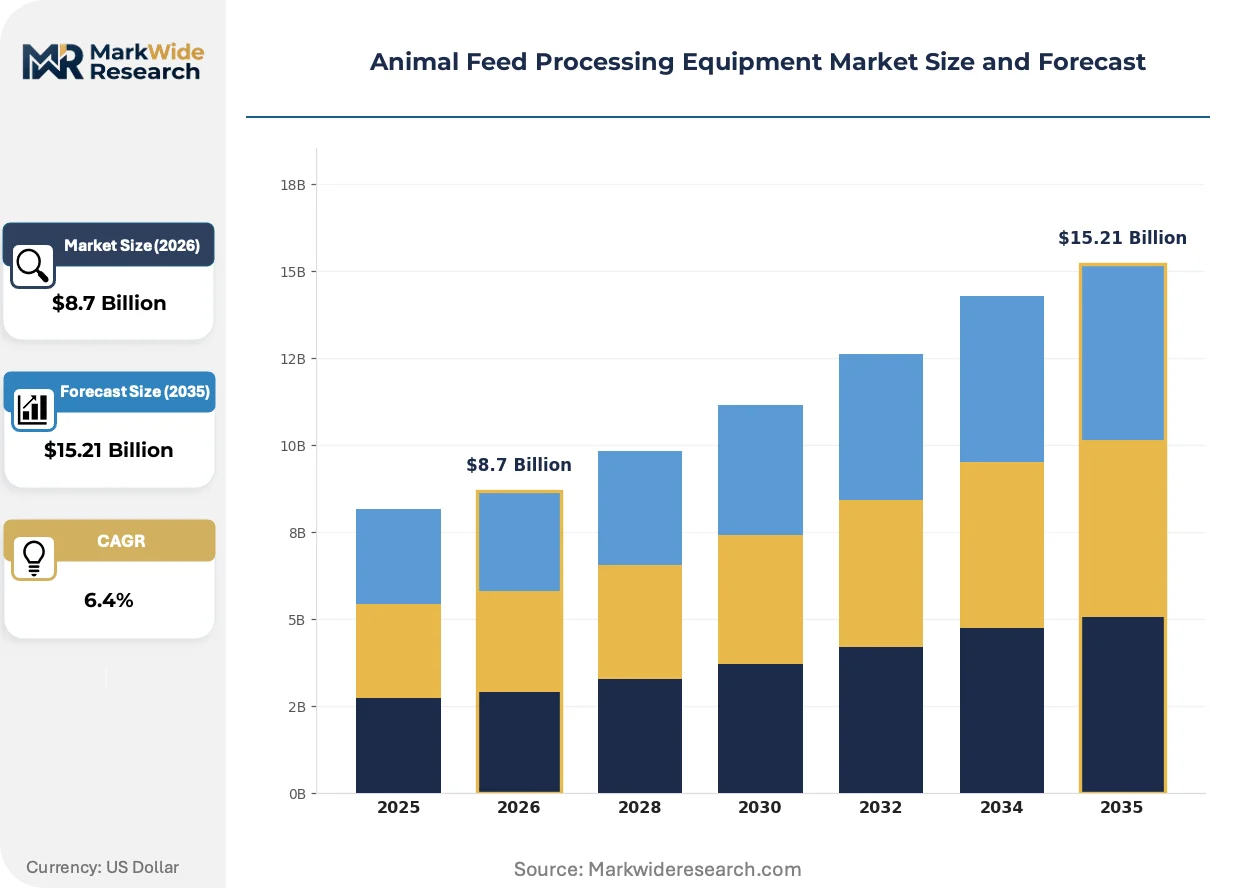
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mills, Mixers, Extruders, Dryers End User: Livestock Farms, Poultry Farms, Aquaculture, Pet Food Manufacturers Technology: Mechanical Processing, Thermal Processing, Chemical Processing, Biological Processing Application: Feed Pelleting, Feed Grinding, Feed Blending, Feed Coating |
| Companies Covered | Jiangsu Muyang Group Co., Ltd., Wenger (Marel), Bühler Holding AG, FAMSUN, ZhengChang Group, Andritz AG, Amandus Kahl GmbH & Co. KG, Double Crane Machinery, CPM Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Processing Equipment Market Emerging Trajectories
Digital instrumentation and modular equipment architectures are compressing deployment timelines and enabling distributed manufacturing models. These shifts are reshaping how processors procure, operate, and upgrade feed production assets.
Near-infrared spectroscopy sensors embedded directly into mixer discharge chutes are enabling real-time moisture and protein measurement. Aquafeed manufacturers in Norway and Chile are adopting these systems fastest to maintain pellet durability indices above ninety-five percent. Inline quality verification is miniaturizing laboratory functions onto the production floor, reducing offline testing delays.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in feed cooling systems. Equipment suppliers must redesign thermal exchange units around natural refrigerants with lower global warming potential. Pellet cooler lines destined for European markets now face extended certification timelines and modified engineering specifications.
Integrated protein companies are unbundling equipment procurement from long-term service contracts. Large pork and poultry operators in the US Midwest now source mills and extruders through capital leases while contracting maintenance separately to regional specialists. This financing separation is most pronounced among publicly traded agribusinesses managing quarterly capital allocation targets.
Animal Feed Processing Equipment Market Segmentation
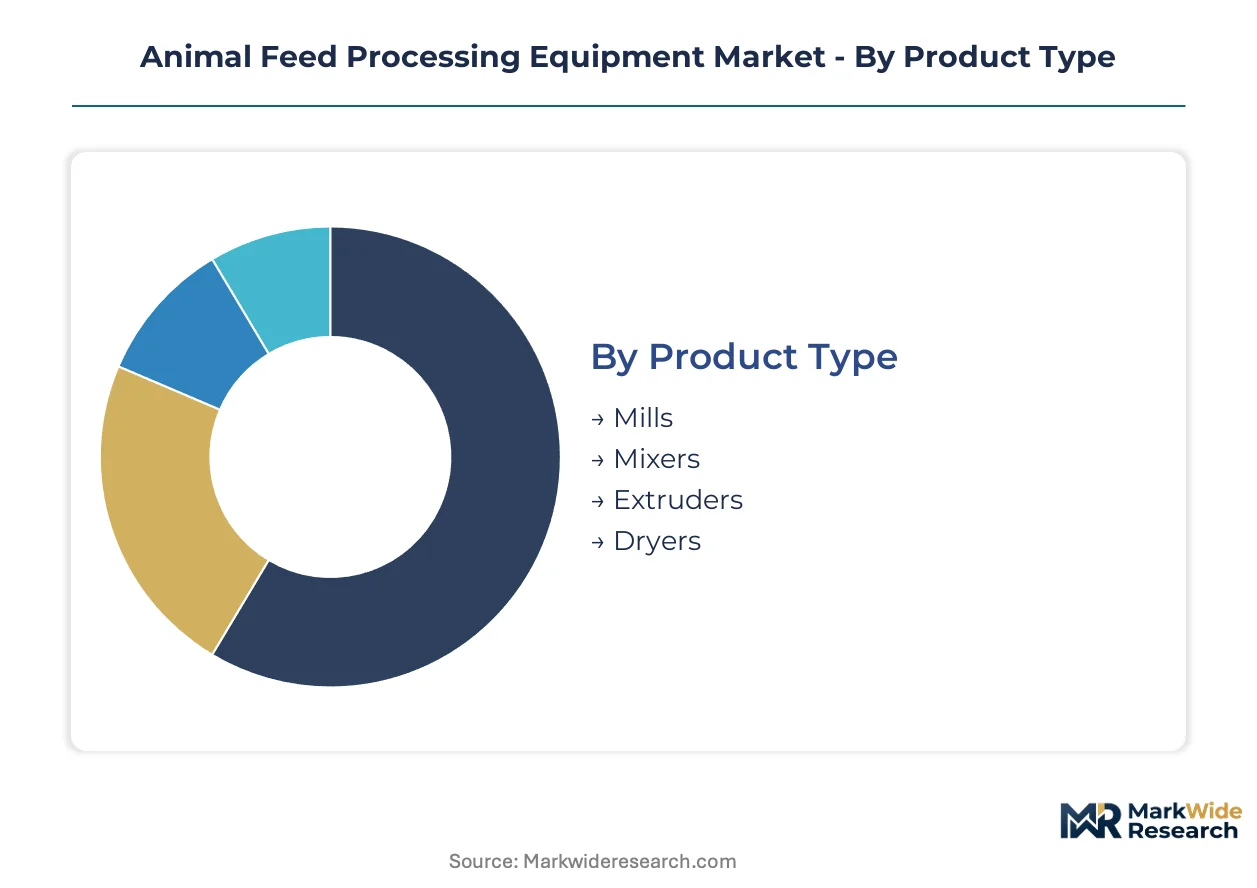
Segmentation in animal feed processing equipment reveals how regulatory pressure and protein substitution economics reshape capital allocation across grinding, thermal, and forming systems. Equipment buyers prioritize traceability-compliant configurations in Europe, energy-efficient retrofits in China, and export-grade automation in Brazil.
Product Type:
EU F-Gas Regulation and REACH chemical standards constrain refrigerant and lubricant choices in thermal processing lines sold across Europe, while FDA feed safety rules mandate hazard analysis plans for equipment contacting medicated premixes in the United States.
- Mills:Universal grinding systems reduce particle size across all feed categories through hammer, roller, or disc configurations. Demand concentrates in China's Yangtze River Delta where integrated pork producers are consolidating feed manufacturing into captive facilities requiring high-throughput grinding capacity.
- Extruders:Barrel temperatures between one hundred twenty and one hundred eighty degrees Celsius gelatinize starches and deactivate anti-nutritional factors in oilseed meals. Salmon and shrimp producers in Norway and Chile are accelerating deployments to process plant-based proteins as fishmeal alternatives, driving thermal processing equipment demand.
- Mixers:Batch uniformity systems homogenize ingredient blends to specified coefficient of variation thresholds. China's SAMR enforces GB standards on heavy-metal migration from alloy contact surfaces, enforcing replacement cycles in developed markets.
- Dryers:Moisture reduction systems condition pellets to storage-stable humidity levels. Brazilian commercial livestock operations are scaling automated feed milling capacity to meet export-grade protein standards.
Mills handle the majority of throughput; extruders are gaining share fastest as aquaculture protein substitution accelerates.
End User:
Customer type determines equipment scale, automation tier, and service contract structure, with integrated protein companies unbundling procurement from long-term maintenance agreements.
- Livestock Farms:Cattle and swine operations deploy grinding and pelleting lines for on-farm or cooperative feed production. Large pork operators in the US Midwest now source mills through capital leases while contracting maintenance separately to regional specialists.
- Aquaculture:Salmon and shrimp producers require extruders achieving pellet durability indices exceeding ninety-five percent. Inline near-infrared spectroscopy sensors embedded in mixer discharge chutes enable real-time moisture verification for these exacting specifications.
- Poultry Farms:Broiler and layer operations prioritize high-throughput pelleting for uniform feed conversion ratios. Brazil's commercial poultry sector is scaling feed milling capacity to meet export certification requirements.
- Pet Food Manufacturers:Niche formulation demands drive smaller-batch flexible processing configurations. Large-scale extruders face configuration constraints when processors require rapid changeovers for specialty recipes.
Livestock farms deploy the largest installed base; aquaculture is expanding most quickly on protein substitution economics.
Technology:
Cost tier separation between mechanical baseline systems and thermal premium equipment widens as energy efficiency mandates intensify.
- Mechanical Processing:Grinding, mixing, and conveying systems form the baseline installed value across all feed categories. These systems dominate replacement cycles in mature markets where batch uniformity regulations enforce equipment refresh.
- Thermal Processing:Extrusion and drying systems capture premium positioning through starch gelatinization and pathogen reduction capabilities. China's dual carbon goals are incentivizing energy-efficient thermal processing retrofits and waste-heat recovery installations.
- Chemical Processing:Enzyme treatment and pH adjustment systems modify nutritional availability and shelf stability. Regulatory constraints on additive contact surfaces limit deployment flexibility in EU and US markets.
- Biological Processing:Fermentation and probiotic inoculation systems enhance digestibility and gut health outcomes. Technical expertise scarcity in microbial process control constrains adoption velocity.
Mechanical processing anchors the installed base; thermal processing is climbing the fastest on aquafeed expansion and energy retrofit demand.
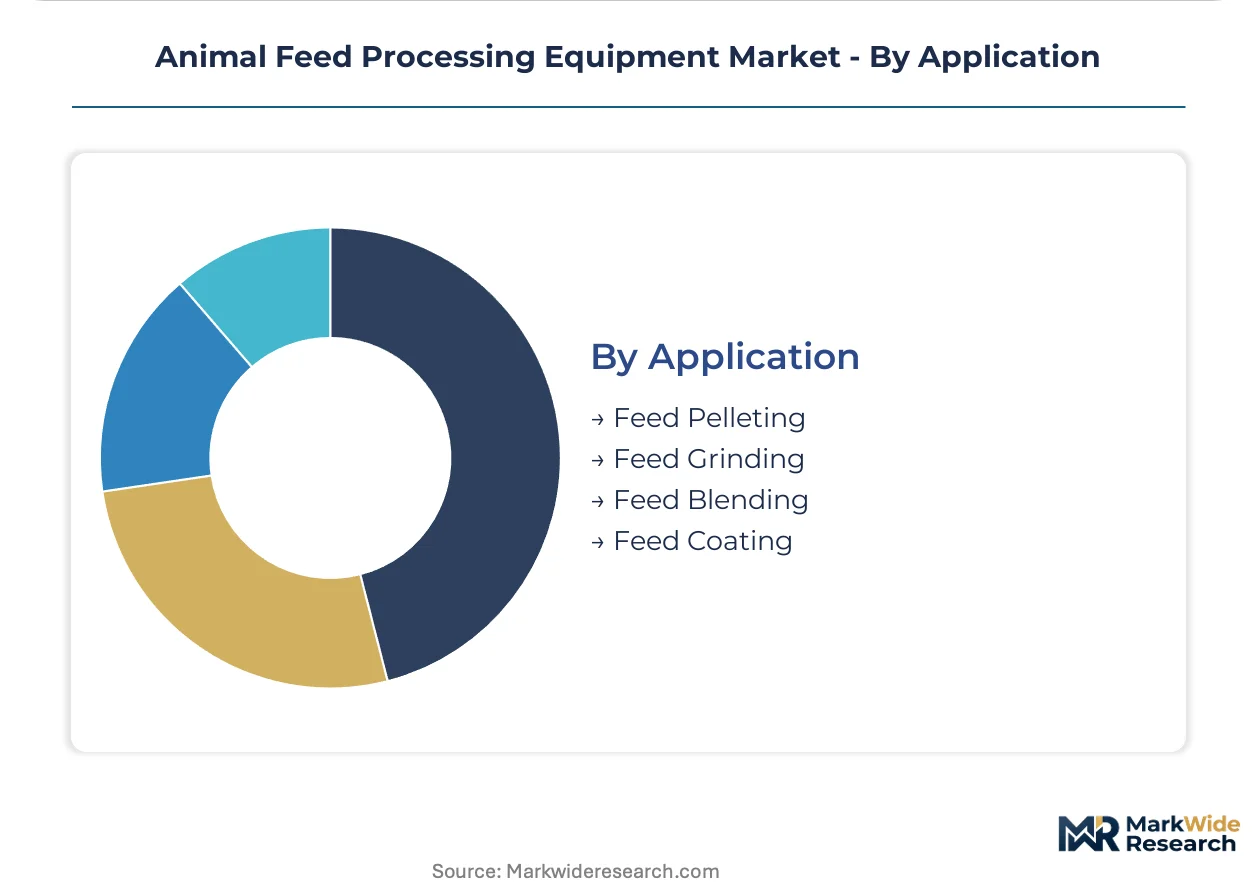
Application:
Margin concentration follows process complexity, with coating and extrusion commanding premium pricing over grinding and blending.
- Feed Pelleting:Compression forming systems produce durable pellets for mechanical handling and controlled nutrient release. Pellet cooler lines destined for European markets face extended certification timelines under F-Gas Regulation phase-down requirements.
- Feed Grinding:Particle size reduction enables ingredient dispersion and digestibility optimization. Automated feed milling capacity expansion across commercial livestock operations is compressing replacement cycles for grinding lines.
- Feed Blending:Homogeneous mixing ensures uniform nutrient distribution across batches. Digital batch-tracking mandates from EU Farm to Fork Strategy are pushing processors toward automated quality control infrastructure.
- Feed Coating:Surface application systems deliver fats, enzymes, and medications for targeted nutrient delivery. Coating lines achieve highest margin pools through precision application technology and formulation flexibility.
Feed grinding processes the largest volume throughput; feed coating is expanding most quickly on precision nutrition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European thermal processing lines where F-Gas Regulation compliance adds certification premiums, while Chinese fabricators compete on alloy cost efficiency and domestic scale. This asymmetry shapes procurement patterns across protein supply chains.
China
Integrated pork producers in the Yangtze River Delta are consolidating feed manufacturing into captive facilities, expanding demand for high-throughput mills and mixers. SAMR enforces GB standards on heavy-metal migration from alloy contact surfaces, tightening equipment specifications. Shanghai and Jiangsu province host the densest cluster of domestic engineering groups serving this captive manufacturing wave.
Brazil
Commercial cattle and poultry operations are scaling automated feed milling capacity to meet export certification requirements for EU and Middle Eastern protein buyers. ANVISA aligns with international feed safety protocols, elevating equipment hygiene standards. São Paulo state anchors the heaviest concentration of new extruder and pelleting line deployments.
Germany
Aquafeed manufacturers along the North Sea coast require extruders achieving pellet durability indices exceeding ninety-five percent for salmon and trout operations. ECHA REACH standards constrain lubricant and refrigerant choices in thermal processing equipment. Lower Saxony and Schleswig-Holstein host specialized engineering consultancies serving this precision equipment segment.
United States
Large pork operators in the US Midwest now source mills through capital leases while contracting maintenance separately to regional specialists, unbundling procurement from service. FDA feed safety rules under FSMA mandate hazard analysis plans for equipment contacting medicated premixes. Iowa and Illinois concentrate the largest installed base of grinding and pelleting assets.
Norway
Salmon producers are accelerating extruder deployments to process plant-based proteins as fishmeal alternatives, driving thermal processing equipment demand. Norwegian regulators enforce strict effluent and energy efficiency standards on coastal processing facilities. Bergen and Trondheim harbor clusters of aquafeed engineering specialists integrating inline near-infrared spectroscopy systems.
Animal Feed Processing Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Swiss and Austrian engineering groups occupy premium positions in thermal processing and pelletizing systems, while Chinese fabricators dominate volume supply through integrated steel-forging and assembly operations. Three archetypes define the field: integrated engineering conglomerates with captive R&D campuses, regional fabrication shops with verticalized component production, and specialized technology licensors. Competitive moves concentrate on geographic expansion into protein export markets and portfolio diversification toward aquafeed applications.
Among European-based engineering groups, Bühler Holding AG and Andritz AG occupy positions exemplifying technology-forward archetypes, while Jiangsu Muyang Group Co., Ltd. anchors the scale-driven tier with Chinese domestic manufacturing depth. These three represent the structural divergence between premium thermal processing specialization and high-volume mill supply.
| Leading Market Players |
|---|
| Jiangsu Muyang Group Co., Ltd. |
| Wenger (Marel) |
| Bühler Holding AG |
| FAMSUN |
| ZhengChang Group |
| Andritz AG |
| Amandus Kahl GmbH & Co. KG |
| Double Crane Machinery |
| CPM Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
Plant protein substitution for fishmeal in aquafeed extrusion is redrawing raw material sourcing maps from marine catch zones to oilseed processing hubs, compressing thermal equipment margins in traditional fishing economies while opening premium pricing corridors for starch gelatinization specialists in soybean belt regions.
Pricing Analysis
Configured-to-order pricing for extruders with inline near-infrared spectroscopy commands a forty to sixty percent premium over standard pelleting lines without real-time moisture verification. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation tier and traceability certification grade, with EU F-Gas Regulation compliance adding certification premiums to thermal processing equipment. Cost compression in standard mechanical processing lines is intensifying because Chinese fabricators are scaling vertical integration into alloy forging and assembly. Livestock cooperatives and mid-sized feed mills exhibit highest price sensitivity, while integrated salmon producers in Norway and Chile demonstrate lowest sensitivity due to pellet durability index requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg are extending lead times for precision extruder components sourced from Swiss and Austrian engineering groups. Manufacturing concentration centers on China, Germany, and Switzerland, with Jiangsu province hosting integrated steel-forging operations and the Alpine corridor anchoring thermal processing R&D. Stainless steel and specialty alloy feedstock draws from Indonesian nickel processing and German precision metallurgy. Single-source vulnerability concentrates in extruder die design expertise held by retiring cohorts at original equipment manufacturers. Distribution runs through regional fabrication shops serving captive feed facilities and direct sales to integrated protein companies unbundling procurement from service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital batch-tracking mandates under the EU Farm to Fork Strategy are forcing a capital equipment refresh cycle that favors automation-forward suppliers over legacy mechanical fabricators.
For Market Incumbents: Fortify thermal processing technology leadership through captive R&D investment in extruder die design and starch gelatinization kinetics, addressing the expertise scarcity threat from retiring engineering cohorts. Deepen backward integration into precision alloy forging to offset stainless steel price volatility and defend margin position against Chinese volume competitors. For New Entrants and Emerging Players: CE marking fast-track for F-Gas-compliant thermal processing equipment opens white-space access to European aquafeed manufacturers facing extended certification timelines. Target Brazil's São Paulo state cattle and poultry sector, where export certification requirements are driving automated feed milling capacity expansion with limited local precision equipment supply. Lead with sensor-software convergence offerings that enable real-time formulation adjustment as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors automation and traceability specialists over pure mechanical fabricators. Over a five-to-ten year viability window, acquisition targets should display vertical integration into alloy contact surfaces and digital control system capabilities. Monitor divergence in carbon-accounting rules for Scope three emissions as the signal to watch for equipment procurement criteria shifts across integrated protein supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Software Integration Investment | Inline near-infrared spectroscopy embedded in mixer discharge chutes enables real-time moisture verification for aquafeed producers. |
| Energy-Efficient Thermal Retrofit Program | Waste-heat recovery system installations align with China's dual carbon goals and SAMR heavy-metal migration standards. |
| Digital Batch-Tracking Platform Development | Automated quality control infrastructure addresses EU Farm to Fork Strategy traceability mandates for European processors. |
| Regional Service Network Expansion | Maintenance specialization contracts capture value from US Midwest pork operators unbundling procurement from long-term service agreements. |
| Natural Refrigerant Thermal Exchange Redesign | Pellet cooler line modifications satisfy EU F-Gas Regulation phase-down requirements for hydrofluorocarbon refrigerants. |
Methodological Framework
Operator-level perspectives from plant engineers at integrated pork facilities, maintenance directors at commercial poultry operations, procurement leads at aquafeed manufacturers, and aftermarket service heads at regional fabrication shops anchored the qualitative base. Secondary validation drew from customs and trade data on alloy and equipment shipments, SEC filings of publicly traded agribusinesses, ANVISA feed safety protocol documentation, and SAMR GB standard enforcement records. Bottom-up equipment deployment tallies across China's Yangtze River Delta, Brazil's São Paulo state, and Norway's coastal processing corridors were triangulated against top-down protein production forecasts.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios for EU F-Gas Regulation compliance timelines and Chinese dual carbon goal implementation intensity. The analytical framework modeled volume and value outputs across product type segmentation, end user categories, technology tiers, and application processes throughout the projection horizon. CAGRs were derived from equipment replacement cycle compression rates, aquaculture protein substitution velocity, and captive manufacturing consolidation patterns in key regional clusters.
Underlying assumptions cover sustained export certification demand from EU and Middle Eastern protein buyers, with deviation risk concentrated in alloy input cost volatility and thermal process engineering talent scarcity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Maize Milling Machine Market