
 Cassava Processing Market | 2026-2036
Cassava Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Cassava Processing Market Intelligence
Mechanical vapor recompression drying is reshaping energy economics in cassava starch extraction, cutting thermal costs by half in large-scale facilities. Thai Wah Public Company Limited leverages backward integration into captive tapioca plantations across Thailand's Nakhon Ratchasima province. Cargill Incorporated anchors its Southeast Asian starch operations through port-advantaged processing hubs in Chon Buri. Ingredion Incorporated differentiates via modified starch R&D pipelines targeting beverage texturization and clean-label reformulations.
Cassava processing transforms the starchy tuberous root of Manihot esculenta into food-grade flours, native and modified starches, chips, and pearl tapioca through washing, grating, fermenting, pressing, and drying stages; the root's high amylopectin content (70-80% of total starch) delivers exceptional thickening stability and freeze-thaw tolerance for industrial food systems. Flour and starch product lines dominate value capture due to their indispensability in gluten-free baking and adhesive manufacturing, while chips and tapioca pearls serve mature, price-sensitive snack and dessert channels with thinner margin pools. The beverages application segment is expanding fastest as cassava-derived maltodextrins and glucose syrups displace corn-based alternatives in craft brewing and functional drink formulations.
Thailand's Ministry of Industry enforces Good Manufacturing Practice standards for cassava starch exports through the Thai Industrial Standards Institute, while the FDA monitors mycotoxin and cyanogenic glycoside limits in processed cassava entering food channels. The EU Green Deal's deforestation-free supply chain due diligence rules are reshaping export compliance burdens for processors sourcing from converted pasturelands. Stakeholders must monitor how carbon border adjustment mechanisms and evolving clean-label certification schemes reposition sourcing strategies across Southeast Asian and African supply basins.
Market Dynamics
Mechanical vapor recompression drying is compressing thermal cost structures across Southeast Asian starch complexes, forcing legacy fuel-fired facilities toward equipment retrofits or market exit.
Growth Catalysts
- Clean-label starch substitution:Food manufacturers in craft brewing and functional beverages are reformulating away from corn-derived inputs toward cassava-based maltodextrins and glucose syrups.
- EU Green Deal due diligence:Deforestation-free supply chain mandates are creating compliance premiums for processors with traceable sourcing from established plantations.
- Thailand's Eastern Economic Corridor clustering:Integrated starch-to-derivatives complexes co-locating near Nakhon Ratchasima raw material bases and Laem Chabang port infrastructure capture logistics arbitrage.
Market Restraints
- Fresh root perishability:Cassava roots deteriorate within 48-72 hours of harvest, binding processing capacity to radial catchment zones and limiting facility scale economies.
- Nigerian mycotoxin thresholds:The national food safety regulator's tightening export standards force processors to upgrade fermentation and drying protocols, elevating capital intensity for smaller operators.
- Corn starch price volatility:Feedstock competition from maize derivatives in adhesive and textile sizing applications constrains pricing power during harvest gluts.
Strategic Opportunities
- Vietnamese processing underpenetration:Domestic starch extraction capacity lags root production growth in Dak Lak and Tay Nguyen provinces, opening greenfield investment corridors.
- Biodegradable packaging films:Cassava-derived thermoplastic starch is virtualizing petroleum-based flexible packaging in European fresh produce logistics.
- Thai Industrial Standards Institute certification:Good Manufacturing Practice export standards create brand differentiation for compliant processors accessing EU and Japanese food channels.
Industry Challenges
- Cyanogenic glycoside management:Processors must maintain precise fermentation pH and duration controls to meet FDA and EFSA residual cyanide limits, requiring skilled laboratory staffing.
- Modified starch R&D talent scarcity:Formulation chemistry expertise for beverage texturization and freeze-thaw stability applications concentrates in Bangkok and Singapore, constraining provincial facility technical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cassava Processing Market |
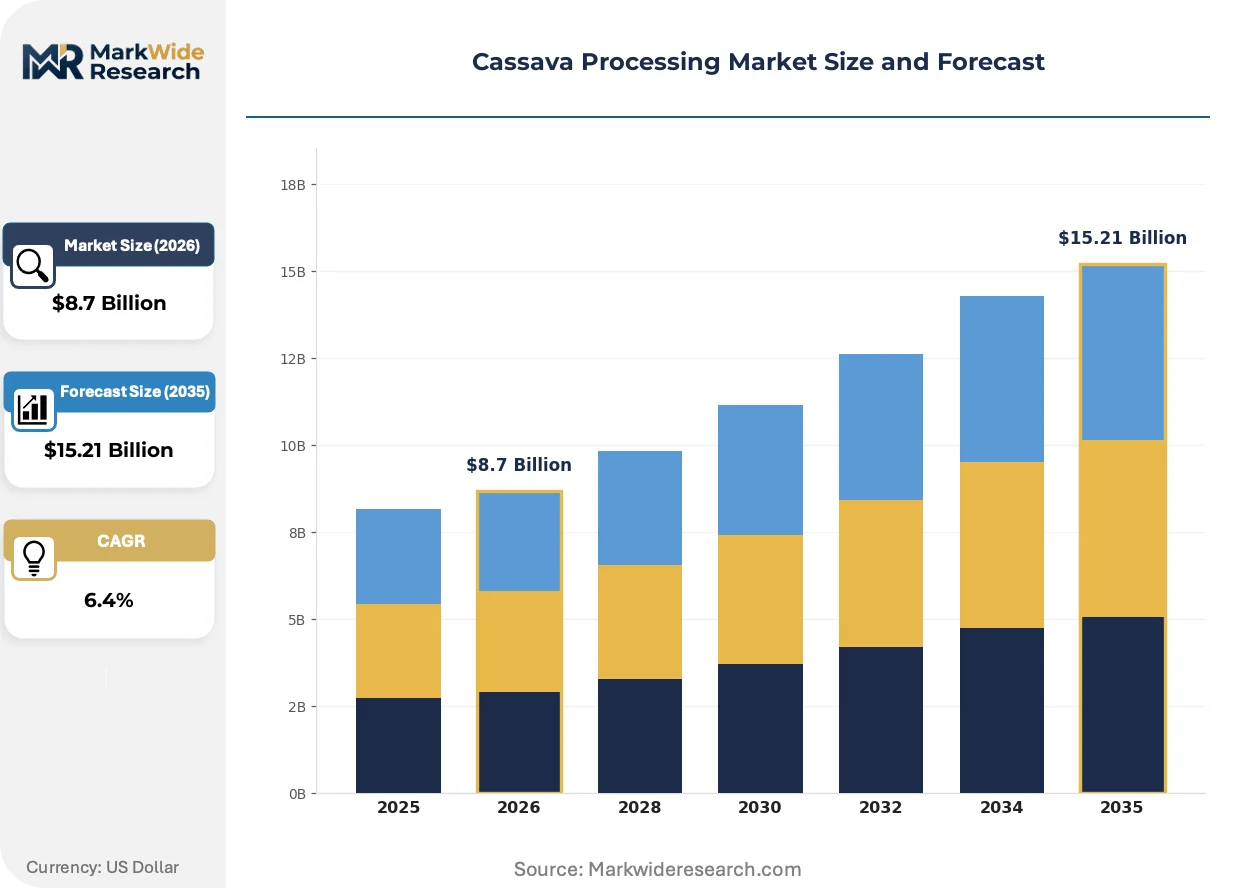
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Starch, Chips, Tapioca End User: Bakeries, Snacks Manufacturers, Breweries, Food Service Distribution Channel: Retail, Wholesale, Online, Direct Sales Application: Beverages, Snacks, Culinary, Animal Feed |
| Companies Covered | Thai Wah Public Company Limited, Archer Daniels Midland Company, Cargill Incorporated, Avebe U.A., Emsland Group, Ingredion Incorporated, Tereos Group, Psaltry International Limited, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cassava Processing Market Strategic Shifts & Innovations
Digital process control and regulatory traceability requirements are converging to reshape capital deployment patterns across cassava processing infrastructure.
Mechanical vapor recompression drying systems are virtualizing conventional steam-heated rotary dryers in Thai Wah and Cargill facilities. Large-scale complexes in Chon Buri and Nakhon Ratchasima provinces are adopting these heat pump configurations to halve thermal energy costs. The technology is virtualizing fuel procurement exposure and compressing operating margin variance for volume processors.
EU Green Deal deforestation-free due diligence rules are mandating geolocation verification and chain-of-custody documentation for imported starch derivatives. European food manufacturers are now requiring satellite-mapped sourcing polygons from Thai and Nigerian suppliers. The regulation is concentrating procurement relationships on processors with captive plantation control and third-party certification.
Clean-label reformulation mandates from beverage multinationals are rotating procurement specifications toward native and minimally modified starches. Craft brewers and functional drink formulators in North American and European markets are specifying cassava-derived inputs over chemically modified alternatives. This preference shift is most visible in contract manufacturing relationships where ingredient storytelling supports retail price positioning.
Cassava Processing Market Segmentation
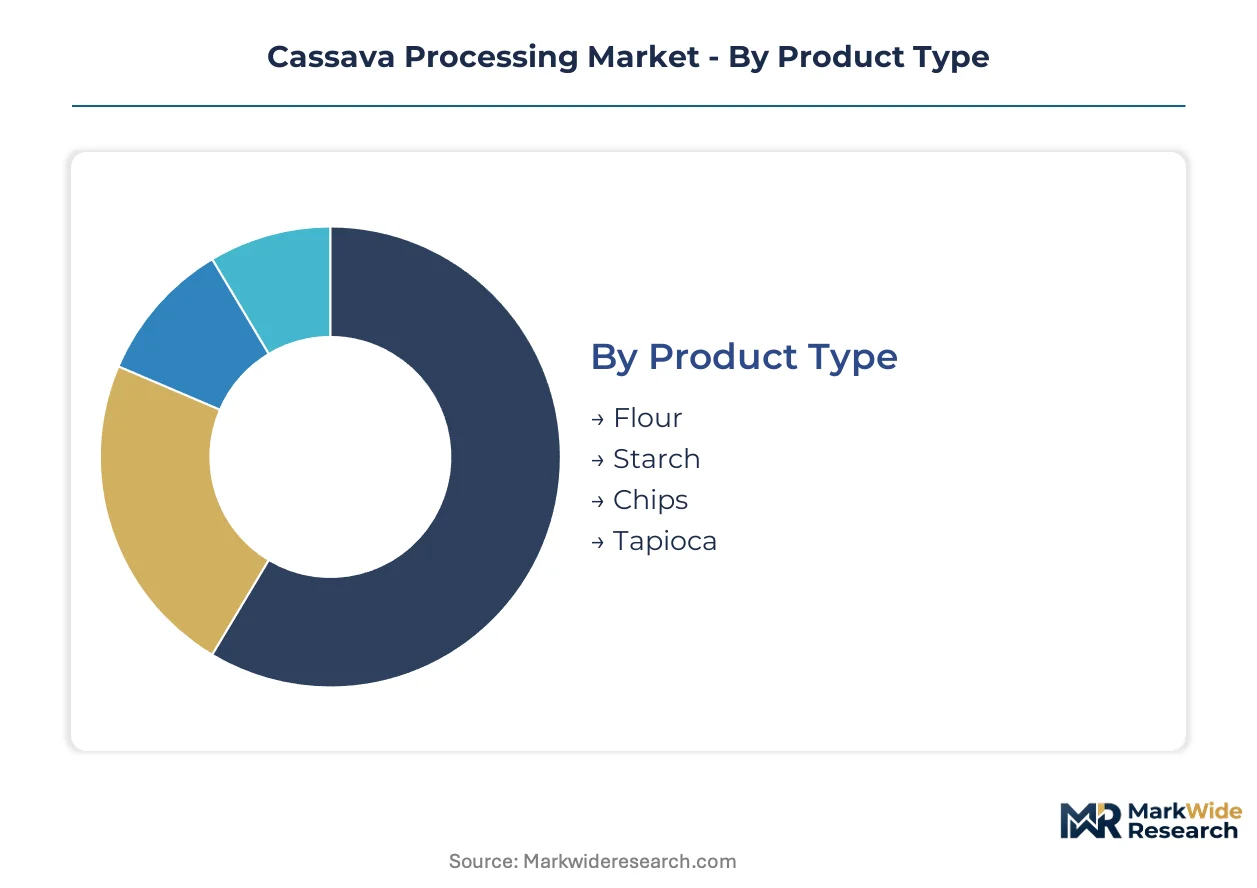
Cassava processing generates divergent margin profiles across product categories, with starch derivatives commanding premium pricing in industrial channels while commodity chips serve volume-driven snack markets. End-use fragmentation demands distinct technical specifications, from beverage-grade maltodextrin purity to food service pearl consistency standards.
Product Type:
Use-case spectrum spans industrial ingredient systems to direct-consumption formats, with amylopectin content and processing intensity determining value capture tiers.
- Starch:Native and modified starches leverage 70-80% amylopectin content for exceptional thickening stability and freeze-thaw tolerance. Demand concentrates in Thai starch-to-derivatives complexes supplying beverage texturization and adhesive manufacturing, driven by clean-label substitution away from corn-derived inputs.
- Flour:Gluten-free baking applications require specific particle size distributions and residual cyanide compliance. Nigerian and Thai processors target EU and North American export channels, constrained by tightening mycotoxin thresholds that elevate quality control capital requirements.
- Chips:Sun-dried and fried formats serve mature snack markets with thinner margin pools.
- Tapioca:Pearl and granular forms supply dessert and beverage topping channels.
Established volume favors Starch; emerging adoption favors Flour.
End User:
Customer sophistication varies from commodity procurement in snack manufacturing to specification-driven formulation partnerships in brewing.
- Breweries:Craft and functional beverage producers specify cassava-derived maltodextrins and glucose syrups for clean-label storytelling and fermentation performance. North American and European contract manufacturers drive procurement, rotating specifications toward native starches over chemically modified alternatives.
- Bakeries:Gluten-free specialists and industrial bakers require consistent flour hydration properties and absence of off-flavors. Thailand's Eastern Economic Corridor clusters supply this segment through integrated processing complexes with captive plantation control.
- Snacks Manufacturers:Volume buyers of chips and extruded products prioritize cost position over technical differentiation.
- Food Service:Pearl tapioca demand concentrates in Southeast Asian bubble tea and dessert chains.
Margin concentration sits with Breweries; volume scale sits with Snacks Manufacturers.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and regulatory documentation needs.
- Direct Sales:Industrial starch buyers in adhesive, textile, and beverage manufacturing require technical formulation support and batch-specific certification documentation. Thai Wah and Cargill anchor relationships through dedicated account management for large-volume processors.
- Wholesale:Regional distributors aggregate fragmented food service and bakery demand across Southeast Asian urban centers, capturing logistics arbitrage through warehouse consolidation.
- Retail:Packaged flour and pearl tapioca for household consumers.
- Online:Emerging channel for specialty gluten-free ingredients and direct-to-bakery procurement.
Relationship intensity defines Direct Sales; geographic reach defines Wholesale.
Application:
Functional requirements range from beverage solubility and clarity to animal feed energy density specifications.
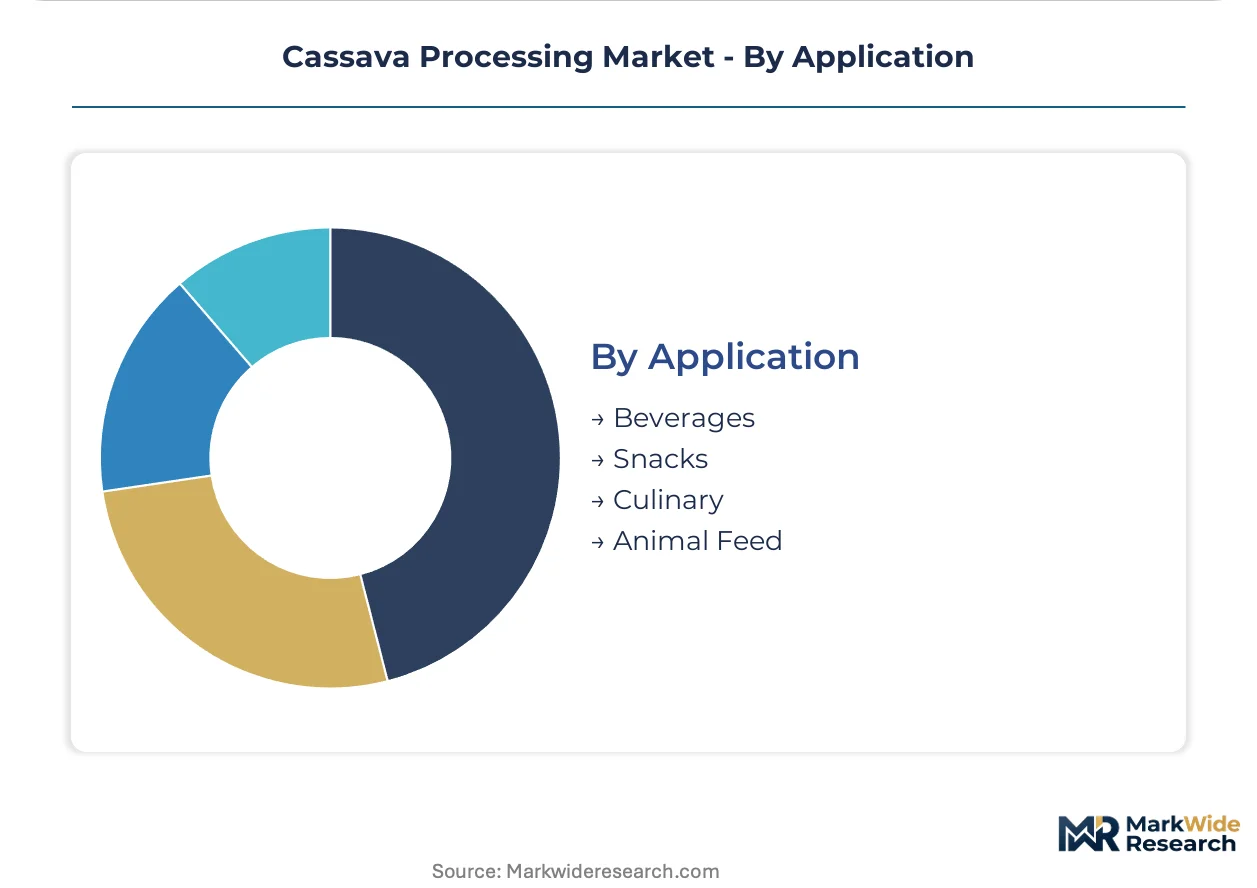
- Beverages:Maltodextrin and glucose syrup applications displace corn-based alternatives in craft brewing and functional drink formulations. Clean-label mandates from multinational beverage manufacturers accelerate specification shifts toward cassava-derived inputs with traceable sourcing.
- Snacks:Chips and extruded products serve mature, price-sensitive markets with established consumption patterns across Southeast Asia and Africa.
- Culinary:Thickening and binding applications in processed foods.
- Animal Feed:Dried chips and residues supply ruminant energy supplementation.
Beverages climb the fastest; Snacks anchor volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented starch complexes in Thailand and Nigeria drive global trade flows, while import demand concentrates in European food manufacturing and North American beverage formulation. Regional regulatory divergence around mycotoxin limits and deforestation traceability is fragmenting compliance architectures.
Thailand
Integrated starch-to-derivatives complexes in Chon Buri and Nakhon Ratchasima supply clean-label maltodextrins to craft brewers and functional beverage manufacturers. The Thai Industrial Standards Institute enforces Good Manufacturing Practice certification for export-bound starch. Laem Chabang port infrastructure enables Thai Wah and Cargill facilities to capture logistics arbitrage on deep-water shipping lanes.
Nigeria
Domestic flour and chip processing serves West African food service channels while export-oriented operators target EU gluten-free baking markets. The national food safety regulator tightened mycotoxin thresholds for processed cassava exports, forcing fermentation protocol upgrades. Ogun State processing clusters near Lagos port infrastructure concentrate capacity for international shipment.
Vietnam
Root production growth in Dak Lak and Tay Nguyen provinces outpaces domestic starch extraction capacity, creating greenfield investment corridors. Provincial industrial development incentives support processing facility construction. Central Highlands logistics networks remain underdeveloped relative to Thai benchmarks, constraining scale economies.
Netherlands
Avebe and Emsland Group facilities in the northern provinces import raw starch for modification and re-export to European food manufacturers. EU Green Deal deforestation-free due diligence rules mandate geolocation verification for cassava derivatives entering Dutch ports. Rotterdam infrastructure anchors continental distribution for modified starch applications.
United States
Ingredion and Archer Daniels Midland operate modification and formulation facilities serving North American beverage and bakery channels. FDA monitoring of residual cyanide limits in imported cassava ingredients shapes procurement specifications. Midwest corn starch competition constrains pricing power during harvest periods.
Cassava Processing Market Key Industry Players
On the supply side, the industry is consolidating around integrated plantation-processor complexes with captive raw material control and port-advantaged logistics. Thai and Nigerian operators dominate upstream extraction, while European and North American players concentrate on modification and formulation. Three archetypes define competitive positioning: plantation-integrated Asian processors, modification-specialist European cooperatives, and global ingredient conglomerates with multi-feedstock flexibility. Dominant competitive moves include backward integration into captive tapioca plantations and strategic partnerships with beverage multinationals for clean-label specification development.
Within the plantation-integrated tier, Thai Wah Public Company Limited exemplifies upstream control strategies through Nakhon Ratchasima province operations. Cargill Incorporated and Ingredion Incorporated occupy positions as global ingredient conglomerates with multi-regional processing footprints and beverage formulation partnerships. These three anchors represent divergent approaches to managing perishable root supply chains and clean-label certification requirements.
| Leading Market Players |
|---|
| Thai Wah Public Company Limited |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Avebe U.A. |
| Emsland Group |
| Ingredion Incorporated |
| Tereos Group |
| Psaltry International Limited |
| Roquette Frères |
| Others |
Cost & Logistics Intelligence
Thailand's Eastern Economic Corridor clustering of integrated starch-to-derivatives complexes concentrates upstream supply control, directing margin capture toward beverage texturization and clean-label maltodextrin tiers downstream. Nigerian export-oriented operators face divergent pricing pressure from mycotoxin compliance investments that elevate quality-control capital requirements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture beverage-grade maltodextrin purity and FDA/EFSA residual cyanide compliance, while economy tiers serve animal feed chip markets with thinner margin pools. Pricing pressure stems from corn starch price volatility during harvest gluts that constrains cassava derivative pricing power. Snacks manufacturers exhibit highest price sensitivity; craft brewers and functional beverage formulators show lowest sensitivity due to clean-label storytelling requirements.
Supply Chain Analysis
EU Green Deal deforestation-free due diligence rules restrict supply chain flows through geolocation verification mandates for imported starch derivatives. Raw material sourcing concentrates in Thailand, Nigeria, and Vietnam, with processing capacity tethered to radial catchment zones due to fresh root perishability within 48-72 hours. Supply chain risk centers on single-source vulnerability from plantation-dependent processors lacking third-party certification. Distribution runs through Laem Chabang and Lagos port infrastructure for export-bound derivatives, with Rotterdam anchoring European modification and re-export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical vapor recompression drying technology is disrupting energy economics across Southeast Asian starch complexes, compressing thermal cost structures and forcing legacy facility exits. This technological inflection concentrates competitive advantage on processors with capital deployment capacity for equipment retrofits.
For Market Incumbents: Harden backward integration into captive tapioca plantations across Nakhon Ratchasima and Dak Lak provinces to secure perishable root supply chains against radial catchment constraints. Deepen modified starch R&D partnerships with beverage multinationals for clean-label specification development, defending position against corn-based substitute competition during harvest gluts. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese starch extraction capacity gaps across Tay Nguyen province, where root production growth outpaces domestic processing infrastructure. Target biodegradable packaging film applications in European fresh produce logistics as a white-space channel with traceable sourcing requirements that favor greenfield entrants over legacy operators lacking plantation control. For Investors and Strategic Acquirers: Capital is best deployed toward plantation-integrated processors with Thai Industrial Standards Institute certification and satellite-mapped sourcing polygons that satisfy EU Green Deal due diligence. Watch for inflection signals in carbon border adjustment mechanism implementation timelines that would reposition sourcing strategies across Southeast Asian supply basins and force updated valuation models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Plantations | Thai Wah's Nakhon Ratchasima operations demonstrate supply security against 48-72 hour root perishability constraints. |
| Mechanical Vapor Recompression Retrofit | Cargill's Chon Buri facilities halve thermal energy costs, compressing operating margin variance for volume processors. |
| Clean-Label Specification Partnership | Ingredion's beverage texturization R&D pipelines capture craft brewing procurement rotating from corn-derived inputs. |
| EU Deforestation-Free Certification | Compliant processors access procurement relationships with European food manufacturers mandating geolocation verification. |
| Vietnamese Greenfield Capacity Buildout | Dak Lak and Tay Nguyen provinces offer investment corridors where domestic extraction lags root production growth. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with starch processing plant managers, beverage formulation R&D directors, and EU food manufacturer procurement leads; and secondary validation through Thai Industrial Standards Institute export certifications, Nigeria's national food safety regulator mycotoxin threshold documentation, and customs trade flow records. Bottom-up triangulation across facility-level capacity assessments and top-down demand modeling across beverage, bakery, and snack manufacturing channels anchored volume and value estimates.
Forecast inputs span product type segmentation across starch, flour, chips, and pearl derivatives; end-user channels from industrial OEMs to food service; and application tiers spanning beverage texturization, gluten-free baking, and biodegradable packaging films. CAGRs were derived through regression analysis of historical export volumes and projected clean-label substitution rates across craft brewing and functional drink formulations. The modeling period incorporates mechanical vapor recompression adoption curves and EU Green Deal compliance timeline assumptions.
Stress conditions across corn starch price volatility bands, Nigerian mycotoxin enforcement intensity, and Thai energy cost trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label procurement rotation and plantation-integrated supply chain consolidation. Material shifts in carbon border adjustment mechanism scope or FDA residual cyanide limit revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Asia-Pacific Agricultural Shredder Machine Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market