
 Global Dry Milling Market | 2026-2036
Global Dry Milling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Milling Market Analysis
Multi-source grain procurement is consolidating across the Global Dry Milling Market as millers seek supply resilience amid climate volatility. Cargill leverages its origination network across the US Corn Belt and Black Sea region to secure feedstock flexibility. Archer Daniels Midland Company anchors North American ethanol-adjacent milling with integrated corn processing infrastructure. Bunge Limited competes through South American oilseed and grain handling assets that feed export milling streams.
Dry milling mechanically reduces cereal grains into flours, grits, and meals without liquid processing, typically achieving particle sizes between 150 and 850 microns depending on sifter configuration and roll corrugation settings. The process preserves native starch structures and protein functionality for downstream food, feed, and industrial fermentation applications. Corn flour dominates product type volumes due to ethanol co-product economics and snack manufacturing pull, while rice flour is gaining structural momentum from gluten-free formulation requirements in baking and cereals. Wheat flour retains mature margin pools in developed markets but faces volume pressure from carbohydrate reduction trends in retail and foodservice channels.
The FDA oversees mycotoxin thresholds and food safety modernization compliance for US milled grain exports, while the EU Green Deal's Farm-to-Fork strategy tightens pesticide residue limits and traceability requirements for European milling operations. China's SAMR enforces GB standards for imported flour specifications that directly shape export-oriented miller quality investments. Stakeholders must monitor how diverging sustainability certification schemes across these jurisdictions reshape procurement premiums and market access conditions.
Market Dynamics
Climate volatility is compressing origination windows across major grain belts, forcing millers to rebuild procurement networks around multi-origin supply resilience rather than single-source efficiency.
Growth Catalysts
- EU Green Deal Farm-to-Fork mandates:European millers are retrofitting facilities to meet tightened pesticide residue limits and traceability requirements, creating certified premium product tiers that command sourcing premiums from export buyers.
- Plant-forward menu development:Foodservice operators in the United States and United Kingdom are expanding milled corn and wheat base procurement for meat-alternative and clean-label formulations, pulling volume through specialty flour channels.
- South American export capacity expansion:Brazil and Argentina are concentrating new milling investments to serve Asian buyers, redirecting trade flows away from traditional North Atlantic routes.
Market Restraints
- Input cost volatility:Natural gas and electricity price swings directly compress margins for energy-intensive tempering and drying stages, particularly affecting European operations exposed to F-Gas Regulation compliance costs.
- Supply concentration risk:Black Sea grain origination remains vulnerable to geopolitical disruption, forcing millers to maintain redundant inventory positions that tie up working capital.
- Technical limitation:Conventional roller mills struggle to achieve sub-150-micron particle sizes for specialized fermentation feedstocks without excessive starch damage, limiting addressable applications in precision fermentation.
Strategic Opportunities
- Underpenetrated geography:Vietnam and Indonesia present white space for gluten-free rice flour penetration as bakery and noodle manufacturers reformulate for export markets and domestic health positioning.
- Technology convergence:Near-infrared spectroscopy integrated with automated sifter control is enabling real-time protein and moisture adjustment, opening contract milling services for small-batch specialty grain processors.
- Regulatory tailwind:China's SAMR enforcement of GB standards for imported flour specifications is accelerating quality investments among export-oriented millers, creating certified-supplier moats against uncertified competitors.
Industry Challenges
- Certification timeline compression:EU Green Deal sustainability certification requirements are forcing millers to requalify entire supplier bases within compressed windows, straining procurement and quality assurance staffing.
- Capex intensity for emissions compliance:Dust collection and volatile organic compound control upgrades required by EPA and MEE standards demand capital deployment that competes with capacity expansion budgets.
- Integration complexity:Legacy mill automation systems resist seamless integration with blockchain traceability platforms demanded by EU and Chinese import protocols, requiring middleware investments that delay compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Milling Market |
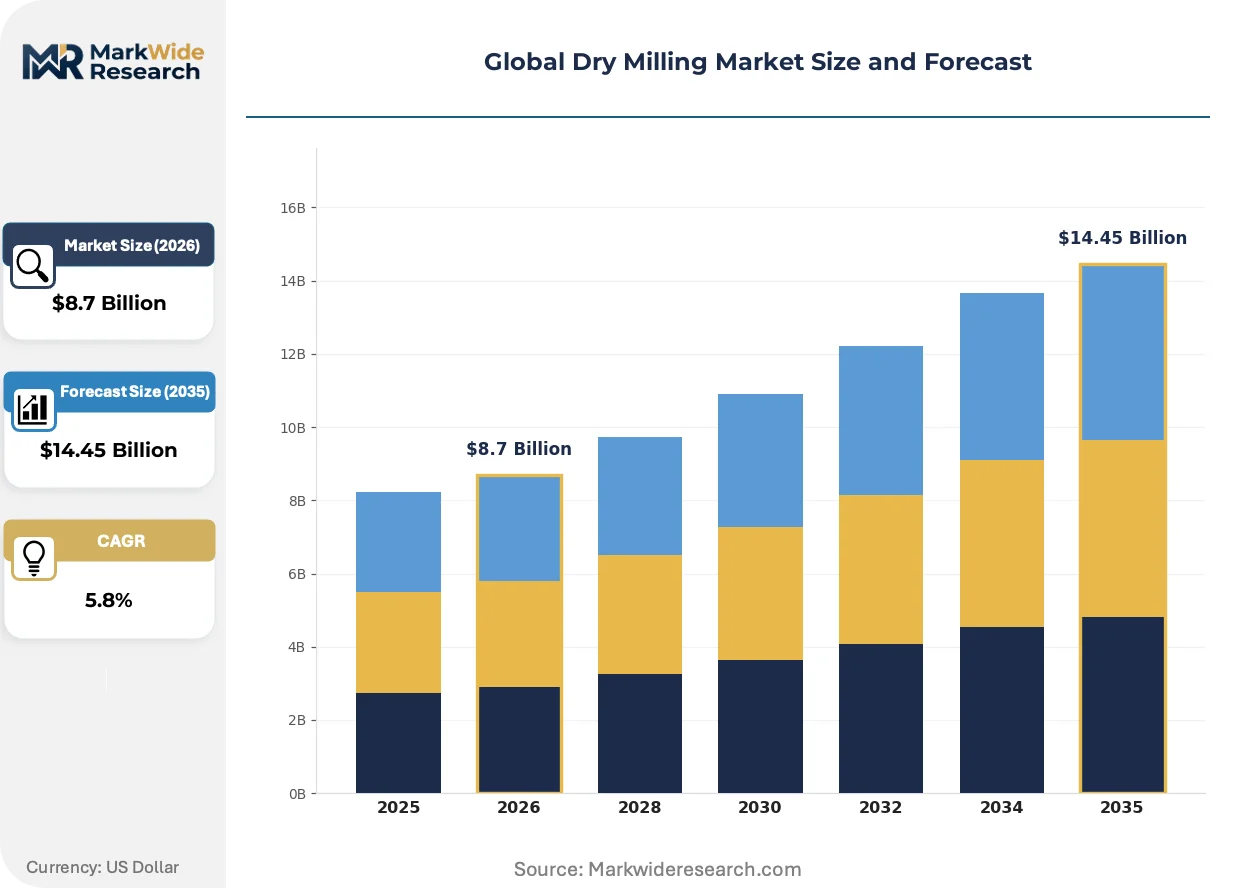
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Flour, Wheat Flour, Rice Flour, Barley Flour Application: Baking, Snacks, Cereals, Beverages End User: Food Industry, Animal Feed Manufacturers, Retail, Foodservice Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Cargill, Archer Daniels Midland Company, Bunge Limited, SunOpta, Inc., Grain Millers Inc., Semo Milling, LLC, LifeLine Foods, LLC, Green Plains Inc., Valero Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Milling Market Emerging Trajectories
Digital grain quality sensing and decentralized processing architectures are displacing centralized mill economics, while regulatory fragmentation across FDA, EFSA, and SAMR jurisdictions is forcing product-line stratification.
Optical sorting combined with artificial intelligence-driven defect detection is decentralizing quality control from centralized laboratory testing to inline production monitoring. Snack manufacturers in Mexico and Thailand are adopting these systems at accelerating rates to reduce mycotoxin-related rejections. The technology is decentralizing risk management responsibilities from third-party certifiers to mill operators themselves, compressing batch-release timelines from days to hours.
REACH authorization requirements for food-contact processing aids are restricting chemical additive options for European millers, forcing reformulation toward mechanical and enzymatic alternatives. The regulation is diverging EU product specifications from FDA-registered US equivalents, complicating dual-market production strategies. Wheat flour exporters to the European Union are responding by segregating production lines and absorbing duplicate certification costs.
Direct sourcing contracts between foodservice chains and origin-adjacent millers are bypassing traditional grain merchant intermediaries, compressing margin capture for integrated traders. Quick-service restaurant procurement teams in Canada and Australia are negotiating volume commitments directly with Argentine and US Corn Belt millers, securing price stability through growing-season hedging. This disintermediation is most visible in corn flour for tortilla and chip manufacturing, where brand-specific particle size and moisture specifications resist commodity substitution.
Global Dry Milling Market Segmentation
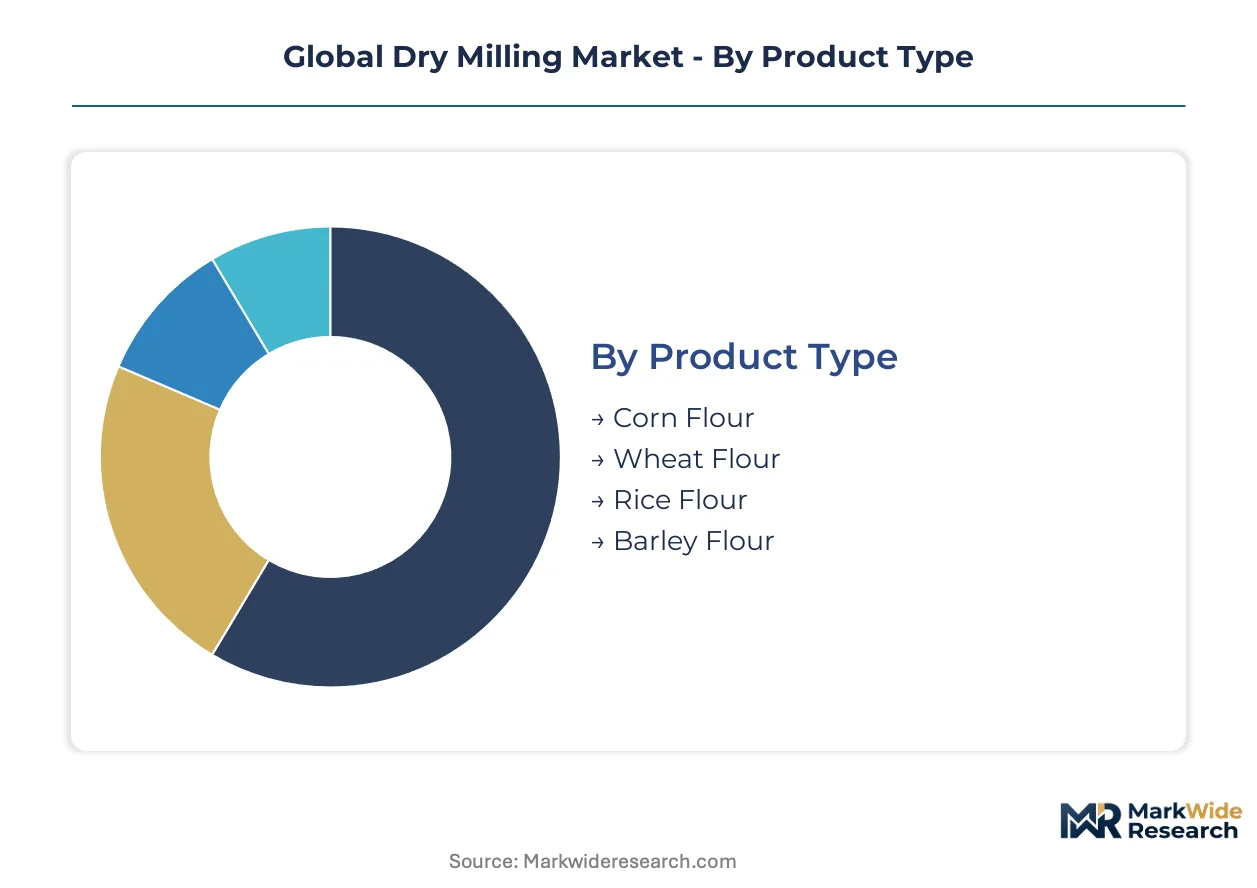
Dry milling output specifications diverge sharply across downstream applications, forcing equipment and process configurations that resist easy reconfiguration. Grain type, particle size distribution, and moisture targets create distinct manufacturing silos with limited interchangeability between product categories.
Product Type:
Customization intensity varies from commodity-grade bulk outputs to precision-milled specialty grades with tight particle distribution tolerances.
- Corn Flour:The dominant volume category spans coarse grits through fine masa flours with particle sizes from 300 to 850 microns. Tortilla and chip manufacturers in Mexico and the United States specify exact moisture and fat absorption profiles that command dedicated milling lines.
- Wheat Flour:Mature demand centers on bread and pastry applications with protein content stratification driving hard versus soft wheat segregation. European millers face EU Green Deal pesticide residue limits that force certified premium tiers with traceable origination.
- Rice Flour:Gluten-free bakery and noodle reformulation in Vietnam and Indonesia is pulling investment in dedicated rice milling capacity with sub-200-micron capabilities.
- Barley Flour:Malt house procurement for brewing and limited specialty baking applications concentrates in Australia and Canada with strict germination and enzyme specifications.
Most installed capacity flows through Corn Flour. Expansion is steepest in Rice Flour.
Application:
Volume concentration versus margin capture splits this category between mass-market throughput and premium formulation requirements.
- Baking:Industrial bread and pastry production consumes standardized patent flours with consistent gluten development and fermentation performance. Chinese and Brazilian bakery chains specify protein ranges that force millers to segregate wheat origination by growing region.
- Snacks:Extruded and sheeted products demand precise starch damage levels and granulation curves that affect expansion and texture. Mexican tortilla chip manufacturers enforce corn flour specifications that reject commodity substitution.
- Cereals:Breakfast and hot cereal applications blend multiple grain streams with vitamin and mineral fortification requirements governed by FDA and FSSAI standards.
- Beverages:Brewing adjuncts and malt-based drinks utilize barley and wheat milling outputs with enzyme activity and fermentable sugar specifications.
Snacks command the tightest specification premiums. Cereals offer the most stable contract volumes.
End User:
Procurement scale and quality assurance intensity create four distinct customer archetypes with diverging supplier relationship models.
- Food Industry:Large manufacturers negotiate multi-year supply agreements with embedded price hedging and dedicated production runs. Cargill and Bunge leverage origination networks to secure preferred supplier status with North American and European food manufacturers.
- Animal Feed Manufacturers:Co-product streams from ethanol-adjacent corn milling supply protein and fiber fractions with variable composition that requires formulation flexibility.
- Retail:Packaged flour brands compete on shelf stability and convenience positioning with private label penetration compressing branded margin pools.
- Foodservice:Quick-service chains in Canada and Australia are negotiating direct sourcing contracts with Argentine and US Corn Belt millers, bypassing traditional grain merchant intermediaries.
Food Industry accounts for the largest volume throughput. Foodservice is gaining share fastest through direct contracting.
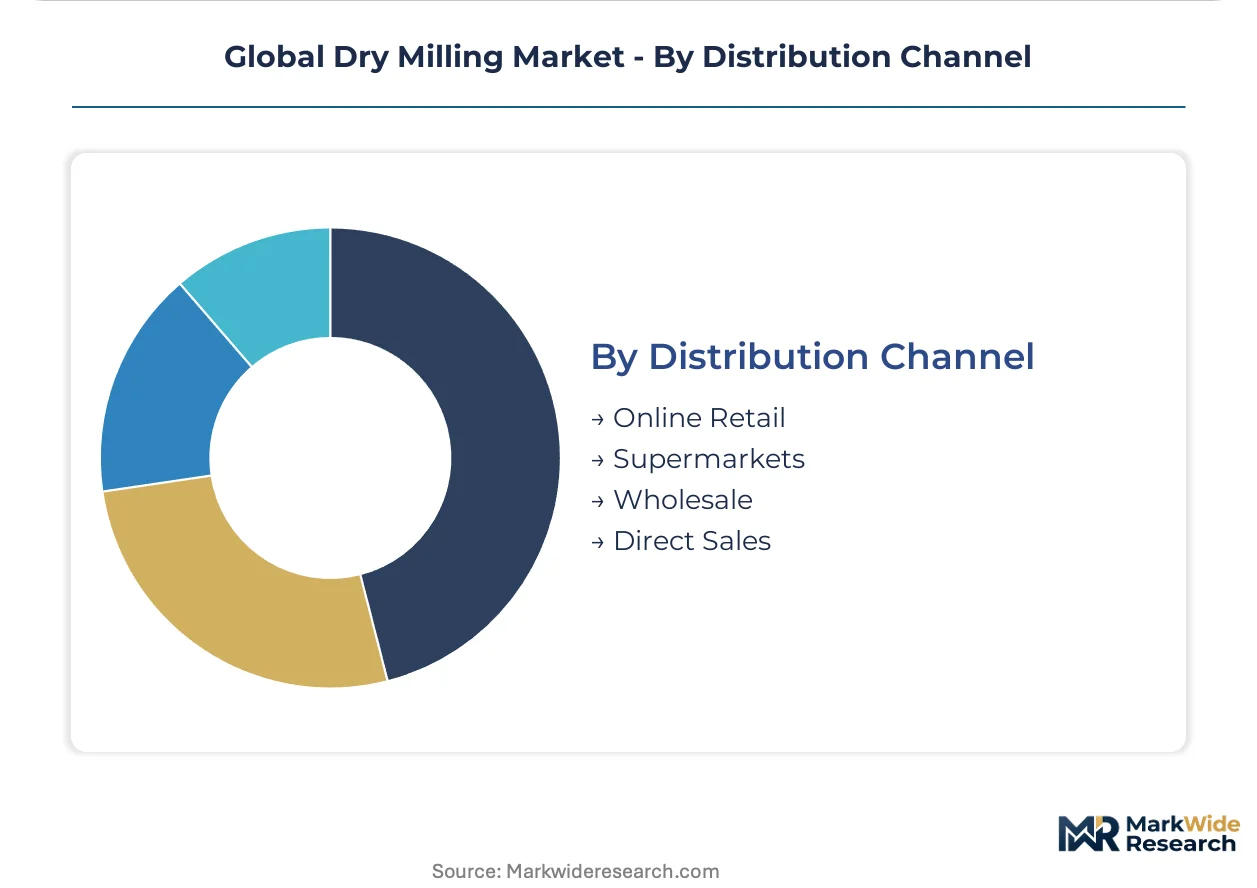
Distribution Channel:
Logistics infrastructure and customer touchpoint requirements shape channel economics and working capital intensity.
- Online Retail:Specialty and organic flour segments exploit direct-to-consumer fulfillment for gluten-free and heritage grain varieties with premium positioning.
- Supermarkets:Mass-market flour and meal distribution depends on shelf space negotiations and promotional calendar alignment with retail category managers.
- Wholesale:Foodservice and small manufacturer supply flows through regional distributors with inventory holding and credit extension functions.
- Direct Sales:Large industrial buyers contract directly with millers for silo-to-silo transfer with quality certificates and origin documentation.
Wholesale handles the greatest tonnage. Direct Sales is expanding most quickly as foodservice chains consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Corn Belt anchors global dry milling capacity, with integrated ethanol-adjacent processors dominating corn flour and co-product streams. Brazil and Argentina are expanding export-oriented milling investments to serve Asian buyers, while European millers retrofit facilities under EU Green Deal mandates. Southeast Asian markets present white space for rice flour penetration as gluten-free formulation accelerates.
United States
Ethanol-adjacent corn milling concentrates in Iowa and Illinois, where integrated processors leverage co-product economics for animal feed and food-grade flour streams. EPA emissions standards and OSHA dust control requirements shape facility upgrade timelines. Cargill and Archer Daniels Midland Company anchor origination networks across the Corn Belt, securing feedstock flexibility through multi-state procurement.
Brazil
Export-oriented milling capacity is expanding in Mato Grosso and Paraná to serve Chinese and Southeast Asian buyers with corn flour and soybean meal co-products. ANVISA enforces pesticide residue limits that align with EU Green Deal traceability requirements, forcing certified supplier investments. Bunge Limited leverages port-adjacent grain handling assets to feed export milling streams with competitive logistics economics.
Argentina
Rosario and Buenos Aires provinces concentrate soybean and corn milling for global export, with direct sourcing contracts bypassing traditional merchant intermediaries. The country's national agricultural regulator enforces export quality certificates that mirror SAMR GB standards for Chinese market access. Quick-service restaurant procurement teams negotiate volume commitments directly with Pampas-region millers for tortilla and chip manufacturing specifications.
Germany
European milling leadership concentrates in North Rhine-Westphalia and Bavaria, where facilities retrofit for EU Green Deal Farm-to-Fork pesticide residue limits and F-Gas Regulation compliance. EFSA traceability requirements and REACH authorization for food-contact processing aids are diverging product specifications from FDA-registered equivalents. Hamburg and Bremen port clusters handle Black Sea grain origination with redundant inventory positions against geopolitical disruption.
China
Shandong and Hebei provinces dominate wheat flour production for domestic baking and noodle manufacturing, with protein content stratification forcing regional wheat origination segregation. SAMR enforcement of GB standards for imported flour specifications accelerates quality investments among export-oriented millers. Yangtze River Delta food manufacturers specify exact moisture and fermentation performance profiles that command dedicated milling lines with segregated production.
Global Dry Milling Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation feedstocks and gluten-free specialty grades. The vendor base stratifies across integrated agricultural traders, independent regional millers, and ethanol-processor co-product specialists. Three archetypes dominate: origination-network integrators leveraging multi-source grain procurement; specialty-grade processors commanding specification premiums; and co-product optimizers maximizing ethanol-adjacent economics. Competitive moves concentrate on strategic partnerships for blockchain traceability compliance and capacity expansion in South American export corridors.
Within the origination-network tier, Cargill exemplifies feedstock flexibility through Corn Belt and Black Sea procurement reach. Archer Daniels Midland Company anchors North American ethanol-adjacent milling with integrated corn processing infrastructure. Bunge Limited occupies a position among South American oilseed and grain handling specialists feeding export milling streams. These three represent divergent geographic and vertical strategies rather than direct product competition.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Bunge Limited |
| SunOpta, Inc. |
| Grain Millers Inc. |
| Semo Milling, LLC |
| LifeLine Foods, LLC |
| Green Plains Inc. |
| Valero Energy Corporation |
| Others |
Supply Flow & Price Mechanics
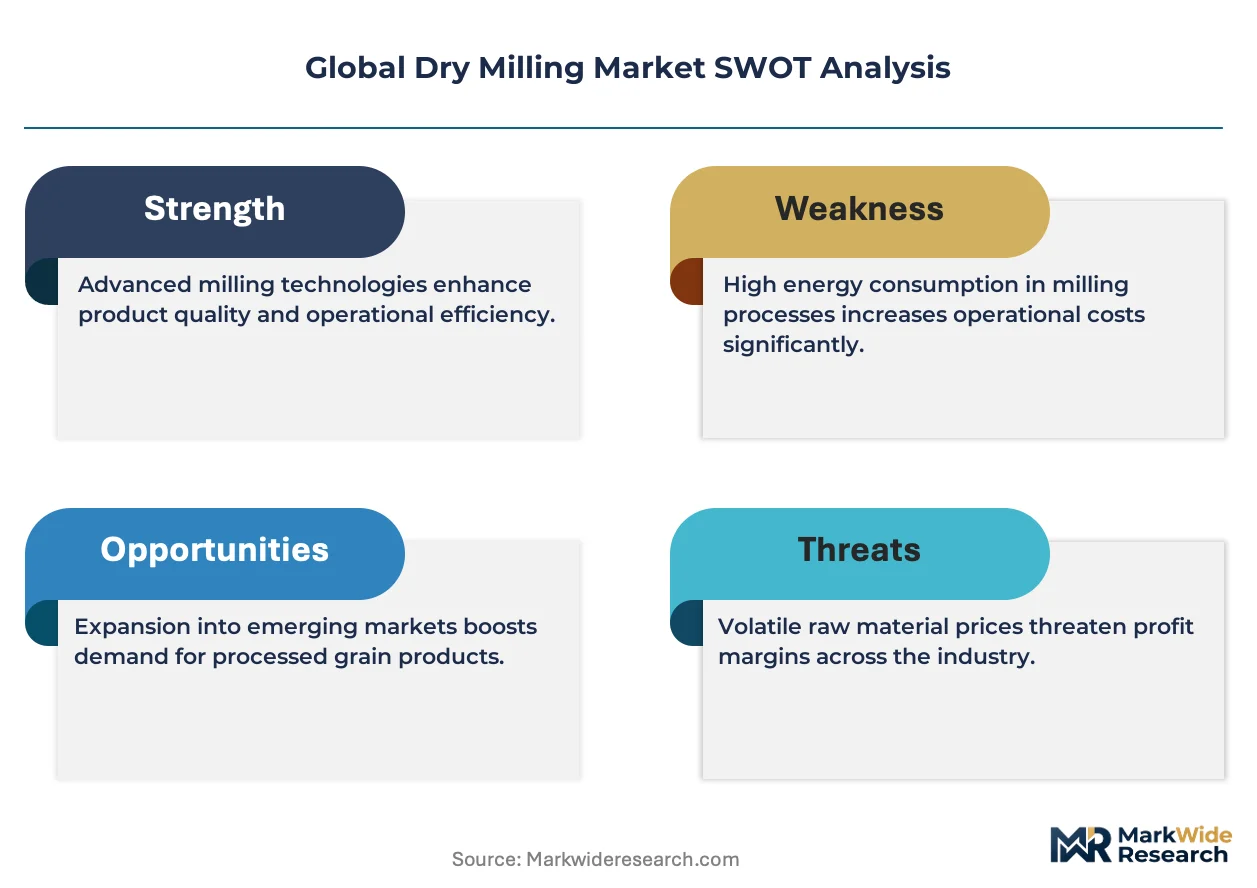
Natural gas and electricity price volatility propagates through tempering and drying stages to compress margins across European and North American milling operations, with energy-intensive facilities passing cost increases downstream through contract renegotiation while spot-market buyers absorb sharper price swings.
Pricing Analysis
Input-cost pass-through dominates contract structures, with long-term offtake agreements embedding fuel-adjustment clauses that shift energy volatility risk between millers and food manufacturers. Price differentiation hinges on EU Green Deal certification tier and volume scale, with traceable premium grades commanding sourcing premiums from export buyers. Pricing pressure stems from F-Gas Regulation compliance costs in Europe, forcing margin compression at standard-grade tiers. Small-batch specialty grain processors show lowest price sensitivity due to specification rigidity, while commodity flour buyers in retail channels negotiate aggressively on per-ton basis.
Supply Chain Analysis
Freight cost differentials between Black Sea and South American origination routes are redirecting Asian buyer procurement toward Brazil and Argentina, compressing traditional North Atlantic trade economics. Supply concentrates in the United States, Brazil, and Argentina, with raw material flows drawing from Corn Belt, Mato Grosso, and Pampas-region grain belts. Wheat, corn, and rice constitute core inputs, with protein content and moisture specifications varying by downstream application. Single-source vulnerability persists in Black Sea grain origination, where geopolitical disruption forces redundant inventory positions. Distribution runs through direct silo-to-silo transfer for industrial buyers and wholesale channels for foodservice intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dry Milling Market functions as a stable compounder, with plant-forward menu development and gluten-free formulation requirements delivering steady volume pull through specialty flour channels.
For Market Incumbents: Cement feedstock flexibility through multi-origin procurement networks spanning US Corn Belt and South American grain belts, insulating margin pools from climate-driven origination compression. Invest in EU Green Deal certification infrastructure to capture premium-tier pricing from export buyers facing tightened traceability mandates. Prioritize automated sifter control integration to defend against technology-first entrants targeting contract milling services.
For New Entrants and Emerging Players: Near-infrared spectroscopy platforms enable real-time quality adjustment that incumbents' legacy automation resists, creating entry pathways into small-batch specialty processing. Target Vietnam and Indonesia rice flour white space, where gluten-free bakery reformulation outpaces dedicated milling capacity. Pursue direct sourcing contracts with quick-service chains seeking brand-specific particle specifications that resist commodity substitution.
For Investors and Strategic Acquirers: Roll-up economics work for regional independent millers because EU Green Deal compliance timelines are forcing consolidation among capital-constrained operators lacking certification infrastructure. Five-to-ten-year viability favors origination-adjacent assets with port access and segregated production capabilities. Watch for inflection in China's SAMR enforcement intensity, which would accelerate quality investment requirements among export-oriented suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill and Bunge leverage Corn Belt and Paraná assets to secure feedstock flexibility against climate volatility. |
| EU Green Deal Certification Investment | German millers retrofit North Rhine-Westphalia facilities to capture premium tiers from traceability-demanding export buyers. |
| Blockchain Traceability Platform Deployment | Middleware integration resolves legacy automation conflicts with EFSA and SAMR documentation requirements. |
| South American Export Capacity Expansion | Brazilian port-adjacent milling investments redirect Asian buyer flows away from traditional North Atlantic routes. |
| Near-Infrared Spectroscopy Integration | Real-time protein and moisture adjustment opens contract milling services for small-batch specialty grain processors. |
Methodological Framework
Coverage spans North America, Europe, South America, and Asia-Pacific, with primary inputs from each region combined with secondary validation across trade databases and regulatory filings. Primary interviews engaged milling operations directors, grain procurement leads at integrated traders, food manufacturer R&D heads, and quick-service restaurant supply chain managers. Secondary sources included customs and trade flow data, EPA and EFSA regulatory documentation, SAMR GB standard publications, and SEC filings from publicly traded agricultural processors. Bottom-up capacity modeling and top-down demand segmentation were triangulated against disclosed production volumes.
Granularity was maintained at product-type, application, and end-user levels, with geographic splits modeled for country-specific regulatory and demand conditions. Corn flour, wheat flour, rice flour, and barley flour were separately projected across baking, snacks, cereals, and beverage applications. CAGRs were derived from volume-weighted growth rates across these segments, incorporating ethanol co-product economics, gluten-free formulation trends, and foodservice direct-contracting velocity as industry-specific demand inputs.
The model holds under stable regulatory enforcement timelines and intact Black Sea trade corridors; deviation in geopolitical disruption severity or accelerated EU Green Deal implementation would shift capacity investment patterns and origination network economics. Stakeholders should weight assumptions against their own operating context and supplier concentration exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Seed Processing Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Global Threshers Market