
 Global Agricultural Harvesting Machinery Market | 2026-2036
Global Agricultural Harvesting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Harvesting Machinery Market Foresight
The capital-intensity divergence between full-line manufacturers and regional specialists is rotating competitive advantage toward firms with in-house engine and precision-technology platforms. John Deere leverages its integrated powertrain and autonomy stack to command premium positioning in North American grain belts. CLAAS anchors European demand through dominant combine harvester engineering and dense dealer networks across Germany and France.
Agricultural harvesting machinery encompasses self-propelled and trailed equipment engineered to cut, thresh, clean, and collect mature crops, with working widths ranging from three to fourteen meters and grain tank capacities exceeding fifteen cubic meters on premium combines. This equipment serves commercial farming operations by compressing harvest windows and minimizing field losses during weather-sensitive periods. Combine harvesters occupy the largest value pool due to their universal deployment across grain, oilseed, and pulse crops, while telemetry systems represent the fastest-expanding technology segment as fleet managers prioritize real-time yield mapping and remote diagnostics. Forage harvesters sustain durable margin pools in dairy-intensive regions where silage quality directly affects livestock productivity metrics.
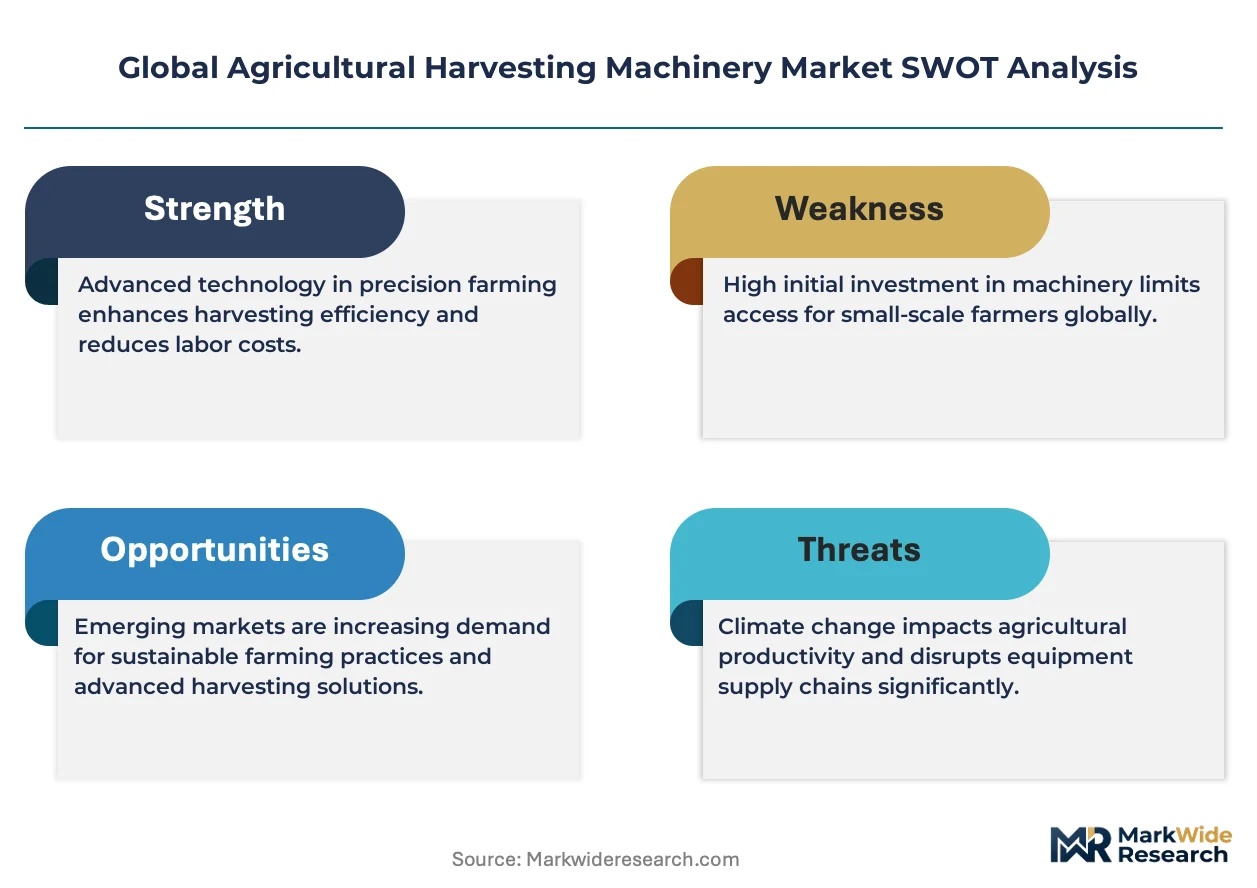
The EPA enforces Tier 4 Final and emerging low-NOx emissions standards that compel engine redesigns and after-treatment investments for equipment sold in the United States. REACH and the EU Green Deal shape material compliance and carbon-accounting obligations for manufacturers distributing across European member states, while ISO 12100 safety standards govern protective-structure design and operator-risk mitigation globally. Stakeholders must weigh the capital requirements of electrification prototyping against the revenue durability of conventional diesel platforms in markets with uneven charging infrastructure.
Market Dynamics
The European Union's F-Gas Regulation is compressing engine development cycles while GPS-guided autonomy stacks concentrate competitive advantage among full-line manufacturers with captive powertrain engineering.
Growth Catalysts
- Precision Autonomy Stacks:Large-scale grain operations in the United States and Brazil are integrating real-time yield mapping with automated steering to compress harvest windows during weather-sensitive periods.
- REACH Material Compliance:The EU Green Deal's carbon-accounting obligations are accelerating replacement cycles for older equipment fleets across Germany and France.
- Soybean-Corn Rotation Intensity:Brazil's Mato Grosso state anchors replacement demand as double-cropping systems strain machinery utilization rates beyond design thresholds.
Market Restraints
- Steel and Rare Earth Volatility:Input cost swings for permanent magnet motors and high-strength alloys compress margin visibility for Tier 2 component suppliers.
- Tier 4 Final After-Treatment Cost:EPA-mandated diesel particulate filters and selective catalytic reduction systems add capital burden without commensurate pricing power in price-sensitive segments.
- Dealer Network Concentration:Dense CLAAS and John Deere distribution in the Corn Belt limits market access for regional specialists lacking service infrastructure.
Strategic Opportunities
- Ukrainian Black Soil Recovery:Post-conflict reconstruction of large-scale grain operations will require high-capacity combine fleets with rapid deployment capability.
- Telematics-As-A-Service:Unbundled subscription models for remote diagnostics and predictive maintenance are penetrating dairy-intensive regions where uptime directly affects silage quality metrics.
- Indian PLI Scheme Alignment:Production-linked incentives for farm mechanization are opening assembly partnerships for mid-range equipment targeting smallholder consolidation zones.
Industry Challenges
- Autonomy Software Integration:Retrofitting legacy combines with sensor fusion and path-planning algorithms requires specialized field engineering talent scarce outside OEM captive teams.
- ISO 12100 Certification Timelines:Protective-structure redesigns for operator-risk mitigation extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Harvesting Machinery Market |
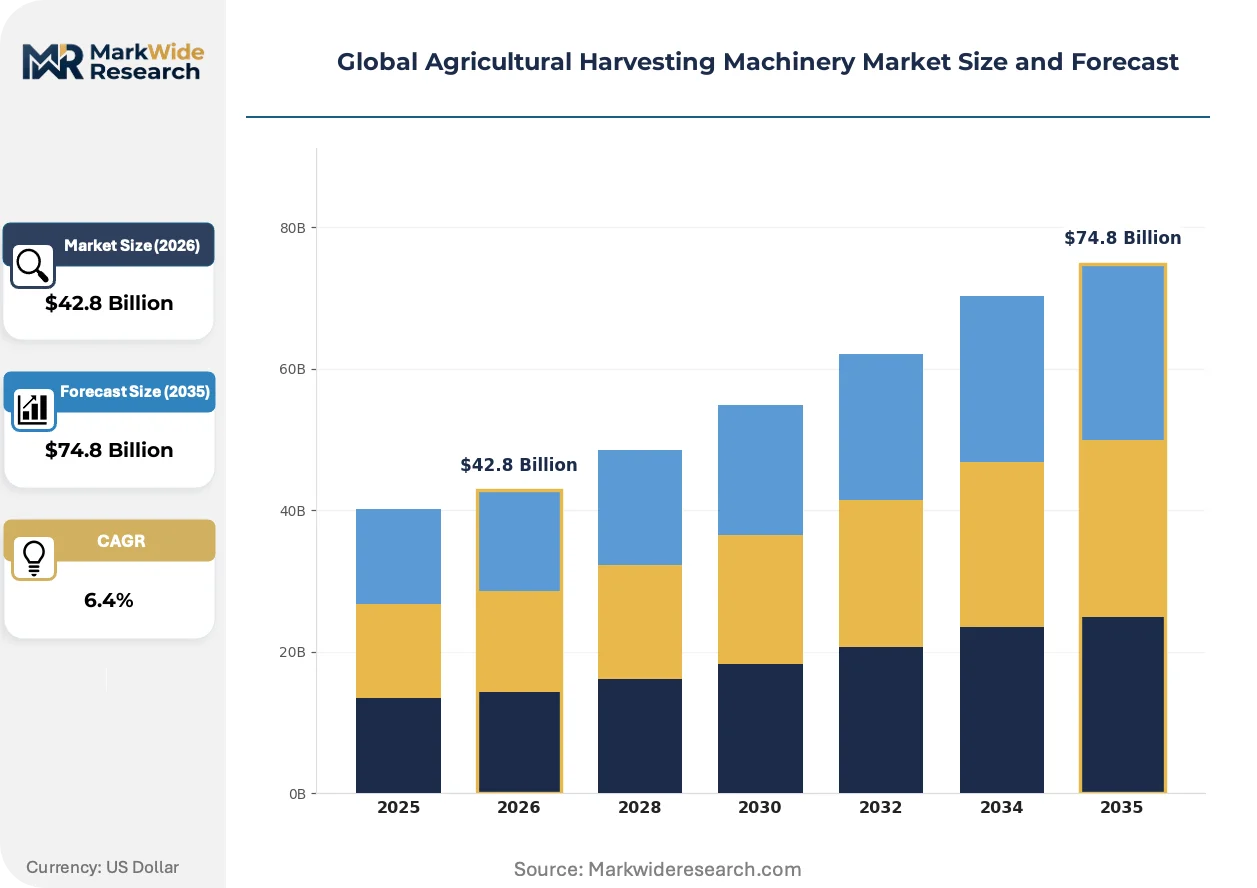
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
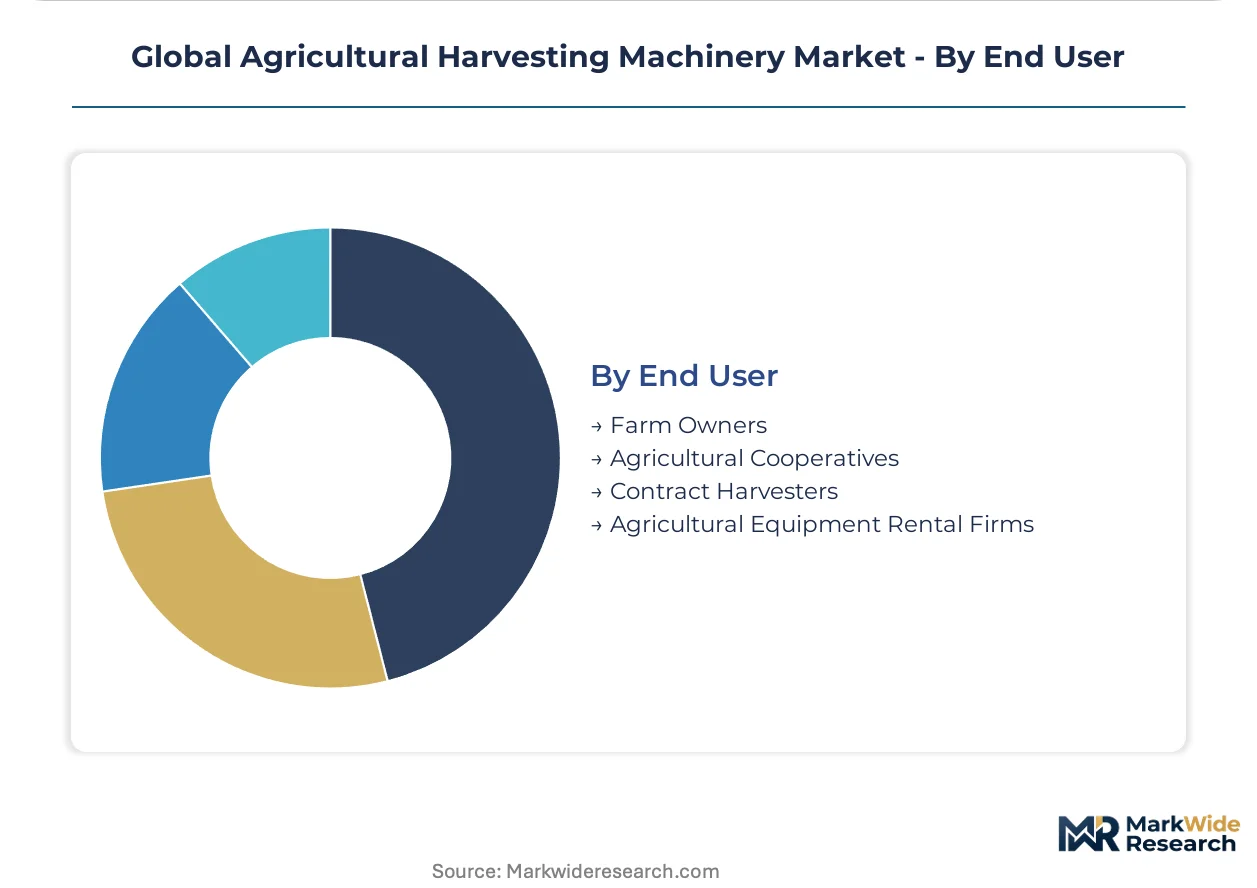
| Segmentation | Product Type: Combine Harvesters, Forage Harvesters, Reapers, Threshers, Swathers Technology: GPS Guidance, Automated Steering, Variable Rate Technology, Sensor-Based Sorting, Telemetry Systems Application: Grain Crops, Root Crops, Oilseed Crops, Fiber Crops, Pulse Crops End User: Farm Owners, Agricultural Cooperatives, Contract Harvesters, Agricultural Equipment Rental Firms |
| Companies Covered | AGCO Corporation, Case IH, CLAAS, Massey Ferguson, Fendt, John Deere, New Holland Agriculture, Rostselmash, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Harvesting Machinery Market Shifts & Advancements
Electrification prototyping is diverging from diesel platform durability as uneven charging infrastructure forces geographic sequencing of battery-electric combine launches.
Swappable battery architectures for mid-size forage harvesters is bifurcating the product roadmap between European dairy cooperatives with depot charging and North American grain belts dependent on field refueling logistics. Danish and Dutch operations are piloting fast-swap systems for silage contractors running 20-hour harvest windows. This technology is compressing the viable range for pure-electric platforms toward sub-200-horsepower segments while extending diesel dominance in high-capacity combines.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing redesigns of cab climate systems and engine cooling circuits. Manufacturers are shifting to CO2-based heat pumps and low-GWP alternatives. German and French combine production lines are absorbing the bulk of retooling costs, with Tier 4 Final engines in the United States following parallel thermal-management development paths.
Fleet managers are unbundling after-sales service contracts from equipment financing, preferring per-hour uptime guarantees over traditional parts-and-labor arrangements. This shift is disrupting dealer revenue models in the United States Corn Belt where CLAAS and John Deere historically captured lifetime value through captive maintenance programs. Dairy operations in Wisconsin and Minnesota are driving this preference, treating harvester availability as an operational expense rather than capital risk.
Global Agricultural Harvesting Machinery Market Segmentation
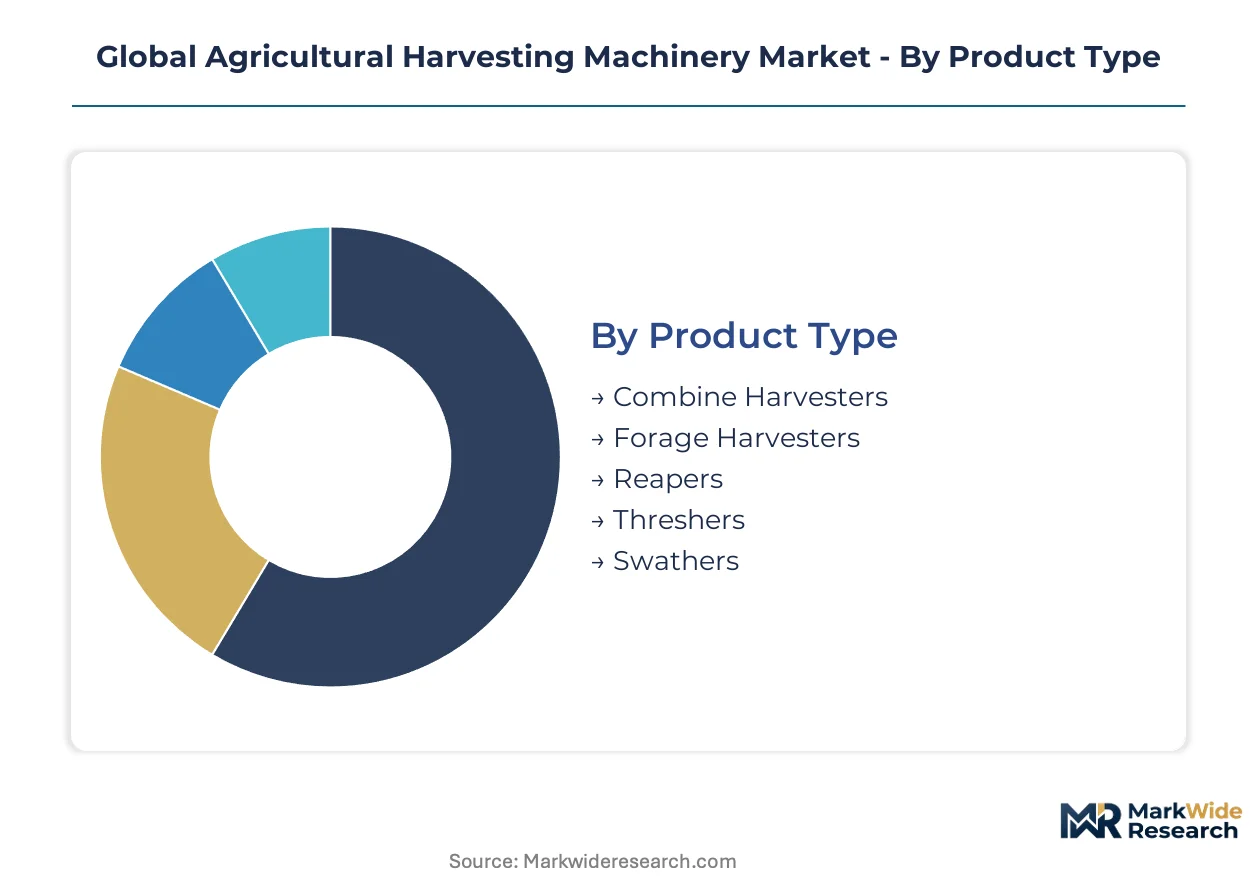
Segmentation in agricultural harvesting machinery reveals how technology premiums concentrate among full-line manufacturers while regional specialists defend niches through application-specific engineering. Equipment specifications diverge sharply between North American grain belts and European dairy-intensive regions.
Product Type:
Substitution pressure from precision autonomy stacks and telemetry-as-a-service models threatens standalone equipment categories that lack integrated powertrain platforms.
- Combine Harvesters:Self-propelled machines integrate cutting, threshing, cleaning, and grain storage with working widths spanning three to fourteen meters. Demand concentrates in Brazil's Mato Grosso state where soybean-corn rotation intensity strains machinery beyond design thresholds.
- Forage Harvesters:Equipment engineered for silage and haylage production with kernel processors and crop-flow optimization. Dairy cooperatives in Wisconsin and Minnesota drive replacement cycles where uptime guarantees now outweigh capital ownership models.
- Reapers:Trailed or mounted cutting equipment for smallholder and mid-scale operations. Indian PLI scheme incentives are opening assembly partnerships targeting consolidation zones.
- Threshers:Stationary or mobile units separating grain from straw. Post-conflict Ukrainian reconstruction will require rapid-deployment fleets for Black Soil recovery.
- Swathers:Windrowing equipment for hay and small grains in moisture-sensitive harvest windows. Canadian prairie operations anchor residual demand for trailed configurations.
Combine Harvesters anchor the volume base while Telemetry Systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium OEM-integrated stacks from aftermarket retrofit kits across dealer networks.
- GPS Guidance:Satellite-based positioning enabling sub-inch accuracy for field operations. Large-scale grain operations in the United States integrate real-time yield mapping to compress harvest windows during weather-sensitive periods.
- Automated Steering:Path-planning algorithms reducing operator fatigue and overlap penalties. CLAAS and John Deere dealer concentration in the Corn Belt limits market access for regional specialists lacking service infrastructure.
- Variable Rate Technology:Input modulation based on yield history and soil mapping. Precision agriculture adoption in Germany and France accelerates replacement of legacy equipment fleets.
- Sensor-Based Sorting:Real-time grain quality assessment during harvest. EU Green Deal carbon-accounting obligations drive upgrade demand for compliance visibility.
- Telemetry Systems:Remote diagnostics and predictive maintenance platforms. Unbundled subscription models penetrate dairy-intensive regions where silage quality directly affects livestock productivity metrics.
GPS Guidance commands the installed base while Automated Steering expands most quickly among new equipment orders.
Application:
Geographic concentration of crop types dictates machinery specification requirements across regional manufacturing footprints.
- Grain Crops:Wheat, rice, and corn harvesting requiring high-capacity combines with grain tank capacities exceeding fifteen cubic meters. EPA Tier 4 Final after-treatment costs add capital burden without commensurate pricing power in price-sensitive segments.
- Oilseed Crops:Soybean and canola operations with specialized headers and residue management. Brazil's double-cropping systems generate replacement demand as utilization rates exceed design thresholds.
- Root Crops:Potato and sugar beet harvesting with gentle-handling requirements. REACH material compliance and EU F-Gas Regulation accelerate fleet turnover in European production zones.
- Fiber Crops:Cotton and hemp operations with module-building and stripping attachments. Input cost volatility for high-strength alloys compresses margin visibility for component suppliers.
- Pulse Crops:Lentil, pea, and bean harvesting with flexible cutterbar configurations. ISO 12100 safety standards extend product launch cycles by 8-14 months for protective-structure redesigns.
Grain Crops dominate equipment deployment while Oilseed Crops climb the fastest on South American expansion.
End User:
Customer type determines financing structure preference and service contract unbundling patterns across mature markets.
- Farm Owners:Individual operators prioritizing equipment control and depreciation capture. Large-scale owners across the United States and Brazil expand GPS-guided combine fleets to improve yield efficiency.
- Agricultural Cooperatives:Member-owned entities pooling capital for shared machinery access. Danish and Dutch operations pilot fast-swap battery systems for silage contractors running extended harvest windows.
- Contract Harvesters:Custom operators charging per-acre or per-hour rates with rapid depreciation schedules. Fleet managers prioritize real-time yield mapping and remote diagnostics for asset utilization optimization.
- Agricultural Equipment Rental Firms:Asset-light models providing seasonal access without ownership risk. Per-hour uptime guarantees disrupt traditional parts-and-labor dealer revenue models in the Corn Belt.
Farm Owners represent the core customer base while Agricultural Cooperatives show the steepest adoption curve for shared-equipment platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal machinery trade deficits in grain-importing nations and surplus positions in manufacturing-intensive economies. Equipment flows track harvest intensity zones and regulatory compliance requirements.
United States
Large-scale grain operations in Iowa and Illinois drive replacement cycles for high-capacity combines with GPS-guided autonomy stacks. EPA Tier 4 Final emissions standards compel after-treatment investments that add capital burden without pricing power recovery. The Corn Belt anchors dealer network concentration where service infrastructure limits market access for regional specialists.
Germany
Engineering-intensive combine production concentrates in Lower Saxony and Baden-Württemberg with dominant harvester manufacturing footprints. EU F-Gas Regulation forces cab climate system redesigns toward CO2-based heat pumps and low-GWP alternatives. Dense dealer networks across Bavaria and North Rhine-Westphalia sustain premium positioning for full-line manufacturers.
Brazil
Soybean-corn rotation intensity in Mato Grosso generates replacement demand as double-cropping systems strain machinery beyond design thresholds. ANVISA and environmental licensing shape equipment import compliance for multinational assemblers. São Paulo state anchors distribution infrastructure for South American fleet expansion.
India
Smallholder consolidation zones in Maharashtra and Gujarat drive PLI scheme-aligned assembly partnerships for mid-range equipment. BIS certification requirements and state-level farm mechanization subsidies compress product launch timelines. Punjab and Haryana sustain residual demand for reapers and threshers in wheat-rice systems.
China
Domestic grain security priorities accelerate fleet modernization in Heilongjiang and Henan provinces with state procurement programs. MIIT equipment standards and GB certification timelines govern protective-structure compliance. Yangtze River Delta manufacturing clusters absorb technology transfer partnerships for precision agriculture components.
Global Agricultural Harvesting Machinery Market Competitive Landscape
Concentration sits with full-line manufacturers possessing captive powertrain engineering and dense service networks. The vendor base stratifies across three tiers: integrated OEMs with autonomy stacks, regional specialists defending application niches, and contract assemblers serving price-sensitive segments. Strategic moves center on telematics unbundling and battery-electric prototyping partnerships.
Within the integrated OEM tier, John Deere and CLAAS exemplify archetypes combining powertrain control with precision technology platforms. AGCO Corporation occupies a position spanning multiple brand architectures. These entities anchor competitive dynamics through in-house production of engine and sensor systems rather than component sourcing.
| Leading Market Players |
|---|
| AGCO Corporation |
| Case IH |
| CLAAS |
| Massey Ferguson |
| Fendt |
| John Deere |
| New Holland Agriculture |
| Rostselmash |
| CNH Industrial |
| Others |
Supply & Pricing Matrix
CO2-based heat pump adoption in cab climate systems is displacing hydrofluorocarbon refrigerants across German and French production lines, simultaneously compressing supplier margins in legacy cooling component ecosystems while redistributing pricing power toward thermal-management engineering specialists with EU F-Gas Regulation certification pathways.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with GPS-guided autonomy stacks and integrated powertrain platforms commanding substantial premiums over regional specialist equipment. Price differentiation separates John Deere and CLAAS dealer-network density from Tier 2 competitors lacking comparable service infrastructure. Pricing pressure stems from EPA Tier 4 Final after-treatment cost absorption without commensurate pricing power recovery in price-sensitive grain segments. Contract harvesters exhibit highest price sensitivity due to rapid depreciation schedules, while large-scale farm owners in Brazil's Mato Grosso demonstrate lowest sensitivity given machinery utilization rates exceeding design thresholds.
Supply Chain Analysis
Permanent magnet motor sourcing from China, rare earth processing concentration in Australia, and high-strength alloy production in Germany create multi-node vulnerability for electrification prototyping timelines. Raw material dependencies center on neodymium-dysprosium magnets, boron-steel alloys, and precision sensor arrays. Supply chain risk manifests as single-source vulnerability for rare earth separation capacity. Distribution runs through captive dealer networks in the United States Corn Belt and dense CLAAS service infrastructure across Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry-as-a-service unbundling represents a platform-economics inflection where fleet managers treat harvester availability as operational expense rather than capital risk, eroding traditional captive maintenance revenue models and demanding interoperability standards across John Deere, CLAAS, and AGCO data architectures.
For Market Incumbents: Secure autonomy software integration capabilities through specialized field engineering talent acquisition, as retrofitting legacy combines with sensor fusion and path-planning algorithms requires expertise scarce outside OEM captive teams. Defend against telematics unbundling by embedding predictive maintenance algorithms into financing contracts rather than treating diagnostics as separable subscription tiers.
For New Entrants and Emerging Players: Per-hour uptime guarantee gaps in dairy-intensive Wisconsin and Minnesota operations expose incumbent reluctance to shift from parts-and-labor revenue models. Target agricultural cooperatives piloting fast-swap battery architectures for mid-size forage harvesters, where 20-hour harvest windows create acute availability sensitivity. Pursue white-label telematics partnerships with Indian PLI scheme-aligned assemblers seeking European market entry.
For Investors and Strategic Acquirers: The market sits at a regulatory-compliance acceleration phase that favors component suppliers with REACH material certification and EU F-Gas Regulation thermal-management expertise. Long-term viability hinges on electrification prototyping partnerships rather than pure diesel platform durability. Watch for Ukrainian Black Soil reconstruction procurement announcements as inflection indicator for high-capacity combine fleet deployment timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomy Stack Integration | Sensor fusion and path-planning algorithm development compresses harvest windows for weather-sensitive grain operations. |
| Telematics Unbundling | Per-hour uptime guarantees disrupt CLAAS and John Deere captive maintenance revenue models in the Corn Belt. |
| Fast-Swap Battery Partnerships | Danish and Dutch dairy cooperatives pilot 20-hour harvest window systems for silage contractors. |
| EU F-Gas Compliance Retooling | CO2-based heat pump adoption forces cab climate system redesigns across German and French production lines. |
| Ukrainian Fleet Prepositioning | Post-conflict Black Soil reconstruction demands rapid-deployment high-capacity combine capabilities. |
Research Methodology
The analysis maps combine harvesters, forage harvesters, reapers, threshers, and swathers, each validated through fleet managers, agricultural cooperative procurement officers, OEM aftermarket service heads, and Tier 2 component supplier executives. Primary interview data triangulates against customs and trade flow databases, EPA and EU F-Gas Regulation compliance filings, SEC 10-K equipment revenue disclosures, and agricultural machinery registration records. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models equipment type, technology tier, crop application, and end-user financing structure as core segmentation dimensions. CAGRs derive from replacement cycle intensity in Brazil's Mato Grosso, fleet modernization timelines in Heilongjiang province, and PLI scheme absorption rates in Maharashtra and Gujarat.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement and EU F-Gas Regulation phasedown schedules; material policy shifts would require re-modeling. Steel and rare earth price volatility, autonomous harvesting liability frameworks, and charging infrastructure deployment unevenness constitute specific revision triggers. Practitioners should keep alternative scenarios live as electrification prototyping diverges from diesel platform durability assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market
Agricultural Processing Equipment
Rice Milling Machinery Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Hemp Processing Equipment Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Shelling Machine Market