
 Shelling Machine Market | 2026-2036
Shelling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shelling Machine Market Analysis
China's manufacturing corridor is rewriting capacity dynamics for shelling equipment destined for Asian food processors. Bühler AG leverages its Swiss engineering heritage to sustain premium positioning in nut and seed processing lines. Satake Corporation anchors rice and grain shelling technology leadership across East Asian markets. F.H. SCHULE Mühlenbau GmbH specializes in custom milling integrations that differentiate its offering from standardized competitors.
A shelling machine mechanically removes husks, pods, or outer layers from nuts, seeds, fruits, and crops through friction, impact, or pressure application, typically operating at throughput rates from 500 kg to 50 tons per hour depending on material density and rotor configuration. Mechanical and electric type segments dominate installed bases due to lower capital requirements and simpler maintenance protocols, though pneumatic systems capture margin pools in high-value nut processing where kernel integrity commands premium pricing. The application split favors nuts and seeds over fruits and crops in revenue terms because almond, cashew, and sunflower processors prioritize yield recovery rates that justify sophisticated equipment expenditure.
USDA grading standards and FDA food safety regulations shape equipment design requirements for shelling machines entering North American food processing facilities, while REACH and CE marking frameworks govern material compliance and electrical safety for European deployments. China's GB standards and MEE emissions directives increasingly influence motor specifications and dust containment architectures for equipment manufactured domestically. Stakeholders must monitor how diverging energy efficiency mandates across major manufacturing jurisdictions affect platform standardization strategies and aftermarket parts compatibility.
Market Dynamics
Automated shelling equipment procurement accelerates as Southeast Asian food processors replace manual labor with friction-based and impact-driven mechanical systems, while Brazil's agricultural operators modernize legacy infrastructure to capture yield recovery premiums in soybean and nut processing operations.
Growth Catalysts
- MEE dual carbon goals:China's emissions directives push domestic manufacturers toward energy-efficient electric motor designs, expanding addressable equipment demand across Asian processing facilities.
- USDA grading standards:North American almond and cashew processors invest in sophisticated shelling lines to meet kernel integrity requirements for premium export tiers.
- Brazilian soybean belt concentration:Large-scale agricultural operators in Mato Grosso and Paraná upgrade mechanical systems to reduce post-harvest losses and labor dependency.
Market Restraints
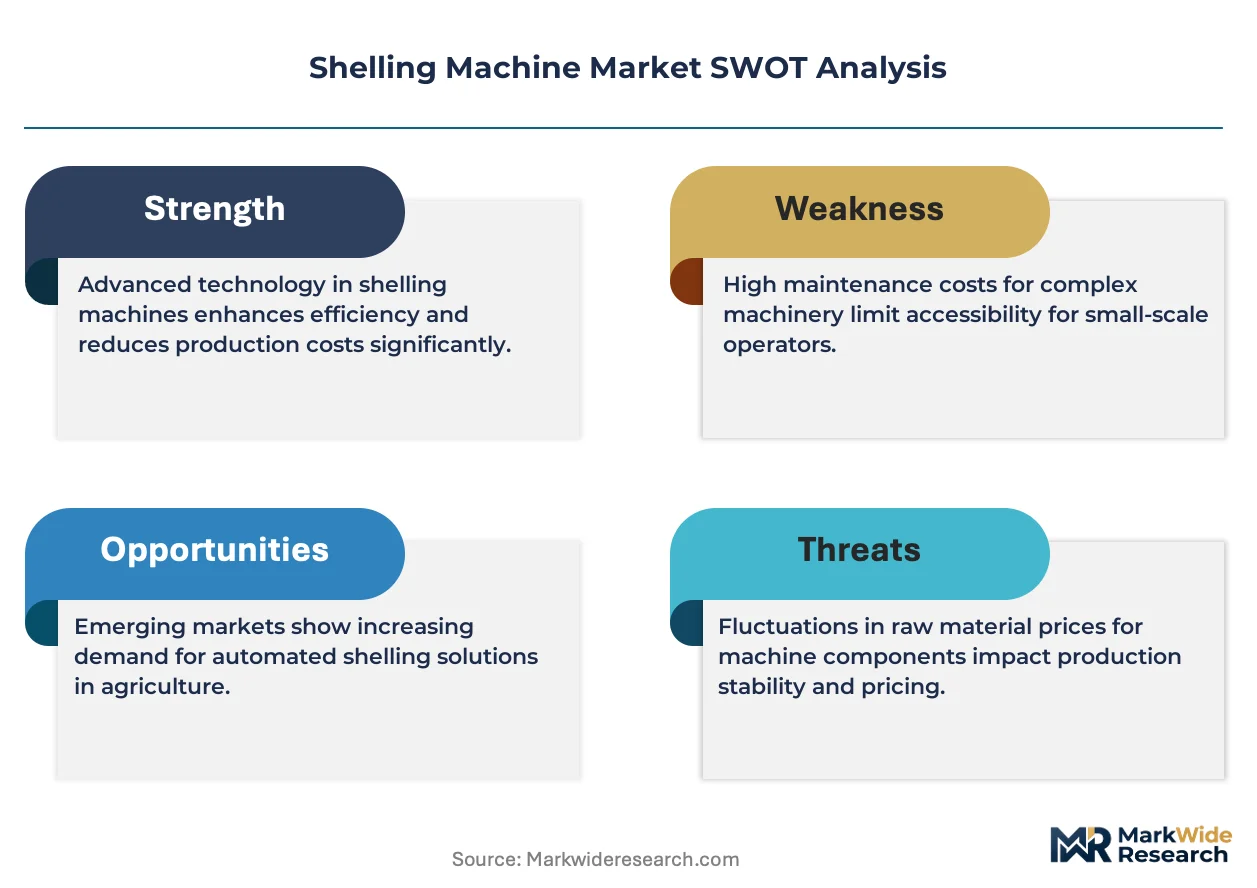
- Stainless steel input volatility:Food-grade 304 and 316 alloy prices fluctuate with nickel and chromium commodity markets, compressing fabrication margins for equipment builders.
- Pneumatic component supply concentration:High-pressure valve and compressor assemblies source predominantly from German and Japanese specialty suppliers, creating procurement bottlenecks.
- Kernel damage trade-offs:High-throughput rotor configurations in nut processing sacrifice yield recovery rates, limiting adoption among premium almond and pistachio operators.
Strategic Opportunities
- India's FSSAI modernization:Food safety compliance mandates drive replacement cycles in Gujarat and Maharashtra cashew processing clusters.
- Convergence of optical sorting and shelling:Integrated vision systems with real-time kernel damage detection command pricing premiums in high-value nut lines.
- Direct equipment financing:Leasing and pay-per-ton models penetrate Southeast Asian mid-scale processors previously excluded by upfront capital requirements.
Industry Challenges
- Mechatronics technician scarcity:Servo motor calibration and PLC programming expertise lags equipment sophistication in Brazil and Indonesian installation bases.
- CE-REACH certification timelines:European material compliance documentation extends delivery schedules for Asian manufacturers entering EU markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelling Machine Market |
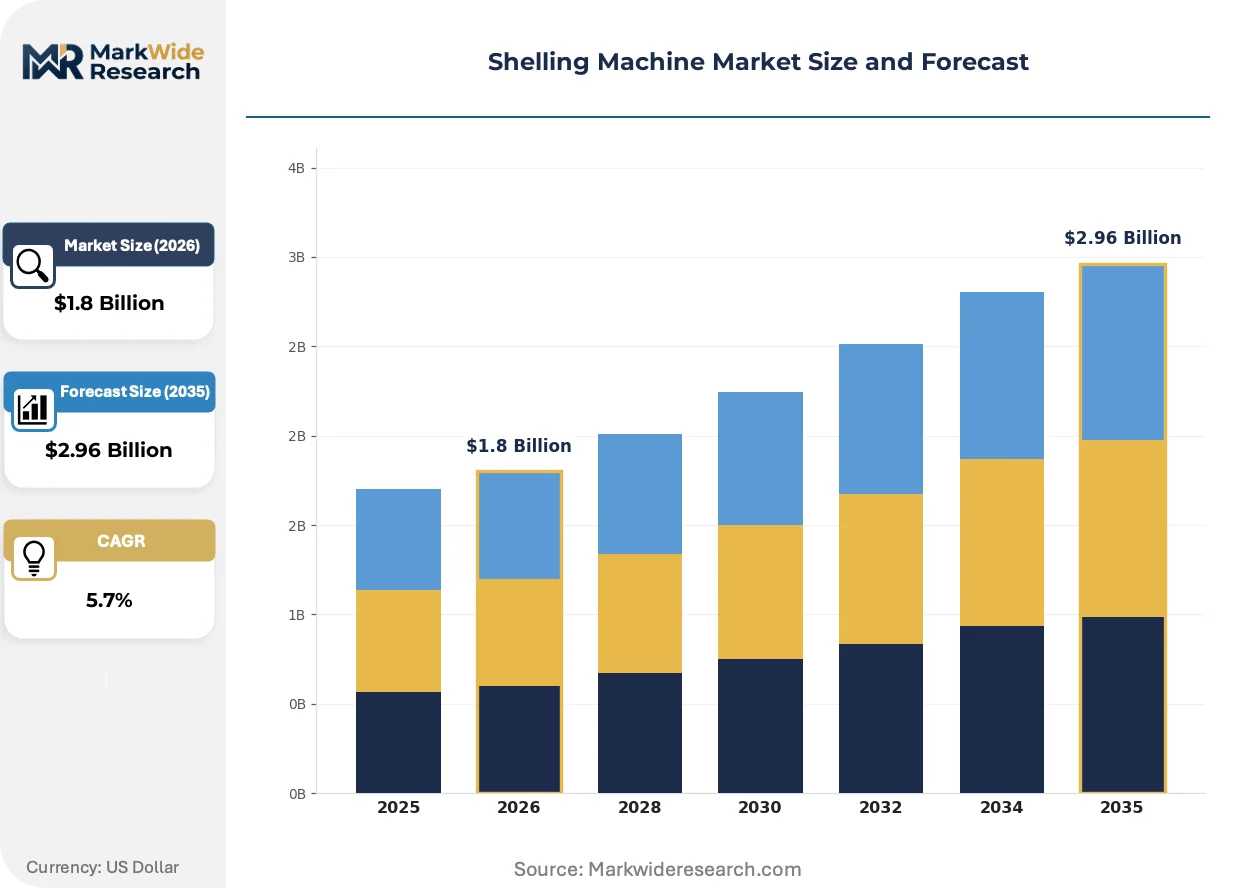
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Pneumatic, Electric, Hydraulic Application: Nuts, Seeds, Fruits, Crops End User: Agriculture, Food Processing, Packaging, Manufacturing Size: Small, Medium, Large, Industrial |
| Companies Covered | Bühler AG, Satake Corporation, F.H. SCHULE Mühlenbau GmbH, AGI, Bratney Companies, TABANLI Machinery, Omas Industries, Sangati Berga, Alvan Blanch Development Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelling Machine Market Emerging Trajectories
Digital twin architectures and predictive maintenance protocols are compressing equipment downtime in high-volume processing environments, while regulatory fragmentation across major manufacturing jurisdictions forces platform modularization strategies.
Sensor-integrated shelling units with real-time throughput monitoring and automated gap adjustment are virtualizing traditional mechanical calibration protocols. Almond processors in California's Central Valley deploy these systems to maintain kernel size consistency across variable harvest moisture conditions. The technology is virtualizing reliance on experienced operator judgment, reducing labor skill requirements while standardizing output quality.
REACH substance restrictions and RoHS electrical safety directives in Europe mandate lead-free bearing alloys and insulated motor housings for equipment entering EU food facilities. Chinese manufacturers redesign export configurations to accommodate dual compliance architectures. Nut and seed processing lines bound for German and Dutch markets absorb the highest certification engineering overhead.
Buyers in Southeast Asia increasingly unbundle after-sales service contracts from initial equipment procurement, sourcing spare parts and maintenance through third-party industrial distributors. This channel fragmentation pressures OEM margin structures. Indonesian and Vietnamese rice millers drive this behavioral shift, prioritizing localized parts availability over manufacturer-authorized service networks.
Shelling Machine Market Segmentation
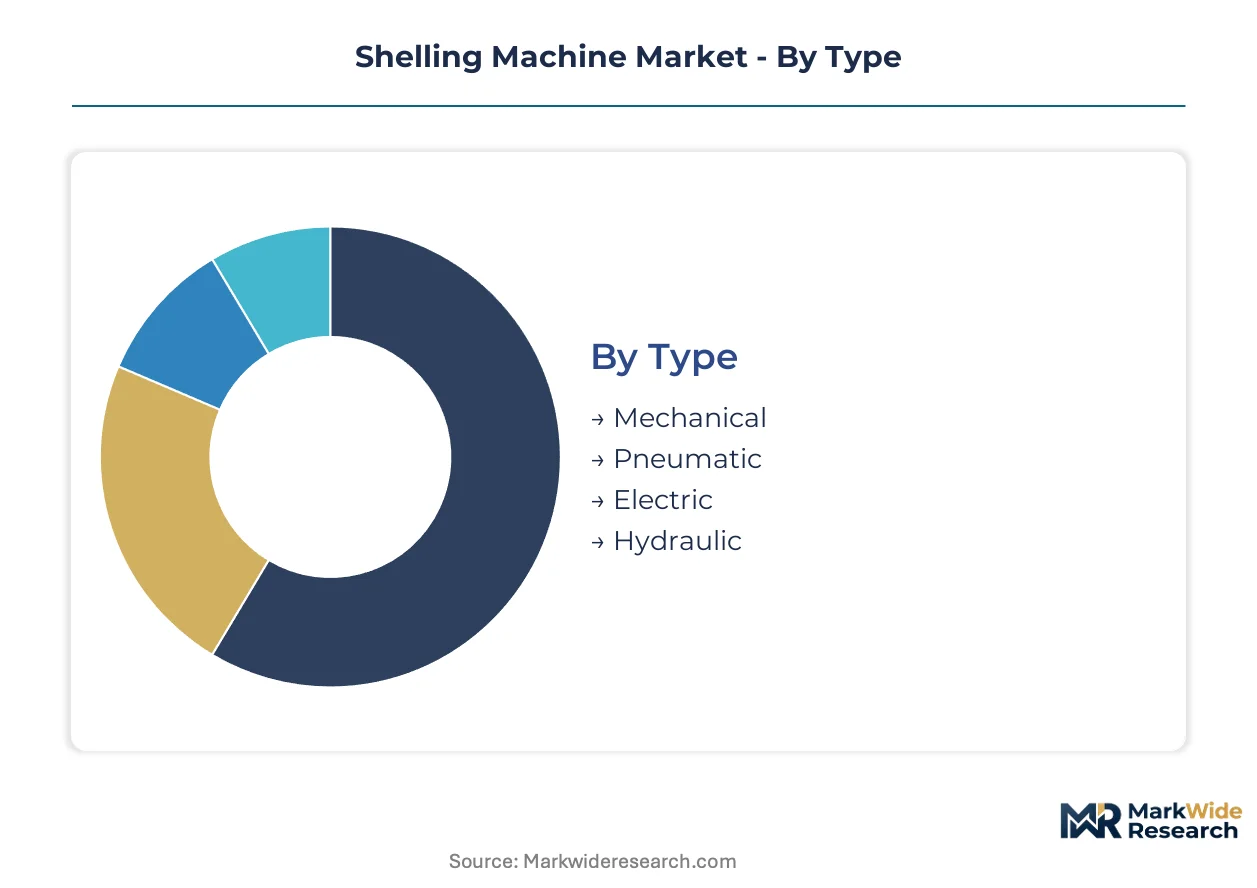
Shelling machine procurement patterns diverge sharply across operational scales and material categories, with equipment specifications calibrated to throughput requirements, kernel fragility, and facility automation levels. Understanding these segment boundaries clarifies why pneumatic systems command premium pricing in almond processing while mechanical units dominate soybean operations in Brazil.
Type:
Equipment type selection tracks the tension between capital efficiency and yield preservation across nut, seed, and grain processing lines.
- Mechanical:Friction and impact-driven rotor systems dominate installed bases due to lower upfront investment and simpler maintenance protocols. Brazilian soybean processors in Mato Grosso favor these units for high-volume operations where kernel damage tolerance permits aggressive throughput configurations.
- Electric:Energy-efficient motor designs align with China's MEE dual carbon directives, expanding procurement among Asian food processors seeking operational cost reduction. These systems integrate variable frequency drives that adjust rotor speed to material moisture content.
- Pneumatic:High-pressure air separation preserves kernel integrity in premium almond and pistachio lines, justifying elevated capital expenditure through yield recovery premiums.
- Hydraulic:Pressure-application systems serve specialized applications in hard-shell nut varieties where mechanical impact risks fracture propagation.
The dominant share belongs to Mechanical, while Electric is closing the gap fastest.
Application:
Material characteristics dictate equipment architecture, with oilseed and tree nut processors prioritizing fundamentally different damage thresholds than fresh fruit operators.
- Nuts:Almond, cashew, and pistachio shelling lines prioritize kernel integrity through controlled-impact designs, with California processors investing in optical sorting integration to maximize USDA premium grade recovery.
- Seeds:Sunflower and pumpkin seed operations balance throughput against hull adhesion variability, with Ukrainian and Russian facilities driving demand for multi-stage dehulling sequences.
- Fruits:Fresh produce shelling concentrates in tropical processing clusters where coconut and palm kernel operations require corrosion-resistant wet-processing configurations.
- Crops:Soybean and legume shelling favors high-capacity continuous-flow designs that minimize labor dependency in Brazilian and Argentinian agricultural belts.
Nuts command the highest equipment expenditure per ton, though Seeds show the steepest expansion trajectory in Eastern European markets.
End User:
Facility type determines automation depth and regulatory compliance burden, with food safety mandates creating divergent procurement specifications across downstream channels.
- Agriculture:On-farm and cooperative shelling operations in Brazil's Paraná state prioritize robust mechanical systems with minimal electronic complexity to reduce field maintenance requirements.
- Food Processing:Commercial facilities face FDA, FSSAI, and EFSA hygiene mandates that specify stainless steel contact surfaces and CIP-compatible architectures, particularly in almond butter and nut ingredient supply chains.
- Packaging:Final-stage shelling for retail-ready products emphasizes gentle handling and optical defect removal, with European snack food manufacturers driving demand for integrated vision systems.
- Manufacturing:Industrial ingredient producers—oil extractors, protein concentrate facilities—accept higher kernel damage rates in exchange for throughput maximization and energy efficiency.
Food Processing absorbs the dominant equipment value, while Agriculture is gaining share fastest through Brazilian mechanization programs.
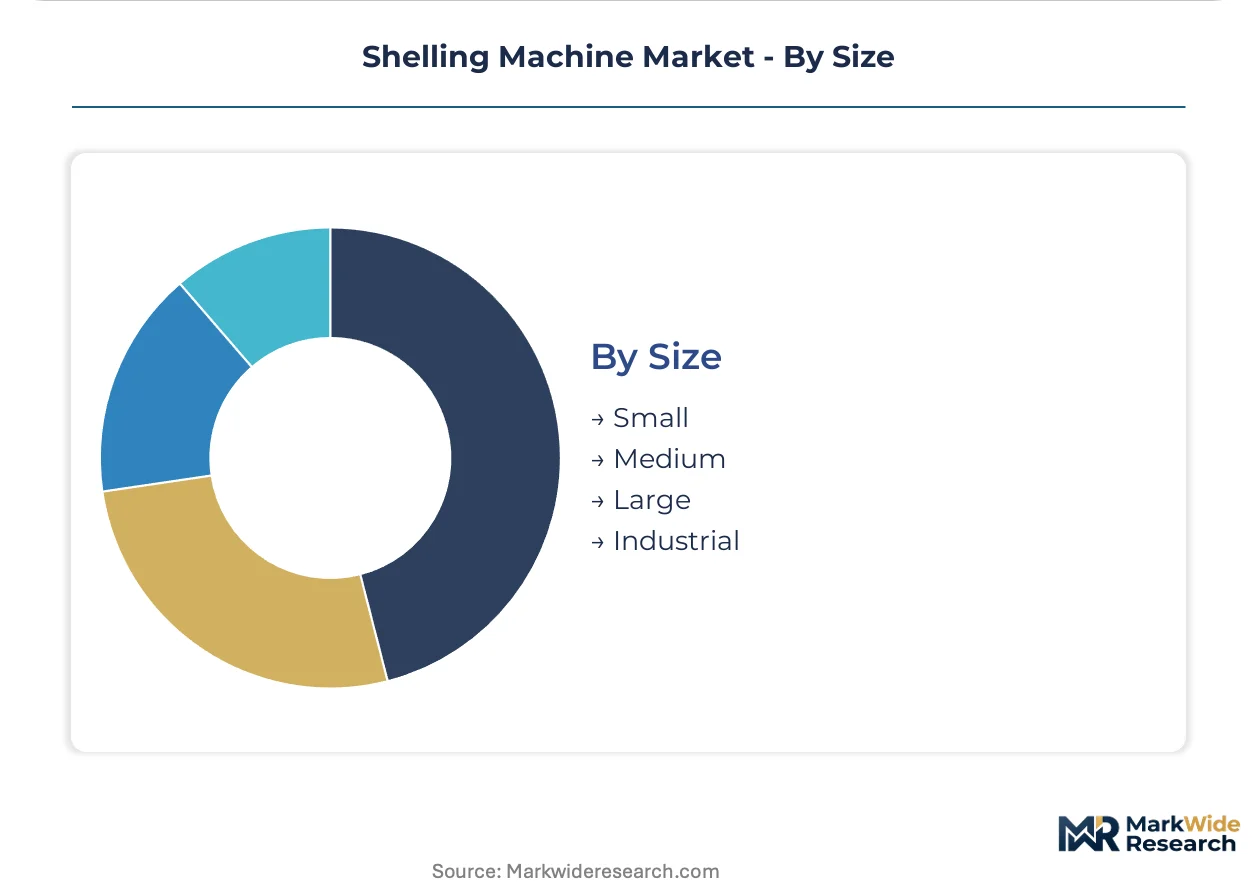
Size:
Scale tier selection reflects facility throughput requirements and capital access constraints, with financing innovation reshaping mid-market procurement patterns.
- Small:Batch-capacity units serve artisanal processors and research facilities, with Indian cashew cooperatives in Kerala deploying these systems for organic certification compliance.
- Medium:Semi-automated lines bridge manual and fully automated operations, attracting Southeast Asian mid-scale processors through emerging equipment leasing models.
- Large:Continuous-flow systems with 10-50 ton hourly capacity anchor commercial nut and oilseed facilities, particularly in California's Central Valley and China's Shandong processing corridor.
- Industrial:Integrated processing complexes with upstream drying and downstream sorting command the highest engineering complexity, with Bühler and Satake dominating this tier through turnkey project execution.
Large-scale configurations hold the dominant position, though Medium units are expanding most quickly through Southeast Asian financing penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in China's Shandong and Jiangsu provinces, with domestic manufacturers supplying Asian food processors and export markets. Brazil's agricultural modernization and India's cashew processing clusters drive regional demand divergence.
China
Shandong Province hosts the densest concentration of shelling equipment fabricators serving domestic and Southeast Asian markets. MEE dual carbon directives mandate energy-efficient motor specifications for equipment manufactured after 2025. Qingdao and Jinan industrial zones export friction-based mechanical systems to Vietnamese rice millers upgrading from manual operations.
Brazil
Mato Grosso and Paraná agricultural operators replace legacy mechanical shellers with continuous-flow systems to reduce post-harvest soybean losses. ANVISA food safety protocols shape stainless steel surface requirements for equipment entering commercial processing facilities. Sorriso and Lucas do Rio Verde processing clusters absorb the highest equipment procurement volumes in South America.
India
Gujarat and Maharashtra cashew cooperatives modernize shelling lines to meet FSSAI hygiene mandates for export-grade kernel production. BIS certification requirements for electrical safety slow import timelines for European pneumatic systems. Kollam and Palanpur processing hubs drive replacement demand as artisanal operators consolidate into commercial facilities.
Germany
REACH substance restrictions and RoHS electrical directives elevate engineering overhead for equipment bound for EU food facilities. EFSA hygiene protocols specify CIP-compatible architectures that Asian manufacturers must adapt for export configurations. Bavarian and North Rhine-Westphalian engineering firms specialize in high-pressure pneumatic components for premium nut processing lines.
United States
California Central Valley almond processors invest in optical sorting integration to maximize USDA premium grade recovery rates. FDA food safety regulations mandate traceable contact surfaces and dust containment systems for commercial facilities. Modesto and Fresno processing clusters represent the highest equipment expenditure per ton in North American tree nut operations.
Shelling Machine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pneumatic valves, high-torque motors, and optical sensors. The vendor base separates into three strategic archetypes: Swiss and Japanese engineering houses with turnkey project capabilities, German specialists in custom milling integrations, and Chinese fabricators scaling standardized mechanical platforms. Competitive moves concentrate on backward integration into motor and control system production, alongside geographic expansion through Southeast Asian distribution partnerships.
Among Swiss-engineered platform providers, Bühler AG anchors the premium system tier through turnkey nut and seed processing line execution. Satake Corporation exemplifies Japanese precision manufacturing dominance across East Asian rice and grain shelling applications. F.H. SCHULE Mühlenbau GmbH represents German custom engineering specialization, occupying a position distinct from standardized equipment competitors through milling integration capabilities.
| Leading Market Players |
|---|
| Bühler AG |
| Satake Corporation |
| F.H. SCHULE Mühlenbau GmbH |
| AGI |
| Bratney Companies |
| TABANLI Machinery |
| Omas Industries |
| Sangati Berga |
| Alvan Blanch Development Company Ltd |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Shandong Province's motor fabrication corridor tightens supplier pricing power for electric shelling systems, while Brazilian agricultural operators absorb cost premiums to secure delivery certainty for soybean belt modernization programs.
Pricing Analysis
MEE dual carbon goals dictate the pricing tier structure across Chinese-manufactured equipment, with energy-efficient motor configurations commanding premiums over legacy mechanical designs. Price differentiation hinges on CE marking compliance for EU-bound exports and stainless steel grade certification for food-contact surfaces. Cost compression in pneumatic component tiers is intensifying because German and Japanese valve suppliers concentrate production capacity. Small-scale Southeast Asian processors exhibit highest price sensitivity, while California almond operators prioritize yield recovery rates over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and select Southeast Asian markets dominates procurement risk calculus for equipment fabricators serving Vietnamese and Indonesian rice millers. Component sourcing draws from China's Jiangsu motor clusters, Germany's pneumatic valve specialists, and Japan's precision bearing manufacturers. Single-source vulnerability concentrates in high-pressure compressor assemblies for premium nut processing lines. Distribution runs through OEM-authorized service networks in developed markets, while third-party industrial distributors capture aftermarket parts flows across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation creates niche opportunities as regional regulatory divergence—China's MEE emissions directives, India's FSSAI hygiene mandates, Brazil's ANVISA protocols—forces platform customization rather than standardization.
For Market Incumbents: Build certification moats around dual-compliance architectures serving both Asian domestic markets and EU export requirements. Deepen backward integration into variable frequency drive production to reduce dependency on Japanese motor controller suppliers. Capture channel control through captive financing subsidiaries addressing Southeast Asian mid-scale processors previously excluded by upfront capital barriers. For New Entrants and Emerging Players: Medium-capacity semi-automated lines for Indian cashew cooperatives in Gujarat and Maharashtra represent the most penetrable entry point, given FSSAI modernization timelines and artisanal operator consolidation trends. Equipment-as-a-service models with pay-per-ton structures bypass capital access constraints among Vietnamese rice millers upgrading from manual operations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform integrators with aftermarket parts and maintenance service contracts attached to initial equipment sales. Long-term viability favors turnkey project execution capabilities spanning shelling, optical sorting, and integrated drying systems. Monitor FSSAI enforcement intensity in Indian export processing clusters as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive supply of variable frequency drives reduces exposure to Japanese controller supplier bottlenecks. |
| Dual-Compliance Platform Architecture | Simultaneous MEE and CE marking compatibility expands addressable markets without configuration duplication. |
| Equipment-as-a-Service Financing Model | Pay-per-ton structures penetrate Southeast Asian mid-scale processors excluded by traditional capital requirements. |
| Optical Sorting Integration Partnership | Vision system alliances with California almond processors maximize USDA premium grade recovery rates. |
| Aftermarket Parts Distribution Expansion | Localized spare parts availability captures Indonesian and Vietnamese channel fragmentation trends. |
Methodological Framework
Operator-level perspectives from plant engineers at Brazilian soybean processing cooperatives, maintenance directors at California almond facilities, and procurement leads at Vietnamese rice milling operations anchored the qualitative base. Secondary validation drew from customs trade data on shelling equipment imports, ANVISA and FSSAI regulatory filings, and SEC disclosures from publicly traded food processing equipment manufacturers. Bottom-up equipment unit economics triangulated against top-down market size estimates derived from agricultural production statistics and processing capacity utilization rates.
Scenario-bracketing framed the analytical approach, with sensitivity analysis applied to MEE enforcement intensity in China, FSSAI compliance timelines in India, and Brazilian agricultural credit availability. Segmentation dimensions modeled include equipment type, application material, facility scale tier, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement cycle acceleration factors, and penetration assumptions for automated systems displacing manual labor. Industry-specific forecast inputs incorporated soybean harvest volume projections and cashew export grade premium differentials.
Macroeconomic conditions sit as an overlay; deviation in Brazilian agricultural credit spreads, nickel and chromium commodity price volatility, or Southeast Asian currency stability would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Meat and Poultry Processing Equipment Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market
Agricultural Processing Equipment
Solar Herbs Dryer Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Global Nut Processing Equipment Market