
 Defeathering Machine Market | 2026-2036
Defeathering Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Defeathering Machine Market Outlook
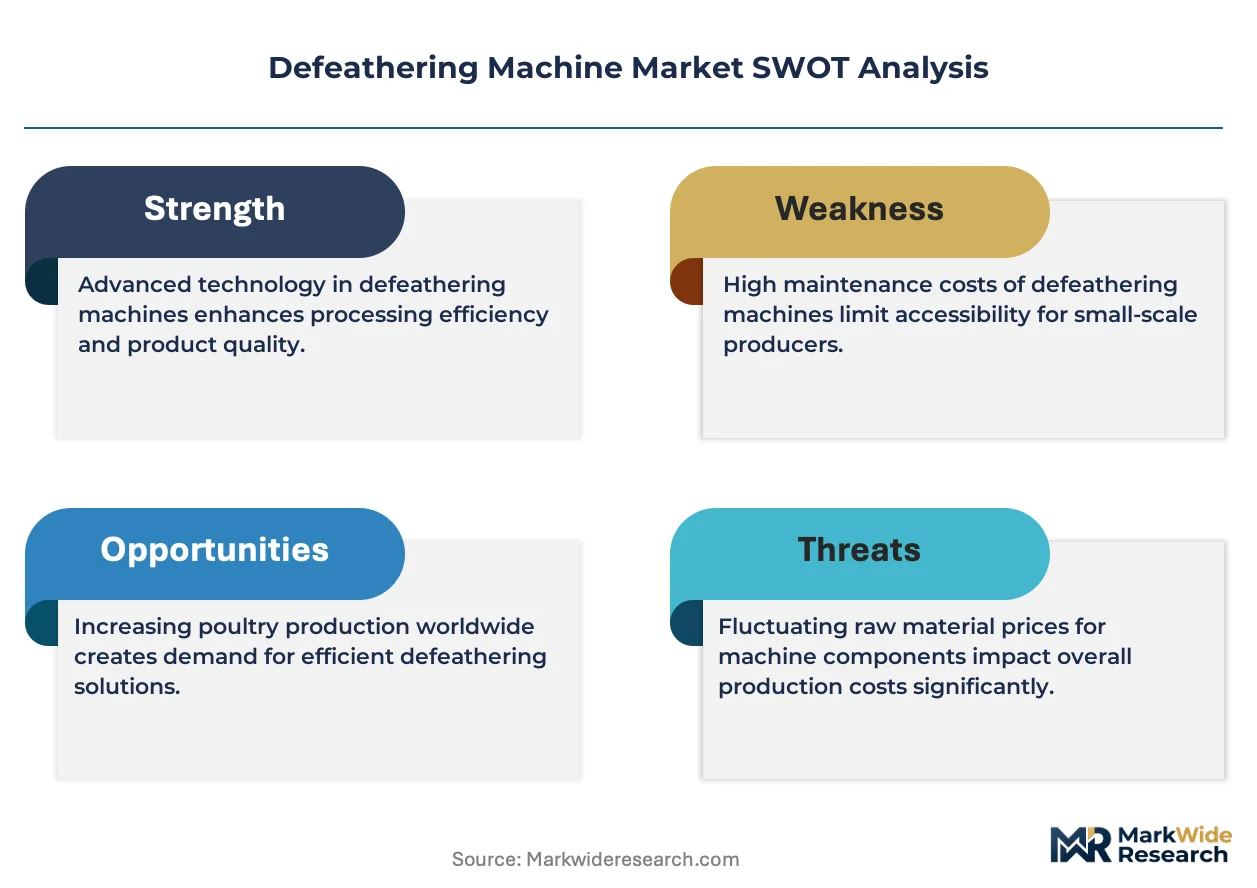
CE marking under the EU Machinery Directive is reorganizing competitive access for defeathering equipment manufacturers seeking placement in European processing facilities. Marel leverages its vertically integrated supply chain to sustain high-volume production of precision-engineered plucking systems. Baader Group anchors its position through deep specialization in poultry processing automation. Meyn Food Processing Technology competes on technology leadership in intelligent line-control integration.
A defeathering machine is mechanical processing equipment designed to remove feathers from slaughtered poultry through rotating rubber fingers or discs that create abrasive contact with carcasses, typically operating at controlled water temperatures and line speeds measured in birds per minute. Its primary industrial purpose is to standardize hygiene outcomes and throughput in high-volume poultry slaughter operations. Automatic and robotic product types command premium positioning as processors prioritize labor reduction and shift consistency across multiple daily production cycles. Pneumatic and hybrid technology segments attract capital allocation where facilities seek energy efficiency alongside mechanical reliability in demanding operating environments.
OSHA workplace safety standards and USDA-FSIS sanitary performance standards govern equipment design and installation protocols in the United States, while EFSA hygiene requirements and CE machinery directives shape product specifications across European member states. These frameworks elevate compliance costs for new entrants but protect incumbent specialists with established certification track records. Stakeholders must monitor evolving automation standards and regional sanitary enforcement intensity when allocating capital across geographic expansion or product development priorities.
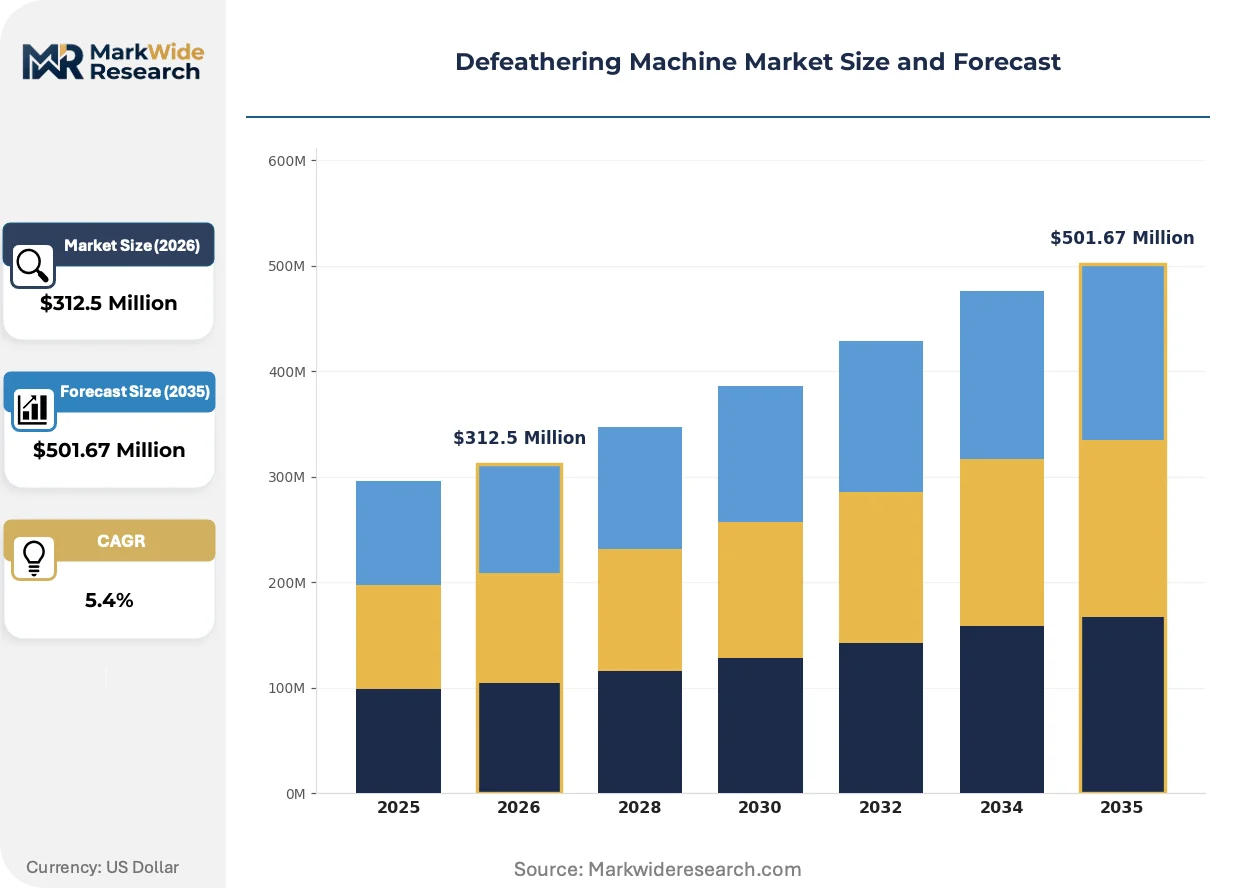
Market Dynamics
Automated defeathering line deployment in Brazil's commercial poultry sector is compressing equipment replacement cycles and forcing suppliers to align with ANVISA sanitary protocols for export-grade processing facilities.
Growth Catalysts
- ANVISA Sanitary Mandates:Brazil's export-grade hygiene requirements are compelling processors to upgrade from manual to automated defeathering systems to maintain market access.
- Rubber Finger Material Advances:New polymer compounds extending abrasive disc lifespan are reducing downtime and maintenance costs in high-throughput environments.
- Line Speed Optimization:Poultry processors operating multiple daily production cycles require consistent throughput measured in birds per minute.
Market Restraints
- Stainless Steel Input Volatility:Equipment fabrication depends on nickel and chromium prices, creating margin pressure for fabricators during commodity spikes.
- CE Marking Compliance Burden:The EU Machinery Directive's documentation and testing requirements extend market entry timelines for non-European manufacturers.
- Water Scarcity in Processing Clusters:Defeathering operations consume substantial water volumes, exposing facilities in drought-prone regions to operational restrictions.
Strategic Opportunities
- Vietnam Poultry Sector Expansion:Southeast Asian processing capacity additions create demand for automated plucking systems as domestic consumption rises.
- Hybrid Pneumatic-Mechanical Convergence:Combining pneumatic actuation with mechanical reliability addresses energy efficiency targets without sacrificing throughput.
- Remote Monitoring Integration:IoT-enabled predictive maintenance modules offer aftermarket revenue streams and strengthen customer lock-in.
Industry Challenges
- Mechatronics Technician Scarcity:Automated line maintenance requires cross-functional skills spanning mechanical, pneumatic, and control systems that training pipelines struggle to produce.
- Legacy Equipment Integration Friction:Retrofitting intelligent controls into existing processing lines demands custom engineering that stretches project timelines and budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defeathering Machine Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Robotic End User: Poultry Processing Plants, Small Scale Farmers, Food Service Industry, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Custom Capacity Technology: Pneumatic, Mechanical, Electrical, Hybrid |
| Companies Covered | Stork Food Processing Equipment (Marel), Baader Group, Meyn Food Processing Technology, Bettcher Industries, Cantrell-Gainco Group, Bayle, Banss, Foodmate, LINCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defeathering Machine Market Strategic Shifts
Equipment manufacturers are converging on sensor-integrated defeathering systems that optimize finger pressure and water temperature in real-time, compressing the gap between mechanical reliability and precision control.
Rotary disc defeathering technology with variable-speed drives is miniaturizing footprint requirements while maintaining throughput. Mid-sized processors in Poland and Thailand are adopting these compact units to retrofit existing facilities without line reconfiguration. The technology is miniaturizing access barriers for capital-constrained operations previously excluded from automation.
CE marking under the EU Machinery Directive is tightening documentation requirements for safety interlocks and emergency stop systems. European integrators now demand certified sub-assemblies to streamline their own compliance audits. This regulatory layer most affects pneumatic actuator suppliers seeking placement in Dutch and German processing facilities.
Buyer procurement committees are consolidating vendor relationships around full-line integrators capable of single-source accountability for hygiene outcomes. Independent equipment specialists face exclusion from large tender processes unless they affiliate with system integrators. This concentration pattern is most visible in Brazilian export-oriented plants where ANVISA audit risk drives preference for turnkey solutions.
Defeathering Machine Market Segmentation
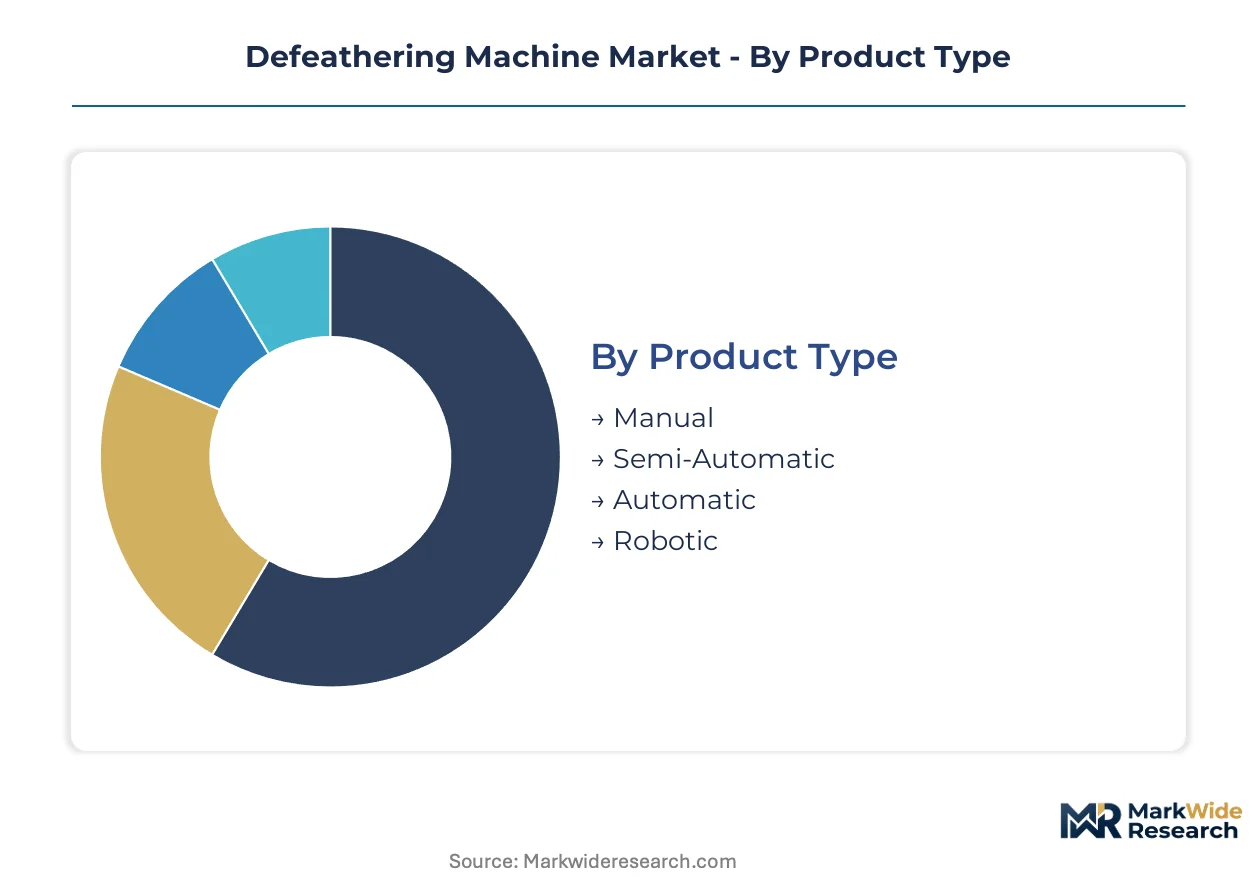
Segmentation in defeathering equipment reveals distinct procurement patterns between export-oriented processors seeking ANVISA-certified automation and domestic operators prioritizing capital efficiency. Equipment specification varies sharply across these boundaries, with technology choice and capacity scaling directly tied to regulatory exposure and volume commitments.
Product Type:
Domestic Brazilian processors favor manual and semi-automatic units for internal market supply, while export-grade facilities mandate automatic and robotic systems to satisfy ANVISA hygiene audits. This geographic-regulatory split shapes supplier R&D allocation and certification investments.
- Manual:Hand-operated plucking devices with stationary rubber finger arrays require operator labor for carcass rotation. Small-scale farmers in Brazil's interior states deploy these units for local market supply where capital constraints outweigh throughput needs.
- Semi-Automatic:Motorized drum systems with partial automation reduce labor intensity while preserving operator oversight. Mid-sized processors in Thailand and Poland retrofit these into existing facilities to bridge manual operations and full automation.
- Automatic:Continuous-flow rotary systems with variable-speed drives and integrated water temperature controls process birds at consistent line speeds. Export-oriented Brazilian plants under ANVISA jurisdiction deploy these systems to standardize hygiene outcomes across multiple daily production cycles.
- Robotic:Vision-guided articulated arms with adaptive finger pressure and real-time carcass assessment optimize plucking precision for premium-grade export carcasses. Robotic systems command premium positioning as European processors integrate intelligent line-control architectures under CE marking requirements.
Automatic systems command the established base. The steepest expansion runs through Robotic configurations as labor costs and audit precision intensify.
End User:
Procurement scale and compliance burden separate these segments, with poultry processing plants absorbing the bulk of capital deployment while research institutions drive specification innovation for next-generation equipment.
- Poultry Processing Plants:High-volume slaughter facilities operating USDA-FSIS or EFSA-governed lines require stainless-steel construction, CIP compatibility, and documented sanitary performance. Brazilian export plants under ANVISA protocols represent the most demanding specification tier for automated defeathering integration.
- Small Scale Farmers:Low-capacity units with simplified maintenance requirements serve dispersed operations in Vietnam and Indonesia where technical service networks remain thin. These buyers prioritize equipment durability over throughput optimization.
- Food Service Industry:Compact tabletop or floor-standing units for central kitchens and catering operations process limited volumes with space constraints. European hospitality chains specify CE-marked equipment with enhanced safety interlocks.
- Research Institutions:Experimental processing lines for breed development and processing methodology studies require configurable parameters and data acquisition capabilities. Universities in the Netherlands and Brazil collaborate with equipment manufacturers on next-generation plucking dynamics.
Poultry Processing Plants absorb the capital concentration. Research Institutions are climbing the fastest as public-private partnerships expand processing innovation funding.
Capacity:
Facility scale determines equipment architecture, with large-scale rotary systems dominating export processing while custom configurations address specialty breed and organic certification requirements.
- Small Scale:Batch-processing units handling under 500 birds per hour serve farm-gate slaughter and local market distribution. These systems minimize water and energy consumption for operations outside grid-intensive processing clusters.
- Medium Scale:Continuous-flow equipment processing 500-2,000 birds per hour balances throughput with footprint constraints. Polish and Thai processors favor these units for retrofit installations without line reconfiguration.
- Large Scale:Integrated rotary systems exceeding 2,000 birds per hour with automated carcass transfer and water reclamation serve integrated poultry conglomerates. Brazilian export facilities deploy these systems to meet ANVISA throughput and traceability mandates.
- Custom Capacity:Engineered-to-order lines for specialty breeds, organic certification requirements, or integration with existing building constraints. European premium poultry processors specify these configurations for slow-growth breed processing under EFSA welfare guidelines.
Large Scale configurations hold the volume base. Custom Capacity is gaining share fastest as differentiation requirements fragment standard equipment demand.
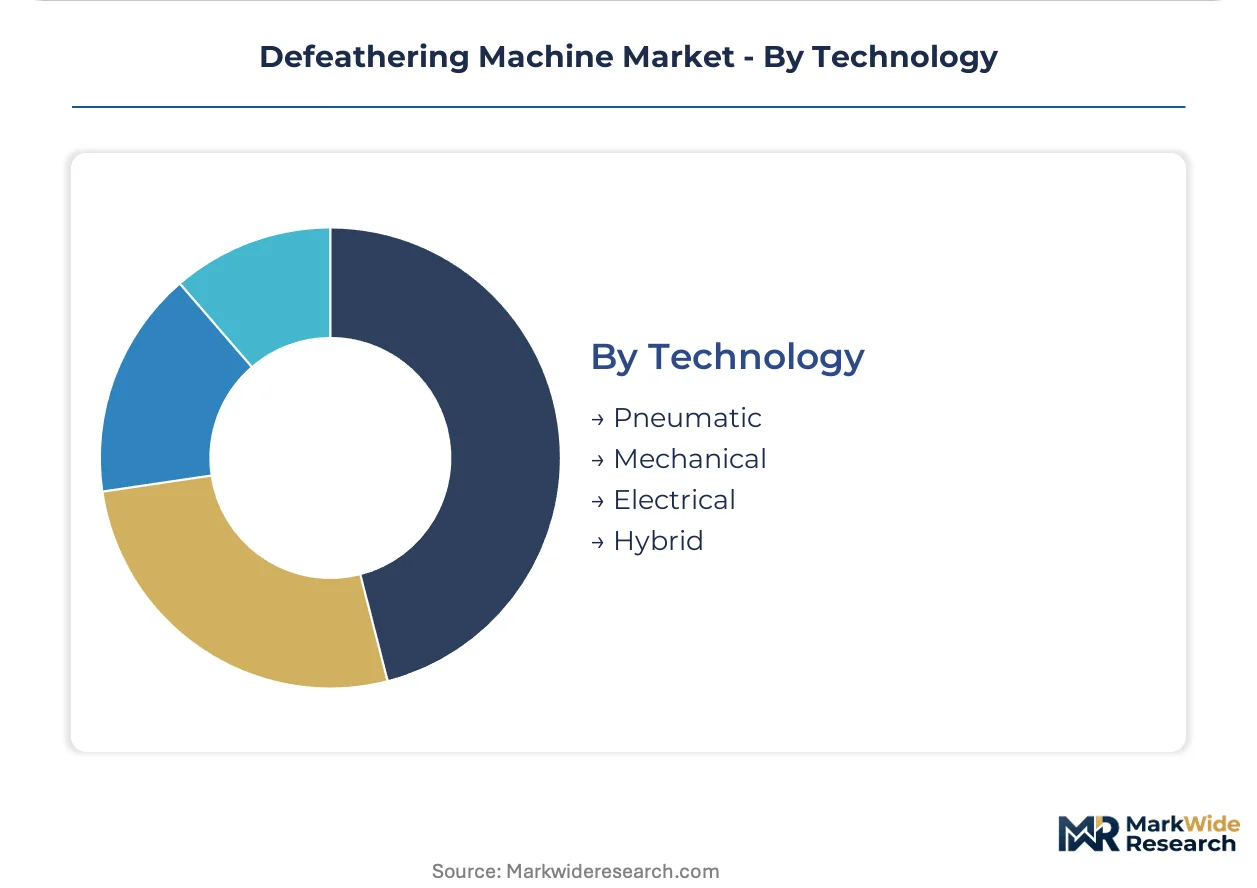
Technology:
Energy efficiency targets and mechanical reliability tradeoffs drive technology selection, with hybrid architectures emerging as the compromise solution for facilities facing dual constraints.
- Pneumatic:Compressed air actuation delivers precise finger pressure control with reduced electrical component exposure to wet environments. Dutch and German processors specify pneumatic sub-assemblies to satisfy CE marking documentation requirements for safety-critical systems.
- Mechanical:Direct-drive motor systems with fixed gear ratios provide proven reliability and simplified maintenance for high-volume operations. Brazilian export plants favor mechanical systems for their tolerance of variable voltage conditions in processing clusters.
- Electrical:Servo-motor precision enables real-time speed and pressure adjustment with integrated feedback loops. These systems support IoT-enabled predictive maintenance modules that strengthen vendor lock-in through aftermarket revenue streams.
- Hybrid:Combined pneumatic-mechanical architectures balance energy efficiency with operational reliability. Southeast Asian processors in Vietnam and Indonesia are adopting hybrid systems as electricity costs rise and water scarcity intensifies operational efficiency pressures.
Mechanical technology anchors the installed base. Hybrid configurations are expanding most quickly as energy and water constraints reshape operating economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA export-grade protocols are compressing equipment replacement cycles across Brazil's commercial poultry belt, while EFSA hygiene mandates and CE marking requirements reshape procurement specifications in European processing facilities. These regulatory frameworks are creating divergent capital allocation patterns between export-oriented automation and domestic-market efficiency plays.
Brazil
Integrated poultry conglomerates in São Paulo and Paraná are deploying large-scale rotary defeathering systems to satisfy ANVISA traceability mandates for EU and Chinese export markets. The country's national health surveillance agency enforces sanitary performance standards that disqualify manual processing lines from export certification. Santa Catarina's processing cluster around Chapecó is expanding automated capacity to capture premium-grade carcass demand from Middle Eastern buyers.
Germany
Dutch and German processors specify pneumatic sub-assemblies with CE-marked safety interlocks to satisfy Machinery Directive documentation audits. The country's federal motor transport authority influences equipment transport standards, while EFSA welfare guidelines shape slow-growth breed processing configurations. North Rhine-Westphalia's Ruhr processing belt is retrofitting hybrid pneumatic-mechanical systems to balance energy efficiency with throughput reliability.
United States
USDA-FSIS sanitary performance standards govern stainless-steel construction and CIP compatibility in high-volume slaughter facilities across the Southeast poultry belt. OSHA workplace safety protocols mandate emergency stop systems and interlock documentation that elevate compliance costs for equipment entrants. Georgia's Gainesville processing cluster and Alabama's Cullman corridor are integrating IoT-enabled predictive maintenance modules to compress downtime across multiple daily production cycles.
Vietnam
Domestic consumption growth and processing capacity additions are driving demand for medium-scale continuous-flow equipment in the Mekong Delta and Red River Delta corridors. The country's food safety authority is tightening hygiene enforcement, nudging processors toward automated systems previously reserved for export-oriented facilities. Ho Chi Minh City's industrial zones are attracting hybrid technology deployments as electricity costs rise and water scarcity intensifies operational efficiency pressures.
Poland
Mid-sized processors in Greater Poland and Silesia are adopting compact rotary disc units with variable-speed drives to retrofit existing facilities without line reconfiguration. EU Machinery Directive CE marking requirements filter equipment procurement toward certified European integrators. Poznań's agri-food technology corridor is emerging as a testbed for sensor-integrated defeathering systems that optimize finger pressure in real-time.
Defeathering Machine Market Competitive Environment
Player mix skews toward vertically integrated full-line integrators and specialized component fabricators competing across distinct specification tiers. Market structure concentrates procurement authority around turnkey solution providers capable of single-source accountability for hygiene outcomes. Three archetypes dominate: European precision-engineering specialists with CE marking certification track records, North American stainless-steel fabricators serving USDA-governed facilities, and Asian cost-optimized producers capturing domestic-market volume. Competitive moves center on strategic partnerships with system integrators and geographic expansion through distributor networks rather than direct asset acquisition.
Within the European specialist tier, Marel and Baader Group exemplify vertically integrated supply chain control, while Meyn Food Processing Technology occupies a position emphasizing intelligent line-control integration. Among North American fabricators, Bettcher Industries and Cantrell-Gainco Group represent the stainless-steel construction archetype serving high-compliance processing environments. These named entities anchor competitive dynamics without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Stork Food Processing Equipment (Marel) |
| Baader Group |
| Meyn Food Processing Technology |
| Bettcher Industries |
| Cantrell-Gainco Group |
| Bayle |
| Banss |
| Foodmate |
| LINCO |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation simultaneously, as European integrators demand certified sub-assemblies that compress procurement options while commanding premium positioning for compliant equipment tiers.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with CE-marked and ANVISA-certified systems commanding substantial premiums over uncertified alternatives. Pricing stratifies across robotic, automatic, semi-automatic, and manual configurations, with labor cost arbitrage and audit precision driving buyers toward higher tiers despite capital intensity. Cost compression in mid-scale equipment is intensifying because Southeast Asian fabricators are scaling stainless-steel production capabilities. Small-scale farmers exhibit highest price sensitivity, while Brazilian export-oriented processors prioritize compliance over capital outlay.
Supply Chain Analysis
Inventory lead times for precision-engineered rubber finger arrays and servo-motor assemblies have extended due to polymer compound customization requirements. Supply concentrates in Germany, Denmark, and the Netherlands for pneumatic sub-assemblies, while China and India anchor stainless-steel fabrication for cost-optimized tiers. Equipment manufacturing draws from nickel, chromium, and specialized polymer feedstocks vulnerable to commodity volatility. Single-source vulnerability runs through European precision-actuator suppliers serving CE-marking-dependent integrators. Distribution runs through authorized system integrators capable of turnkey installation and ANVISA audit support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional mechatronics expertise represents the critical bottleneck constraining both equipment innovation and aftermarket service capacity, with training pipelines failing to match automated line deployment velocity across Brazil and Southeast Asia.
For Market Incumbents: Shield market position by deepening captive production of precision rubber finger compounds and sensor-integrated control modules. Consolidate channel control through exclusive distribution agreements with ANVISA-certified system integrators in São Paulo and Paraná processing clusters. Prioritize certification maintenance investments as emerging Asian fabricators challenge mid-tier positioning. For New Entrants and Emerging Players: Lead with compact rotary disc configurations targeting Polish and Thai mid-sized processors seeking retrofit compatibility without line reconfiguration. Vietnam's Mekong Delta corridor offers the most penetrable geography as domestic consumption growth outpaces local fabrication capacity. Position through hybrid pneumatic-mechanical architectures addressing electricity cost pressures and water scarcity constraints simultaneously. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic and sensor-integrated product tiers as software development and precision-actuator sourcing dominate cost structures. Long-term viability favors acquisition targets with established CE marking track records and embedded relationships with European full-line integrators. Monitor ANVISA enforcement intensity as the critical signal for Brazilian equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Finger Compounds | Captive polymer formulation secures supply continuity for high-abrasion disc arrays serving ANVISA-certified lines. |
| CE Marking Pathway Investment | Machinery Directive compliance documentation opens placement in Dutch and German processing facility upgrades. |
| IoT Predictive Maintenance Module Launch | Sensor-integrated aftermarket revenue streams strengthen vendor lock-in across Brazilian export-oriented plants. |
| Joint Venture with Vietnamese System Integrator | Local assembly capability addresses Mekong Delta demand while navigating electricity cost and water scarcity pressures. |
| Hybrid Technology Platform Standardization | Pneumatic-mechanical convergence targets energy efficiency mandates without sacrificing throughput reliability in Southeast Asia. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing poultry processing plant maintenance directors, OEM procurement teams at full-line integrators, aftermarket service heads, and regulatory compliance officers at ANVISA and EFSA. Secondary validation drew from equipment certification databases, customs trade records for stainless-steel processing machinery, SEC filings of publicly traded food technology conglomerates, and ANVISA sanitary protocol documentation. Bottom-up unit economics and top-down sectoral demand patterns were triangulated to anchor volume and value estimates.
Across the projection horizon, analytical frameworks modeled segmentation dimensions including product type tier, end-user scale category, capacity throughput band, and technology architecture. CAGRs were derived from equipment replacement cycle analysis, regulatory enforcement trajectory assessment, and regional processing capacity expansion pipelines. Forecast inputs incorporated rubber finger material advance curves, water reclamation technology penetration, and mechatronics technician supply constraints.
Forecasts assume regulatory continuity in ANVISA sanitary protocols, EU Machinery Directive CE marking requirements, and USDA-FSIS performance standards; material policy shifts would require re-modeling. Stainless-steel commodity volatility and water scarcity enforcement intensity represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
Feed Screw Barrel Market
Agricultural Processing Equipment
Japan Agricultural Shredder Machine Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Color Sorter Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Global Egg Processing Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Dal Mill Machine Market
Agricultural Processing Equipment
Rice Polishing Machines Market