
 Seed Processing Equipment Market | 2026-2036
Seed Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Processing Equipment Market Outlook
European equipment manufacturers is rebalancing capacity toward optical and air-flow systems as farmers demand higher purity thresholds. Bühler AG leverages its Swiss engineering heritage to dominate high-capacity cleaning lines for commodity grains. Satake Corporation anchors Asian supply networks with rice-specialized grading technology. PETKUS Technologie GmbH differentiates through modular treating equipment that integrates chemical coating and drying in single-pass configurations.
Seed processing equipment encompasses machinery engineered to clean, grade, sort, treat, and dry seeds to commercial viability standards, with optical sorters achieving defect detection thresholds below 0.1% contamination rates. These systems enable seed companies and commercial farmers to meet certification requirements for germination uniformity, genetic purity, and phytosanitary compliance before field deployment. Cleaning equipment occupies the largest installed base across commodity grain operations where throughput volume governs equipment selection. Optical technology represents the fastest-expanding segment as vegetable seed producers prioritize phenotype consistency and labor reduction. Treating equipment commands premium margins due to integrated chemical application systems that reduce handling losses and regulatory exposure.
The EPA regulates chemical seed treatment formulations and application rates in the United States, while the EU Green Deal and F-Gas Regulation constrain fumigation-based processing methods across European facilities. India's FSSAI and CDSCO impose parallel phytosanitary and quality standards on imported seed processing lines, shaping vendor certification requirements. Stakeholders must monitor evolving chemical registration timelines and optical detection standard upgrades to align capital deployment with compliance windows.
Market Dynamics
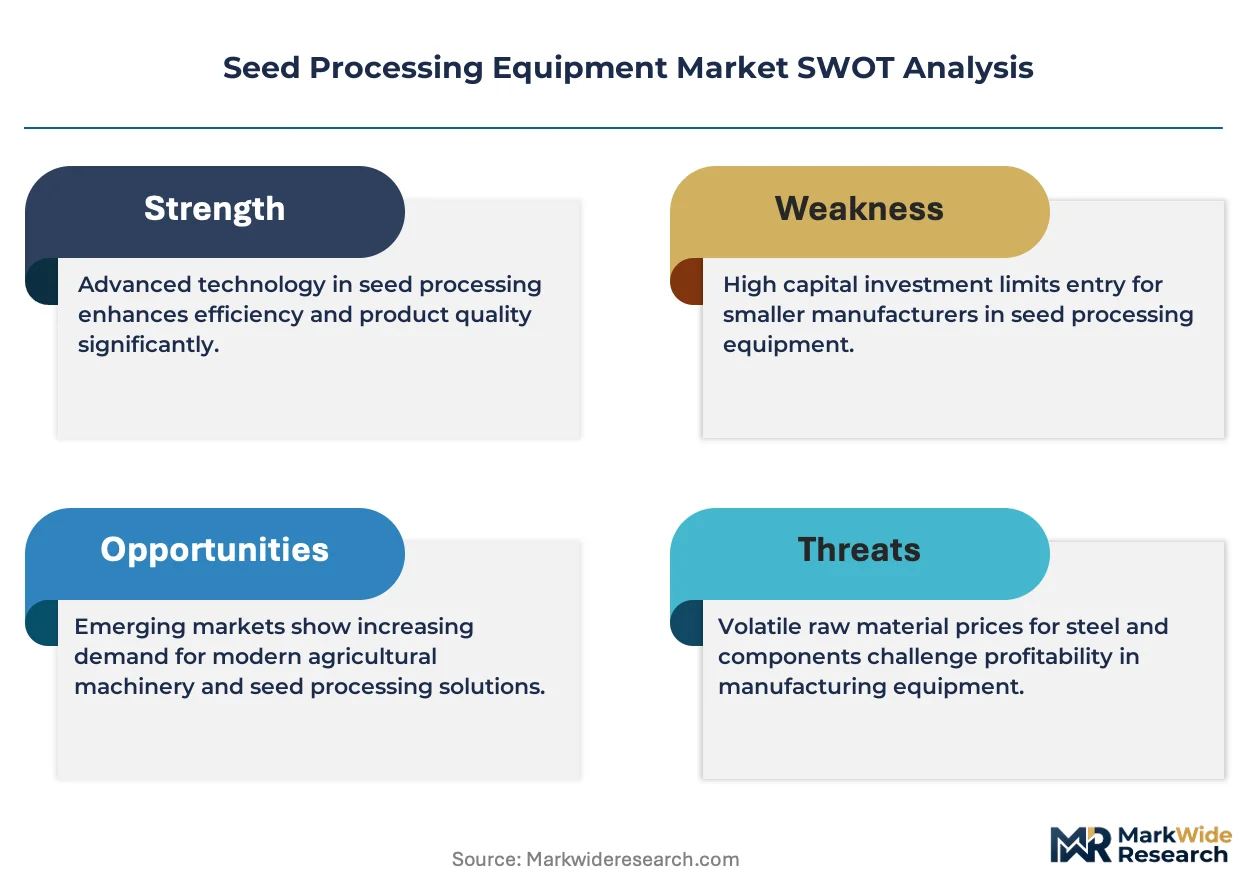
Optical sorting technology is compressing equipment replacement cycles as vegetable seed producers demand sub-0.1% contamination thresholds, forcing capital allocation toward vision-based systems and away from legacy mechanical separators.
Growth Catalysts
- Precision Agriculture Infrastructure:Commercial farming operations in the United States are scaling automated seed treatment lines to meet identity-preserved certification standards for premium grain exports.
- EU Green Deal Compliance:The F-Gas Regulation is accelerating facility upgrades across Germany as fumigation-based processing methods face phase-down timelines.
- Optical Detection Standards:Near-infrared spectroscopy integration is enabling real-time genetic purity verification that manual grading cannot achieve.
Market Restraints
- Stainless Steel Input Volatility:Equipment fabrication costs fluctuate with nickel and chromium price swings, compressing margin buffers for mid-cap manufacturers.
- Supply Concentration Risk:High-resolution camera modules for optical sorters depend on concentrated sensor fabrication in East Asian supply corridors.
- REACH Chemical Registration:Seed treatment formulation approvals face extended timeline uncertainty, delaying treating equipment deployment decisions.
Strategic Opportunities
- India Processing Modernization:CDSCO and FSSAI quality enforcement is creating first-mover advantage for vendors offering integrated cleaning-treating-drying lines.
- Carbon-Neutral Treatment Systems:The EU Green Deal's carbon border adjustment mechanism rewards equipment with energy-recovery drying modules.
- Blockchain-Enabled Traceability:Convergence of optical sorting data with distributed ledger systems is opening premium pricing corridors for certified seed lots.
Industry Challenges
- Vision Systems Integration:Retrofitting optical sorters into legacy mechanical cleaning lines requires specialized automation engineering talent that remains scarce.
- Phytosanitary Certification Timelines:Export equipment approvals from India's DGFT and CDSCO create order-to-delivery gaps that strain working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Processing Equipment Market |
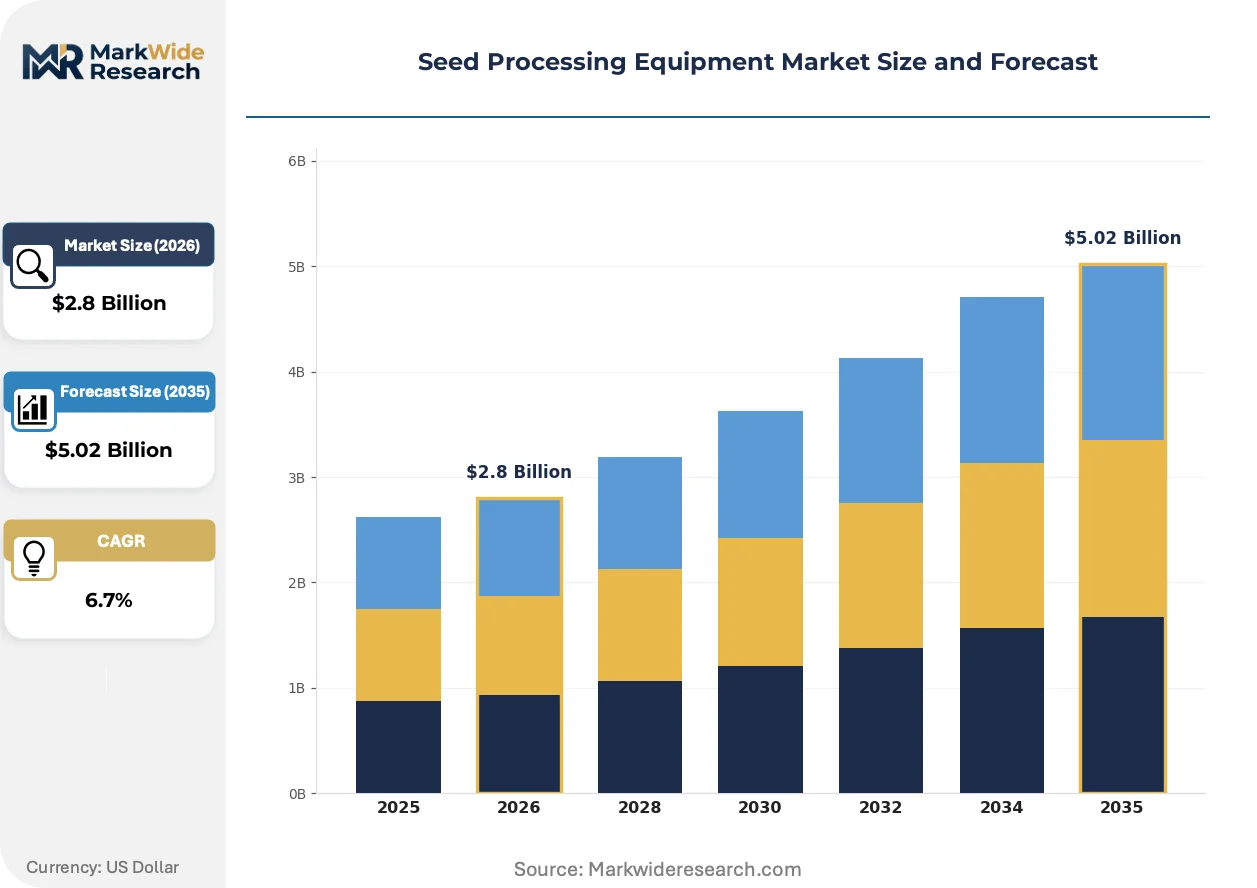
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Equipment, Grading Equipment, Sorting Equipment, Treating Equipment End Use Industry: Agriculture, Horticulture, Commercial Farming, Research Institutions Technology: Mechanical, Optical, Air-Flow, Chemical Capacity: Small Scale, Medium Scale, Large Scale, Customizable |
| Companies Covered | Westrup A/S, Alvan Blanch Development Company, Bühler AG, Agrosaw, AGCO Corporation, Cimbria A/S, Satake Corporation, Incotec Group BV, PETKUS Technologie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Processing Equipment Market Strategic Shifts
Equipment architecture is converging around single-pass processing configurations that compress footprint and handling losses. Vendors are unifying chemical application, coating, and drying stages into continuous-flow systems that reduce labor touchpoints.
Hyperspectral imaging is unifying defect detection and genetic purity verification into unified optical platforms. Vegetable seed producers in the Netherlands and California are adopting these systems at replacement-cycle pace. The technology is unifying what previously required separate mechanical and laboratory stages, compressing capital deployment timelines for premium corridors.
The EPA's revised chemical seed treatment application standards are tightening drift and containment requirements. Equipment buyers in the United States now specify enclosed treating systems with negative-pressure enclosures and automated clean-in-place protocols. Corn and soybean seed operations face the steepest retrofit obligations as existing open-treatment lines fall out of compliance.
Service contracting is displacing outright equipment ownership among mid-scale seed cooperatives. Leasing arrangements with bundled maintenance and software updates are gaining share in Germany and the United States. Vegetable seed clusters in Spain and Italy show the fastest uptake as seasonal volume volatility makes fixed-asset ownership less attractive.
Seed Processing Equipment Market Segmentation
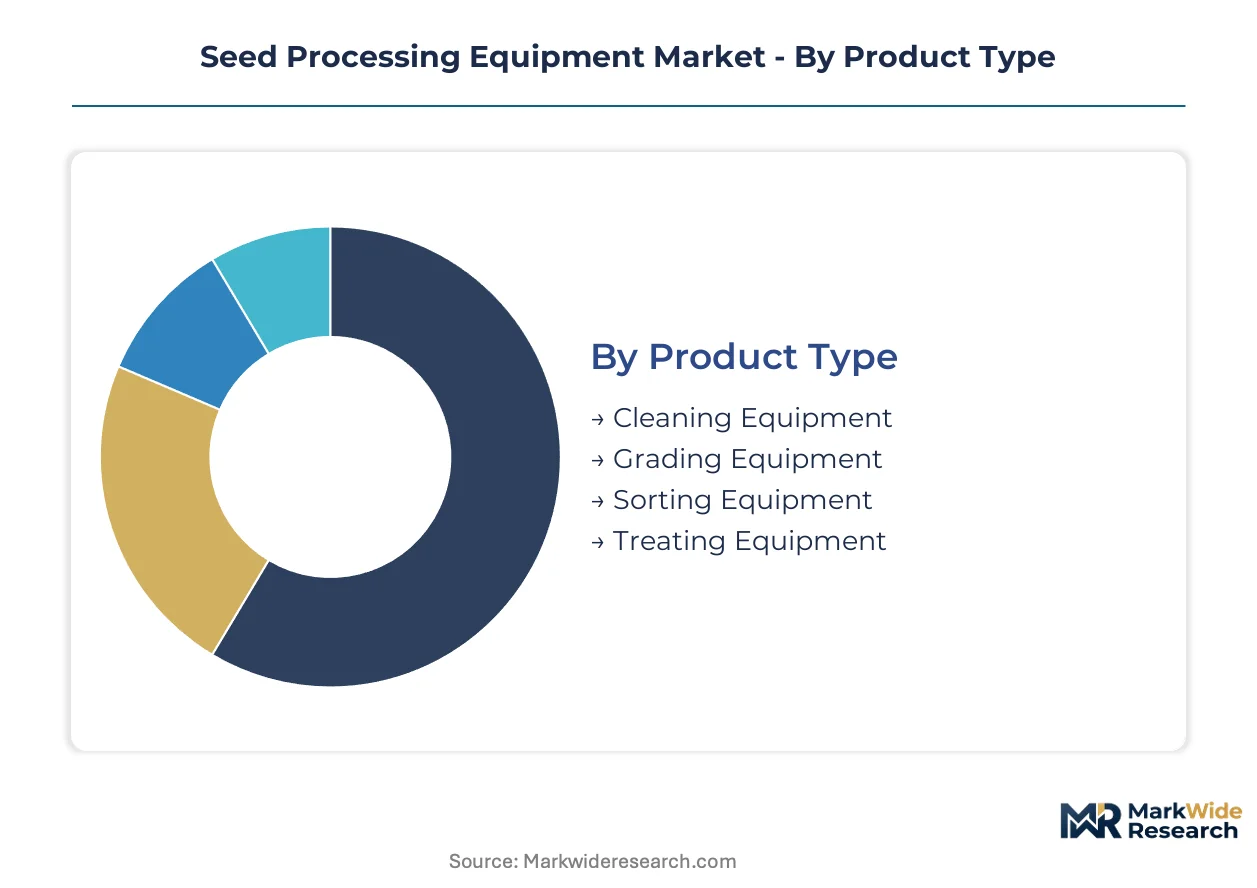
Equipment buyers align capital deployment with specific operational requirements across product function, end-use intensity, and throughput scale. Segmentation reveals where replacement cycles concentrate and which technology transitions command premium pricing.
Product Type:
Upgrade cycles vary sharply by equipment function, with optical and treating systems driving the fastest replacement timelines as purity thresholds tighten.
- Cleaning Equipment:Air-screen separators and gravity tables remove foreign matter and immature seeds through mechanical separation. Commodity grain operations in the United States deploy high-capacity cleaning lines to meet export certification standards for identity-preserved soybeans and corn.
- Sorting Equipment:Optical sorters deploy near-infrared spectroscopy and hyperspectral imaging to detect defects and verify genetic purity. Vegetable seed producers in the Netherlands and California are replacing mechanical graders with vision-based systems to achieve sub-0.1% contamination thresholds.
- Grading Equipment:Sieve-based and dimensional sorters classify seeds by size, shape, and density for uniform planting performance. Rice-specialized grading lines anchor installed bases across Asian processing corridors.
- Treating Equipment:Integrated chemical application, coating, and drying systems reduce handling losses and regulatory exposure. Enclosed treating configurations with negative-pressure enclosures are displacing open-treatment lines under EPA revised drift standards.
Cleaning Equipment sits at the top of the volume ranking, with Sorting Equipment climbing the fastest as optical detection standards proliferate.
End Use Industry:
Capital intensity and equipment specification diverge sharply across end-use sectors, with commercial farming operations demanding integrated single-pass configurations.
- Commercial Farming:Large-scale operations deploy automated seed treatment lines with bundled cleaning, treating, and drying stages. Identity-preserved certification requirements in Germany and the United States are accelerating specification of enclosed chemical application systems.
- Agriculture:Broadacre grain producers prioritize throughput volume and stainless steel durability for commodity seed conditioning. Nickel price volatility directly compresses margin buffers for mid-cap equipment purchases in this segment.
- Horticulture:Vegetable and flower seed producers demand phenotype consistency and labor reduction through optical grading platforms. Hyperspectral imaging adoption concentrates in Netherlands greenhouse clusters and California Central Valley operations.
- Research Institutions:Precision breeding programs require small-batch flexibility and genetic purity verification beyond commercial thresholds. Modular treating equipment with single-pass configuration serves germplasm conservation and varietal development workflows.
Commercial Farming captures the largest equipment revenue share, with Horticulture gaining share fastest as premium vegetable seed corridors expand optical system deployment.
Technology:
Technology selection determines capital recovery timelines, with mechanical systems facing displacement as optical and air-flow methods achieve superior purity at comparable throughput.
- Optical:Vision-based platforms unify defect detection and genetic purity verification into unified processing stages. Real-time near-infrared spectroscopy integration enables verification that manual grading cannot achieve.
- Mechanical:Air-screen separators, gravity tables, and sieve graders retain installed base dominance in commodity grain corridors where capital constraints limit upgrade velocity.
- Air-Flow:Pneumatic separation systems remove lightweight contaminants and chaff with lower energy intensity than mechanical alternatives. European manufacturers are rebalancing capacity toward these configurations as farmers demand higher purity thresholds.
- Chemical:Seed treatment application systems integrate coating, drying, and containment functions for phytosanitary compliance. REACH chemical registration timeline uncertainty delays treating equipment deployment decisions.
Mechanical technology retains the largest installed base, with Optical expanding most quickly as vegetable seed producers compress replacement cycles.
Capacity:
Scale selection reflects volume volatility and asset utilization strategy, with mid-scale cooperatives shifting toward service contracting to reduce fixed-asset exposure.
- Large Scale:Continuous-flow systems process thousands of metric tons annually for commodity export operations. Identity-preserved certification standards in the United States and Germany drive specification of integrated cleaning-treating-drying lines.
- Customizable:Modular architecture enables reconfiguration across crop types and seasonal volume swings. Leasing arrangements with bundled maintenance are gaining share among vegetable seed clusters in Spain and Italy.
- Medium Scale:Batch processing configurations serve regional seed cooperatives with variable throughput requirements. Service contracting is displacing outright ownership as seasonal volatility makes fixed-asset ownership less attractive.
- Small Scale:Compact units serve research institutions and specialty seed producers with low-volume, high-purity requirements. Blockchain-enabled traceability integration opens premium pricing corridors for certified seed lots in this segment.
Large Scale dominates capital deployment value, with Customizable showing the steepest expansion trajectory as modular architecture reduces reconfiguration downtime.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering heritage contrasts with India's infrastructure buildout pace, yet both drive equipment specification toward integrated single-pass configurations. The United States anchors commercial farming automation, while China scales domestic optical sorting capacity. Japan and the Netherlands concentrate high-value vegetable seed processing corridors.
United States
Commercial farming operations deploy automated seed treatment lines to meet identity-preserved certification standards for premium grain exports. EPA revised drift standards mandate enclosed chemical application systems with negative-pressure enclosures. Corn and soybean seed clusters across Iowa and Illinois face steep retrofit obligations as open-treatment lines fall out of compliance.
Germany
F-Gas Regulation phase-down timelines accelerate facility upgrades toward air-flow and optical systems that eliminate fumigation-based processing. EU Green Deal carbon border adjustment mechanisms reward equipment with energy-recovery drying modules. Bavarian equipment manufacturers rebalance capacity toward higher purity threshold configurations demanded by domestic farmers.
China
Domestic precision agriculture infrastructure expansion drives demand for optical sorting technology displacing legacy mechanical separators. MIIT industrial upgrading programs support domestic fabrication of high-resolution camera modules for vision-based systems. Yangtze River Delta processing corridors concentrate vegetable seed grading capacity for export markets.
India
CDSCO and FSSAI quality enforcement creates first-mover advantage for vendors offering integrated cleaning-treating-drying lines. DGFT export equipment approval timelines strain working capital cycles for capital goods procurement. Maharashtra and Gujarat seed cooperatives shift toward service contracting as seasonal volume volatility reduces fixed-asset ownership attractiveness.
Netherlands
Vegetable seed producers adopt hyperspectral imaging platforms to achieve phenotype consistency and labor reduction in greenhouse clusters. REACH chemical registration timeline uncertainty delays treating equipment deployment decisions for export-oriented operations. Wageningen corridor research institutions drive small-batch precision breeding equipment specifications beyond commercial thresholds.
Seed Processing Equipment Market Competitive Environment
Swiss and German producers anchor the premium-tier engineering segment; Danish specialists hold mid-scale modular configurations. The vendor base organizes around three strategic archetypes: precision-engineering heritage houses, rice-specialized Asian fabricators, and modular treating system integrators. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing agreements for optical detection platforms.
Within the precision-engineering tier, Bühler AG and PETKUS Technologie GmbH exemplify Swiss and German heritage positioning. Satake Corporation anchors Asian supply networks. These three names represent distinct geographic and specialization vectors without exhaustively mapping competitive positioning.
| Leading Market Players |
|---|
| Westrup A/S |
| Alvan Blanch Development Company |
| Bühler AG |
| Agrosaw |
| AGCO Corporation |
| Cimbria A/S |
| Satake Corporation |
| Incotec Group BV |
| PETKUS Technologie GmbH |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between identity-preserved and commodity seed processing lines manifests in both equipment pricing and supply chain sourcing patterns. Premium-tier optical sorting systems command substantial markups over mechanical alternatives, while stainless steel input volatility and concentrated sensor fabrication in East Asian corridors shape vendor margin structures and buyer procurement timelines.
Pricing Analysis
Distributor margins compress most acutely for mid-scale batch processing configurations as seasonal volume volatility in Spain and Italy shifts procurement toward service contracting with bundled maintenance. Three-tier pricing structure across premium, standard, and economy levels separates enclosed chemical application systems with negative-pressure enclosures from open-treatment lines facing EPA compliance obsolescence. Price differentiation hinges on optical detection thresholds and integrated single-pass architecture. Cost compression in standard-tier mechanical equipment intensifies as nickel price swings strain fabrication budgets. Regional seed cooperatives in India exhibit highest price sensitivity, while commercial farming operations in Germany and the United States prioritize certification compliance over capital expenditure minimization.
Supply Chain Analysis
Workforce availability constraints in Swiss and German precision engineering hubs elevate lead times for high-capacity cleaning lines, while Danish modular specialists leverage more flexible labor pools. Manufacturing concentrates in Germany, Switzerland, and Denmark for premium-tier equipment, with China scaling domestic optical sorting fabrication under MIIT industrial upgrading programs. Raw material dependencies center on nickel and chromium for stainless steel hulls, high-resolution camera modules from East Asian sensor fabricators, and specialized pneumatic components. Single-source vulnerability in camera module supply creates exposure to geopolitical friction in Taiwan Strait corridors. Distribution runs through authorized dealer networks for large-scale commodity grain operations, with direct vendor relationships dominating premium vegetable seed corridors in the Netherlands and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seed processing equipment market functions as a regulatory compounder where EPA drift standard revisions and EU F-Gas Regulation phase-down timelines generate sustained replacement demand across installed bases.
For Market Incumbents: Deploy optical detection platform licensing as a defensive lever against Asian fabricators scaling domestic vision-based capacity. Incumbents should anchor backward integration into high-resolution sensor supply through strategic partnerships with East Asian module producers, mitigating single-source concentration risk. Capacity addition in India serves CDSCO and FSSAI quality enforcement windows before first-mover advantages erode. Channel control through bundled service contracting defends margin position against leasing arrangements displacing outright ownership among Mediterranean vegetable seed cooperatives. For New Entrants and Emerging Players: Hyperspectral imaging integration for small-batch research applications offers the most penetrable white-space target, as Wageningen corridor institutions demand precision breeding equipment beyond commercial thresholds. Modular treating configurations with blockchain-enabled traceability capture premium pricing in specialty seed segments where established vendors underinvest. Go-to-market execution should emphasize pilot programs with Dutch greenhouse clusters to generate referenceable phenotype consistency outcomes before scaling to California Central Valley operations. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap manufacturers face margin compression from stainless steel input volatility and struggle to fund optical R&D catch-up. Long-term viability favors vendors with captive supply of critical sensor components or exclusive distribution lockups in India processing modernization corridors. Acquisition target archetype: Danish modular specialists with reconfigurable architecture and established leasing infrastructure in seasonal-volume markets. Signal to watch: DGFT export equipment approval timeline compression indicating regulatory streamlining that accelerates capital deployment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Platform Licensing | Technology transfer agreements enable Asian fabricators to bridge vision-based capability gaps under MIIT programs. |
| Service Contracting Expansion | Leasing arrangements with bundled maintenance reduce fixed-asset exposure for Spanish and Italian vegetable seed clusters. |
| India Distribution Partnerships | Local assembly capabilities circumvent DGFT approval delays straining working capital cycles for imported lines. |
| Energy-Recovery Drying Integration | EU Green Deal carbon border adjustment mechanisms reward equipment with thermal efficiency modules in German facilities. |
| Blockchain Traceability Bundling | Convergence of optical sorting data with distributed ledger systems opens premium pricing corridors for certified seed lots. |
Study Parameters
Bottom-up commercial farming and horticulture modeling reconciled against top-down equipment fabrication tracking forms the analytical core of this study. Primary interviews with seed processing plant managers, OEM procurement teams at agricultural equipment manufacturers, aftermarket service heads, and regulatory compliance officers combined with secondary validation against EPA enforcement actions, EU ECHA chemical registration databases, CDSCO quality directives, and customs trade data for stainless steel and optical component flows. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity across product function, end-use intensity, and capacity scale.
Historical trendline analysis of replacement cycle compression and technology displacement patterns informs projection modeling across the analysis window. Segmentation dimensions span equipment type, end-use industry, technology modality, and capacity tier, with regional regulatory cluster overlays for EPA, EU Green Deal, and CDSCO enforcement trajectories. CAGRs derive from equipment shipment tracking, capital expenditure disclosures from commercial farming operations, and vendor order book analysis. Industry-specific forecast inputs include optical detection standard upgrade timelines and chemical seed treatment formulation approval velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical registration timeline extensions, nickel price volatility trajectories, and geopolitical friction in East Asian sensor supply corridors. Forecasts reflect assumptions regarding regulatory enforcement consistency and precision agriculture infrastructure buildout pace without guarantee of realization. Material deviation in EPA drift standard implementation timelines or F-Gas Regulation phase-down schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Meat Dicing Machine Market
Agricultural Processing Equipment
Combine Harvesters Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
North America Feed Pelletizing Agent Market
Agricultural Processing Equipment
Corn Milling Machine Market