
 Japan Agricultural Shredder Machine Market | 2026-2036
Japan Agricultural Shredder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Agricultural Shredder Machine Market Insights
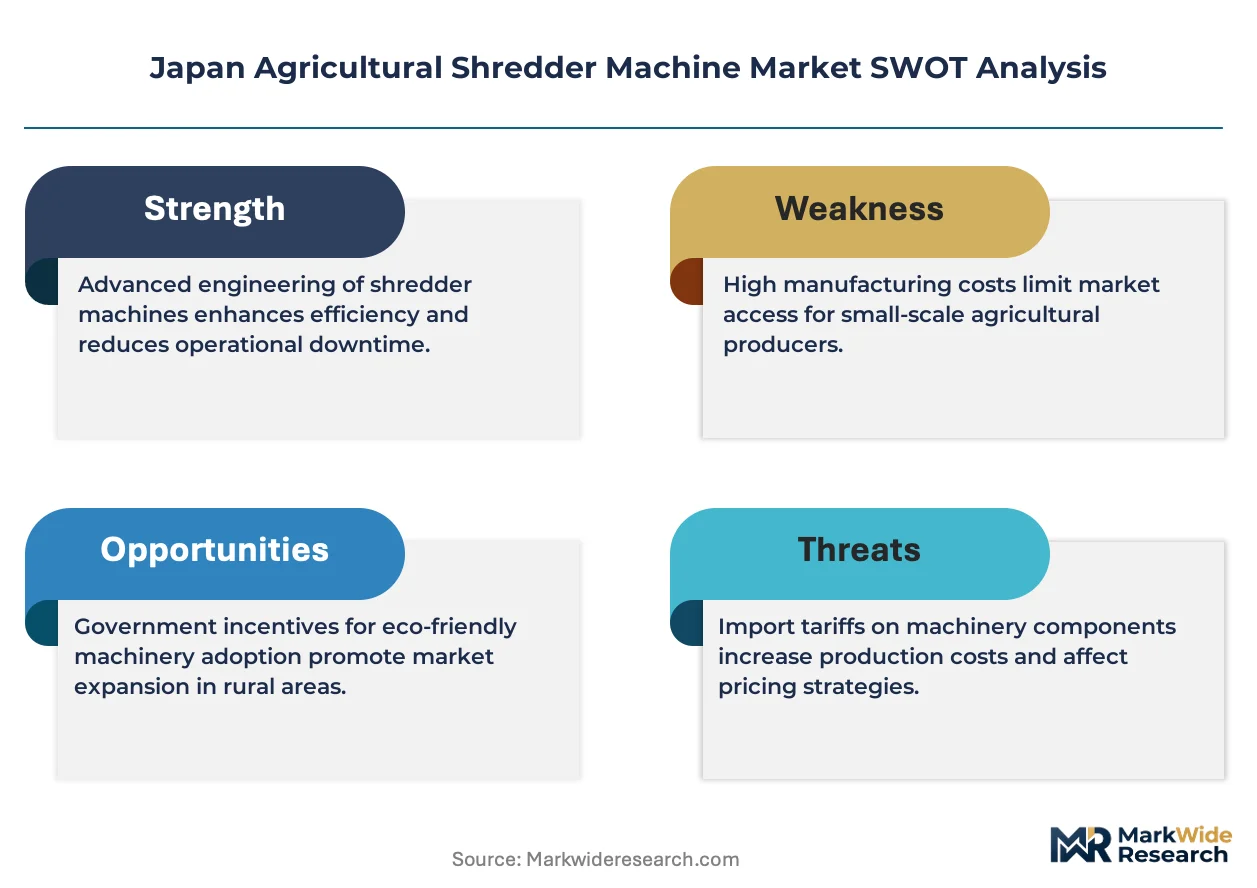
Premium-grade shredding throughput with sub-50mm particle consistency is rotating farmer preferences toward precision residue management. Kubota Corporation leverages its domestic dealer density to sustain replacement-cycle capture across Honshu. Yanmar Company Limited anchors its position through compact tractor-integrated shredder systems. Iseki & Co., Ltd. competes via specialized vineyard and orchard configurations.
Agricultural shredder machines mechanically reduce crop residues, pruning debris, and organic waste through rotary blade or hammer-mill assemblies operating at 1,500–3,000 RPM, producing uniform biomass feedstock for composting or energy recovery. Diesel shredder units dominate installed base due to field mobility independence from grid access. Hydraulic technology configurations command margin premiums where contractors demand variable torque control across variable feedstock density. Crop residue application leads volume as rice straw disposal regulations tighten prefecture-by-prefecture.
METI efficiency standards and JIS safety certifications shape manufacturer design obligations and market access thresholds for imported equipment. Japan's national biomass town initiative and prefectural-level agricultural residue ordinances mandate mechanized processing, directly expanding addressable demand. Stakeholders must monitor evolving organic waste recycling subsidies and prefectural compaction mandates that will determine equipment specification requirements and replacement timing.
Market Dynamics
METI's biomass utilization roadmap and prefectural residue ordinances are compelling mechanized processing adoption across Japan's agricultural belt, forcing equipment specification upgrades and accelerating replacement cycles among orchard and rice farming operations.
Growth Catalysts
- Rice straw disposal regulations:Prefecture-by-prefecture tightening of residue management rules mandates mechanized shredding for compliance, expanding equipment procurement across Honshu rice belts.
- Biomass town initiative:Japan's national program subsidizes organic waste-to-energy infrastructure, directly funding agricultural shredder deployment in designated municipalities.
- Citrus belt mechanization:Kyushu's expanding orchard acreage drives demand for tractor-integrated shredding systems to process pruning debris at scale.
Market Restraints
- Diesel input cost volatility:Field mobility dependence on diesel engines exposes operators to fuel price swings that compress operating margins and delay replacement decisions.
- JIS certification timeline:Safety standard compliance testing creates extended product launch delays for imported equipment seeking market access.
- Grid-independent substitute:PTO-driven shredder attachments for existing tractors present lower-capital alternatives that constrain standalone unit demand in smallholder segments.
Strategic Opportunities
- Aomori orchard services:Specialized management contractors in northern Honshu present untapped demand for premium vineyard-configured shredding equipment.
- Hydraulic torque control:Variable feedstock density adaptation through hydraulic technology convergence commands margin premiums from contractor segments.
- Prefectural compaction mandates:Evolving organic waste volume reduction requirements will specify sub-50mm particle consistency, favoring precision equipment upgrades.
Industry Challenges
- Technician specialization gap:Hydraulic system maintenance and rotary blade calibration require skilled service capacity that rural dealer networks struggle to retain.
- Legacy tractor integration:Compatibility verification with aging installed bases of compact tractors complicates sales cycles and increases pre-purchase technical consultation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Agricultural Shredder Machine Market |
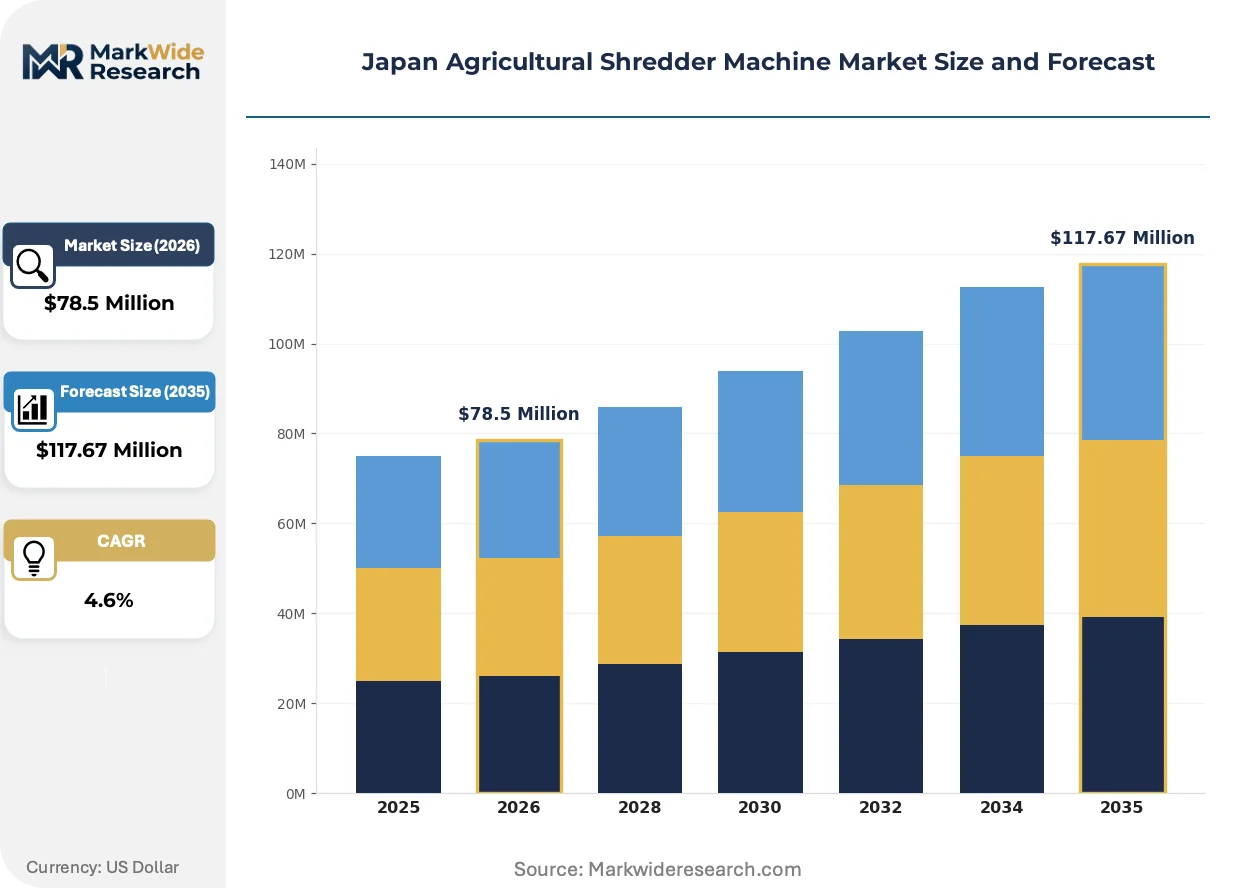
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $117.67 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Shredder, Diesel Shredder, Manual Shredder, PTO Shredder Application: Crop Residues, Pruning Waste, Wood Waste, Yard Waste End User: Farmers, Agricultural Contractors, Landscaping Companies, Nurseries Technology: Hydraulic, Mechanical, Electric, Gasoline |
| Companies Covered | Kubota Corporation, Iseki & Co., Ltd., Yanmar Company Limited, Mitsubishi Agricultural Machinery, IHI Shibaura Machinery Corporation, Taiyo Co., Ltd., Kubota Tractor Corp., AGCO Corp., Deere & Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Agricultural Shredder Machine Market Trends and Innovations
Precision residue management specifications and variable torque control architectures are redefining equipment performance benchmarks across Japan's mechanized agricultural processing sector.
Hammer-mill assemblies operating at optimized RPM ranges are decomposing crop residues into uniform biomass feedstock for composting and energy recovery applications. Orchard contractors in Aomori and citrus operations across Kyushu are adopting these systems to meet sub-50mm particle consistency requirements. This technology is decomposing the historical trade-off between throughput volume and feedstock uniformity that constrained earlier blade-based designs.
METI efficiency standards and JIS safety certifications are reshaping manufacturer design obligations for both domestic producers and import entrants. Equipment must now demonstrate documented energy performance and emergency-stop compliance before prefectural subsidy eligibility. Diesel shredder units face the most stringent testing protocols, while hydraulic configurations navigate additional torque validation requirements.
Service bundling unbundling is altering how orchard management contractors acquire shredding capacity. Equipment-only transactions are displacing traditional full-service leases as Aomori-based operators seek capital ownership for tax depreciation advantages. This pattern is most visible among mid-scale citrus processors in Kyushu, where biomass town subsidies reduce financing risk for direct purchase decisions.
Japan Agricultural Shredder Machine Market Segmentation
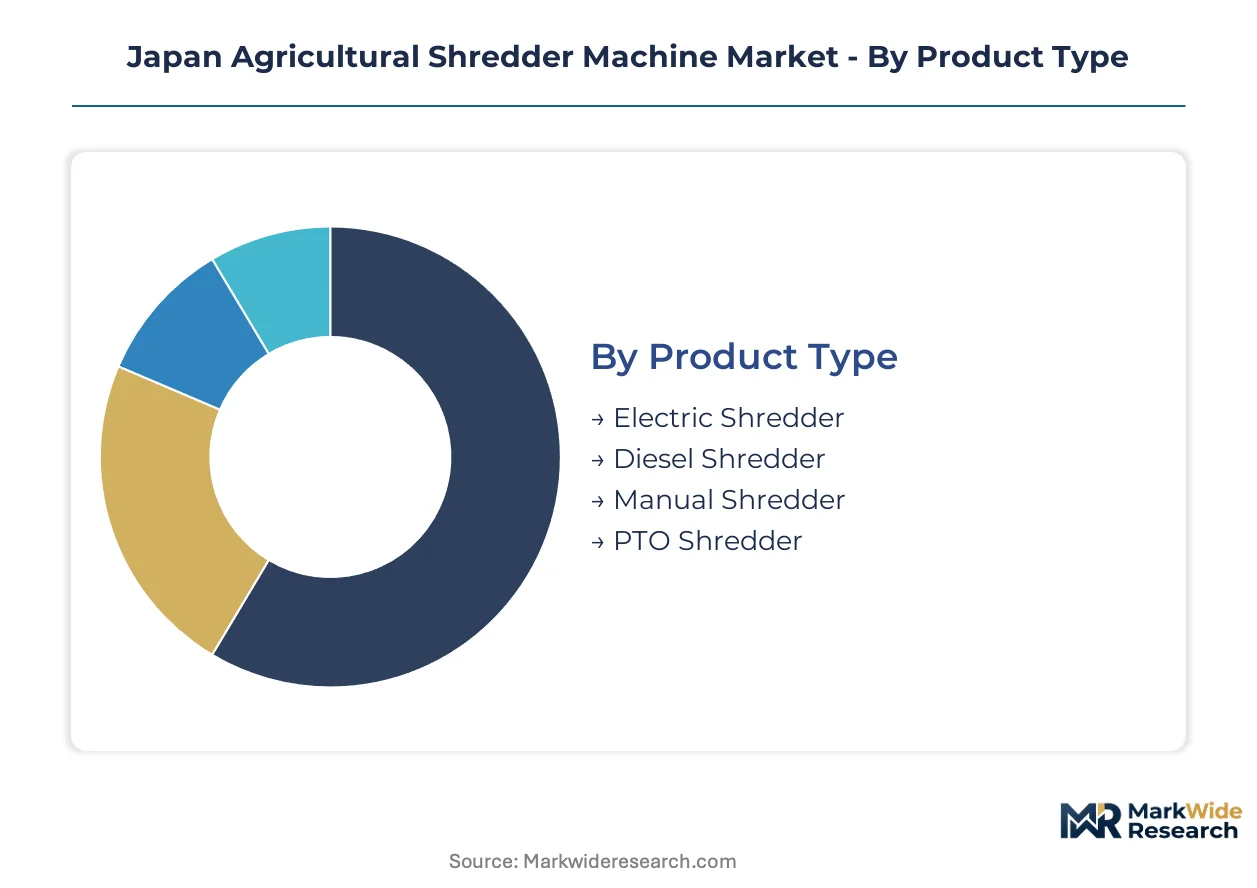
Segmentation in Japan's agricultural shredder machine market reveals how equipment specifications align with prefectural residue regulations and orchard management economics. Understanding these divides exposes where manufacturers capture premium pricing versus where commoditization pressures concentrate.
Product Type:
Margin pools concentrate in configurations that balance field mobility with torque precision, rewarding suppliers who solve the diesel-hydraulic integration challenge.
- Diesel Shredder:Self-propelled units with independent power generation dominate Japan's rice belt installations. Honshu prefectures facing tightened straw disposal mandates drive procurement clusters where grid access remains unreliable. Diesel torque output satisfies high-throughput rice residue processing requirements.
- PTO Shredder:Tractor-powered attachments leverage existing compact tractor installed bases across Kyushu's citrus operations. Lower capital barriers accelerate adoption among smallholders responding to biomass town subsidies, though revenue per unit trails standalone configurations.
- Electric Shredder:Grid-dependent systems suit nursery and greenhouse operations with reliable power infrastructure.
- Manual Shredder:Hand-fed units serve hobbyist and micro-scale landscaping applications with minimal throughput demands.
The dominant share belongs to Diesel Shredder, while PTO Shredder is closing the gap fastest.
Application:
Volume flows track regulatory enforcement intensity across Japan's agricultural prefectures, with residue type determining equipment specification requirements.
- Crop Residues:Rice straw processing commands the largest equipment deployment as prefecture-by-prefecture disposal regulations tighten. Sub-50mm particle consistency requirements specified in organic waste ordinances favor hammer-mill assemblies over legacy blade designs. METI biomass utilization roadmap funding accelerates mechanized adoption in designated municipalities.
- Pruning Waste:Orchard debris from Aomori's apple belt and Kyushu's citrus expansion drives demand for variable-feed systems. Hydraulic torque control configurations capture contractor preference where branch density fluctuates seasonally.
- Wood Waste:Forestry thinning residue processing requires reinforced blade assemblies and higher RPM tolerances.
- Yard Waste:Municipal landscaping contracts generate seasonal demand peaks with lower specification thresholds.
Crop Residues holds the dominant position, though Pruning Waste is expanding most quickly as orchard mechanization accelerates.
End User:
Customer type determines procurement channel economics, with contractor consolidation reshaping equipment specification and service bundling preferences.
- Agricultural Contractors:Specialized management services in Aomori Prefecture and Kyushu's citrus belt drive premium equipment procurement. These operators demand hydraulic technology for variable feedstock density and prioritize sub-50mm particle consistency for biomass town compliance. Capital ownership trends displace traditional full-service leases as tax depreciation advantages become clearer.
- Farmers:Direct ownership remains concentrated in mid-scale rice operations across Honshu where residue processing is mandatory rather than outsourced.
- Landscaping Companies:Municipal and commercial maintenance contracts generate equipment demand with lower utilization intensity.
- Nurseries:Compact electric and PTO configurations serve controlled-environment operations with limited throughput requirements.
Agricultural Contractors command the dominant revenue share, while Farmers are gaining procurement momentum as subsidy structures shift toward direct ownership.
Technology:
Technology selection reflects the trade-off between capital cost and operational flexibility, with hydraulic systems capturing margin premiums in contractor segments.
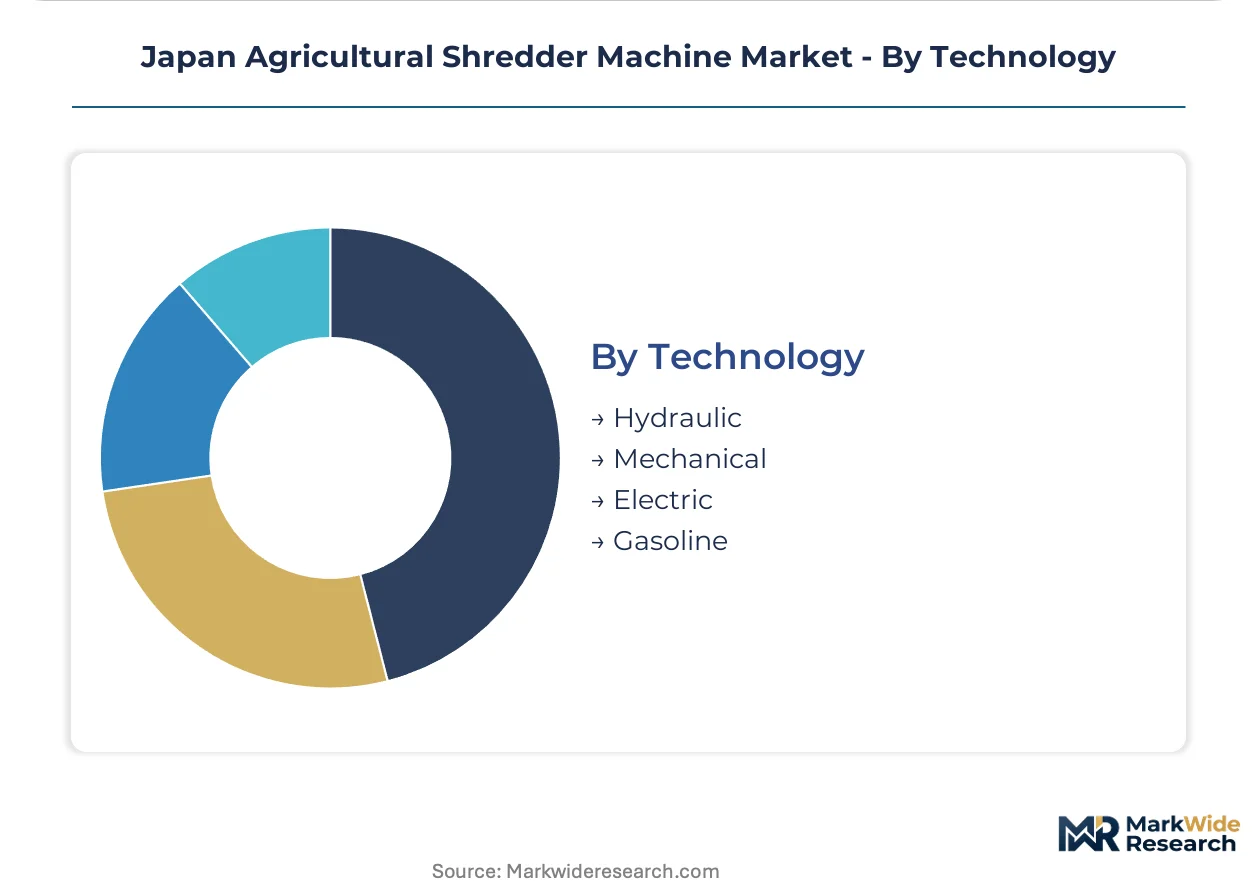
- Hydraulic:Variable torque control architectures command price premiums from orchard contractors processing heterogeneous feedstock. Aomori vineyard specialists and Kyushu citrus operators specify these systems for branch density adaptation. METI efficiency standards impose additional torque validation requirements that extend certification timelines but protect incumbent suppliers.
- Mechanical:Fixed-ratio gear systems dominate rice straw applications where feedstock uniformity reduces adaptation requirements.
- Electric:Grid-tied configurations suit nursery and greenhouse environments with consistent power availability.
- Gasoline:Portable units serve landscaping applications requiring site-to-site mobility without tractor dependency.
Hydraulic technology captures the dominant margin pool, though Mechanical systems retain volume leadership in standardized residue processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Kyushu's citrus belt exhibit the lowest price elasticity as orchard contractors prioritize hydraulic torque control, while Honshu rice farmers face tighter capital constraints under prefectural straw disposal mandates. The market fragments across distinct agricultural geographies where residue type and subsidy access determine procurement intensity.
Kanto/Tokyo
Metropolitan-adjacent nursery operations and landscape maintenance contractors drive compact electric and PTO shredder demand. METI biomass town subsidies flow heavily into designated municipalities across Saitama and Chiba prefectures. Equipment specification clusters around sub-50mm particle consistency requirements for organic waste volume reduction compliance.
Kansai/Osaka
Legacy rice farming operations in Shiga and Nara prefectures face accelerating straw disposal regulation enforcement. PTO-driven attachments for existing compact tractor bases dominate procurement as farmers minimize capital outlay. Dealer networks concentrate in Osaka's industrial corridor, supporting maintenance capacity for mechanical gear systems.
Kyushu
Expanding citrus acreage across Kumamoto and Miyazaki prefectures generates premium demand for tractor-integrated hydraulic shredding systems. Orchard contractors specify variable torque control for heterogeneous pruning debris density. Biomass town initiative funding reduces financing risk for direct capital ownership among mid-scale processors.
Tohoku
Aomori Prefecture's apple belt anchors specialized vineyard-configured equipment procurement through management service contractors. Prefectural organic waste ordinances mandate mechanized residue processing with documented particle consistency. Service bundling unbundling trends concentrate here as operators seek tax depreciation advantages from capital ownership.
Chubu/Nagoya
Industrial machinery manufacturing density in Aichi Prefecture supports hydraulic system component supply chains for shredder assemblers. Rice straw processing volume remains substantial across Toyama and Ishikawa prefectures under tightening disposal rules. Technician specialization gaps for rotary blade calibration create service bottlenecks in rural dealer networks.
Japan Agricultural Shredder Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's agricultural shredder machine market. Domestic manufacturers with dense dealer networks capture replacement cycles through service integration, while import entrants face extended JIS certification timelines that compress margin structures. Three archetypes dominate: integrated agricultural equipment conglomerates, specialized compact machinery fabricators, and international tractor-shredder system suppliers. Competitive moves concentrate on hydraulic-diesel integration refinement and prefectural subsidy eligibility positioning.
Among domestic integrated manufacturers, Kubota Corporation, Iseki & Co., Ltd., and Yanmar Company Limited occupy positions shaped by their existing agricultural equipment installed bases. These companies exemplify the archetype of leveraging tractor compatibility and dealer density to anchor replacement demand. Their geographic concentration in Japan's industrial heartland reinforces service network proximity to key agricultural prefectures.
| Leading Market Players |
|---|
| Kubota Corporation |
| Iseki & Co., Ltd. |
| Yanmar Company Limited |
| Mitsubishi Agricultural Machinery |
| IHI Shibaura Machinery Corporation |
| Taiyo Co., Ltd. |
| Kubota Tractor Corp. |
| AGCO Corp. |
| Deere & Company |
| Others |
Pricing and Supply Chain Analysis
Hammer-mill blade assemblies replacing legacy rotary configurations in premium orchard equipment are simultaneously shifting component sourcing toward Aichi Prefecture's precision metalworking cluster and compressing margin structures for mechanical-gear suppliers unable to adapt torque-validation requirements.
Pricing Analysis
After-sales service contracts and replacement blade programs capture lifetime value exceeding original equipment margins by substantial multiples. Three-tier pricing structure across hydraulic premium, mechanical standard, and PTO economy levels segments buyer archetypes by residue processing intensity. Price differentiation hinges on JIS certification tier and dealer service bundling. Cost compression in economy PTO tiers is intensifying because smallholders leverage existing tractor bases. Agricultural contractors exhibit lowest price sensitivity; rice belt farmers face acute capital constraints under prefectural mandate timelines.
Supply Chain Analysis
Strategic stockpiling of hydraulic torque components dominates procurement behavior among Aomori orchard contractors facing seasonal pruning peaks. Manufacturing concentration centers on Japan's Chubu industrial corridor, with China and South Korea supplying forged blade assemblies and precision bearings. Raw material dependencies include high-carbon steel for cutting surfaces, hydraulic fluid formulations, and diesel engine blocks. Single-source vulnerability concentrates in specialized torque sensor suppliers. Distribution runs through Kubota and Yanmar dealer networks with embedded service capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's biomass utilization roadmap and prefectural residue ordinances constitute a regulatory inflection accelerating equipment replacement cycles beyond historical patterns.
For Market Incumbents: Consolidate dealer service capacity in Aomori and Kyushu to capture replacement-cycle timing. Deepen backward integration into hydraulic torque component production to defend margin position against import entrants facing JIS certification delays. Prioritize certification investment for sub-50mm particle consistency specifications ahead of prefectural mandate expansion. For New Entrants and Emerging Players: Differentiate on compact tractor-integrated PTO configurations targeting Kyushu citrus smallholders underserved by premium hydraulic systems. White-space opportunity concentrates in Aomori vineyard-specialized equipment where management contractors seek capital ownership. Go-to-market angle should leverage biomass town subsidy eligibility documentation to accelerate procurement decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale hydraulic system fabricators in Aichi Prefecture lacking national dealer footprint. Long-term viability frames around 5-10 year mechanization completion across Japan's designated biomass towns. Acquisition target archetype: specialized orchard-configured equipment suppliers with JIS certification in place. Signal to watch: prefectural compaction mandate expansion beyond current Aomori and Kyushu enforcement zones.| Strategic Initiative | Industry Significance |
|---|---|
| Hydraulic-Diesel Integration Investment | Variable torque control captures premium pricing from Aomori orchard contractors processing heterogeneous feedstock. |
| JIS Certification Acceleration | Prefectural subsidy eligibility requires documented safety compliance before equipment deployment authorization. |
| Dealer Service Network Expansion | Technician specialization gaps in rural networks create bottleneck for rotary blade calibration demand. |
| Biomass Town Subsidy Positioning | METI roadmap funding flows directly to designated municipalities for organic waste-to-energy infrastructure. |
| Compact Tractor Compatibility Program | Legacy installed bases across Kyushu smallholders constrain standalone unit demand without PTO integration verification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with orchard management contractors, agricultural equipment dealers, hydraulic system engineers, and prefectural agricultural extension officers. Secondary validation drew from METI biomass utilization roadmap documentation, JIS certification registry databases, prefectural organic waste ordinance filings, and customs trade records for agricultural machinery imports. Bottom-up equipment procurement modeling and top-down agricultural residue volume estimates were triangulated to establish market sizing.
Across the analysis window, forecasts segment by product type, application, end user, and technology configuration. CAGRs were derived from equipment replacement cycle analysis, subsidy program budget trajectories, and prefectural regulatory enforcement timelines. Industry-specific inputs include rice straw disposal mandate expansion schedules and citrus belt acreage projections.
Decision-makers should treat outputs as directional under assumptions of continued METI biomass town funding and prefectural ordinance enforcement; material deviation would warrant model refresh. Revision becomes warranted when diesel input cost volatility or JIS certification timeline extensions cross thresholds that compress replacement cycle economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Manure Handling Equipment Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Cassava Processing Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Corn Milling Machine Market
Agricultural Processing Equipment
India Rice Milling Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Animal Feed Processing Equipment Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Egg Processing Machine Market
Agricultural Processing Equipment
Harvesting Machinery Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market