
 Meat Dicing Machine Market | 2026-2036
Meat Dicing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Dicing Machine Market Foresight
EU Green Deal food waste reduction targets are shifting procurement priorities across European meat processing. Marel hf leverages its integrated software-hardware platforms to sustain automation leadership in Nordic markets. GEA Group anchors its position through upstream control over stainless steel fabrication networks in Central Europe. Dadaux SAS differentiates via specialized blade geometry R&D for premium charcuterie applications.
A meat dicing machine is an industrial food processing unit that employs reciprocating or rotary blade assemblies to reduce whole muscle or formed meat blocks into uniform cubes, strips, or flakes at throughput rates from 500 kg to 12,000 kg per hour. Automatic systems dominate volume sales due to labor cost arbitrage in high-throughput facilities, while Smart Technology integration is expanding fastest as IoT-enabled blade-wear monitoring reduces unplanned downtime. Food Processing Plants represent the deepest margin pool because equipment amortizes across three-shift operations and buyers prioritize total cost of ownership over capital expenditure.
EMA hygiene standards, FDA Hazard Analysis and Critical Control Points frameworks, and ISO 14159 machinery safety specifications collectively shape product design and market access requirements across jurisdictions. Brazil's ANVISA and South Korea's MFDS impose divergent electrical enclosure ratings that fragment certification burdens for exporters. Stakeholders must monitor divergence between EU MDR-aligned food contact material rules and emerging state-level water reuse restrictions in US protein processing corridors.
Market Dynamics
EU Green Deal food waste reduction mandates are forcing meat processors to replace manual cutting lines with automated dicing systems capable of precise portion control and trim optimization. This regulatory pressure is concentrating procurement authority in sustainability compliance officers rather than traditional operations managers.
Growth Catalysts
- ANVISA Hygiene Mandates:Brazil's national health surveillance agency requires HACCP-validated cutting equipment in industrial slaughterhouses, accelerating replacement of manual operations in facilities processing over 500,000 head annually.
- IoT Blade-Wear Monitoring:Smart sensor arrays embedded in rotary knife assemblies predict maintenance intervals, reducing unplanned downtime in three-shift protein processing plants.
- Labor Cost Arbitrage:High-throughput facilities in Germany and the Netherlands justify automatic system investments where wage differentials between skilled butchers and machine operators exceed 40 percent.
Market Restraints
- Stainless Steel Supply Concentration:Central European fabrication networks control 316L grade sheet supply, creating input cost volatility when nickel prices fluctuate on London Metal Exchange benchmarks.
- Electrical Enclosure Fragmentation:Divergent IP ratings between Brazil's ANVISA and South Korea's MFDS force redundant certification testing for exporters targeting both markets.
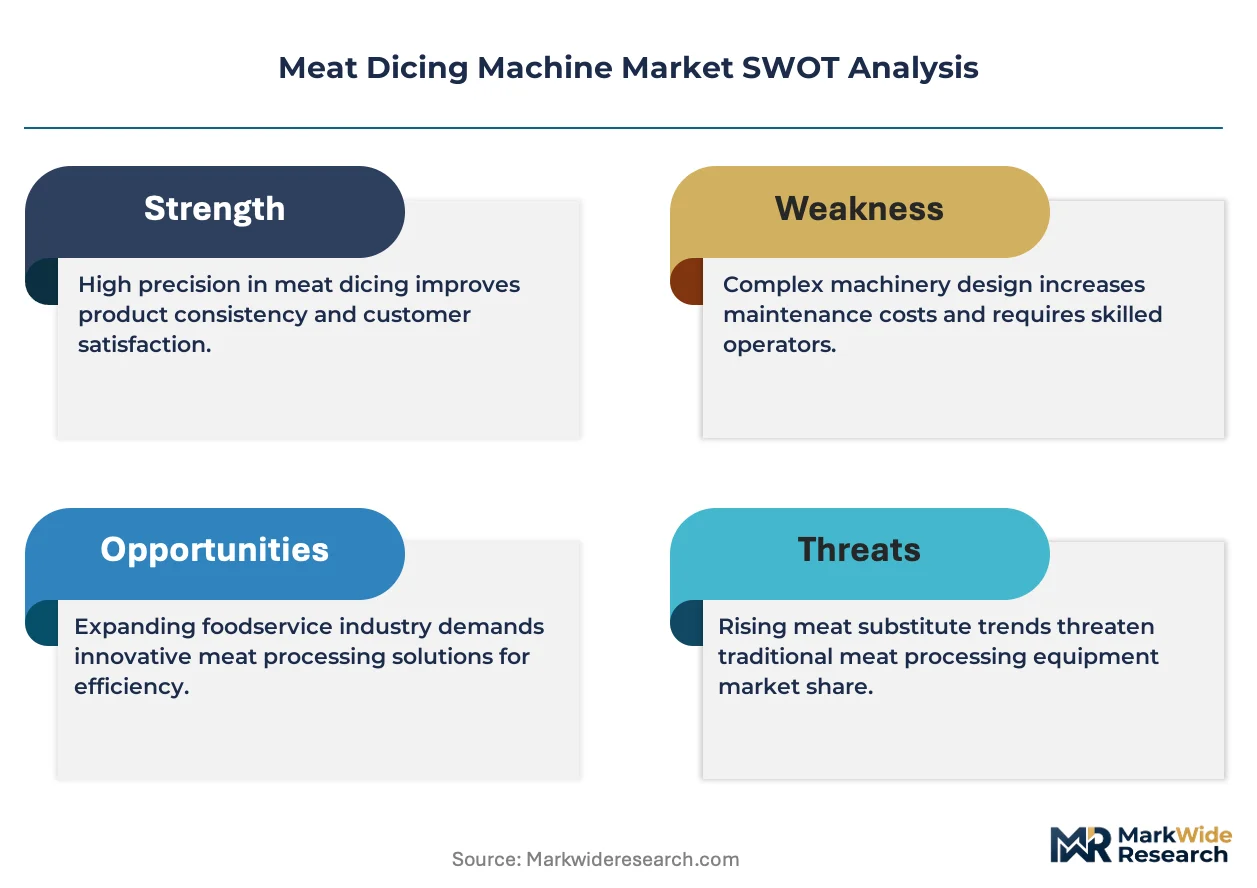
- Manual Cutting Substitution Ceiling:Premium charcuterie applications requiring irregular dice geometries resist full automation, preserving niche demand for skilled artisanal cutters.
Strategic Opportunities
- Water Reuse Corridors:Emerging state-level restrictions in US protein processing regions create demand for closed-loop sanitation systems integrated with dicing line CIP protocols.
- Plant-Based Protein Convergence:Extruded mycoprotein and textured vegetable protein blocks require modified blade geometries, opening adjacent equipment markets with shared cutting mechanics.
- EU AI Act Alignment:Predictive maintenance algorithms qualify as high-risk AI systems under forthcoming European regulations, creating first-mover advantage for vendors with pre-certified software architectures.
Industry Challenges
- Mechatronics Talent Scarcity:Servo-driven blade positioning systems require technicians fluent in both food safety protocols and precision motion control, a skill intersection with limited training pipelines.
- Legacy System Integration:Brownfield installations must synchronize new dicing lines with existing SCADA networks using proprietary communication protocols from 1990s-era equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Dicing Machine Market |
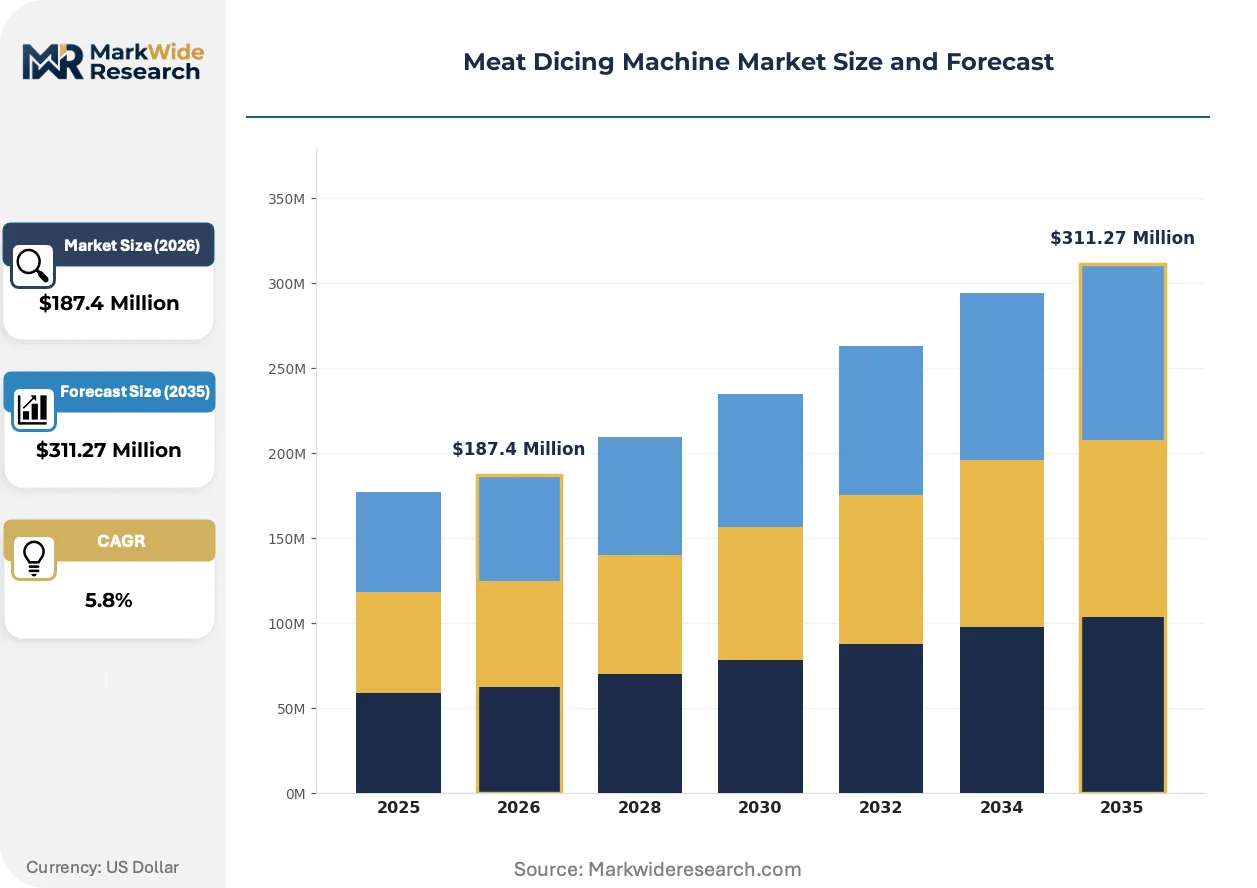
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Semi-Automatic, Industrial End User: Food Processing Plants, Restaurants, Supermarkets, Butcher Shops Capacity: Small Scale, Medium Scale, Large Scale, Custom Size Technology: Blade Technology, Continuous Flow, Multi-purpose, Smart Technology |
| Companies Covered | MHS, Meat Machinery, ABM Company SRL, Temic SL, Watanabe Foodmach Co., Ltd., Marel hf, GEA Group, Dadaux SAS, Ire Korea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Dicing Machine Market Shifts & Advancements
Reciprocating blade assemblies with adaptive feed mechanisms are displacing fixed-geometry rotary systems across high-throughput facilities. This hardware evolution converges with software-defined sanitation protocols and compressed buyer decision cycles.
Vision-guided portioning systems using hyperspectral cameras are automating real-time fat-to-lean ratio verification during the dicing operation. Food processing plants in Denmark and Sweden deploy these systems to meet retail chain specifications without offline laboratory testing. The technology is automating quality control labor out of the production line, collapsing the traditional separation between cutting and inspection stations.
EU MDR-aligned food contact material rules now govern blade coatings and lubricants in European installations. Manufacturers must submit migration testing documentation for polymer-based anti-friction surfaces previously grandfathered under older frameworks. German processors face the steepest compliance burden as their federal food safety authority interprets migration thresholds more stringently than southern European counterparts.
Buying committees now unbundle after-sales service contracts from capital equipment purchases, negotiating blade resharpening and spare parts logistics separately. This pattern compresses vendor margins on installation revenue while shifting profit pools to consumables and predictive maintenance subscriptions. The behavior is most pronounced in Brazilian industrial slaughterhouses where procurement teams benchmark total cost of ownership across multi-year horizons.
Meat Dicing Machine Market Segmentation
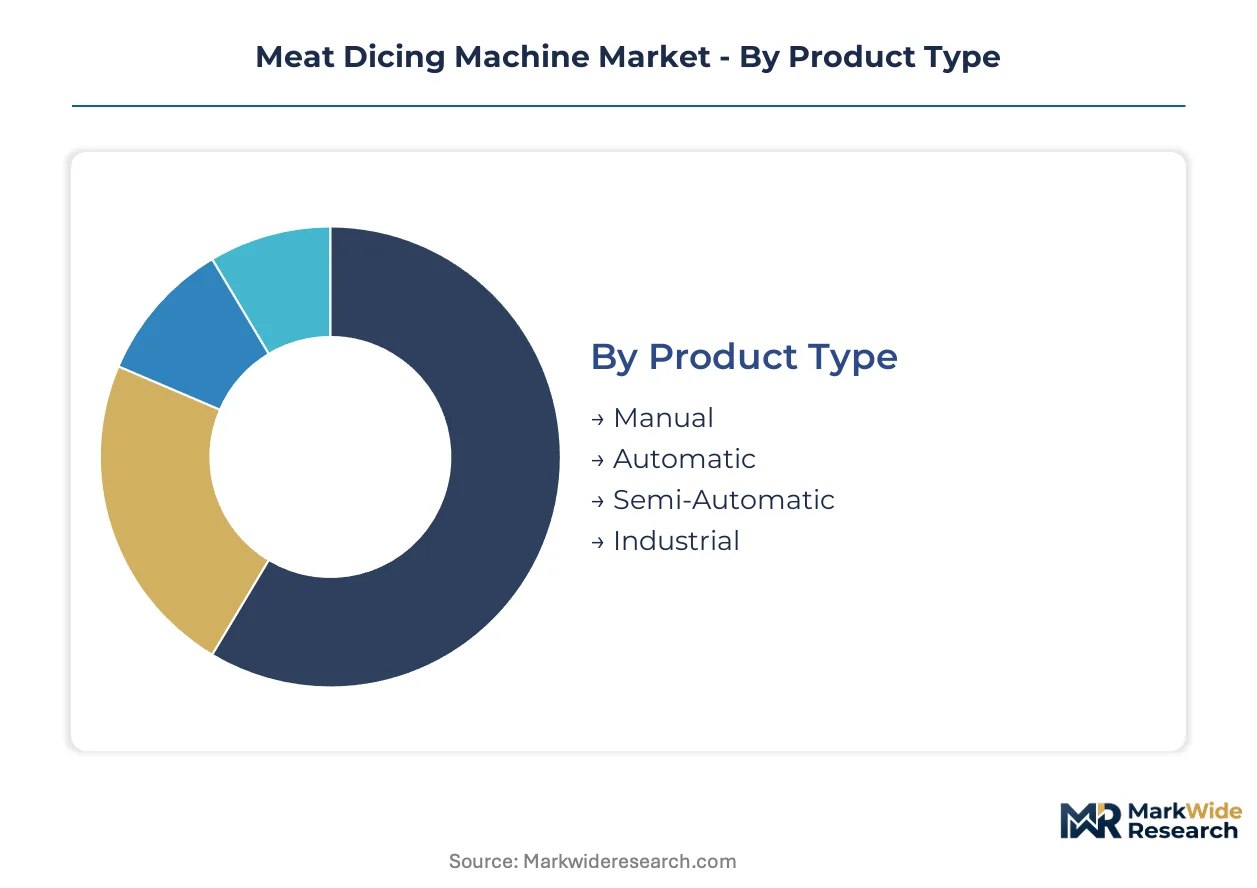
Meat dicing equipment segments diverge sharply between high-volume commodity processing and precision artisanal applications. Procurement committees now unbundle purchasing decisions across these dimensions, treating blade technology, throughput capacity, and sanitation protocols as independent negotiation levers rather than bundled specifications.
Product Type:
Automatic systems command volume leadership while manual equipment retains defensible niches where labor arbitrage fails.
- Automatic:Reciprocating or rotary blade assemblies process 500 kg to 12,000 kg hourly with minimal operator intervention. Demand concentrates in German and Dutch facilities where wage differentials between skilled butchers and machine operators exceed 40 percent, justifying capital deployment despite stainless steel input volatility.
- Manual:Hand-fed cutting units serve premium charcuterie workshops requiring irregular dice geometries that resist algorithmic portioning. Brazilian ANVISA mandates are accelerating replacement in industrial slaughterhouses processing over 500,000 head annually, though artisanal cutters persist in heritage-protected production zones.
- Semi-Automatic:Hybrid feed mechanisms blend operator judgment with mechanical consistency for mid-tier processors.
- Industrial:Integrated line configurations synchronize dicing with upstream grinding and downstream packaging stations.
Today's leader: Automatic. Tomorrow's challenger: Industrial.
End User:
Margin pools concentrate where equipment amortizes across continuous operations and buyers prioritize total cost of ownership over capital expenditure.
- Food Processing Plants:Three-shift protein facilities represent the deepest margin pool due to throughput intensity and predictive maintenance subscription attach rates. Danish and Swedish deployments integrate vision-guided portioning with hyperspectral fat-to-lean verification, collapsing traditional separations between cutting and inspection stations.
- Restaurants:Central kitchen configurations in large chain operations drive demand for compact automatic units with rapid blade-change protocols.
- Supermarkets:In-store fresh preparation counters require sanitation-focused designs with tool-free disassembly for hourly CIP compliance.
- Butcher Shops:Traditional retail cutters favor semi-automatic equipment balancing throughput flexibility with craft identity preservation.
Food Processing Plants capture current procurement authority. Restaurants are climbing the fastest as chain consolidation accelerates central kitchen investment.
Capacity:
Scale segmentation tracks batch frequency rather than absolute throughput, distinguishing intermittent artisanal production from continuous flow operations.
- Large Scale:Systems exceeding 8,000 kg hourly throughput dominate Brazilian industrial slaughterhouses and German export-oriented processors. EU Green Deal food waste reduction targets are forcing replacement of manual cutting lines with automated systems capable of precise portion control and trim optimization.
- Medium Scale:2,000-8,000 kg hourly configurations serve regional processors balancing volume flexibility with capital constraint.
- Small Scale:Sub-2,000 kg units address specialty protein processors and emerging plant-based mycoprotein operations.
- Custom Size:Engineered-to-order installations accommodate non-standard block dimensions in game meat and exotic protein processing.
Large Scale holds installed base dominance. Custom Size offers steepest expansion trajectory as extruded protein blocks require modified blade geometries.
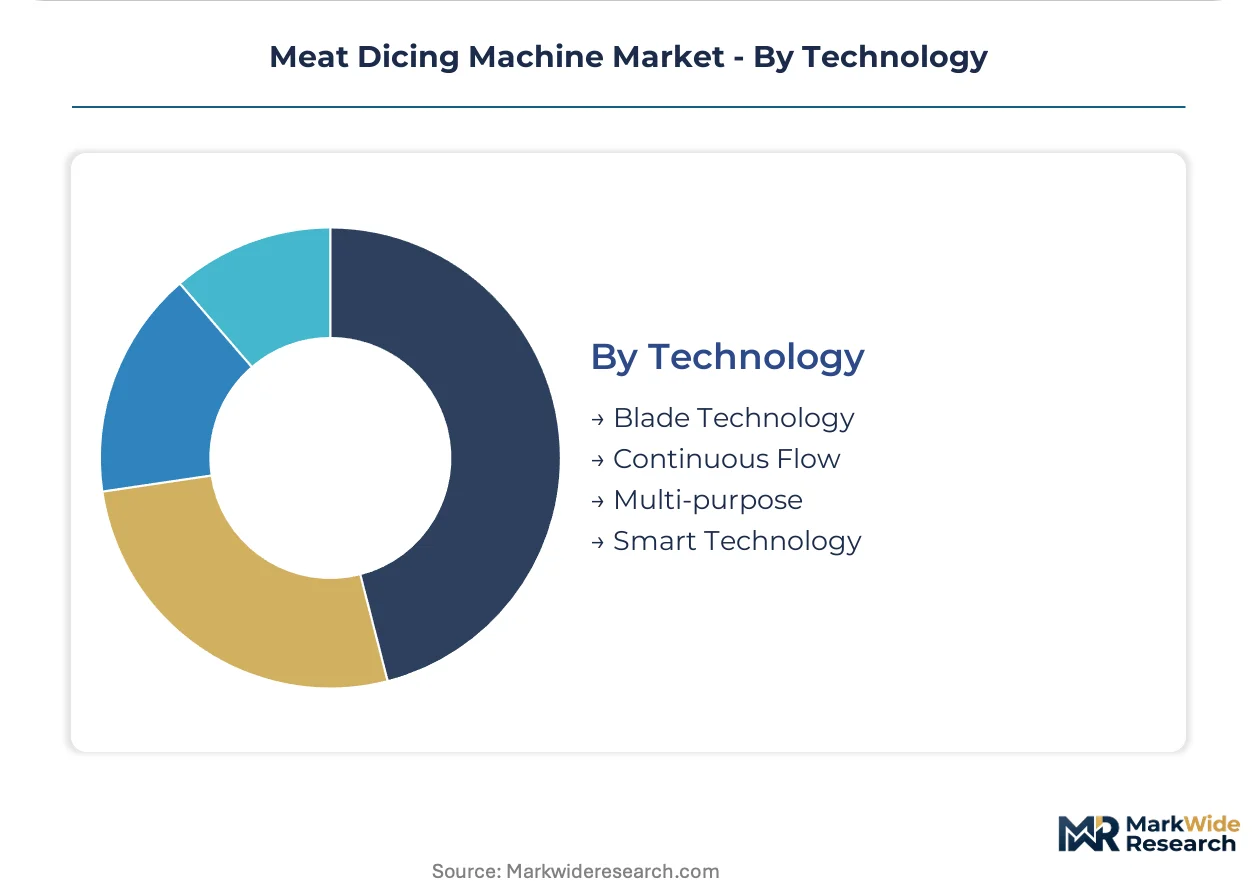
Technology:
Hardware evolution converges with software-defined sanitation protocols, compressing buyer decision cycles around integrated platform offerings.
- Smart Technology:IoT-enabled blade-wear monitoring via embedded sensor arrays predicts maintenance intervals, reducing unplanned downtime in three-shift operations. EU AI Act alignment creates first-mover advantage for vendors with pre-certified predictive maintenance algorithms as high-risk AI systems.
- Blade Technology:Specialized geometry R&D for premium charcuterie applications differentiates vendors serving heritage-protected production methods.
- Continuous Flow:Uninterrupted feed mechanisms eliminate batch transfer losses in high-throughput facilities.
- Multi-purpose:Modular blade assemblies accommodate cube, strip, and flake outputs without line reconfiguration.
Smart Technology is gaining share fastest. Blade Technology defends margin position in premium segments resistant to full automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled butchers and mechatronics technicians concentrate in Northern European protein processing corridors, anchoring automation adoption rates and aftermarket service density.
Germany
Industrial slaughterhouses in Lower Saxony and North Rhine-Westphalia deploy large-scale automatic systems to meet EU Green Deal food waste reduction targets. The Federal Office for Consumer Protection and Food Safety enforces stringent migration thresholds for blade coatings under EU MDR-aligned rules. Dortmund-based fabrication clusters supply 316L stainless steel components to domestic OEMs.
Brazil
ANVISA hygiene mandates are accelerating replacement of manual cutting equipment in facilities processing over 500,000 head annually. The national health surveillance agency requires HACCP-validated equipment with specific electrical enclosure ratings. São Paulo state concentrates the deepest procurement activity as JBS and BRF expand automated dicing capacity.
United States
State-level water reuse restrictions in Nebraska and Iowa protein processing corridors are driving demand for closed-loop sanitation systems integrated with dicing line CIP protocols. FDA Hazard Analysis and Critical Control Points frameworks govern equipment validation. Omaha and Sioux Falls anchor the largest installed base of large-scale throughput systems.
Denmark
Vision-guided portioning systems using hyperspectral cameras are automating real-time fat-to-lean ratio verification in Danish Crown and Danish Agro facilities. EFSA food contact material rules govern blade lubricants and anti-friction surfaces. Copenhagen and Aarhus host the densest concentration of smart technology-integrated installations.
South Korea
MFDS electrical enclosure ratings diverge from Brazilian ANVISA standards, fragmenting certification burdens for exporters targeting both markets. Seoul Capital Area processors prioritize IoT-enabled blade-wear monitoring to reduce unplanned downtime in three-shift operations. Busan-Ulsan corridor facilities lead adoption of predictive maintenance subscriptions.
Meat Dicing Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the meat dicing machine market, creating a tiered structure where stainless steel fabricators and software-integrated platform vendors occupy distinct competitive lanes. The vendor base clusters around three strategic archetypes: integrated automation conglomerates with captive fabrication networks, specialized blade geometry R&D houses serving premium charcuterie applications, and regional machinery builders focused on cost-optimized manual-to-automatic conversion. Dominant competitive moves include backward integration into 316L grade sheet supply and strategic partnerships with hyperspectral camera suppliers for vision-guided portioning systems.
Among Nordic integrated automation providers, Marel hf exemplifies the software-hardware platform archetype, while GEA Group anchors the Central European fabrication network tier. Dadaux SAS occupies a specialist position within the premium charcuterie equipment segment. These three companies represent the primary competitive vectors—platform integration, upstream supply control, and application-specific R&D—that structure procurement committee evaluations across German, Brazilian, and Danish processing facilities.
| Leading Market Players |
|---|
| MHS |
| Meat Machinery |
| ABM Company SRL |
| Temic SL |
| Watanabe Foodmach Co., Ltd. |
| Marel hf |
| GEA Group |
| Dadaux SAS |
| Ire Korea |
| Others |
Supply & Pricing Matrix
Smart Technology-enabled automatic systems command a 35-45 percent price premium over conventional blade assemblies, a bifurcation that deepens as Brazilian ANVISA mandates and EU Green Deal compliance requirements concentrate procurement authority in sustainability officers who prioritize total cost of ownership over capital expenditure. This tier divergence manifests in supply chain configurations where 316L stainless steel fabrication networks in Central Europe feed premium-tier OEMs while cost-optimized manual-to-automatic conversion kits source from regional machinery builders with captive component stamping.
Pricing Analysis
Bundled after-sales service contracts are unbundling from capital equipment purchases, compressing vendor margins on installation revenue while shifting profit pools to consumables and predictive maintenance subscriptions. Pricing stratifies across premium, standard, and economy tiers where EU MDR-aligned food contact material certification and IoT-enabled blade-wear monitoring drive differentiation. Cost compression in economy-tier manual equipment is intensifying because Brazilian procurement teams benchmark total cost of ownership across multi-year horizons. Food processing plants exhibit lowest price sensitivity due to three-shift amortization schedules, while butcher shops face acute budget constraints.
Supply Chain Analysis
Freight costs for 316L stainless steel sheet from Central European mills to Brazilian assembly plants have risen disproportionately, amplifying landed cost volatility when London Metal Exchange nickel benchmarks fluctuate. Supply concentrates in Germany, Italy, and China for precision blade assemblies, with servo-driven positioning systems drawing from Japanese and German motion control specialists. Single-source vulnerability concentrates in Dortmund-based fabrication clusters supplying domestic OEMs. Distribution runs through OEM-direct channels for large-scale food processing plants and regional machinery distributors serving mid-tier butcher shops and supermarket fresh preparation counters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meat dicing machine market functions as a regulatory compounder where EU Green Deal food waste reduction targets and Brazil ANVISA hygiene mandates create sustained replacement demand across European and South American processing corridors.
For Market Incumbents: Lock in predictive maintenance subscription attach rates through pre-certified EU AI Act algorithm architectures before high-risk AI system designations take effect. Deepen backward integration into 316L grade sheet supply to offset London Metal Exchange nickel volatility threatening margin stability in large-scale system configurations. Consolidate blade resharpening logistics networks to defend against emerging regional service aggregators. For New Entrants and Emerging Players: The premium-to-economy price gap in semi-automatic equipment offers entry latitude for mid-tier processors in Denmark and Sweden seeking vision-guided portioning without full Smart Technology platform investment. Target water reuse corridor restrictions in Nebraska and Iowa protein processing regions with closed-loop sanitation system integrations. Deploy direct-to-plant sales teams bypassing legacy distributor markups in Brazilian São Paulo state facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics talent scarcity intersects with legacy SCADA integration complexity, favoring platforms with pre-certified software architectures over hardware-only vendors. Acquisition targets should display captive blade geometry R&D capabilities or established hyperspectral camera supplier partnerships. Monitor EU AI Act implementation timelines as inflection indicator for predictive maintenance algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 316L Stainless Steel Supply | Captive sourcing from Dortmund fabrication clusters insulates margin volatility from London Metal Exchange nickel benchmarks. |
| EU AI Act Algorithm Pre-Certification | Pre-certified predictive maintenance architectures qualify as high-risk AI systems under forthcoming European regulations. |
| Hyperspectral Camera Supplier Partnership | Vision-guided portioning collaborations with Danish Crown and Danish Agro collapse traditional cutting-inspection station separations. |
| Water Reuse Corridor System Integration | Closed-loop sanitation protocols address emerging state-level restrictions in Nebraska and Iowa protein processing regions. |
| Predictive Maintenance Subscription Scale-Up | Blade-wear monitoring IoT arrays reduce unplanned downtime in three-shift Brazilian industrial slaughterhouse operations. |
Research Methodology
Coverage spans Germany, Brazil, the United States, Denmark, and South Korea, with primary inputs from each region combining structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation. Bottom-up and top-down triangulation rests on regulatory filings from ANVISA, FDA, and MFDS, customs and trade data for 316L stainless steel component flows, SEC filings from listed automation conglomerates, and equipment certification databases tracking EU MDR-aligned food contact material compliance.
Granularity-level modeling distinguishes automatic, manual, semi-automatic, and industrial product configurations across food processing plant, restaurant, supermarket, and butcher shop end-user segments, with capacity tier and technology integration depth as cross-cutting dimensions. CAGRs derive from installed base replacement cycles, regulatory mandate implementation timelines, and labor cost arbitrage thresholds across the projection horizon. Industry-specific inputs include ANVISA hygiene mandate compliance deadlines and EU Green Deal food waste reduction target enforcement schedules.
Caveats apply where nickel price volatility on London Metal Exchange benchmarks, divergence between EU MDR-aligned food contact material interpretations, or state-level water reuse restriction adoption rates could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation consistency and mechatronics talent pipeline expansion. A model refresh is warranted upon material change in EU AI Act high-risk AI system designation timelines or Brazilian ANVISA electrical enclosure rating harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Destoner Machine Market
Agricultural Processing Equipment
Asia-Pacific Meat Processing Equipment Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Meat Cutting Machine Market
Agricultural Processing Equipment
China Agricultural Shredder Machine Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Industrial Shelling Machines Market
Agricultural Processing Equipment
Shelling Machine Market
Agricultural Processing Equipment
Solar Powered Agricultural Dryer Market
Agricultural Processing Equipment
Rice Polishing Machines Market
Agricultural Processing Equipment
Global Dry Milling Market