
 Field Marking Paint Market | 2026-2036
Field Marking Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Field Marking Paint Market Analytics
Sporting goods retail channels is narrowing as direct procurement contracts between paint manufacturers and municipal park departments expand. PPG Industries leverages its industrial coatings infrastructure to serve large-scale roadway and parking lot contracts. Sherwin-Williams anchors the professional contractor segment through its Glidden Professional brand and dedicated distribution network. Pioneer Athletics specializes in niche sports field applications where performance specifications exceed commodity requirements.
Field marking paint comprises pigmented coatings engineered for temporary to semi-permanent demarcation on asphalt, concrete, grass, and synthetic turf surfaces, with formulations typically specifying dry-to-touch times under thirty minutes and abrasion resistance measured by ASTM traffic paint standards. Water-based acrylic systems dominate new installations where low VOC compliance governs specification, while chlorinated rubber retains share in heavy-wear roadway markings where solvent durability outperforms environmental alternatives. Fast-drying formulations command premium positioning in stadium environments where game schedules compress application windows, and reflective grades concentrate margin pools in airport and highway applications where nighttime visibility standards apply.
EPA VOC regulations restrict solvent-based formulation sales in ozone non-attainment zones, while OSHA workplace exposure limits shape contractor handling protocols and personal protective equipment requirements. State environmental agencies in California and New York enforce stricter volatile compound limits than federal baselines, fragmenting formulation portfolios across geographic markets. Stakeholders must monitor evolving PFAS restrictions and bio-based content mandates that could force reformulation investments ahead of compliance deadlines.
Market Dynamics
EPA VOC regulations are forcing solvent-based chlorinated rubber formulations out of ozone non-attainment zones while water-based acrylic systems absorb volume, compressing application windows and reformulation cycles across municipal procurement channels.
Growth Catalysts
- Sun Belt Climate Concentration:Year-round outdoor sports activity in Texas, Florida, and Arizona sustains repaint frequency three to four times higher than northern states, anchoring volume demand for fast-drying formulations.
- ASTM D6132 Traffic Paint Standards:Updated abrasion resistance testing protocols are elevating specification thresholds for synthetic turf applications, disqualifying commodity suppliers from premium athletic field contracts.
- California Air Resources Board (CARB) Suggested Control Measure:Stricter VOC limits in the nation's largest state economy are accelerating water-based formulation transitions ahead of federal baselines, creating first-mover advantages for compliant suppliers.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment costs fluctuate with chloride process capacity constraints in Chinese production clusters, squeezing margin stability for formulation-dependent mid-tier suppliers.
- Solvent Durability Gap:Chlorinated rubber retains performance superiority in heavy-wear roadway markings where water-based alternatives fail ASTM scrub resistance thresholds, fragmenting portfolio requirements.
- OSHA Permissible Exposure Limits:Workplace handling protocols for solvent-based products impose personal protective equipment burdens and contractor training costs that slow field adoption despite technical performance.
Strategic Opportunities
- Reflective Grade Airport Applications:FAA nighttime visibility standards for runway and taxiway markings command premium positioning where glass bead incorporation justifies 40-60% price elevation over standard formulations.
- PFAS-Free Reformulation Mandates:Anticipated state-level restrictions on per- and polyfluoroalkyl substances in coatings create white space for early-compliant suppliers to capture specification lock-in ahead of enforcement deadlines.
- Direct Municipal Procurement Contracts:Bypassing sporting goods retail channels through dedicated park department agreements reduces margin leakage and enables multi-year volume commitments with predictable repaint scheduling.
Industry Challenges
- Application Technician Certification Gaps:Specialized spray equipment operation for synthetic turf demarcation requires training programs that municipal maintenance departments lack, slowing specification uptake.
- Legacy Inventory Stranded by Regulatory Shifts:Distributors holding solvent-based stock in transitioning markets face write-downs as EPA non-attainment zone designations expand without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Marking Paint Market |
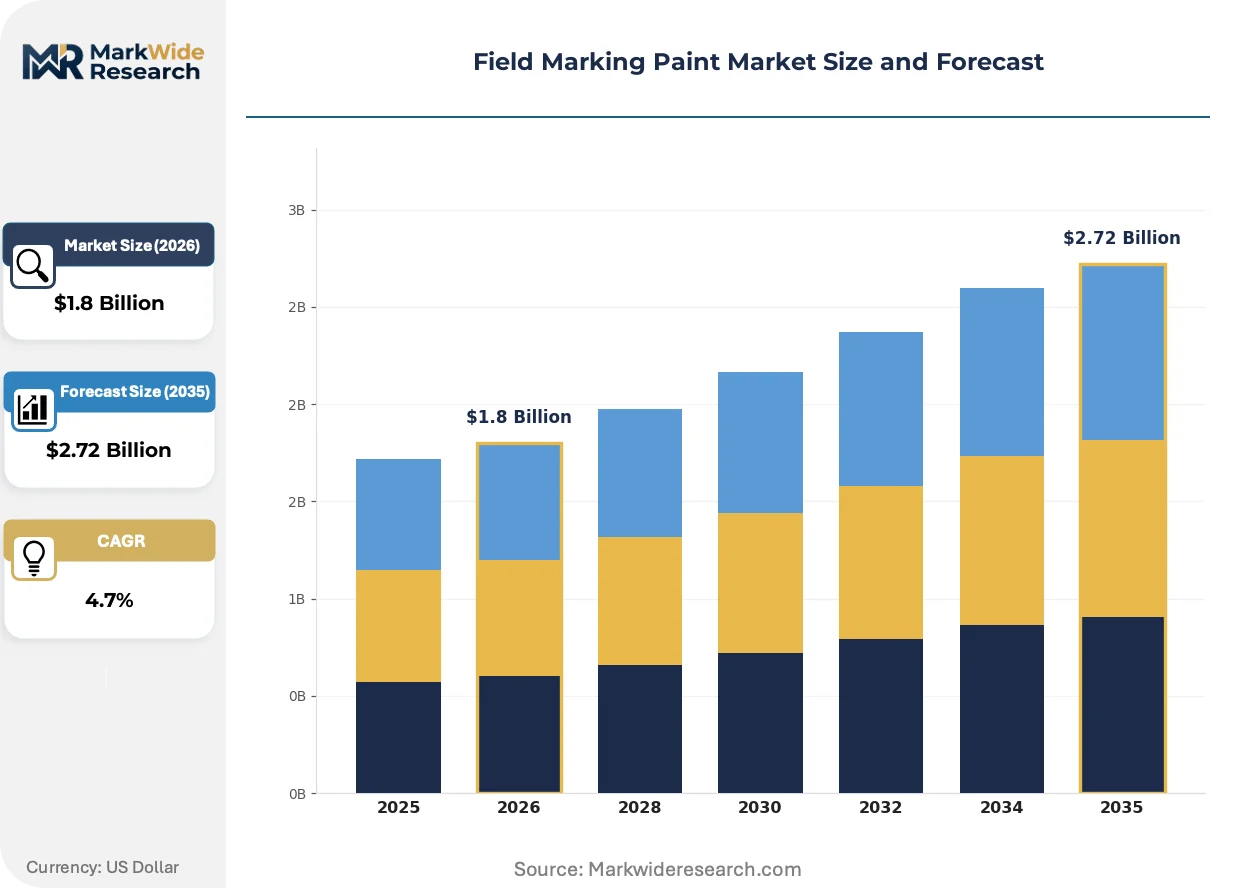
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Sports Fields, Parking Lots, Roadway Markings, Industrial Sites Base Material: Acrylic, Chlorinated Rubber, Water-Based, Solvent-Based Formulation: Reflective, Non-Reflective, Fast-Drying, Eco-Friendly End User: Stadiums, Municipalities, Construction Companies, Schools |
| Companies Covered | US Specialty Coatings, PPG Industries, Sherwin-Williams, Seymour, Pioneer Athletics, Glidden Professional, PGG Wrightson, Asphalt Line Striping, Hirshfield's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Marking Paint Market Evolving Landscape
Formulation chemistry and procurement architecture are undergoing parallel transformation as environmental compliance deadlines compress development cycles and buyer concentration reshapes channel economics.
Bio-based acrylic resin systems incorporating agricultural byproduct feedstocks are rendering obsolete petroleum-derived latex binders in municipal specifications. Park departments in Minnesota and Oregon have adopted these formulations for trail and field markings despite 15-20% cost premiums. The shift is compressing supplier R&D timelines as bio-content mandates approach in multiple state legislatures.
REACH Annex XVII restrictions on chlorinated solvents are eliminating rubber-based roadway marking options across EU member states and influencing formulation portfolios in export-oriented US manufacturers. Industrial coatings divisions serving multinational infrastructure contractors must maintain dual-compliant stock-keeping units. German KBA type-approval requirements for reflective highway markings are accelerating glass bead dispersion technology investments.
Consolidated purchasing cooperatives among county park districts are displacing fragmented individual municipal orders in the Midwest and Southeast. These aggregators negotiate multi-year framework agreements that lock out smaller regional paint distributors. The concentration is most visible in Ohio and Pennsylvania where intergovernmental purchasing alliances now control 30-40% of field marking volume.
Field Marking Paint Market Segmentation
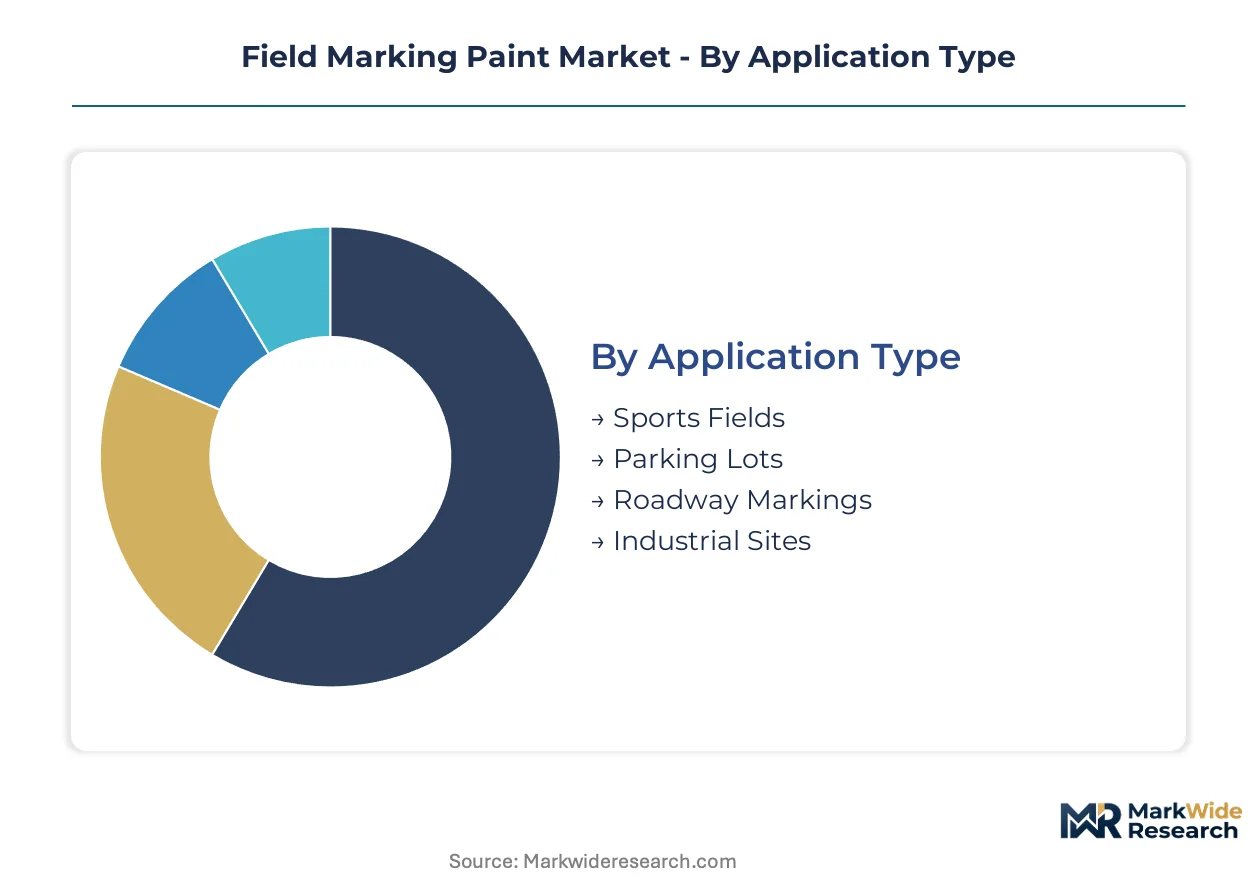
Field marking paint segmentation reveals how formulation chemistry, application environment, and procurement channel intersect to determine supplier positioning. Distinct performance thresholds across sports turf, highway, and industrial surfaces fragment specification requirements.
Application Type:
Mature municipal infrastructure segments coexist with emerging synthetic turf specializations, each demanding incompatible dry-time and durability specifications.
- Sports Fields:Fast-drying acrylic formulations dominate natural grass and synthetic turf installations where game schedules compress application windows to under four hours. Texas and Florida municipalities sustain repaint frequency three to four times higher than northern states due to year-round activity.
- Parking Lots:Chlorinated rubber retains share in heavy-wear commercial zones where ASTM scrub resistance thresholds exceed water-based performance. Demand concentrates in Sun Belt retail developments with high vehicle turnover.
- Roadway Markings:Reflective glass bead incorporation meets FAA and state DOT nighttime visibility standards, commanding premium positioning over standard formulations.
- Industrial Sites:Solvent-based systems persist in manufacturing facilities where chemical resistance and rapid cure times override VOC compliance priorities.
Sports Fields retains volume leadership; Parking Lots holds the steepest expansion curve as commercial development accelerates across southern states.
Base Material:
Cost tier stratification separates commodity petroleum-derived systems from emerging bio-based alternatives carrying 15-20% price premiums.
- Acrylic:Water-compatible resin systems anchor municipal procurement specifications where EPA VOC regulations restrict solvent alternatives. Minnesota and Oregon park departments have adopted bio-acrylic formulations for trail markings.
- Chlorinated Rubber:Solvent-carried chlorinated polymers deliver superior abrasion resistance in heavy-traffic roadway applications. REACH Annex XVII restrictions are eliminating this chemistry across EU member states.
- Water-Based:Low-VOC emulsion systems absorb volume from displaced solvent formulations in ozone non-attainment zones. California CARB limits accelerate transitions ahead of federal baselines.
- Solvent-Based:Hydrocarbon-carried systems retreat to industrial exemptions and heavy-wear segments where durability gaps persist. OSHA permissible exposure limits impose PPE burdens that slow contractor adoption.
Water-Based captures volume leadership; Acrylic climbs the fastest as bio-content mandates approach in multiple state legislatures.
Formulation:
Application window requirements and visibility standards create margin tiering across performance grades.
- Reflective:Glass bead dispersion technology meets FAA runway and taxiway specifications, justifying substantial price elevation over standard grades. German KBA type-approval requirements accelerate supplier R&D investments.
- Non-Reflective:Standard pigmented coatings serve daytime-visible applications in municipal parks and school grounds where budget constraints dominate specification.
- Fast-Drying:Accelerated cure formulations command premium positioning in stadium environments where game schedules compress maintenance windows. Dry-to-touch specifications under thirty minutes disqualify commodity suppliers.
- Eco-Friendly:Bio-based resin systems incorporating agricultural byproduct feedstocks render petroleum-derived alternatives obsolete in sustainability-mandated procurements.
Non-Reflective retains volume leadership; Eco-Friendly gains share fastest as PFAS-free mandates create specification white space.
End User:
Customer concentration reshapes channel economics as direct procurement displaces fragmented retail purchasing.
- Stadiums:Professional and collegiate athletic facilities demand fast-drying, high-visibility formulations with precise color matching for broadcast presentation. Compressed application windows between events drive premium grade specification.
- Municipalities:Consolidated purchasing cooperatives among county park districts now control substantial volume in Ohio and Pennsylvania, locking out smaller regional distributors through multi-year framework agreements.
- Construction Companies:Infrastructure contractors require dual-compliant stock-keeping units for multinational projects spanning EU and US regulatory jurisdictions.
- Schools:Budget-constrained K-12 districts prioritize cost-minimization over performance specifications, channeling demand toward economy-grade water-based systems.
Municipalities retain volume leadership; Stadiums holds the steepest expansion curve as collegiate athletic facility investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and municipal park networks across the United States anchor North American demand infrastructure for field marking applications. Federal surface transportation programs channel maintenance funding toward state DOT contracts, while Sun Belt athletic facility expansion sustains above-average repaint cycles.
United States
Texas, Florida, and Arizona sustain repaint frequency three to four times higher than northern states due to year-round outdoor sports activity. EPA VOC regulations in ozone non-attainment zones accelerate water-based formulation transitions ahead of federal baselines. The Dallas-Fort Worth metroplex concentrates municipal procurement volume through consolidated purchasing cooperatives.
Germany
REACH Annex XVII restrictions on chlorinated solvents eliminate rubber-based roadway marking options across EU member states. German KBA type-approval requirements for reflective highway markings accelerate glass bead dispersion technology investments. The Rhine-Ruhr industrial corridor anchors formulation R&D clusters serving export-oriented infrastructure contractors.
China
Titanium dioxide feedstock volatility from chloride process capacity constraints in Chinese production clusters squeezes margin stability for mid-tier suppliers. MEE enforcement of dual carbon goals pressures solvent-based formulation capacity in coastal provinces. The Yangtze River Delta concentrates industrial coatings manufacturing serving domestic airport and highway expansion.
Australia
ASTM D6132 traffic paint standards influence synthetic turf specification thresholds for premium athletic field contracts in professional sports venues. State-level environmental compliance frameworks in New South Wales and Victoria accelerate water-based acrylic adoption. The Sydney-Melbourne corridor concentrates stadium infrastructure investment driving fast-drying formulation demand.
Canada
Health Canada and PMRA oversight of coating formulations aligns with US EPA baselines while permitting provincial variation in VOC limits. Ontario and Quebec municipal park departments expand athletic field refurbishment programs through intergovernmental purchasing alliances. The Greater Toronto Area anchors volume demand for parking lot and roadway marking applications.
Field Marking Paint Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on formulation chemistry. The vendor base separates into consolidated industrial coatings divisions with multi-market infrastructure and niche sports field specialists with performance-specification expertise. Three archetypes dominate: diversified coatings conglomerates with municipal procurement scale, dedicated athletic field formulators with synthetic turf specialization, and regional distributors with contractor channel relationships. Competitive moves concentrate on direct municipal contract acquisition and PFAS-free reformulation pre-positioning.
Within the diversified coatings tier, PPG Industries and Sherwin-Williams occupy positions spanning industrial infrastructure and professional contractor channels. Pioneer Athletics exemplifies the niche specialist archetype, anchoring sports field applications where performance specifications exceed commodity requirements. These three represent the competitive spectrum from scale-driven municipal procurement to specification-locked premium positioning.
| Leading Market Players |
|---|
| US Specialty Coatings |
| PPG Industries |
| Sherwin-Williams |
| Seymour |
| Pioneer Athletics |
| Glidden Professional |
| PGG Wrightson |
| Asphalt Line Striping |
| Hirshfield's |
| Others |
Value Network & Pricing Analysis
Port of Houston freight corridors anchor titanium dioxide feedstock movements from Chinese chloride process clusters, with logistics cost volatility transmitting directly into formulation pricing tiers and downstream municipal procurement bid structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fast-drying stadium formulations from commodity water-based systems and budget-grade school district offerings. Price differentiation hinges on ASTM D6132 certification status and volume scale of multi-year municipal framework agreements. Cost compression in economy tiers is intensifying because schools prioritize budget constraints over performance specifications. School districts exhibit the highest price sensitivity; professional stadium operators accept substantial premiums for compressed application windows.
Supply Chain Analysis
Contract manufacturing concentration rests with PPG Industries and Sherwin-Williams industrial coatings divisions holding captive production capacity across Ohio, Texas, and California facilities. Raw material dependencies center on titanium dioxide pigment, acrylic resin feedstocks, and glass bead additives for reflective grades. Supply chain risk concentrates in single-source vulnerability for chloride-process titanium dioxide from Chinese production clusters. Distribution runs through direct municipal procurement contracts and dedicated contractor channels, bypassing sporting goods retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field marking paint demand follows cyclical recovery patterns tied to municipal capital expenditure cycles, with Sun Belt athletic facility refurbishment programs entering an upswing phase.
For Market Incumbents: Pre-empt PFAS-free specification lock-in by accelerating bio-acrylic reformulation investments ahead of state-level enforcement deadlines. Secure multi-year direct procurement contracts with consolidated county park purchasing cooperatives in Ohio and Pennsylvania to defend against mid-tier distributor displacement. Vertical integration into titanium dioxide sourcing buffers margin pressure from Chinese feedstock volatility.
For New Entrants and Emerging Players: Build out synthetic turf specialization capabilities targeting ASTM D6132-compliant premium athletic field contracts where commodity suppliers face disqualification. The penetrable white space sits in fast-drying formulation supply to collegiate stadiums with compressed maintenance windows. A go-to-market angle anchored on application technician training programs addresses municipal maintenance department capability gaps.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial coatings conglomerates seeking to divest non-core sports field segments. Long-term viability favors suppliers with dual-compliant formulation portfolios spanning US EPA and EU REACH jurisdictions. The signal to watch is CARB-compliant water-based specification adoption rates in California municipal procurements.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Reformulation Program | Early compliance with anticipated state restrictions secures specification lock-in ahead of enforcement deadlines. |
| Direct Municipal Contract Acquisition | Bypassing retail channels reduces margin leakage and enables multi-year volume commitments with predictable scheduling. |
| Application Technician Certification Program | Training infrastructure addresses municipal maintenance department capability gaps slowing synthetic turf uptake. |
| Backward Integration into Titanium Dioxide Sourcing | Captive pigment supply buffers margin pressure from Chinese chloride process capacity constraints. |
| Reflective Grade Glass Bead R&D Investment | FAA nighttime visibility standards command premium positioning in airport and highway marking applications. |
Research Methodology
Desk research of EPA regulatory filings, ASTM standards documentation, and municipal procurement databases preceded structured interviews with park department procurement managers, coatings plant managers, contractor equipment operators, and technical R&D directors at formulation suppliers. Primary fieldwork combined with secondary validation from SEC 10-K disclosures, trade customs data, and state environmental agency enforcement records. Bottom-up volume estimates triangulated against top-down market sizing across application segments.
Assumptions held fixed include EPA VOC regulatory baselines and ASTM D6132 abrasion resistance protocols; variables stress-tested encompass titanium dioxide feedstock cost trajectories and state-level PFAS restriction timelines. The analytical framework modeled formulation chemistry transitions, procurement channel shifts, and regional repaint frequency differentials across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating Sun Belt climate concentration effects and consolidated purchasing cooperative expansion patterns.
Stress conditions across titanium dioxide price volatility, regulatory enforcement acceleration, and municipal budget contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about water-based formulation transition rates and direct procurement channel penetration. Quarterly review of CARB regulatory updates, municipal bond issuance for park infrastructure, and chloride process capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
North America Feed Minerals Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
Chelated Iron Agriculture Micronutrient Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
South America Soil Treatment Market