
 Corn Thresher Market | 2026-2036
Corn Thresher Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Thresher Market Analytics
Market Dynamics
Electrification of small-scale farm equipment is tilting procurement patterns toward hybrid-capable threshing platforms. John Deere leverages its precision agriculture ecosystem to bundle threshers with telemetry-enabled fleet management tools. AGCO Corporation anchors its competitive stance through regional assembly hubs that shorten delivery cycles for African and Latin American buyers. CLAAS KGaA mbH differentiates via high-capacity axial-flow threshing technology optimized for wet corn conditions.
A corn thresher is a mechanical device that separates corn kernels from cobs and husks through rotary drum or axial-flow action, typically processing two to twelve metric tons per hour depending on power source and drum configuration. Its primary commercial purpose is to reduce post-harvest labor requirements and grain loss prior to drying and storage. Electric threshers now lead unit volume in electrified rural grids across South Asia, while gasoline threshers retain dominance in off-grid farming zones where fuel logistics outperform battery infrastructure. Multi-crop threshers command premium positioning as margin pools concentrate among equipment capable of switching between maize, sorghum, and millet without component swaps.
EPA emissions standards for small spark-ignition engines directly constrain gasoline thresher designs sold in the United States, while CE marking requirements under EU machinery directives enforce guarding and noise thresholds across European distribution channels. India's BIS certification mandates safety interlocks and operator protection structures for power-operated threshers sold domestically. Stakeholders must monitor evolving carbon-border adjustment mechanisms and electrification subsidy programs to calibrate regional product portfolios and powertrain investments.
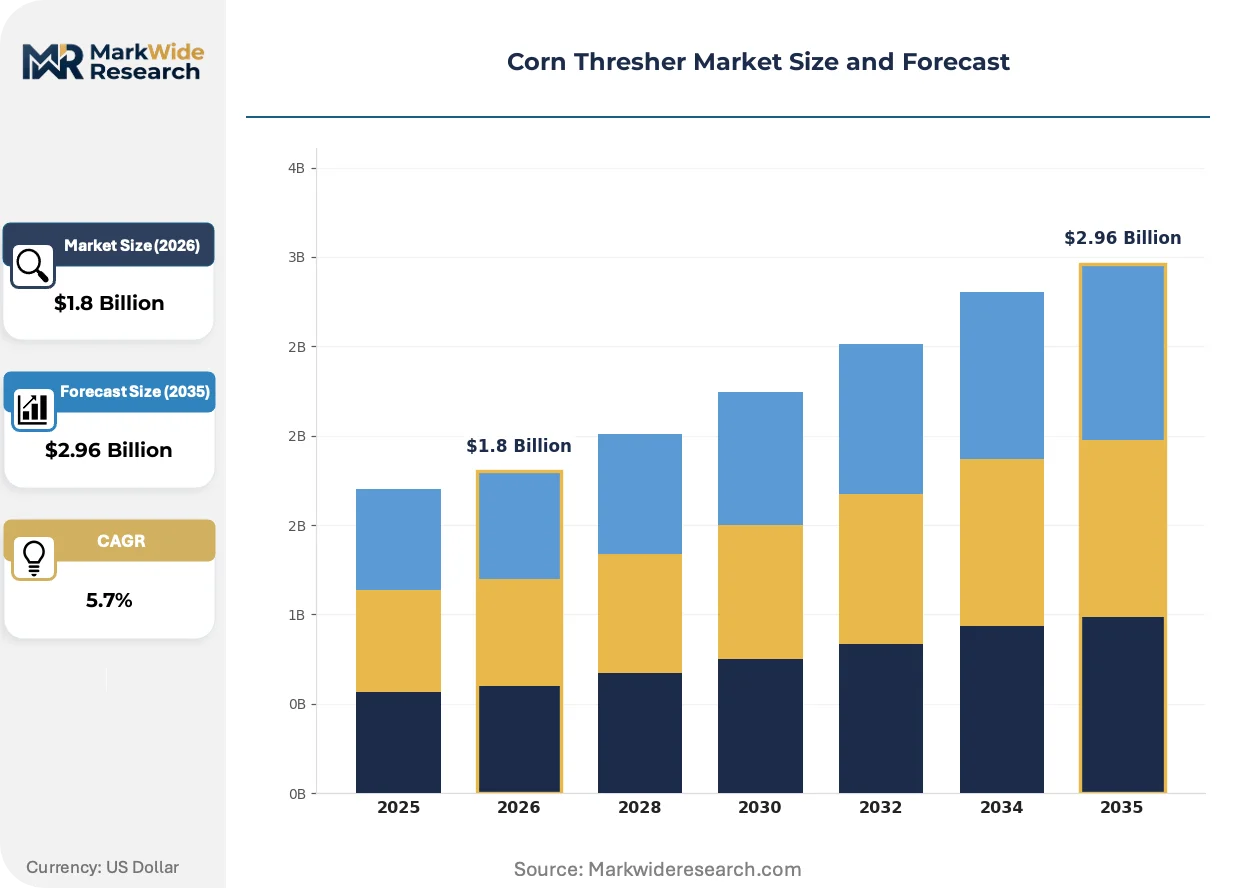
Market Dynamics
Electrification mandates and precision agriculture integration are compressing the traditional gasoline-powered thresher supply base while elevating telemetry-equipped platforms. Brazil's Mato Grosso corn belt and Sub-Saharan African cooperatives now anchor divergent procurement patterns around powertrain choice.
Growth Catalysts
- EU CE marking machinery directives:Safety and noise thresholds are accelerating replacement cycles across European distribution channels as farmers retire unguarded legacy equipment.
- Small holder cooperatives in Sub-Saharan Africa:Mechanized threshing adoption is expanding addressable volume as manual labor costs rise and post-harvest loss reduction becomes a priority.
- Hybrid-capable threshing platforms:Electrification of rural grids in South Asia is tilting procurement toward dual-powertrain machines that switch between electric and gasoline operation.
Market Restraints
- EPA emissions standards for small spark-ignition engines:Design constraints on gasoline threshers sold in the United States are compressing model variety and raising compliance costs for manufacturers.
- Battery infrastructure gaps:Off-grid farming zones in Sub-Saharan Africa and parts of South Asia retain gasoline dominance where fuel logistics outperform charging networks.
- Steel and aluminum input volatility:Drum and frame material costs fluctuate with commodity markets, pressuring margin stability for regional assembly operations.
Strategic Opportunities
- India's PLI scheme for farm mechanization:Domestic production incentives are creating white space for localized manufacturing of BIS-certified electric threshers.
- Multi-crop switching capability:Equipment capable of processing maize, sorghum, and millet without component swaps commands premium positioning in diversified smallholder markets.
- Telemetry-enabled fleet management:Convergence of IoT sensors and precision agriculture platforms is opening subscription revenue streams around predictive maintenance.
Industry Challenges
- Certification timeline compression:CE marking, BIS, and EPA approval processes run on mismatched cycles, complicating synchronized product launches across Brazil, India, and the United States.
- Axial-flow wet corn optimization:Engineering talent scarcity in high-capacity threshing technology limits rapid scaling of premium product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Thresher Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Threshers, Electric Threshers, Gasoline Threshers, Multi-Crop Threshers End User: Farmers, Agricultural Co-operatives, Large Scale Producers, Small Holders Capacity: Low Capacity, Medium Capacity, High Capacity, Extra High Capacity Distribution Channel: Online Retail, Agricultural Equipment Dealers, Direct Sales, Trade Shows |
| Companies Covered | John Deere, AGCO Corporation, CLAAS KGaA mbH, Mahindra & Mahindra Ltd., Kubota Corporation, Deluxe Agro Industries, ALMACO, Iseki & Co., Cimbria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Thresher Market Evolving Landscape
Telemetry integration and powertrain diversification are actively fragmenting the traditional thresher specification landscape. Equipment buyers now prioritize data connectivity and fuel flexibility over raw throughput metrics.
Axial-flow threshing technology optimized for wet corn conditions is rendering obsolete conventional rotary drum designs in high-moisture harvest zones. Large-scale farming operations in Brazil's Mato Grosso region are adopting these platforms at accelerated replacement cycles. The shift is compressing demand for legacy drum configurations while elevating manufacturers with proprietary wet-crop engineering capabilities.
REACH chemical compliance and EU machinery safety directives under CE marking are forcing redesigns of hydraulic fluids, surface coatings, and operator guarding systems. Manufacturers serving European distribution channels must reformulate material specifications and retool assembly lines. Wet corn axial-flow platforms face the steepest compliance burden due to their complex fluid systems and high-operator-interaction designs.
Cooperative procurement consortia are consolidating smallholder demand into volume tenders that bypass traditional dealer networks. Sub-Saharan African farming cooperatives and Indian state-level farmer producer organizations are driving this channel shift. Equipment financing bundled with threshing services is displacing outright purchase in Kenya and Maharashtra, compressing upfront price sensitivity while elevating total-cost-of-ownership analytics.
Corn Thresher Market Segmentation
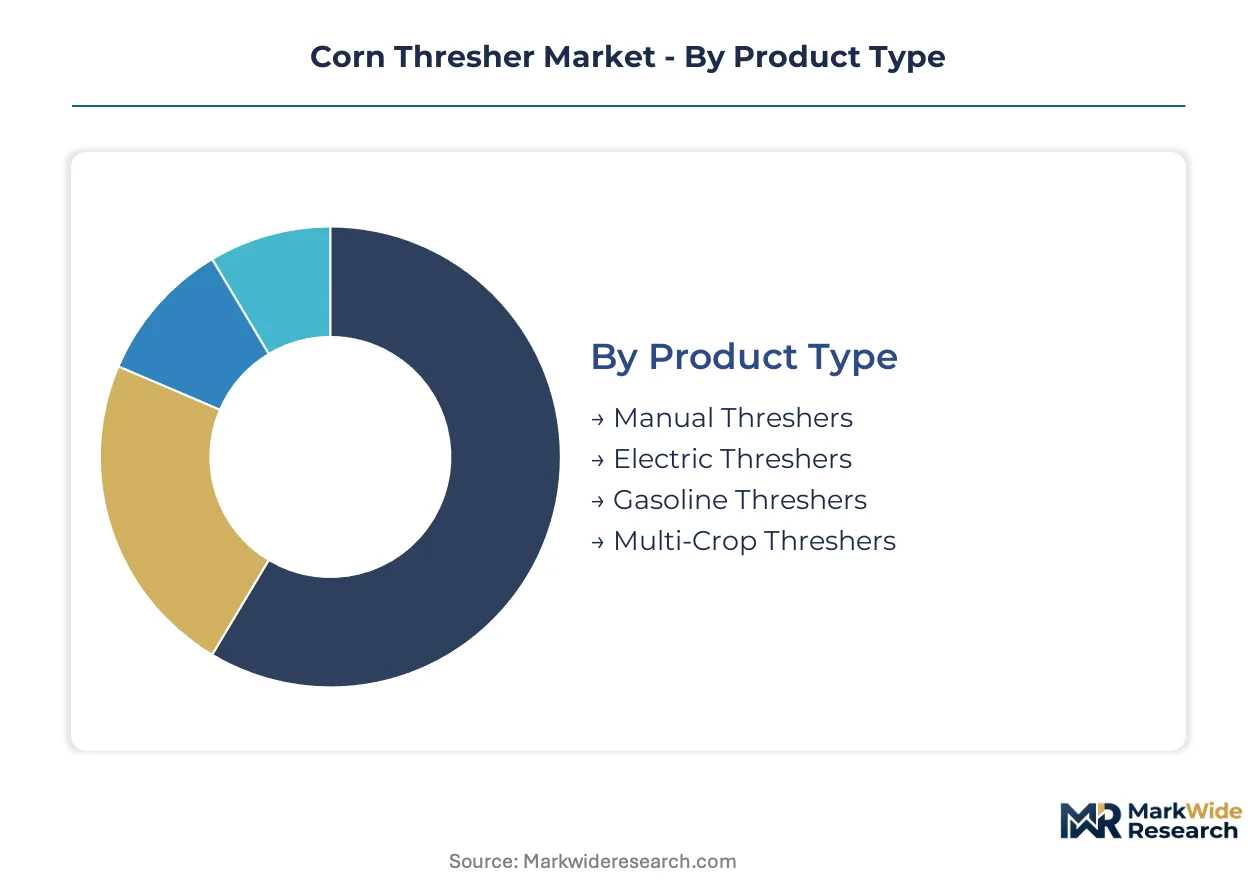
Corn thresher procurement patterns fragment sharply across powertrain technologies and operator scale, with after-sales service networks determining manufacturer stickiness in dispersed agricultural markets. Equipment specification diverges between electrified grids and fuel-dependent zones, creating distinct margin architectures for each segment cluster.
Product Type:
After-sales service intensity varies dramatically by powertrain complexity, with electric platforms requiring diagnostic software updates and gasoline units demanding spare parts logistics across remote farming corridors.
- Manual Threshers:Hand-operated wooden or metal devices processing under one metric ton per hour through rotary crank mechanisms. Demand concentrates among subsistence farmers in Ethiopia's highland regions and Nepal's hill districts where capital constraints and terrain inaccessibility block motorized alternatives.
- Electric Threshers:Grid-powered machines with 2-5 HP induction motors and belt-driven threshing drums rated for 2-4 metric tons hourly. Adoption accelerates in India's electrified rural zones under Bihar and Uttar Pradesh state grid extension programs, displacing manual labor where tariff subsidies reduce operating costs below gasoline equivalents.
- Gasoline Threshers:Portable spark-ignition units favored in off-grid farming belts across Zambia's Copperbelt and Myanmar's central dry zone where fuel distribution networks outperform battery charging infrastructure.
- Multi-Crop Threshers:Modular drum and concave systems enabling maize, sorghum, and millet processing without component replacement. Premium positioning in Nigeria's northern grain belt and Maharashtra's diverse smallholder markets commands 40-60% price premiums over single-crop equivalents.
By volume, gasoline threshers lead in Sub-Saharan Africa and South Asian off-grid zones. By growth pace, electric platforms are climbing the fastest in electrified South Asian cooperatives.
End User:
Customer scale determines financing modality and service contract structure, with cooperatives consolidating maintenance spend while individual farmers prioritize acquisition cost over lifecycle economics.
- Farmers:Individual owner-operators purchasing 2-5 HP units through dealer credit or microfinance arrangements. Procurement concentrates in Vietnam's Mekong Delta and Indonesia's East Java corn belts where household-scale processing dominates post-harvest workflows.
- Agricultural Co-operatives:Member-owned entities pooling capital for shared 10+ HP equipment with seasonal scheduling protocols. Mechanization adoption accelerates in Kenya's Rift Valley and Tanzania's Southern Highlands where cooperative procurement consortia bypass traditional dealer markups.
- Large Scale Producers:Commercial farming enterprises operating axial-flow platforms with 20+ metric ton hourly capacity and integrated telemetry. Demand anchors in Brazil's Mato Grosso corn belt and Ukraine's central black-soil regions where harvest windows compress and labor scarcity elevates automation premiums.
- Small Holders:Landholders under five hectares accessing threshing services through equipment-hire networks rather than outright purchase. Service-based access models expand in Bangladesh's northwestern districts and Ghana's northern region through NGO-facilitated pay-per-use arrangements.
Large scale producers generate the highest per-unit revenue. Small holders constitute the deepest volume pool through service-access models.
Capacity:
Throughput specification aligns with farm size distribution and harvest labor availability, with mid-range units dominating replacement cycles in transitioning agricultural economies.
- Low Capacity:Units processing 0.5-2 metric tons hourly, typically manual or sub-3 HP motorized designs. Market presence concentrates in Afghanistan's eastern valleys and Laos' upland maize zones where plot fragmentation limits equipment scale.
- Medium Capacity:3-8 HP machines achieving 3-6 metric tons hourly, representing the procurement sweet spot for emerging cooperative structures. Sales velocity peaks in Senegal's groundnut basin and Cambodia's Battambang province where medium-scale commercialization is displacing hand threshing.
- High Capacity:10-20 HP platforms with 8-15 metric ton hourly ratings and axial-flow or large-drum rotary configurations. Adoption concentrates in Argentina's Pampas and Romania's Transylvanian plains where contractor fleets serve dispersed medium farms.
- Extra High Capacity:Self-propelled or tractor-mounted systems exceeding 20 metric tons hourly with automated grain handling and real-time moisture sensing. Deployment centers on Iowa's corn belt and France's Champagne-Ardenne region where harvest logistics demand continuous-flow processing.
Medium capacity units dominate unit shipments. Extra high capacity platforms command the steepest expansion trajectory in precision agriculture integration zones.
Distribution Channel:
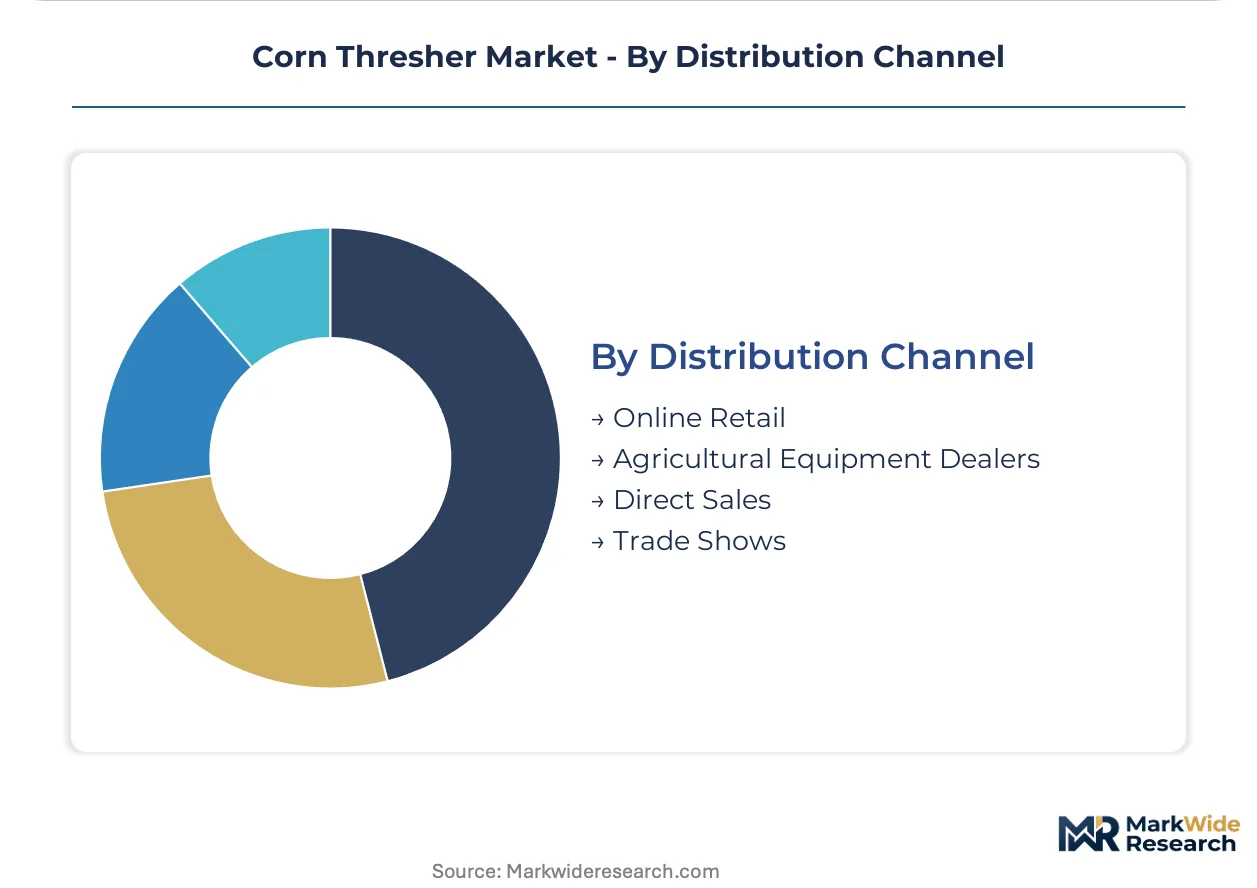
Channel selection reflects buyer sophistication and financing requirements, with dealer networks retaining service attachment advantages over direct and digital alternatives.
- Online Retail:E-commerce platforms aggregating small equipment sales with logistics partnerships for rural last-mile delivery. Traction builds in China's Taobao-served counties and India's agri-equipment portals where specifications are standardized and service expectations are minimal.
- Agricultural Equipment Dealers:Brick-and-mortar networks providing demonstration, credit facilitation, and spare parts inventory. Channel dominance persists in Mexico's Bajío region and Poland's Masovian Voivodeship where relationship-based procurement and seasonal maintenance contracts anchor supplier loyalty.
- Direct Sales:Manufacturer-to-farm transactions for large-scale and cooperative buyers, often bundled with training and extended warranty. Volume concentrates in South Africa's commercial maize sector and Australia's Darling Downs where procurement committees negotiate fleet purchases.
- Trade Shows:Seasonal exhibitions enabling side-by-side performance demonstrations and immediate order placement. Influence peaks at Brazil's Agrishow in Ribeirão Preto and India's Kisan Mela in Ludhiana where cooperative buyers consolidate annual procurement decisions.
Dealer networks capture the majority transaction value. Online retail is gaining share fastest among replacement part sales and standardized small equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports axial-flow threshing platforms to Argentina's Pampas region while Chinese manufacturers supply electric units to Bangladesh and Myanmar. India ships multi-crop designs to Nigeria's northern grain belt. Germany and Italy anchor European precision agriculture integration.
Brazil
Mato Grosso's corn belt drives replacement demand as contractors upgrade from drum to axial-flow wet-crop systems. ANVISA oversees agricultural machinery safety alongside INMETRO certification for electromagnetic compatibility. Ribeirão Preto hosts Agrishow, South America's largest equipment exhibition where cooperative buyers consolidate fleet procurement decisions.
India
Bihar and Uttar Pradesh state grid extensions accelerate electric thresher adoption among electrified rural cooperatives. BIS mandates safety interlocks and operator protection structures for all power-operated threshers sold domestically. Ludhiana's Kisan Mela anchors northern procurement patterns where Punjab and Haryana farmers compare multi-crop specifications side-by-side.
Germany
CE marking machinery directives enforce noise thresholds and guarding standards that accelerate legacy equipment retirement. KBA coordinates type-approval processes for self-propelled harvesting platforms. Baden-Württemberg's precision agriculture cluster integrates telemetry-enabled threshers into fleet management ecosystems.
United States
Iowa's corn belt demands extra-high-capacity continuous-flow processing for compressed harvest windows. EPA emissions standards for small spark-ignition engines constrain gasoline thresher designs and compress model variety. Nebraska's equipment dealerships bundle precision agriculture subscriptions with axial-flow platform sales.
China
MIIT's dual carbon goals tilt state procurement toward electrified farm equipment in grid-extended rural zones. GB standards govern agricultural machinery safety and electromagnetic compatibility for domestic sales. Shandong Peninsula manufacturers export medium-capacity electric threshers to Southeast Asian cooperatives through Taobao-served logistics networks.
Corn Thresher Market Competitive Landscape
On the supply side, the industry is bifurcated between precision agriculture integrators and regional assembly specialists. Tier-one players bundle telemetry-enabled fleet management with high-capacity platforms. Mid-tier fabricators compete on delivery velocity and localized certification compliance. Dominant competitive moves include geographic expansion through regional assembly hubs and portfolio diversification into multi-crop switching capability.
Among German precision agriculture specialists, CLAAS KGaA mbH exemplifies wet-crop engineering differentiation. John Deere and AGCO Corporation anchor the integrated ecosystem tier, representing bundled hardware-software platforms that lock in service contract renewal. These three companies occupy positions across premium specification vectors where axial-flow technology and telemetry convergence determine procurement committee selection.
| Leading Market Players |
|---|
| John Deere |
| AGCO Corporation |
| CLAAS KGaA mbH |
| Mahindra & Mahindra Ltd. |
| Kubota Corporation |
| Deluxe Agro Industries |
| ALMACO |
| Iseki & Co. |
| Cimbria |
| Others |
Value Network & Pricing Analysis
Undercapacity in axial-flow wet-corn engineering talent compresses supplier pricing power while elevating premiums for telemetry-integrated platforms, forcing procurement committees to trade off throughput specifications against connectivity bundles.
Pricing Analysis
Current-generation axial-flow platforms command substantial premiums over legacy rotary drum designs, while next-generation hybrid-capable units are entering at price points that bridge electric and gasoline alternatives. Three-tier pricing structure across premium telemetry-enabled, standard mechanized, and economy manual-equipment levels dominates procurement patterns. Price differentiation hinges on CE marking certification tier and after-sales service bundling intensity. Cost compression in economy gasoline threshers is intensifying because EPA emissions compliance raises engineering overhead. Small holder cooperatives exhibit highest price sensitivity, while large-scale Brazilian producers prioritize total-cost-of-ownership metrics over acquisition cost.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian markets dominates supply chain risk calculations for electric thresher components. Manufacturing concentrates in China's Shandong Peninsula, India's Ludhiana cluster, and Brazil's São Paulo industrial corridor. Steel drum forgings, aluminum frame extrusions, and induction motor assemblies anchor raw material dependencies. Single-source vulnerability in precision sensor modules for telemetry platforms threatens fleet management integration timelines. Distribution runs through agricultural equipment dealers with captive spare parts inventory, though cooperative direct procurement is displacing traditional channel markups in Sub-Saharan Africa and South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering scarcity in wet-crop axial-flow optimization and precision agriculture firmware development constrains competitive replication, privileging incumbents with captive R&D infrastructure and punishing latecomers without backward integration into threshing component fabrication.
For Market Incumbents: Insulate premium positioning by deepening captive production of axial-flow concave systems and telemetry sensor modules, neutralizing substitute threats from regional assemblers in India and China. Accelerate BIS and CE marking certification pipelines to compress new entrant timeline advantages. Vertical integration into precision agriculture software stacks locks in service contract renewal and elevates switching costs for Brazilian Mato Grosso contractor fleets. For New Entrants and Emerging Players: Pursue white-space penetration in multi-crop switching capability for Nigeria's northern grain belt and Maharashtra's diversified smallholder markets, where 40-60% price premiums reward modular engineering without component swap requirements. Target cooperative procurement consortia in Kenya's Rift Valley and Tanzania's Southern Highlands with equipment-as-a-service financing that bypasses upfront capital constraints. Anchor go-to-market through NGO-facilitated pay-per-use networks in Bangladesh and Ghana. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telemetry-enabled platform development, favoring asset-light regional assemblers with software partnership strategies over full-stack hardware investments. Long-term viability over the coming decade rests on convergence with precision agriculture ecosystems rather than standalone equipment margins. Acquisition target archetype: mid-tier fabricators with BIS-certified electric thresher production and established dealer networks in electrified South Asian grids. Watch for inflection in carbon-border adjustment mechanism implementation timelines affecting export competitiveness from high-emission manufacturing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Hub Expansion | AGCO's African and Latin American hubs compress delivery cycles for cooperative buyers. |
| Multi-Crop Switching Capability Development | Modular drum systems capture premium positioning in Nigeria and Maharashtra diversified markets. |
| Telemetry Platform Integration | John Deere's precision agriculture ecosystem locks in subscription revenue from predictive maintenance. |
| CE Marking Compliance Acceleration | EU machinery directives force legacy equipment retirement and open replacement demand. |
| Equipment-as-a-Service Financing | Pay-per-use models in Kenya and Maharashtra displace outright purchase and compress price sensitivity. |
Research Methodology
The analysis maps powertrain technology generations, end-user scale tiers, and distribution channel structures, each validated through equipment procurement managers at agricultural cooperatives, aftermarket service directors at regional dealer networks, plant engineers at thresher assembly facilities, and regulatory compliance officers at certification bodies. Primary interview findings triangulate against customs trade data for agricultural machinery, BIS and EPA certification filings, state-level grid extension program disclosures, and cooperative procurement tender databases. Bottom-up unit shipment estimates from country-level dealer networks reconcile with top-down market value calculations from manufacturer revenue disclosures.
Fixed assumptions across the projection horizon include continued rural grid extension in South Asia, stable EPA emissions standards for small spark-ignition engines, and persistent fuel logistics superiority over battery infrastructure in Sub-Saharan off-grid zones. Segmentation dimensions modeled encompass powertrain technology, operator scale, processing capacity tier, and regional regulatory cluster. CAGRs derive from logistic curve fitting to cooperative mechanization adoption rates and replacement cycle compression in precision agriculture integration zones. Forecast inputs include commodity price indices for steel and aluminum, and electrification subsidy program disbursement trajectories.
Macroeconomic conditions sit as an overlay; deviation in rural electrification investment flows, agricultural commodity price volatility, or carbon-border adjustment implementation intensity would shift the trajectory. Forecasts reflect documented assumptions about technology adoption curves and regulatory enforcement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Poultry Processing Equipment Market
Agricultural Processing Equipment
Pulp Wash Equipment Market
Agricultural Processing Equipment
Tobacco Drying Machines Market
Agricultural Processing Equipment
Rotary Drum Dryers Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Global Agricultural Harvesting Machinery Market
Agricultural Processing Equipment
Cashew Processing Machine Market
Agricultural Processing Equipment
Rice Milling Machines Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Global Square Straw Baler Market
Agricultural Processing Equipment
Corn Wet-Milling Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Global Threshers Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Global Feed Processing Market
Agricultural Processing Equipment
Rice Polishers Market