
 Meat Cutting Machine Market | 2026-2036
Meat Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Cutting Machine Market Foresight
Buyer concentration among large food processing plants is hardening as mid-sized processors merge or exit, concentrating procurement power with volume operators. Marel leverages its integrated software-hardware platforms to lock in multi-year service contracts with these consolidated buyers. GEA Group anchors its position through captive engineering networks across Northern European protein hubs. Baader Group specializes in fish-to-meat crossover cutting systems that differentiate its portfolio from pure-play competitors.
A meat cutting machine is an industrial or commercial device designed to section, slice, mince, or dice raw or processed protein using rotating blades, reciprocating knives, or continuous band saws operating at controlled speeds and temperatures. Band saws dominate installed base value due to their versatility across carcass breakdown tasks, though dicers command premium pricing in prepared-meals segments where portion uniformity drives yield recovery. Electric technology leads new equipment sales as plants retire pneumatic lines to cut energy intensity and maintenance downtime. Manual equipment persists in butcher shops where capital constraints and low throughput requirements limit automation appetite.
USDA FSIS sanitation performance standards and FDA Food Safety Modernization Act preventive controls mandate clean-in-place compatibility and material traceability, forcing redesign cycles among incumbent suppliers. CE marking under EU Machinery Directive and MDR-adjacent stainless-steel contact-surface rules constrain market access for non-European OEMs. Stakeholders must monitor evolving national hygiene codes and energy-efficiency benchmarks as procurement criteria shift from upfront cost toward total lifecycle compliance exposure.
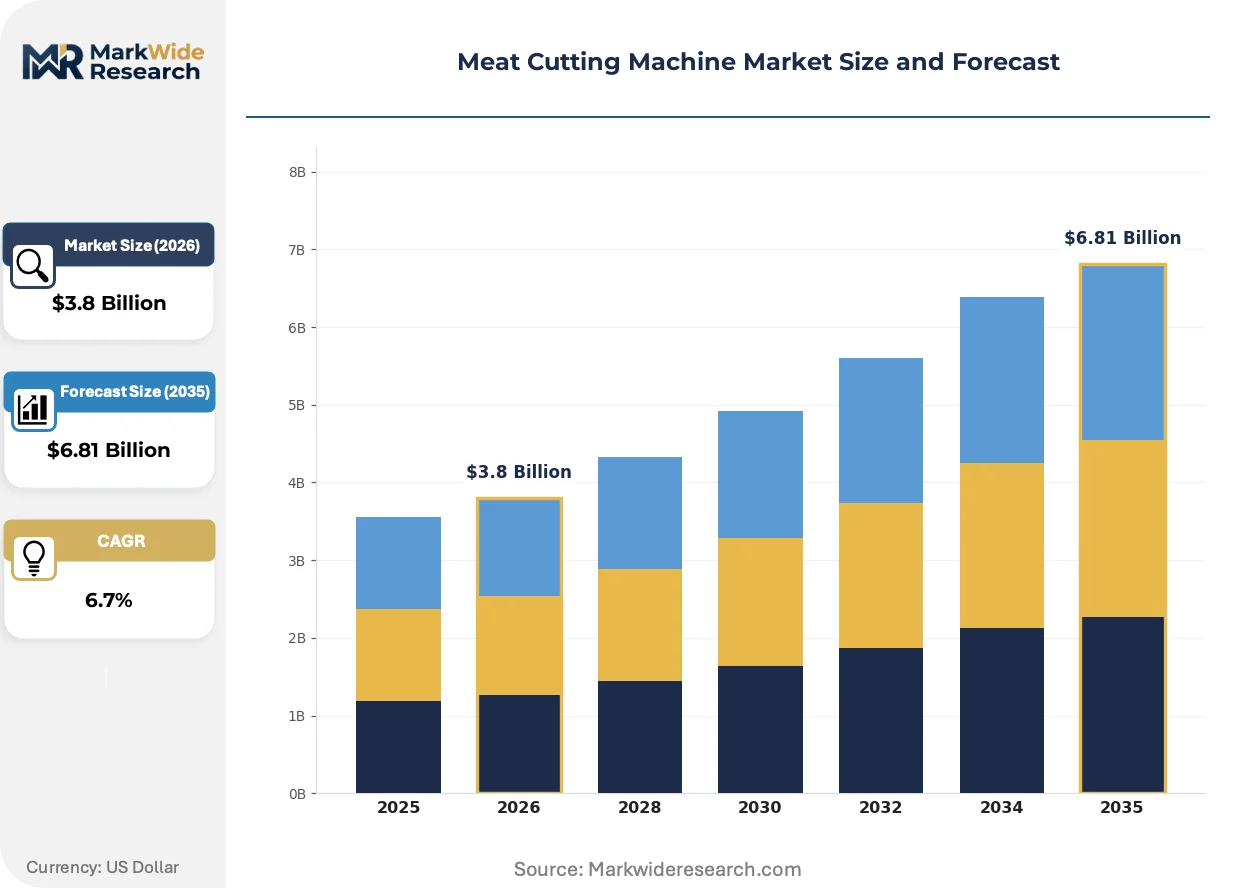
Market Dynamics
Automated cutting line retrofits are compressing replacement cycles as food processing plants race to meet throughput targets while absorbing USDA and FDA sanitation mandates that force material and design overhauls.
Growth Catalysts
- USDA FSIS Sanitation Performance Standards:Mandates for clean-in-place compatibility are forcing equipment upgrades across North American protein processing facilities, creating pull for stainless-steel contact-surface redesigns.
- Prepared-meals segment:Portion uniformity requirements in ready-to-eat protein products are driving premium dicer adoption where yield recovery justifies higher capital outlays.
- Electric motor technology:Plants are retiring pneumatic cutting lines to cut energy intensity and maintenance downtime, accelerating electric band saw and slicer procurement.
Market Restraints
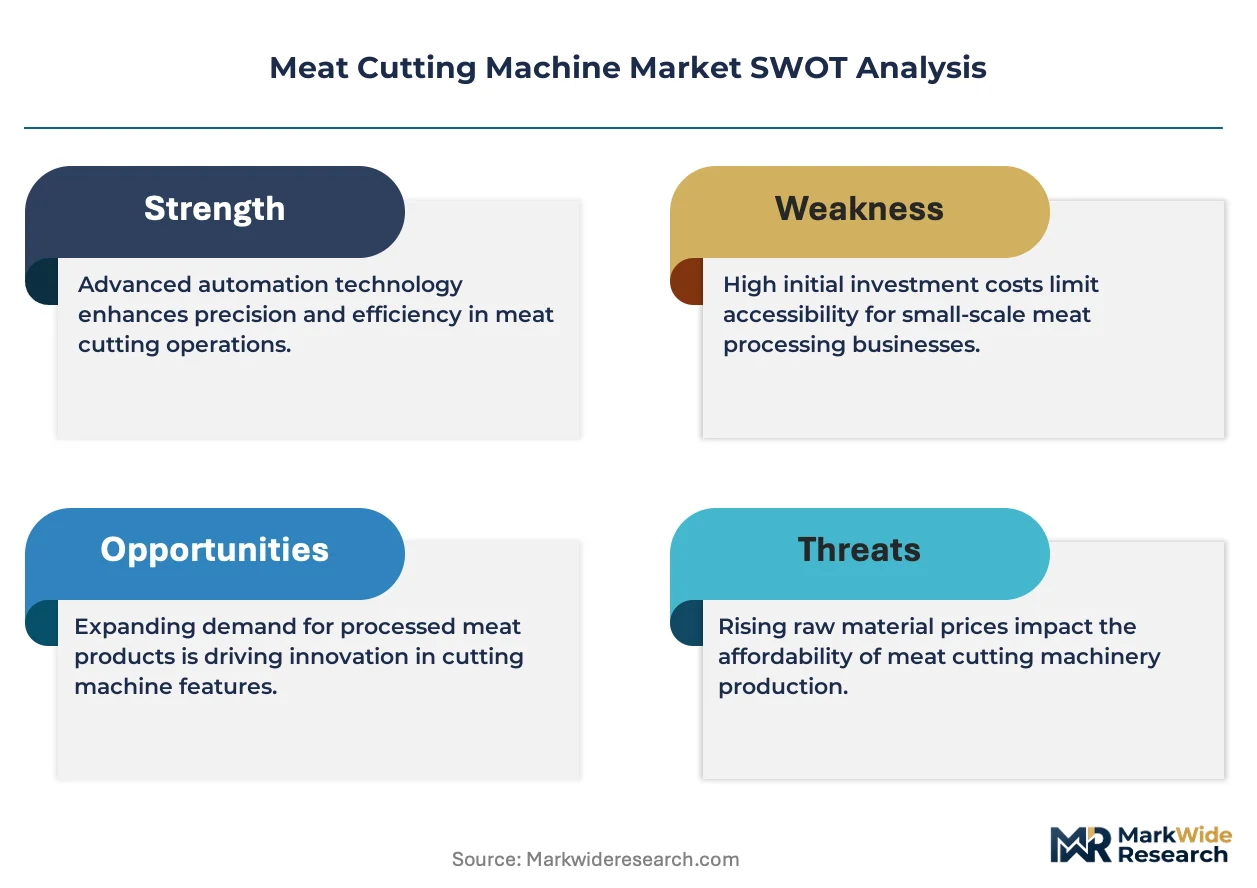
- Stainless-steel input volatility:Contact-surface grade 316L stainless pricing swings compress margin visibility for OEMs locked into fixed-price service contracts.
- German engineering concentration:Precision machining capability clusters in Baden-Württemberg and Bavaria, creating geographic supply risk for non-European buyers seeking CE-marked equipment.
- Manual equipment persistence:Capital-constrained butcher shops and small processors resist automation where throughput requirements fail to justify depreciation schedules.
Strategic Opportunities
- India FSSAI modernization:Cold chain infrastructure expansion and formalized meat processing create first-mover advantage for automated cutting line suppliers meeting BIS equipment safety standards.
- Robotics-vision convergence:Machine learning-enabled blade path optimization paired with collaborative robot arms opens precision portioning applications in high-variability carcass breakdown.
- EU Green Deal energy benchmarks:Motor efficiency tier upgrades under Ecodesign regulations create retrofit demand for variable-frequency drive integration in legacy cutting lines.
Industry Challenges
- Mechatronics technician scarcity:Servo-controlled blade positioning and HMI programming require skills absent in traditional maintenance workforces, extending commissioning timelines.
- CE marking documentation burden:EU Machinery Directive technical file compilation and Notified Body engagement add six-to-nine month certification delays for non-European OEMs.
- Legacy pneumatic integration:Hybrid retrofit projects face compressed air system incompatibility with electric cutting heads, forcing complete line replacement rather than component upgrade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Cutting Machine Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Band Saws, Meat Slicers, Mincers, Dicers Application: Commercial Kitchens, Butcher Shops, Food Processing Plants, Supermarkets End User: Chefs, Meat Processors, Retailers, Food Service Operators Technology: Manual, Electric, Hydraulic, Pneumatic |
| Companies Covered | GEA Group, Marel, JBT Corporation, Heat and Control, Baader Group, The Middleby Corporation, Bettcher Industries, Illinois Tool Works, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Cutting Machine Market Shifts & Advancements
Equipment architecture is fragmenting from monolithic lines toward reconfigurable subsystems that processors can redeploy across protein types and shift patterns without engineering intervention.
Band saw blade cartridge systems with quick-release tensioning and automated kerf compensation are modularizing breakdown operations in high-volume beef and pork plants. Mid-sized processors in the US Midwest are adopting these units to switch between carcass sizes within single shifts. This modularizing capability is compressing the capital threshold for automated portioning, eroding the volume advantage that historically anchored large-plant procurement power.
EU MDR-adjacent stainless-steel surface finish rules are tightening Ra value thresholds for protein contact zones, forcing abrasive media and passivation process investments among incumbent suppliers. German OEMs with captive finishing facilities are absorbing compliance costs faster than competitors reliant on third-party metal treatment. The prepared-meals segment faces the steepest retooling burden as dicer contact surfaces must meet both FDA preventive controls and EU medical-device-adjacent hygiene benchmarks.
Service contract unbundling is fragmenting the traditional bundled maintenance model as consolidated buyers demand à-la-carte spare parts access and self-service diagnostics. Large North American protein processors are negotiating direct blade and bearing supply agreements, bypassing OEM captive parts networks. This behavior is most pronounced in the US Southeast, where Tyson and JBS facilities have established independent procurement teams for consumables previously sourced through multi-year service agreements.
Meat Cutting Machine Market Segmentation
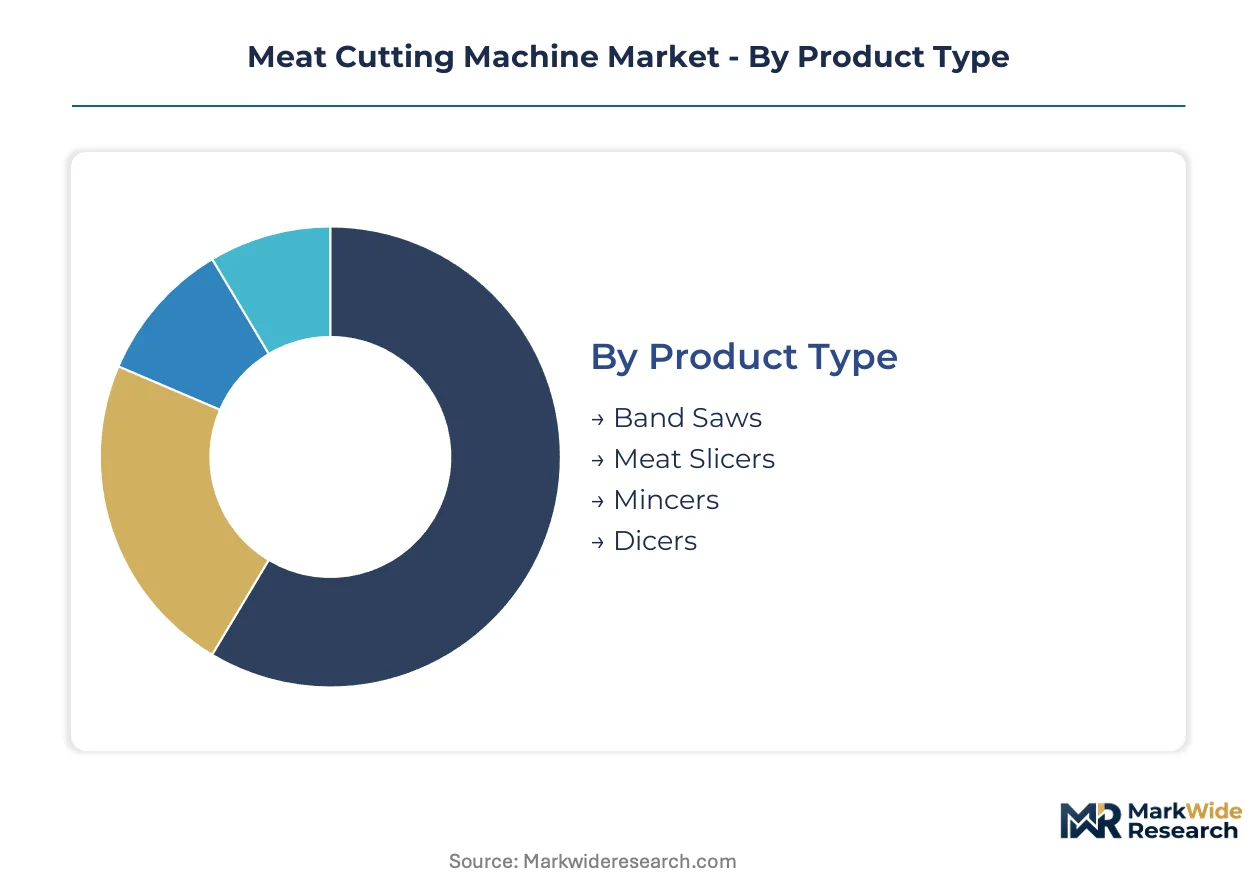
Segmentation in meat cutting machines reveals how protein handling requirements diverge across operational scales and regulatory exposure. Equipment specifications, power systems, and hygiene architectures must align precisely with end-user throughput demands and facility compliance obligations.
Product Type:
Volume operators prioritize different blade mechanics than precision portioning specialists, creating distinct procurement clusters across the installed base.
- Band Saws:Continuous loop blades mounted on tensioned wheels execute primal and subprimal breakdown across beef, pork, and lamb carcasses. Demand concentrates in high-volume Midwest US beef plants where USDA FSIS sanitation mandates favor stainless-steel frame construction with clean-in-place spray compatibility.
- Dicers:Grid knife assemblies produce uniform cubes for prepared-meals manufacturing where portion consistency directly impacts yield recovery. German precision-engineered units command premium positioning in EU facilities subject to MDR-adjacent surface finish regulations.
- Meat Slicers:Rotating blade or gravity-fed systems generate controlled thickness portions for deli and retail applications.
- Mincers:Auger-driven grinding mechanisms reduce muscle tissue to specified particle sizes for sausage and ground product lines.
Volume sits with Band Saws; growth tilts toward Dicers.
Application:
Facility scale and regulatory intensity segment buyers into four operational archetypes with divergent capital deployment patterns.
- Food Processing Plants:Industrial-scale automated lines integrate multiple cutting stations with centralized washdown systems and HACCP monitoring. North American protein giants in Nebraska and Texas drive procurement of electric band saw arrays with servo-controlled feed mechanisms to meet throughput targets under FDA FSMA preventive controls.
- Commercial Kitchens:Mid-volume operations in hotels, hospitals, and institutional catering require compact electric slicers and mincers with rapid sanitation cycles. US Southeast healthcare food service chains prioritize equipment with NSF certification for joint commission compliance.
- Butcher Shops:Small-scale artisanal processors favor manual or light-duty electric equipment where capital constraints limit automation appetite.
- Supermarkets:In-store meat departments demand versatile slicers with consumer-facing safety guards and quick-change blade systems.
Revenue concentrates in Food Processing Plants; expansion accelerates most rapidly in Commercial Kitchens.
End User:
Technical sophistication and procurement authority separate professional operators from retail intermediaries in equipment specification decisions.
- Meat Processors:Industrial operators with dedicated engineering staff specify integrated cutting lines with predictive maintenance diagnostics and spare parts inventory management. German Baden-Württemberg protein hubs anchor demand for CE-marked systems with captive service networks.
- Food Service Operators:Chain restaurant central kitchens and contract caterers prioritize standardized equipment platforms across multi-site footprints for technician cross-training efficiency.
- Chefs:High-end culinary professionals select precision slicers with adjustable blade angles for texture control in premium protein presentations.
- Retailers:Supermarket meat department managers balance equipment cost against labor productivity in high-turnover environments.
Procurement authority rests with Meat Processors; specification influence is climbing fastest among Food Service Operators.
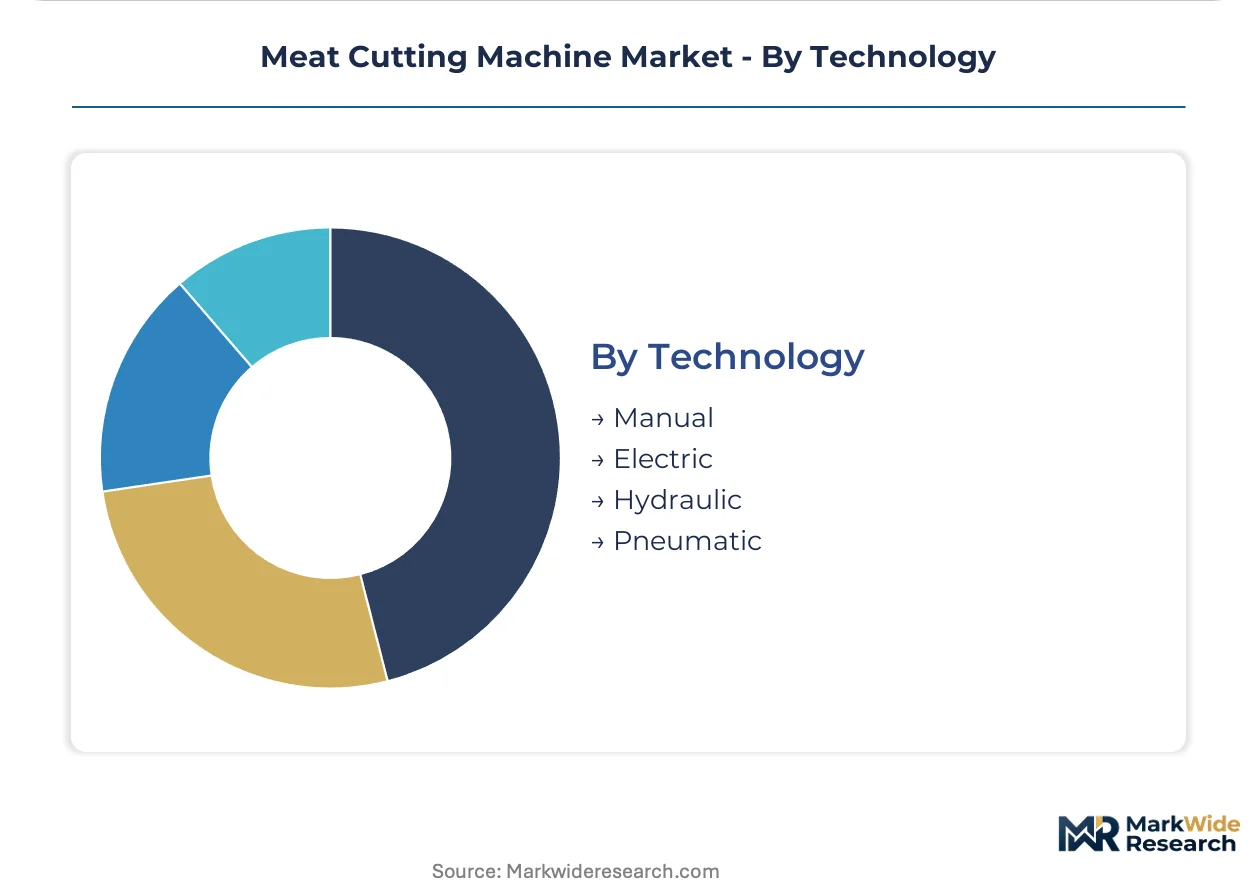
Technology:
Power system selection reflects energy cost trajectories and maintenance workforce capabilities across facility generations.
- Electric:Variable-frequency drive motors deliver precise speed control with reduced energy intensity versus legacy pneumatic systems. New equipment sales tilt heavily toward electric as North American plants retire compressed air infrastructure under Ecodesign efficiency benchmarks.
- Manual:Hand-cranked or gravity-fed mechanisms persist in artisanal butcher shops and developing market small processors where grid reliability and capital access constrain electrification.
- Hydraulic:Fluid power systems deliver high torque for dense bone-in cutting applications in select heavy-duty installations.
- Pneumatic:Compressed air drives remain in legacy lines facing complete replacement rather than component upgrade due to hybrid integration incompatibilities.
Installed base tilts toward Electric; Manual equipment retains stubborn persistence in specific geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for meat cutting equipment concentrates in industrial protein processing corridors where regulatory pressure and throughput requirements intersect. Facility operators in high-volume regions prioritize electric band saw arrays and dicer systems that satisfy both sanitation mandates and yield targets.
United States
Midwest beef processing plants in Nebraska and Iowa drive procurement of automated cutting lines with servo-controlled feed mechanisms. USDA FSIS sanitation performance standards mandate clean-in-place compatibility, forcing stainless-steel frame redesigns. Tyson and JBS facilities in the US Southeast have established independent procurement teams for consumables, bypassing traditional OEM service networks.
Germany
Baden-Württemberg and Bavaria anchor European demand for precision-engineered dicers and band saws with CE marking under EU Machinery Directive. MDR-adjacent stainless-steel surface finish rules tighten Ra value thresholds for protein contact zones. German OEMs with captive finishing facilities absorb compliance costs faster than competitors reliant on third-party metal treatment.
India
Cold chain infrastructure expansion and formalized meat processing create first-mover opportunity for automated cutting line suppliers. FSSAI modernization programs and BIS equipment safety standards reshape procurement criteria for domestic processors. Maharashtra and Gujarat protein hubs are retrofitting facilities with electric slicers and mincers as grid reliability improves.
China
Yangtze River Delta and Pearl River Delta processing clusters scale automated portioning to serve domestic prepared-meals manufacturing. GB standards for food machinery hygiene and SAMR equipment safety certification constrain market access for non-domestic OEMs. Local fabricators are displacing imported pneumatic lines with variable-frequency drive electric systems.
Brazil
São Paulo and Minas Gerais beef and poultry processors deploy heavy-duty band saw arrays for carcass breakdown under ANVISA sanitary surveillance requirements. Export-oriented facilities invest in CE-marked equipment to maintain European market access. Energy cost trajectories favor electric motor retrofits over legacy hydraulic cutting systems in new plant construction.
Meat Cutting Machine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular subsystem architectures that processors can redeploy across protein types. The vendor base stratifies across three maturity tiers: integrated platform providers with captive service networks, precision engineering specialists concentrated in Northern Europe, and regional fabricators serving price-sensitive developing markets. Dominant competitive moves include multi-year service contract bundling to lock in consolidated buyers and captive engineering network expansion to reduce commissioning timelines.
Among Northern European precision engineering groups, GEA Group and Marel exemplify the integrated platform archetype through software-hardware convergence and multi-year service agreements. Baader Group occupies a specialist position spanning fish-to-meat crossover cutting systems. These three anchors demonstrate how geographic engineering concentration shapes competitive positioning in CE-marked equipment procurement.
| Leading Market Players |
|---|
| GEA Group |
| Marel |
| JBT Corporation |
| Heat and Control |
| Baader Group |
| The Middleby Corporation |
| Bettcher Industries |
| Illinois Tool Works |
| Bühler Group |
| Others |
Supply & Pricing Matrix
EU MDR-adjacent stainless-steel surface finish rules gate qualified supply access for premium-tier meat cutting equipment, forcing OEMs with captive finishing facilities to absorb compliance costs faster than competitors reliant on third-party metal treatment. German precision-engineered dicers command pricing premiums against standard-tier band saws as CE marking documentation burdens and 316L input volatility compress margin visibility for non-captive suppliers.
Pricing Analysis
Volume operators capture thin margins on high-unit band saw sales while precision dicer specialists extract premiums from prepared-meals manufacturers where portion uniformity drives yield recovery. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked German systems with captive service networks from mid-tier electric retrofits and manual equipment for capital-constrained butcher shops. Pricing pressure stems from stainless-steel input volatility compressing fixed-price service contract profitability. Food processing plants in Nebraska and Iowa demonstrate lowest price sensitivity due to throughput-justified depreciation schedules, while small-scale artisanal processors in developing markets resist automation where capital constraints dominate procurement criteria.
Supply Chain Analysis
Freight cost escalation from Baden-Württemberg and Bavaria engineering clusters to North American protein hubs amplifies landed cost premiums for CE-marked equipment against regional fabricators. Manufacturing concentrates in Germany, China, and Brazil as local fabricators in the Yangtze River Delta displace imported pneumatic lines with variable-frequency drive electric systems. Supply chains draw from 316L stainless contact-surface grade, servo motor assemblies, and precision-machined blade cartridges. Single-source vulnerability concentrates in German precision machining capability clusters. Distribution runs through OEM captive service networks, though large North American processors increasingly negotiate direct blade and bearing supply agreements bypassing traditional bundled maintenance models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over captive stainless-steel finishing facilities and blade cartridge supply determines margin defense against service contract unbundling pressures.
For Market Incumbents: Deepen backward integration into 316L stainless surface finishing to absorb EU MDR-adjacent Ra value compliance costs faster than competitors reliant on third-party metal treatment. Expand captive engineering networks across Northern European protein hubs to compress commissioning timelines threatened by mechatronics technician scarcity. Lock in multi-year software-hardware platform contracts with consolidated buyers before modular subsystem entrants erode volume-advantage procurement power. For New Entrants and Emerging Players: Launch via direct-to-processor blade and bearing supply agreements targeting the US Southeast, where Tyson and JBS facilities have established independent procurement teams bypassing OEM captive parts networks. Target Maharashtra and Gujarat protein hubs in India as cold chain infrastructure expansion and FSSAI modernization create first-mover advantage for automated cutting line suppliers meeting BIS equipment safety standards. Pursue robotics-vision convergence partnerships for machine learning-enabled blade path optimization in high-variability carcass breakdown applications. For Investors and Strategic Acquirers: Service contract unbundling announcements from large North American protein processors are the leading indicator that traditional bundled maintenance models are fragmenting toward à-la-carte spare parts access and self-service diagnostics. Long-term viability favors acquisition targets with modular subsystem architectures that processors can redeploy across protein types without engineering intervention. Monitor captive finishing facility investments as signals of compliance cost absorption capability versus third-party-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Stainless-Steel Finishing Investment | EU MDR-adjacent Ra value rules tighten surface finish thresholds for protein contact zones. |
| Modular Subsystem Architecture Development | Quick-release blade cartridge systems compress capital thresholds for automated portioning. |
| Robotics-Vision Convergence Partnership | Machine learning-enabled blade path optimization opens precision portioning in variable carcass breakdown. |
| Direct Consumables Supply Agreement | Independent procurement teams at Tyson and JBS facilities bypass traditional OEM parts networks. |
| Variable-Frequency Drive Retrofit Program | Ecodesign energy benchmarks accelerate electric motor procurement as plants retire pneumatic infrastructure. |
Research Methodology
Multi-period observation of equipment replacement cycles, regulatory redesign timelines, and service contract restructuring anchored the trend analysis, supplemented by interviews with plant engineers at Midwest beef processing facilities, aftermarket service heads at OEMs, procurement managers at protein processing giants, and maintenance directors at commercial kitchen chains. Secondary validation drew from USDA FSIS sanitation performance standards documentation, FDA Food Safety Modernization Act preventive controls guidance, EU Machinery Directive technical file requirements, and SEC filings of publicly traded food processing equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down protein processing capacity expansion data.
Input-output matrices modeled installed base value and new equipment sales across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycle compression and forward projection of regulatory mandate adoption curves. Industry-specific forecast inputs included electric motor retrofit penetration rates and FSSAI modernization program implementation timelines.
Stainless-steel input price volatility, CE marking certification delays for non-European OEMs, and mechatronics technician scarcity are the dominant revision risks that could alter equipment procurement trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Processing Equipment
Harvesters Market
Agricultural Processing Equipment
Harvesting Equipment Market
Agricultural Processing Equipment
Rice Processing Machine Market
Agricultural Processing Equipment
Defeathering Machine Market
Agricultural Processing Equipment
Oil Mill Machine Market
Agricultural Processing Equipment
Screw Press Dewatering Machine Market
Agricultural Processing Equipment
Rice Polishers Market
Agricultural Processing Equipment
Grain Processing Equipment Market
Agricultural Processing Equipment
Corn Thresher Market
Agricultural Processing Equipment
Global Rice Milling Market
Agricultural Processing Equipment
Destemmer Machine Market
Agricultural Processing Equipment
Grain Handling Equipment Market
Agricultural Processing Equipment
Global Dry Milling Market
Agricultural Processing Equipment
Vegetable Dicing Machines Market
Agricultural Processing Equipment
Meat Processing Equipment Market
Agricultural Processing Equipment
Global Grain and Seed Cleaning Equipment Market