
 Feldspar Market | 2026-2036
Feldspar Market Size, Share, and Industry Trends Forecast 2026-2036
Feldspar Market Intelligence
Value-added processing of raw feldspar into high-purity micronized grades is reshaping competitive positioning within the supply chain. Sibelco leverages its global production footprint to supply consistent grades to multinational glass manufacturers. Imerys S.A. specializes in engineered mineral solutions for ceramics and fillers. Meanwhile, Eczacıbaşı Group dominates the Turkish market through its integrated mining and ceramics manufacturing operations.
Feldspar is a group of aluminosilicate minerals, containing elements such as sodium, potassium, or calcium, that form a key component of the Earth's crust. Its primary industrial function is as a flux, lowering the melting temperature of materials in applications like glass and ceramics. Potassium feldspar remains the dominant product type due to its suitability for high-quality ceramic glazes and bodies. Within applications, the glass manufacturing segment consumes the largest volume, while demand for fillers in paints and plastics is expanding.
Global quality consistency is guided by ISO 9001 standards, which are critical for suppliers. In Europe, the ECHA enforces REACH regulations, scrutinizing the chemical composition of feldspar grades. The U.S. EPA also sets permissible exposure limits for crystalline silica, often found in feldspar deposits, affecting mining and processing operations. Suppliers must now focus on securing long-term access to high-purity reserves to meet the increasingly stringent specifications of end-users.
Market Dynamics
The feldspar market's central dynamic is the increasing demand for high-purity, processed grades for industrial applications colliding with stringent environmental and chemical safety regulations that govern mineral extraction and use globally.
Growth Catalysts
- Glass Manufacturing Expansion:Demand from the glass sector, particularly for flat glass used in construction and automotive industries, requires consistent, high-volume supplies of feldspar as a critical fluxing agent to lower energy costs and improve production efficiency.
- Ceramics Hub in Turkey:The concentration of ceramic tile and sanitaryware manufacturing in Turkey creates a powerful regional demand center, pulling in significant volumes of both domestic and imported potassium and sodium feldspar.
- Value-Added Micronization:The development of processing techniques to produce micronized feldspar powders opens new applications as functional fillers and extenders in paints, plastics, and coatings, commanding higher price points than raw mineral grades.
Market Restraints
- Regulatory Compliance Burden:The European Union's REACH regulation imposes significant compliance costs and administrative burdens on producers and importers, requiring extensive chemical safety documentation for market access.
- Silica Exposure Limits:Regulations set by bodies like the U.S. EPA on permissible exposure limits for crystalline silica, a common impurity in feldspar deposits, increase operational costs for dust suppression and worker safety protocols.
- Reserve Quality Depletion:The finite availability of economically viable, high-purity feldspar deposits creates a long-term structural constraint, forcing miners to invest more in beneficiation to upgrade lower-quality ore.
Strategic Opportunities
- Functional Fillers Market:There is a significant opportunity to displace more expensive materials in the paints, plastics, and adhesives markets by promoting finely ground feldspar as a cost-effective functional filler that improves hardness and chemical resistance.
- High-Purity Electronics Grades:Developing ultra-pure feldspar grades with extremely low iron content presents an opportunity to supply specialized materials for manufacturing electronic display glass and other high-tech ceramic components.
- South American Construction Growth:Expanding into South American markets, where growing urban centers are driving demand for construction materials like glass and ceramic tiles, offers a new geographic growth vector for suppliers.
Industry Challenges
- Capital-Intensive Processing:Upgrading or building new beneficiation plants to produce the high-purity, micronized grades demanded by end-users requires significant capital expenditure, creating a barrier for smaller operators.
- Logistical Complexity:Managing the bulk transportation of feldspar from often remote mining locations to industrial centers is logistically complex and constitutes a major component of the final delivered cost.
- ISO 9001 Certification:Achieving and maintaining ISO 9001 quality management certification, a prerequisite for supplying multinational glass and ceramics manufacturers, involves a rigorous and continuous commitment of resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feldspar Market |
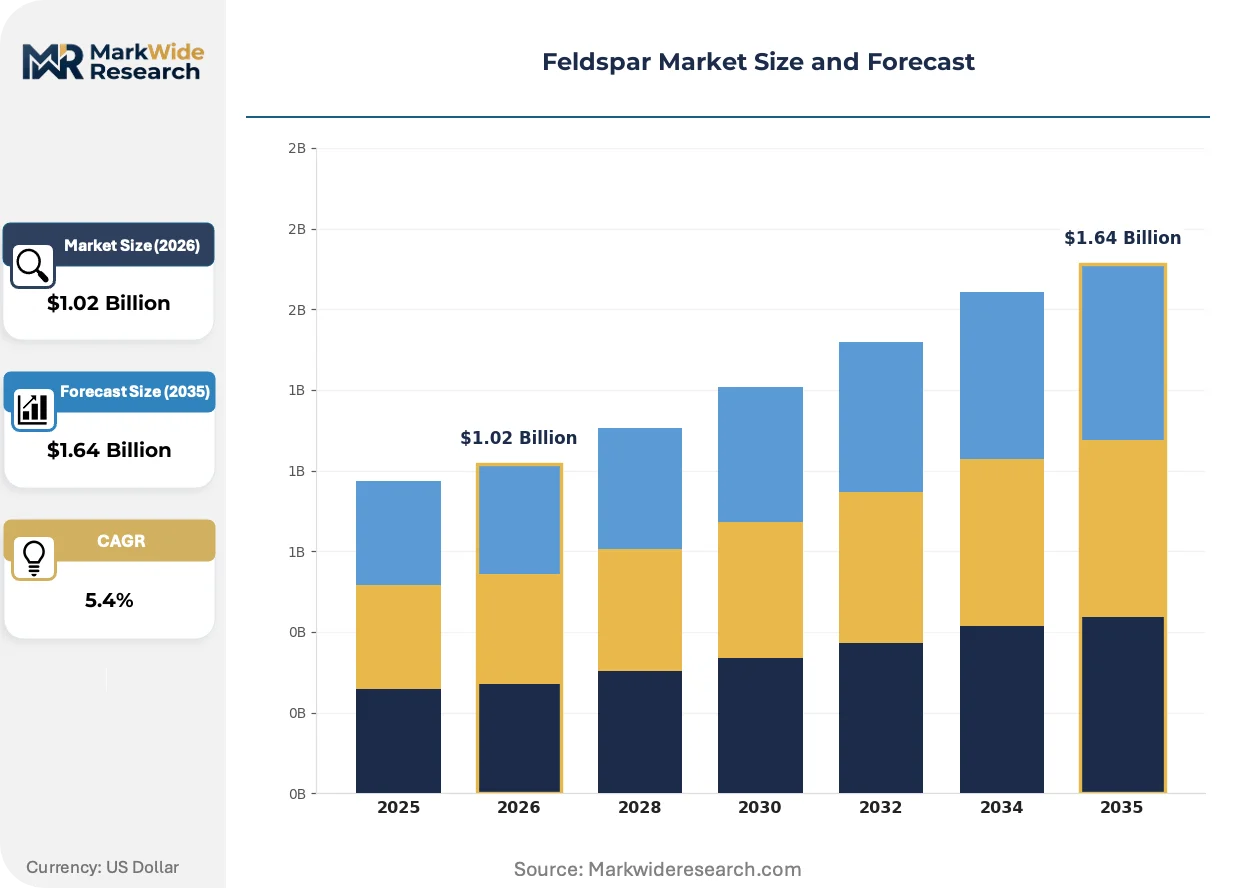
| Market Size in 2026 | $1.02 Billion |
| Market Size in 2035 | $1.64 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Feldspar, Sodium Feldspar, Calcium Feldspar, Alkali Feldspar Application: Ceramics, Glass Manufacturing, Fillers, Paints, Plastics, Adhesives End Use Industry: Construction Material Suppliers, Glassware Manufacturers, Paint Companies, Polymer Producers Form: Powder, Granules, Coarse Grains, Lump |
| Companies Covered | The Quartz Corp, Gimpex, Imerys S.A., Eczacıbaşı Group, Micronized Group, Sibelco, LB MINERALS, Ltd., Sun Minerals, Quarzwerke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feldspar Market Strategic Shifts & Innovations
The feldspar industry is undergoing a shift toward greater precision in processing and supply chain traceability. This movement is driven by end-user demands for tighter chemical specifications and a complex global regulatory landscape that scrutinizes mineral sourcing and composition.
Advanced sensor-based sorting technologies are being implemented in feldspar beneficiation plants. Glass and ceramics manufacturers, who require exceptionally tight control over mineral chemistry to ensure product consistency, are driving adoption. This technology is digitizing the quality assurance process, enabling real-time adjustments and shifting quality control from post-production batch testing to in-line, continuous monitoring.
European chemical safety regulations, specifically REACH as enforced by ECHA, mandate comprehensive data on the composition and potential hazards of industrial minerals. This forces suppliers to conduct extensive testing and provide detailed safety data sheets for all feldspar grades sold into the EU market. The ceramics and glass industries are most affected, as they must validate the compliance of their entire raw material supply chain.
A preference shift is occurring among major industrial consumers toward suppliers who can guarantee globally consistent product quality and supply chain security. This trend disadvantages smaller, regional mining operations that lack the resources for broad-based ISO 9001 certification or sophisticated quality control systems. The consolidation of procurement is most evident among multinational glass manufacturers in North America and Europe.
Feldspar Market Segmentation
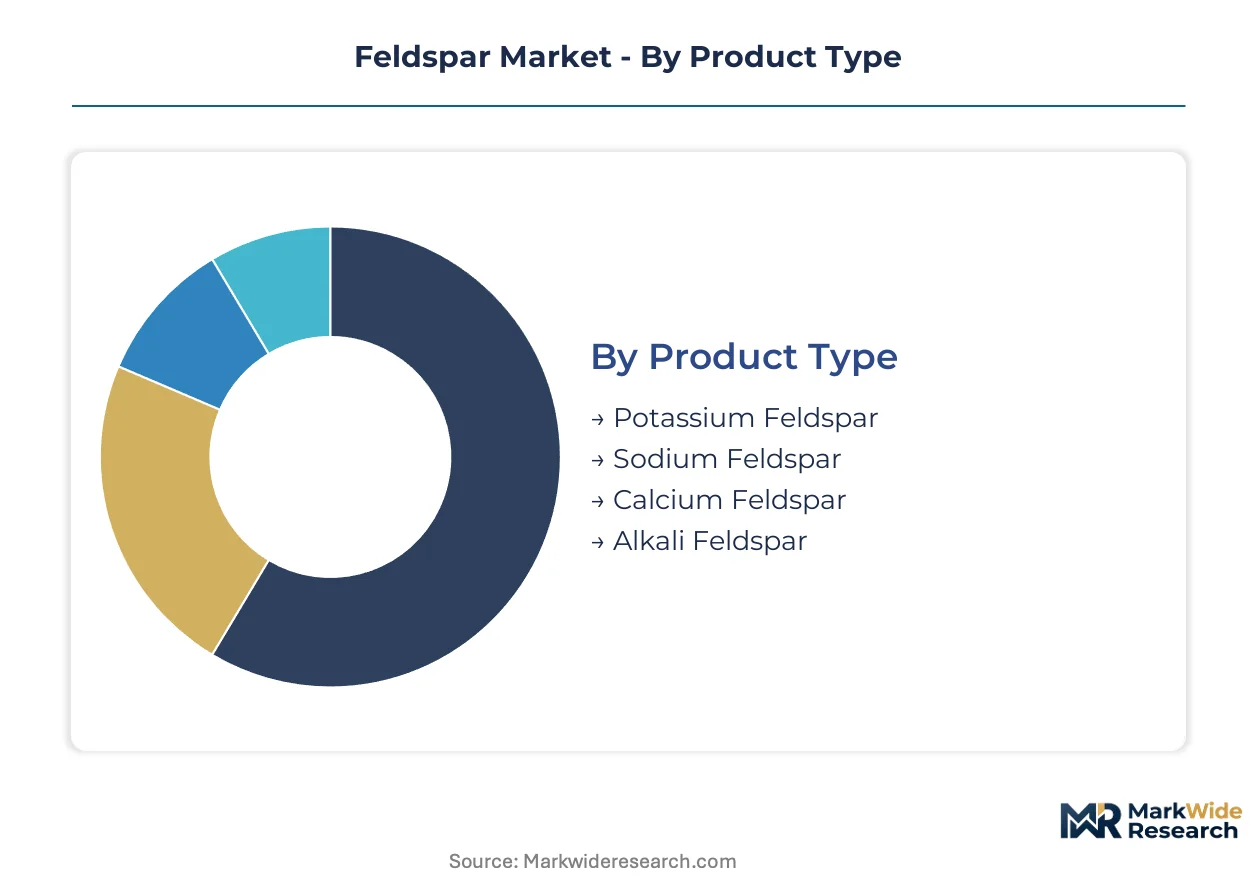
The feldspar market's segmentation highlights diverse material specifications and processing requirements across industrial applications. Understanding these distinctions is crucial for suppliers to align production capabilities with specific end-user demands for purity, particle size, and chemical composition. This breakdown enables strategic targeting of high-growth sectors and identification of specialized product niches.
Product Type:
The after-sales service intensity for feldspar product types varies significantly based on their chemical consistency and required purity levels for end-use. High-purity grades often necessitate more rigorous technical support and certification documentation.
- Potassium Feldspar:This aluminosilicate mineral contains potassium and is valued for its high melting point and excellent fluxing properties in ceramic glazes and bodies. Demand concentrates in the European ceramics industry due to its suitability for high-quality tile production and consistent material performance.
- Sodium Feldspar:Characterized by its sodium content, this type offers a lower melting temperature compared to potassium feldspar, making it ideal for glass manufacturing and certain ceramic applications. The glass sector in North America requires consistent, high-volume supplies to optimize furnace efficiency.
- Calcium Feldspar:Containing calcium, this feldspar variant is often used in specific ceramic formulations and as a minor fluxing agent where its unique thermal properties are beneficial.
- Alkali Feldspar:This category encompasses both sodium and potassium feldspars, or mixtures thereof, providing flexibility in industrial applications based on desired alkali content and melting characteristics.
Potassium Feldspar holds the largest share; momentum sits with Sodium Feldspar due to its expanding use in glass.
Application:
Application diversity within the feldspar market reflects the mineral's critical role as a fluxing agent and functional filler across various industrial processes. Each application requires specific particle sizes and chemical compositions.
- Glass Manufacturing:Feldspar lowers the melting temperature of silica during glass production, reducing energy consumption and improving melt viscosity for flat glass and container glass. Demand for this application dominates in the European Union, driven by robust automotive and construction sectors.
- Ceramics:In ceramic bodies and glazes, feldspar acts as a flux, promoting vitrification and enhancing strength, gloss, and durability in tiles, sanitaryware, and tableware. Turkish ceramic producers rely heavily on high-grade feldspar concentrates to meet export quality standards.
- Fillers:Finely ground feldspar serves as an inert, cost-effective filler in various products, improving mechanical properties and reducing raw material costs.
- Paints:As a functional filler in paints, feldspar enhances hardness, abrasion resistance, and chemical stability, contributing to the durability of coatings.
- Plastics:Micronized feldspar improves the stiffness, dimensional stability, and scratch resistance of plastic compounds, particularly in engineering plastics.
- Adhesives:Feldspar adds body and reinforces adhesive formulations, contributing to improved bond strength and reduced shrinkage in certain specialty adhesives.
Glass Manufacturing commands the largest volume, while the Fillers segment is expanding most quickly.
End Use Industry:
Customer type in the feldspar market dictates procurement volumes, quality specifications, and the complexity of logistical arrangements. Large industrial consumers often require direct supply agreements and rigorous quality control protocols.
- Construction Material Suppliers:These entities procure feldspar primarily for manufacturing flat glass, ceramic tiles, and other building components where volume and consistent quality are paramount. The rapidly urbanizing markets in South America present significant growth opportunities for these suppliers.
- Glassware Manufacturers:Producing items from bottles to specialty glass, these manufacturers demand high-purity feldspar with strict iron content limits to ensure optical clarity and product integrity. Multinational glassware companies in Europe prioritize suppliers with ISO 9001 certification.
- Paint Companies:Utilizing feldspar as a functional extender, paint companies seek finely ground grades that enhance coating properties and provide cost advantages.
- Polymer Producers:As an additive in various plastics, polymer producers require specific feldspar particle sizes and surface treatments to improve material performance.
Construction Material Suppliers generate the highest demand, with Polymer Producers showing strong growth.
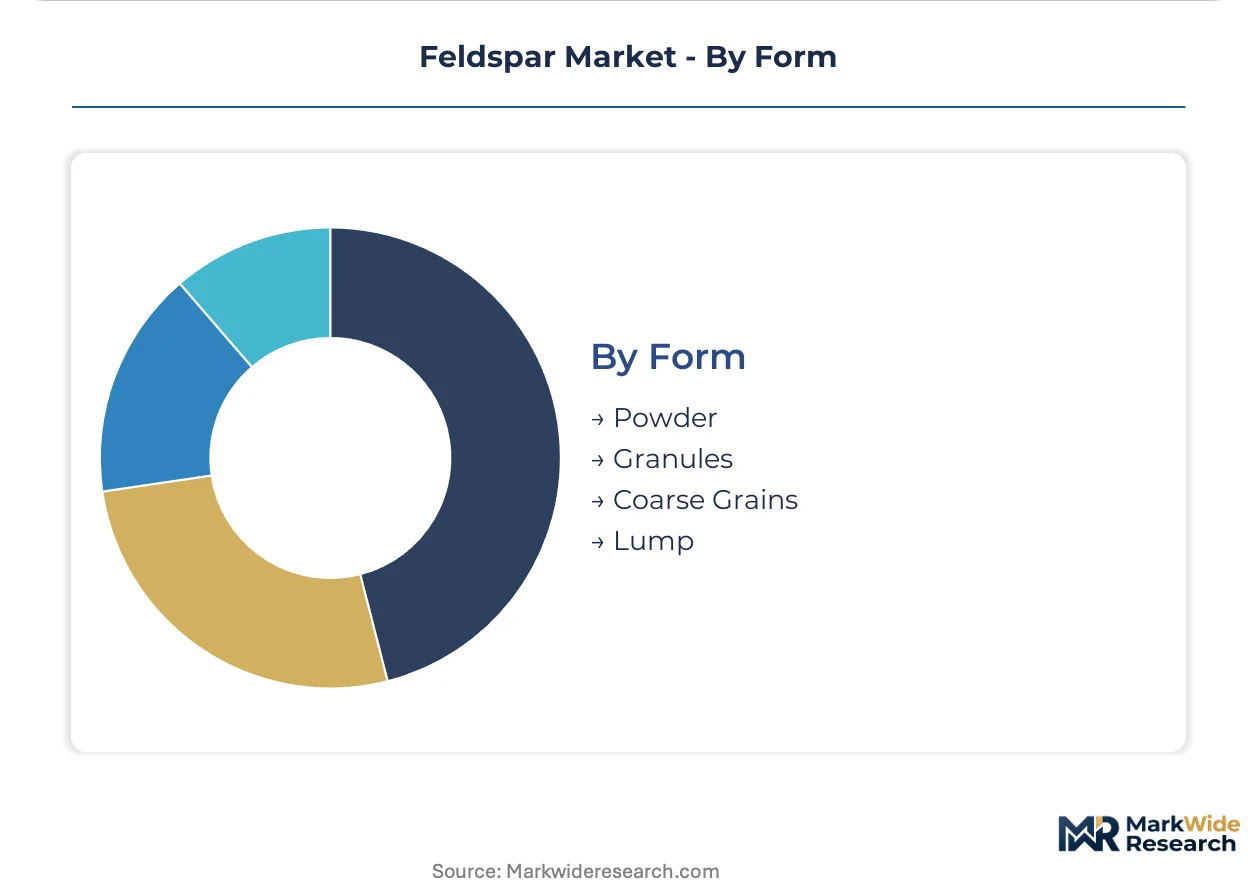
Form:
The maturity of feldspar processing technologies directly influences the available forms of the mineral, ranging from raw extracted material to highly engineered powders. Each form serves distinct industrial requirements.
- Powder:This highly processed form involves micronization, offering precise particle size distribution for applications demanding superior surface area and reactivity, such as advanced ceramics and functional fillers. The development of ultra-pure grades for electronics is a key innovation.
- Granules:Granular feldspar provides a more controlled particle size than coarse grains, suitable for consistent feeding into industrial processes like glass furnaces and certain ceramic body formulations. Global quality consistency standards, like ISO 9001, are critical for granular supply.
- Coarse Grains:Representing a less processed form, coarse grains are used where exact particle size is less critical, often in bulk applications or as an intermediate processing stage.
- Lump:This is the rawest form of feldspar, directly extracted from the mine, typically requiring further crushing and beneficiation before industrial use.
Powdered feldspar offers the highest value, while granular forms maintain stable industrial consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply of feldspar often concentrates around major mining regions, shaping the accessibility and cost for industrial consumers globally. This geographic concentration influences trade flows and compels end-users to secure diverse sourcing strategies for critical raw materials. Regulatory frameworks in key consuming nations also dictate material specifications and processing requirements.
Turkey
Demand for feldspar in Turkey is driven by its robust ceramic tile and sanitaryware manufacturing sectors, which require consistent, high-grade materials. The Turkish Ministry of Energy and Natural Resources oversees mining permits and environmental compliance for feldspar extraction. The ceramic production hub in Bilecik and Kütahya utilizes significant volumes of potassium and sodium feldspar to meet export quality standards.
Germany
German glass and ceramics manufacturers require high-purity feldspar for automotive glass, specialty ceramics, and high-quality glazes. The European Union's REACH regulation, enforced by ECHA, mandates stringent chemical safety documentation for all feldspar grades imported or produced in Germany. Industrial clusters in Bavaria and North Rhine-Westphalia are major consumers, focusing on advanced material applications.
United States
The United States glass and construction industries consume substantial volumes of feldspar, particularly for flat glass and fiberglass insulation. The U.S. EPA sets permissible exposure limits for crystalline silica, impacting feldspar mining and processing operations in states like North Carolina and South Dakota. Manufacturing facilities in Ohio and Pennsylvania depend on reliable feldspar supplies for their glass production lines.
China
China's expansive construction and ceramics industries generate immense demand for feldspar, used in ceramic tiles, sanitaryware, and various glass products. The Ministry of Ecology and Environment (MEE) implements strict environmental protection policies that influence mining practices and beneficiation processes. Industrial zones in Guangdong and Shandong provinces are significant consumers, supporting large-scale manufacturing operations.
India
India's rapidly expanding infrastructure and housing sectors drive demand for feldspar in ceramic tiles, sanitaryware, and container glass production. The Bureau of Indian Standards (BIS) sets quality specifications for industrial minerals, including feldspar, used in domestic manufacturing. Ceramic clusters in Morbi, Gujarat, and glass manufacturing units in Uttar Pradesh rely on local and imported feldspar resources.
Feldspar Market Key Industry Players
Integrated mineral producers and specialized processing firms split the feldspar market, with each archetype serving distinct segments of the industrial supply chain. The market structure exhibits a tiered approach, where large multinational corporations leverage global footprints, while regional players focus on specific geographic or application niches. Dominant competitive moves include strategic acquisitions to secure high-purity reserves and continuous investment in beneficiation technologies.
At the scale-driven end, Sibelco and Imerys S.A. exemplify multinational mineral solutions providers that offer consistent, high-purity feldspar grades to global glass and ceramic manufacturers. Sibelco, with its extensive global production footprint, supplies diverse industrial sectors. Imerys S.A. occupies a position as a specialist in engineered mineral solutions for advanced ceramics and functional fillers. Eczacıbaşı Group, a significant player in the Turkish market, represents a vertically integrated model, controlling both mining and ceramics manufacturing operations.
| Leading Market Players |
|---|
| The Quartz Corp |
| Gimpex |
| Imerys S.A. |
| Eczacıbaşı Group |
| Micronized Group |
| Sibelco |
| LB MINERALS, Ltd. |
| Sun Minerals |
| Quarzwerke GmbH |
| Others |
Cost & Logistics Intelligence
High-purity feldspar reserves, often concentrated in specific mining regions like Turkey, directly influence pricing power and margin capture for integrated ceramics manufacturers. Managing bulk transportation costs from remote extraction sites significantly impacts downstream profitability for end-users.
Pricing Analysis
After-sales technical support for high-purity feldspar grades drives significant lifetime value for specialized suppliers. Pricing primarily follows a contract-based long-term offtake model for multinational glass and ceramics manufacturers. Price differentiation stems from the product's quality grade, specifically micronized vs. coarse forms, and adherence to ISO 9001 certification. Pricing pressure originates from the high capital investment required for beneficiation plants. Construction material suppliers exhibit the highest price sensitivity, while electronics manufacturers requiring ultra-pure grades are least sensitive.
Supply Chain Analysis
Strict export controls on critical minerals, though not currently impacting feldspar significantly, highlight the potential for future regulatory restrictions on raw material flows. The global supply of feldspar concentrates in key mining regions such as Turkey, the United States, and China. Manufacturers depend on consistent access to high-purity feldspar deposits. A primary supply chain risk involves regulatory restrictions, like the EU's REACH standards, alongside reserve quality depletion. Distribution often runs through direct supply agreements for major industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feldspar market presents a fragmentation opportunity, driven by end-user demands for highly specialized, micronized grades and ultra-pure electronics materials. This shift creates distinct niches beyond traditional bulk applications.
For Market Incumbents: Build proprietary beneficiation technology to create a strong competitive moat against emerging players. Incumbents should invest in advanced sensor-based sorting to ensure consistent product quality, mitigating regulatory threats from ECHA's REACH standards. Securing long-term access to high-purity reserves is critical to counter reserve depletion and maintain supply security for multinational glass manufacturers. Continuous R&D into micronization techniques will protect market share.
For New Entrants and Emerging Players: South American construction markets represent a significant underpenetration for feldspar suppliers, particularly for ceramic tiles and flat glass. New entrants can target the expanding functional fillers market in paints and plastics, displacing more expensive materials. The most penetrable segment involves regional construction material suppliers seeking cost-effective, consistent-grade feldspar. A focused go-to-market angle involves offering localized supply chains with streamlined logistics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional mining operators lacking the capital for advanced beneficiation, creating attractive acquisition targets. The feldspar market offers long-term viability, driven by sustained demand for high-purity grades in glass and ceramics. Investors should seek vertically integrated mid-cap specialists possessing certified reserves and advanced processing capabilities. A key signal to watch is the increasing consolidation of smaller mining operations by larger players.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand from the glass manufacturing sector in the EU. |
| Backward Integration | Secures long-term access to high-purity feldspar reserves for integrated producers. |
| Green Manufacturing Transition | Aligns operations with stringent environmental regulations from the U.S. EPA. |
| Long-term Supply Agreement | Ensures consistent material flow for multinational ceramic tile manufacturers. |
| Specialized Product Development | Captures higher margins in the functional fillers market for plastics. |
Research Approach
Initial hypotheses were tested against primary input from procurement leads at glass manufacturers, R&D directors in ceramics, and plant managers of beneficiation facilities, then refined. This involved combining insights from these industry stakeholders with secondary validation from customs data, geological surveys, and relevant industry association reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all segments.
The demand-supply-balance model formed the core of the quantitative analytical framework across the analysis window. Segmentation dimensions like product type, application, end-use industry, and form were meticulously modeled. Compound annual growth rates were derived from historical performance, projected industrial output, and anticipated regulatory impacts. Key industry-specific inputs included global glass production volumes and regional ceramic manufacturing capacity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational mineral solutions providers or new market entrants would shift outcomes. Forecasts reflect current market dynamics and regulatory landscapes. Material shifts in beneficiation technology or significant changes to environmental protection policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Global Rice Husk Ash Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Brown Fused Alumina Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market