
 Lubricant Packaging Market | 2026-2036
Lubricant Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricant Packaging Market Intelligence
The distinction between large-scale industrial accounts and smaller, specialized workshops is collapsing as e-commerce platforms enable direct procurement. Greif Inc. leverages its extensive global manufacturing footprint to supply large-format drums and intermediate bulk containers for industrial clients. In contrast, Berry Global specializes in smaller, consumer-facing plastic bottles and canisters, catering to the automotive aftermarket and retail channels. Mauser Packaging Solutions operates across both segments, offering a diversified portfolio of rigid packaging solutions.
Lubricant packaging refers to primary and secondary containers designed to store, transport, and dispense petroleum-based or synthetic lubricants. These containers, often made from high-density polyethylene (HDPE) or steel, must provide excellent chemical resistance and barrier properties to prevent leakage and product degradation. Plastic bottles dominate the consumer automotive segment by volume, while large-format metal drums remain the standard for bulk industrial equipment applications. Flexible pouches represent the fastest-growing packaging type, gaining share due to lower material usage and shipping costs.
Regulations from bodies like the U.S. Environmental Protection Agency (EPA) and the European Union's REACH framework govern material composition and disposal protocols for packaging. These standards mandate clear labeling for hazardous contents and are pushing for designs that facilitate recycling and re-use, directly impacting material selection. Navigating the trade-offs between packaging durability, cost, and circular economy compliance is the central strategic challenge for manufacturers and lubricant brands.
Market Dynamics
The lubricant packaging market's evolution is governed by the structural tension between performance mandates for chemical containment and regulatory pressures for circular economy compliance. This requires material science innovation and supply chain adjustments to balance durability with recyclability.
Growth Catalysts
- Industrial Expansion:Rapid industrialization and infrastructure development in nations like India and Vietnam are fueling demand for large-format steel drums and intermediate bulk containers for heavy machinery lubricants.
- Sustainability Regulations:The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to adopt verifiable sustainable packaging, accelerating the switch to recycled-content plastics and certified fiberboard.
- Automotive Aftermarket:A growing global vehicle fleet, particularly in Southeast Asia and Latin America, sustains high-volume demand for small-format HDPE bottles and flexible pouches sold through retail and service channels.
Market Restraints
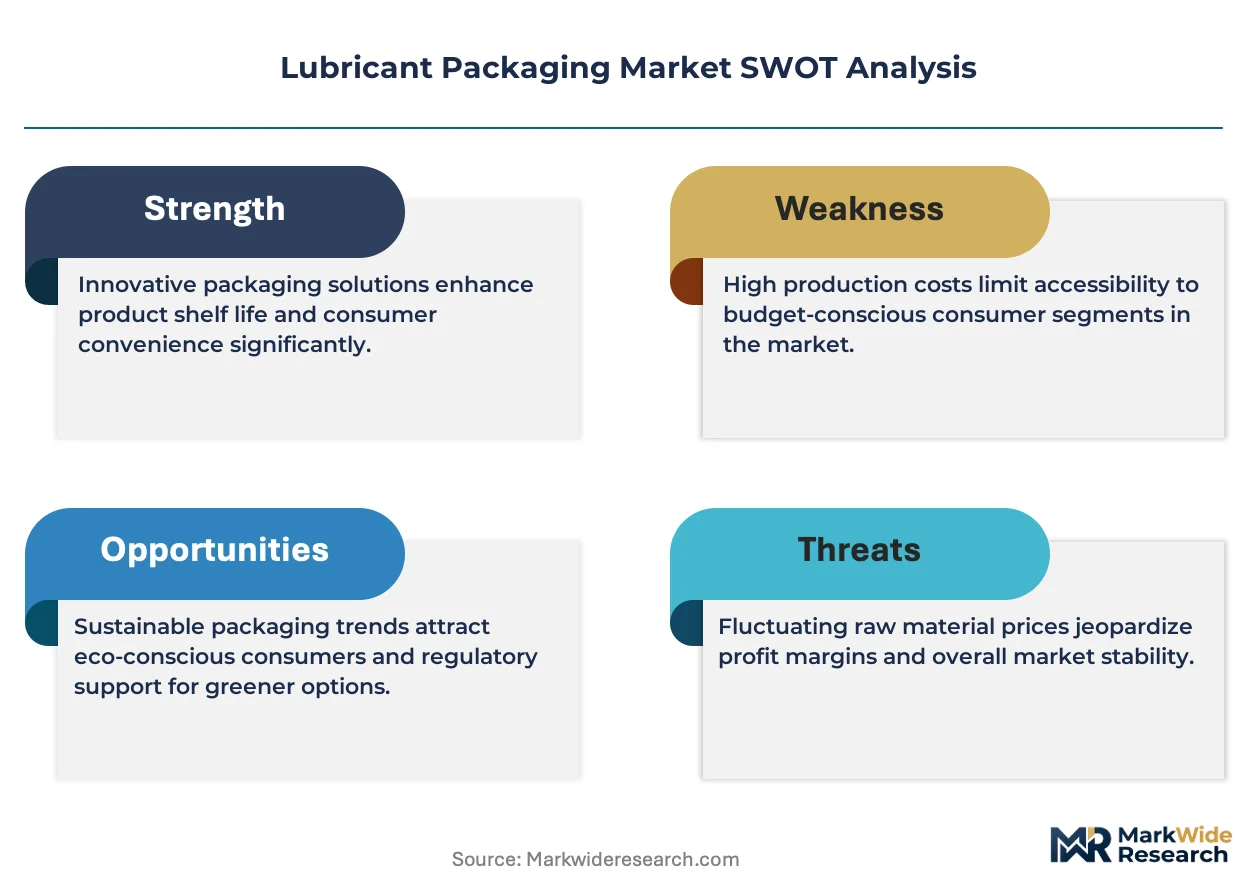
- Input Cost Volatility:Price fluctuations for raw materials, particularly crude oil derivatives for HDPE and steel, create significant margin uncertainty for packaging converters and their customers.
- Regulatory Disharmony:Divergent chemical safety and recycling regulations, such as the EPA's framework in the United States versus the EU's REACH standards, complicate global product design and trade.
- Threat from Bulk Dispensing:The installation of centralized, on-site lubricant dispensing systems in large manufacturing plants and fleet depots reduces demand for single-trip drums and pails.
Strategic Opportunities
- Bio-Based Polymers:Developing and scaling production of bio-derived plastics like bio-HDPE presents an opportunity to meet corporate sustainability goals and appeal to environmentally conscious customers.
- Smart Packaging:Integrating technologies such as QR codes or NFC tags into packaging enables enhanced track-and-trace capabilities, inventory management, and anti-counterfeiting measures for high-value lubricants.
- Flexible Packaging for Industrial Use:Expanding the application of flexible pouches beyond the consumer segment into small-volume industrial and maintenance applications offers material and freight cost savings.
Industry Challenges
- Contaminated Waste Streams:The absence of widespread, cost-effective infrastructure to collect and decontaminate used lubricant containers remains the primary barrier to achieving high recycling rates and closing material loops.
- Capital Investment for Re-tooling:Transitioning production lines to accommodate new lightweight designs, incorporate higher percentages of post-consumer resin, or handle different material types requires significant capital expenditure on molds and machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricant Packaging Market |
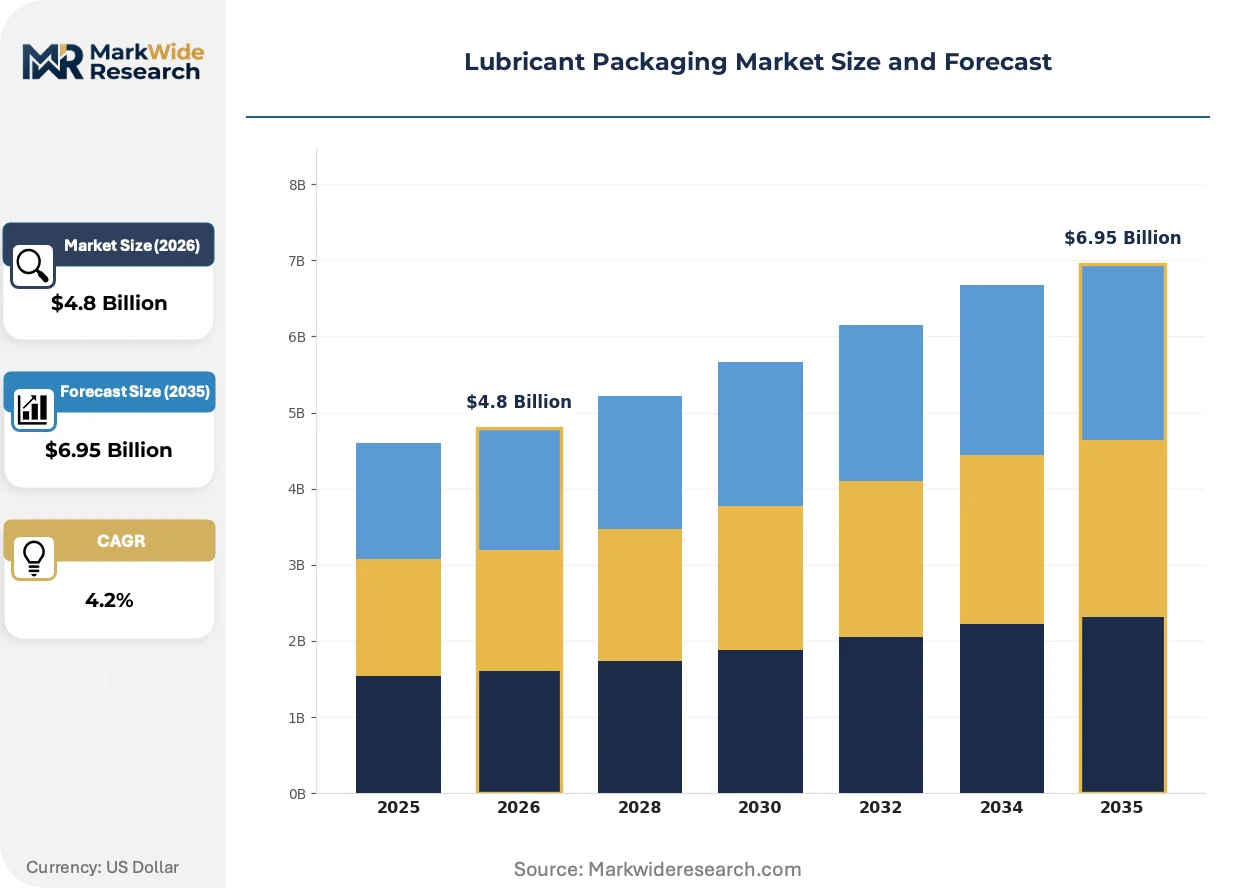
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottle, Drum, Pouch, Canister, Cartridge Material: Plastic, Metal, Composite, Glass, Fiberboard End User: Vehicle Manufacturing, Industrial Equipment, Marine Operations, Agricultural Machinery, Power Generation Distribution Channel: Direct Sales, Distributors, Retail Outlets, E-commerce Platforms, Specialty Stores |
| Companies Covered | Berry Global, Greif Inc., Mauser Packaging Solutions, Scholle IPN Corporation, Mold-Tek Packaging, Amcor Limited, Time Technoplast Ltd., Balmer Lawrie, SIG Combibloc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricant Packaging Market Strategic Shifts & Innovations
Material science and digital integration are the primary forces acting on lubricant packaging. The push for circularity is driving innovation in polymers and container formats, while e-commerce is reconfiguring distribution channels and procurement behaviors across end-use segments.
Additive manufacturing, specifically 3D printing of molds, provides a new capability for rapid prototyping. Specialized lubricant blenders and R&D departments are the earliest adopters for creating custom and low-volume container designs. This technology is fragmenting the conventional, high-volume tooling market by enabling cost-effective design iteration and niche product launches without massive upfront investment.
European Union directives on extended producer responsibility (EPR) are fundamentally altering cost structures. These regulations make lubricant producers financially liable for the collection, sorting, and recycling of their packaging at its end of life. The mandate most heavily impacts high-volume producers of single-use HDPE bottles, forcing investment in collection schemes or a pivot toward reusable container systems.
Direct-to-mechanic e-commerce is altering traditional distribution hierarchies. This model allows independent workshops and small fleet operators to procure lubricants and other supplies directly from manufacturers or specialized online platforms. It disintermediates regional distributors and wholesalers, a shift highly visible in the mature automotive aftermarket sectors of North America and Europe.
Lubricant Packaging Market Segmentation
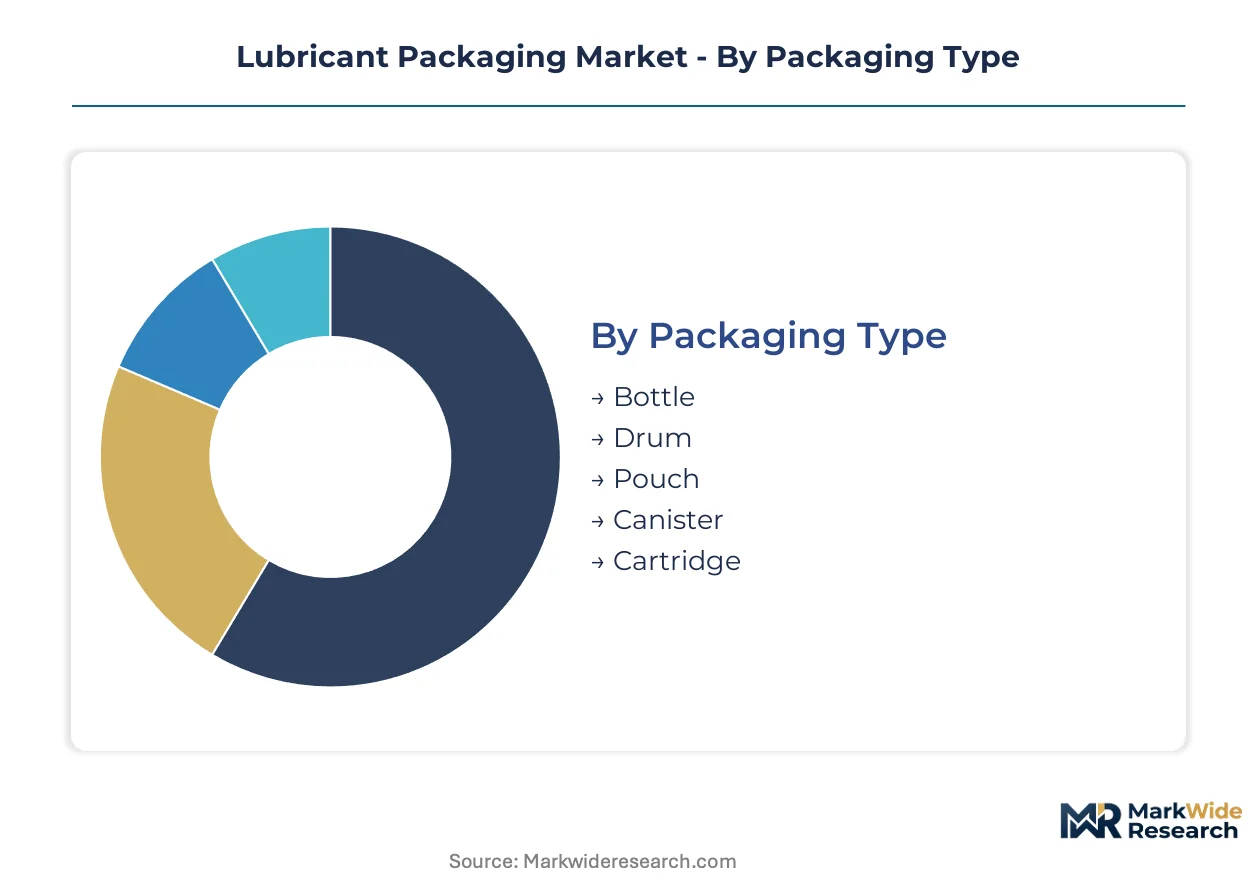
The lubricant packaging market is highly segmented, reflecting the diverse applications and distribution models for lubricants across industrial and consumer sectors. Understanding these distinct segments is crucial for manufacturers to tailor packaging solutions, optimize material selection, and navigate complex regulatory landscapes effectively.
Packaging Type:
The channel mix for lubricant packaging significantly influences the choice of packaging type, reflecting both industrial bulk procurement and consumer retail dynamics.
- Drum:Large-format drums, typically made from steel or high-density polyethylene (HDPE), provide robust containment for bulk lubricants. Demand concentrates in industrial hubs within China and India, driven by heavy machinery and infrastructure projects requiring large-volume supply.
- Pouch:Flexible pouches, often constructed from multi-layer films, offer material efficiency and reduced shipping weight. Their adoption is accelerating in the automotive aftermarket across Southeast Asia due to convenience and a lower environmental footprint.
- Bottle:Plastic bottles, primarily HDPE, serve the consumer automotive segment, offering ease of dispensing and brand visibility.
- Canister:Metal or plastic canisters provide durable packaging for specific automotive and industrial lubricant grades, ensuring product integrity.
- Cartridge:Grease cartridges facilitate precise application of specialized lubricants in maintenance and repair operations.
By volume, drums lead the market. By growth pace, flexible pouches are expanding most quickly.
Material:
Material selection for lubricant packaging is primarily driven by application-specific performance requirements and regulatory compliance.
- Plastic:High-density polyethylene (HDPE) dominates the plastic segment, offering chemical resistance and cost-effectiveness for consumer and light industrial lubricants. Consumer automotive applications in North America and Europe account for substantial plastic bottle demand.
- Metal:Steel remains the standard for large-format drums, providing superior barrier properties and durability for bulk industrial lubricants. Industrial equipment manufacturers in Germany and Japan rely heavily on metal packaging for critical applications.
- Fiberboard:Fiberboard containers are gaining traction, particularly for less aggressive lubricants and as a sustainable alternative to plastics in certain applications.
- Composite:Composite materials combine different layers to achieve enhanced barrier properties, often used for specialized or sensitive lubricants.
- Glass:Glass packaging is used for niche, high-purity, or specialty lubricants where inertness and premium presentation are essential.
Sustainability mandates from the EU's Corporate Sustainability Reporting Directive (CSRD) are driving shifts towards recycled plastics and fiberboard.
End User:
End-user segmentation highlights the diverse operational needs and lubricant consumption patterns across various industries.
- Industrial Equipment:This sector requires robust, large-format packaging for heavy machinery lubricants, demanding high chemical resistance and durability. Massive manufacturing and infrastructure projects in China are a primary demand driver.
- Vehicle Manufacturing:Lubricant packaging for vehicle manufacturing includes both factory-fill and aftermarket products, ranging from large drums to smaller bottles. The growing global vehicle fleet, particularly in Southeast Asia, sustains high-volume demand.
- Marine Operations:Marine vessels require specialized lubricants in durable packaging that can withstand harsh environmental conditions and ensure long-term storage.
- Agricultural Machinery:Agricultural equipment relies on specific lubricants, with packaging designed for durability and ease of use in field conditions.
- Power Generation:Power plants utilize specialized lubricants for turbines and generators, requiring secure packaging to maintain product integrity over long periods.
Industrial sectors collectively account for the largest demand volume, driven by operational scale and maintenance requirements.
Distribution Channel:
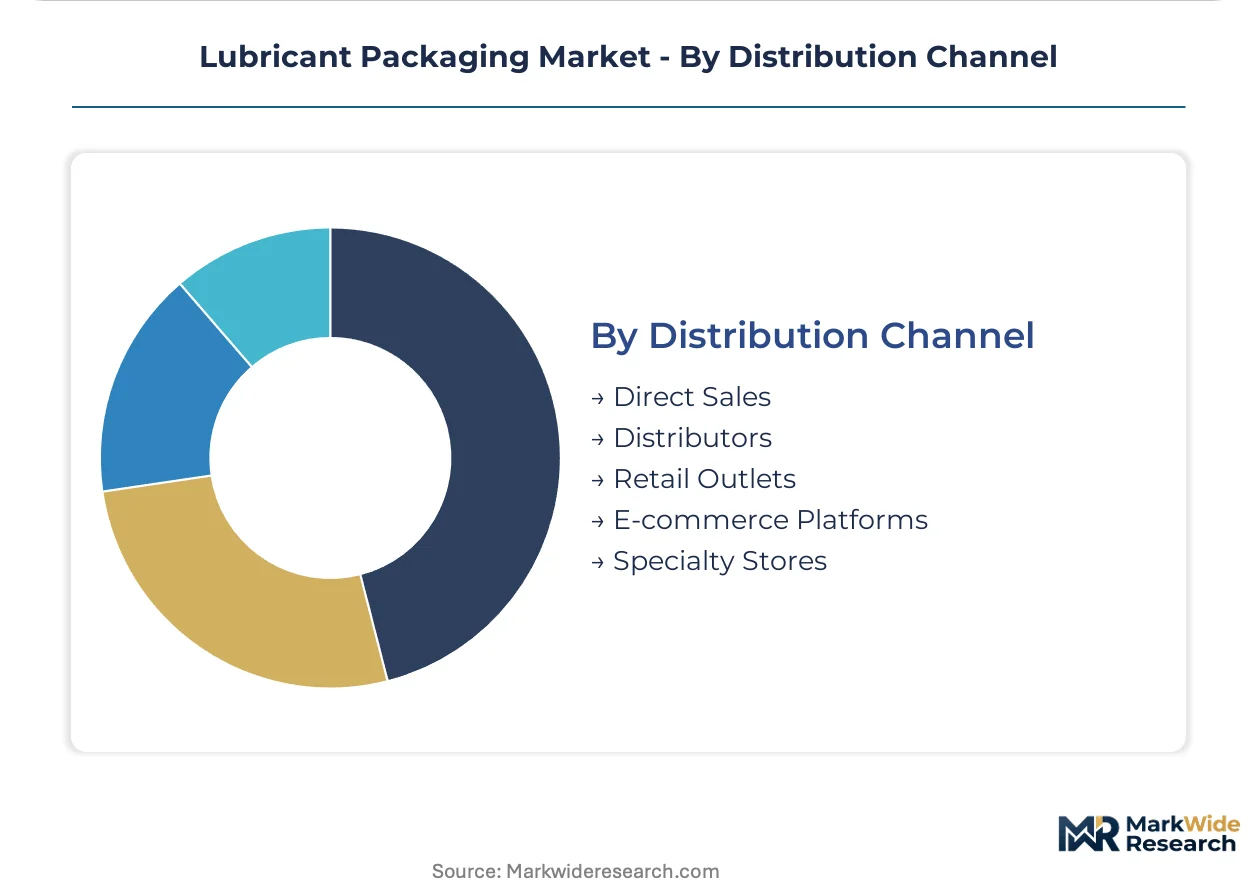
Distribution channel dynamics reflect evolving procurement patterns and market reach, from traditional supply chains to digital platforms.
- E-commerce Platforms:These platforms enable direct procurement for workshops and smaller operators, bypassing traditional intermediaries and offering wider product access. Direct-to-mechanic sales in North America are significantly impacting established distribution models.
- Distributors:Traditional distributors serve as crucial intermediaries, managing inventory and logistics for a broad range of industrial and automotive customers. Their established networks remain vital for large-volume industrial supply.
- Direct Sales:Large industrial accounts often engage in direct sales agreements with lubricant and packaging manufacturers for customized solutions and bulk orders.
- Retail Outlets:Retail stores cater to individual consumers and small workshops, offering a variety of packaged lubricants for the automotive aftermarket.
- Specialty Stores:These outlets focus on niche lubricants or specific brands, providing expert advice and a curated product selection.
E-commerce platforms are reshaping traditional procurement behaviors, particularly in the automotive aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global lubricant packaging market's regional dynamics are significantly shaped by the presence of extensive manufacturing and trade infrastructure, such as China's vast network of industrial parks and ports. These assets facilitate both the production and distribution of lubricants across various end-use sectors. Demand patterns for packaging materials differ by continent, reflecting local industrial bases and regulatory environments.
China
Massive infrastructure projects and manufacturing expansion drive demand for large-format drums. China's dual carbon goals promote sustainable packaging solutions within its industrial zones. Industrial hubs like the Yangtze River Delta concentrate demand for robust, high-volume lubricant containers.
India
Rapid industrialization across India fuels demand for intermediate bulk containers for heavy machinery. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing, increasing lubricant consumption. Major automotive and industrial clusters in Maharashtra and Gujarat require substantial lubricant packaging.
Germany
Industrial equipment manufacturers in Germany rely on metal packaging for critical applications. The EU's REACH framework mandates strict material composition and disposal protocols for lubricant containers. The Ruhr area's heavy industry sector generates consistent demand for specialized bulk lubricant packaging.
United States
Consumer automotive applications in the United States account for substantial plastic bottle demand. The EPA regulates material composition and disposal, influencing packaging design and recycling efforts. Direct-to-mechanic e-commerce platforms in major metropolitan areas are reshaping procurement for smaller workshops.
Vietnam
Growing industrial development in Vietnam sustains demand for lubricants in various sectors. Government policies supporting foreign direct investment boost manufacturing output, increasing lubricant packaging needs. Manufacturing zones near Ho Chi Minh City are seeing rising requirements for small-format and industrial lubricant packaging.
Lubricant Packaging Market Key Industry Players
Concentration sits with established packaging giants offering diversified portfolios across materials and formats. The market structure exhibits a tiered consolidation, with a few large global players dominating bulk industrial solutions. Mid-sized specialists carve out niches in consumer-facing or flexible packaging segments, while smaller regional players cater to localized demand. Competitive moves include geographic expansion into emerging industrial markets, strategic partnerships for sustainable material development, and investment in digital integration.
Among scale-driven providers, Greif Inc. occupies a position as a global supplier of large-format industrial containers for bulk lubricants. Mauser Packaging Solutions, a diversified entity, exemplifies a comprehensive approach across both industrial and consumer segments, offering a broad portfolio of rigid packaging solutions. Berry Global, an Inc.-structured firm, represents specialization in smaller, consumer-facing plastic packaging solutions, catering specifically to the automotive aftermarket and retail channels. These companies anchor the market across various material types and end-user requirements, adapting to evolving sustainability mandates.
| Leading Market Players |
|---|
| Berry Global |
| Greif Inc. |
| Mauser Packaging Solutions |
| Scholle IPN Corporation |
| Mold-Tek Packaging |
| Amcor Limited |
| Time Technoplast Ltd. |
| Balmer Lawrie |
| SIG Combibloc |
| Others |
Cost & Logistics Intelligence
EU's Corporate Sustainability Reporting Directive (CSRD) gates both packaging supply qualification and price differentiation by mandating verifiable sustainable materials. This regulatory pressure influences material costs and market access for lubricant packaging manufacturers.
Pricing Analysis
Volume-based contract pricing dominates the industrial lubricant packaging market, offering significant discounts for large-format drums and intermediate bulk containers. Price differentiation also depends on customization level for specialized applications and geographic delivery costs, especially for remote industrial sites. Pricing pressure stems from input cost volatility, particularly for crude oil derivatives for HDPE and steel. Small workshops and individual consumers procuring through retail channels are highly price-sensitive, whereas large industrial equipment manufacturers prioritize supply reliability and performance.
Supply Chain Analysis
Inventory management and lead times are critical due to the bulk nature of many packaging materials and the global distribution network. Geographic supply concentration for raw materials centers on countries like China for HDPE and steel, alongside specialized film producers in Europe. Raw material dependencies include high-density polyethylene, steel, and multi-layer films for flexible pouches. Commodity price volatility for crude oil derivatives and steel presents a significant structural risk. Distribution runs through direct sales for large industrial accounts, traditional distributors for mid-sized clients, and e-commerce platforms for the automotive aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lubricant packaging market is in an early-cycle expansion phase, driven by increasing penetration of sustainable packaging solutions across industrial and consumer segments. This shift reflects both regulatory mandates and evolving consumer preferences for eco-friendly options.
For Market Incumbents: Compound investments in material science R&D to develop advanced bio-based polymers and higher recycled content HDPE. This strategy mitigates the threat from new sustainable material entrants and addresses stringent regulations like the EU's CSRD. Incumbents should also enhance channel control by integrating smart packaging solutions for track-and-trace capabilities, particularly for high-value industrial lubricants. Focusing on capacity additions in emerging industrial hubs like India can further solidify market position.
For New Entrants and Emerging Players: Specialized digital platforms that streamline procurement for small-to-medium enterprises represent a service-layer gap where incumbents under-serve. New entrants can target the automotive aftermarket segment in Southeast Asia with innovative flexible pouch solutions, emphasizing lower material usage and shipping costs. Offering customized, low-volume packaging designs through additive manufacturing can provide a unique go-to-market angle. Partnerships with local recycling infrastructure providers also offer a competitive advantage.
For Investors and Strategic Acquirers: The EU's extended producer responsibility (EPR) directives reshape the acquisition landscape, favoring companies with established collection and recycling infrastructure or advanced sustainable material capabilities. Long-term viability (5-10 years) hinges on adaptability to circular economy mandates and material innovation. Acquisition target archetypes include mid-sized specialists in flexible packaging or bio-based polymer development. The signal to watch is the increasing adoption rate of post-consumer recycled content in packaging across major industrial regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global sustainability mandates like CSRD. |
| Long-term Supply Agreement | Secures raw material access amidst volatility and ensures consistent production for key clients. |
| Product Launch | Introduces new flexible packaging formats for industrial applications, expanding market reach. |
| Geographic Expansion | Establishes manufacturing presence in high-growth industrial regions like India. |
| Platform Integration | Embeds smart packaging technologies for enhanced traceability and anti-counterfeiting measures. |
Research Approach
Initial hypotheses were tested against primary input from lubricant manufacturers, packaging converters, industrial equipment maintenance directors, and automotive aftermarket distributors, then refined through iterative analysis. This involved combining in-depth interviews with secondary validation from customs data, industry association reports, and company annual filings. Bottom-up data collection for specific segments was triangulated with top-down market sizing.
Variance decomposition attributed market shifts to changes in packaging type, material composition, end-user demand, and regional industrial development across the analysis window. The model segmented demand by lubricant type (industrial vs. automotive), container size, and distribution channel. Compound annual growth rates were derived from historical data trends, macroeconomic indicators, and projected industrial output. Key forecast inputs included raw material price projections and regulatory compliance timelines.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in unforeseen raw material supply disruptions or accelerated shifts in circular economy mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Thermal Insulation Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
PET Strap Market
Packaging Materials
Child Resistant Re-Closable Edible Bags Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Single-Use Packaging Market
Packaging Materials
VCI Films Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
France Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Foam Bottle Technology Market